
 Renewable Energy Integration with Smart Grid Market | 2026-2036
Renewable Energy Integration with Smart Grid Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Integration with Smart Grid Market Analytics
The EU Green Deal is realigning procurement criteria for grid-connected renewable assets across European utilities. Siemens leverages its digital grid software portfolio to anchor utility-scale automation contracts in continental Europe. Schneider Electric sustains competitive positioning through integrated energy management systems that span generation control to demand response orchestration. ABB dominates high-voltage direct current interconnector projects that bridge offshore wind clusters to onshore load centers.
Renewable energy integration with smart grid denotes the coordinated deployment of bi-directional communication infrastructure, advanced metering architecture, and distributed energy resource management systems to synchronize variable renewable generation with real-time electricity demand. The technical core relies on IEC 61850 protocol standards for substation automation and IEEE 1547 interconnection requirements ensuring grid stability during reverse power flows. Energy storage systems command premium margins due to frequency regulation mandates and the technical necessity of buffering solar and wind intermittency. Demand response solutions are expanding fastest among commercial building operators seeking to curtail peak charges through automated load flexibility. Smart meters represent the most mature segment, with utility rollouts now shifting from deployment to data monetization and grid-edge analytics.
The Federal Energy Regulatory Commission in the United States mandates Order 2222 compliance for distributed resource aggregation, while China's National Energy Administration enforces GB/T standards for grid-code conformance of renewable inverters. India's Central Electricity Authority issued technical standards requiring renewable generators above specified capacity thresholds to install remote monitoring systems. Stakeholders must monitor evolving interconnection queue reforms and storage procurement mandates as regulators recalibrate market rules to accommodate accelerating renewable penetration.
Market Dynamics
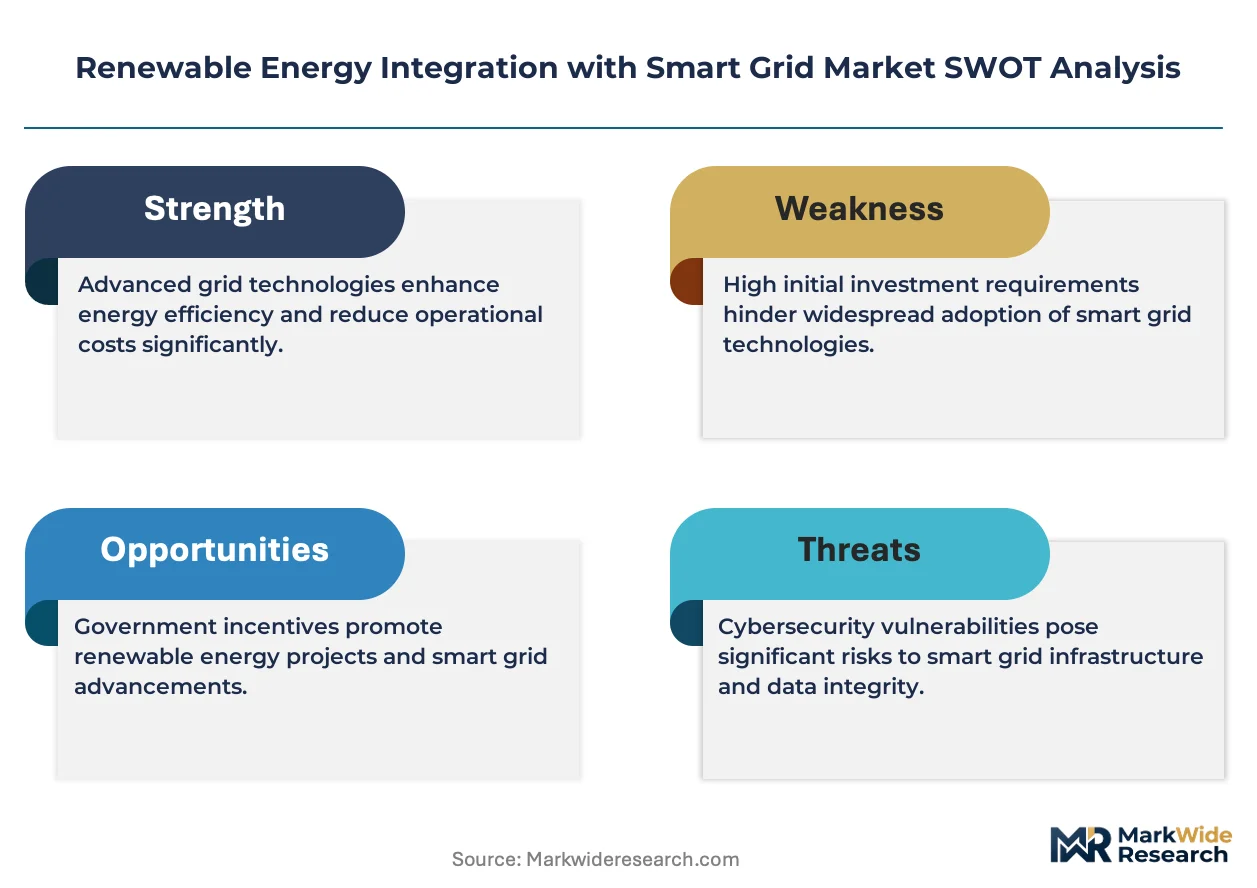
The renewable energy integration with smart grid market is being fundamentally restructured by the collision of aging transmission infrastructure with the technical demands of distributed energy resource interconnection, forcing utilities to choose between massive grid reinforcement investments and software-defined grid-edge orchestration platforms.
Growth Catalysts
- FERC Order 2222 Mandate:The Federal Energy Regulatory Commission's aggregation rules compel US grid operators to accommodate distributed resource participation in wholesale markets, creating immediate procurement pull for DERMS platforms.
- Offshore Wind Cluster Development:North Sea and Atlantic coast projects require HVDC interconnectors and synchronized inverter controls, driving demand for high-voltage power electronics and submarine cable systems.
- Commercial Building Electrification:Corporate net-zero commitments are accelerating automated demand response deployments across office and retail portfolios, with facility managers prioritizing peak charge reduction.
Market Restraints
- Critical Mineral Supply Concentration:Lithium and rare earth processing capacity concentrates in China, exposing energy storage system manufacturers to input cost volatility and geopolitical supply disruption.
- Interconnection Queue Backlogs:Grid operators in Germany and California face multi-year delays for renewable project approvals, freezing capital deployment and compressing developer returns.
- Legacy SCADA Protocol Incompatibility:Existing substation automation infrastructure relies on proprietary communication standards that resist seamless integration with IEC 61850-compliant smart grid architectures.
Strategic Opportunities
- India Grid Modernization:The Central Electricity Authority's remote monitoring mandates for renewable generators above 25 MW create immediate demand for telemetry hardware and cloud-based asset management platforms.
- Vehicle-to-Grid Convergence:Bidirectional charging infrastructure is integrating electric vehicle batteries as mobile grid storage assets, opening new revenue streams for utilities and fleet operators.
- EU Green Deal Storage Procurement:Member state capacity auctions and strategic reserve mechanisms are mandating battery storage co-location with solar and wind assets, guaranteeing offtake for system integrators.
Industry Challenges
- Cybersecurity Talent Scarcity:Grid operators struggle to recruit industrial control system security specialists capable of securing IEC 62351-compliant substation networks against targeted attacks.
- Multi-Vendor System Integration:Utilities deploying heterogeneous smart meter, DERMS, and energy storage platforms face protocol translation complexity and interoperability testing delays that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Integration with Smart Grid Market |
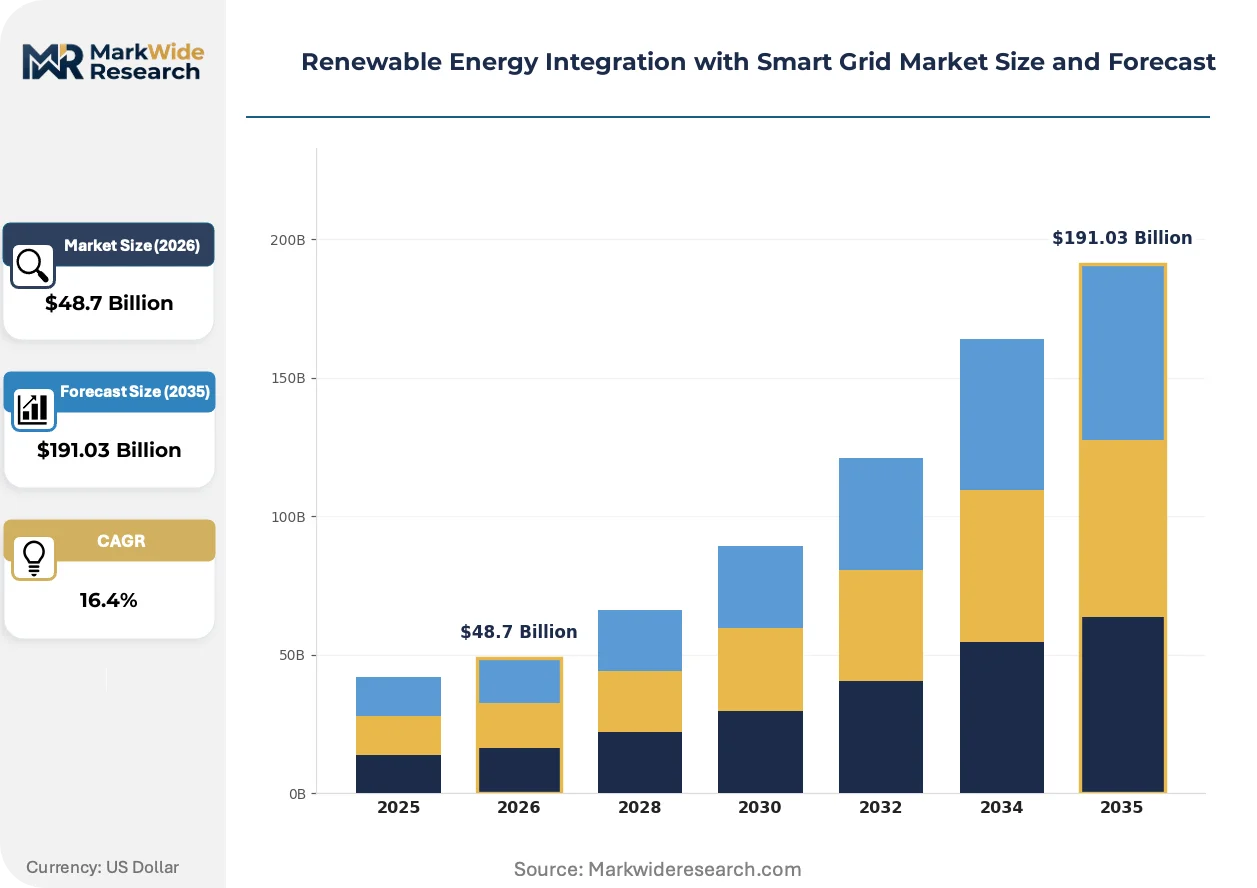
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wind Turbines, Solar Panels, Energy Storage Systems, Smart Meters Solution: Demand Response, Energy Management Systems, Distributed Generation, Advanced Grid Analytics End User: Utilities, Industrial Sector, Commercial Buildings, Residential Customers Application: Load Balancing, Power Quality Management, Renewable Integration, Peak Shaving |
| Companies Covered | ABB, Schneider Electric, Siemens, General Electric, IBM Corporation, Cisco Systems, Honeywell International, Oracle Corporation, Itron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Integration with Smart Grid Market Evolving Landscape
Digital twin technology is compressing grid planning cycles by enabling real-time simulation of renewable intermittency scenarios, while artificial intelligence is displacing rule-based control systems for frequency regulation and voltage optimization.
Digital twin platforms are integrating physics-based grid models with live SCADA telemetry to simulate distributed energy resource behavior under extreme weather events. German transmission system operators including 50Hertz and TenneT are deploying these systems for congestion forecasting and dynamic line rating optimization. This technology is integrating previously siloed planning and operations functions, collapsing the traditional separation between asset management and real-time control centers.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on machine learning models used for predictive load forecasting and automated grid switching. European utilities must now document training data provenance and algorithmic transparency for AI systems classified as high-risk critical infrastructure components. Grid software vendors are responding by establishing dedicated AI governance functions and pursuing ISO/IEC 42001 certification for their development pipelines.
Corporate power purchase agreements are displacing traditional utility green tariff programs as the dominant procurement mechanism for renewable energy in the United States. Large technology and industrial buyers are negotiating directly with project developers for solar-plus-storage configurations with guaranteed capacity availability, bypassing incumbent utility intermediaries. This restructuring is most visible in Texas and California, where deregulated market structures permit bilateral contracting outside standard tariff frameworks.
Renewable Energy Integration with Smart Grid Market Segmentation
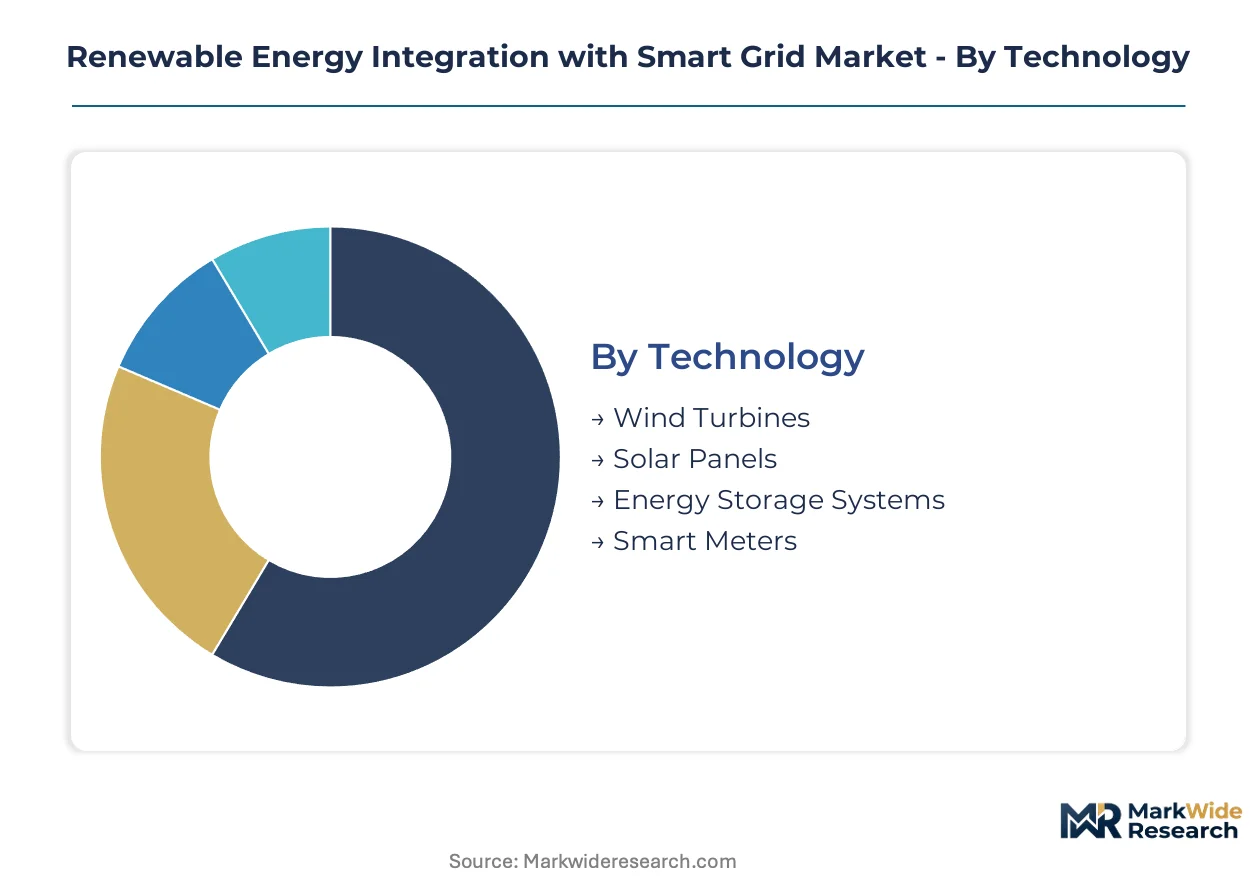
Segmentation in renewable energy integration with smart grid reveals how technology maturity, solution architecture, and customer sophistication create distinct procurement patterns. Understanding these divides exposes where capital concentrates and where margin compression threatens incumbent positioning.
Technology:
Supply concentration in power electronics and battery cell manufacturing reshapes competitive dynamics across hardware categories.
- Wind Turbines:Large-scale onshore and offshore turbine installations require synchronized inverter controls and grid-code compliant power conditioning systems. Demand clusters in North Sea offshore clusters and Texas onshore corridors where HVDC interconnection mandates drive premium equipment procurement.
- Solar Panels:Photovoltaic arrays with smart inverters enable bidirectional power flows and remote telemetry for utility dispatch centers. Utility-scale deployments in California and Gujarat dominate procurement volumes as interconnection standards tighten under FERC Order 2222 and India's CEA mandates.
- Energy Storage Systems:Lithium-ion battery arrays with power conversion systems buffer renewable intermittency for frequency regulation services.
- Smart Meters:Advanced metering infrastructure with bidirectional communication protocols completes the last-mile grid visibility layer.
Today's leader: Smart Meters. Tomorrow's challenger: Energy Storage Systems.
Solution:
Cost tier differentiation separates enterprise-grade platforms from modular point solutions.
- Demand Response:Automated load curtailment systems aggregate commercial building flexibility for wholesale market participation. Large retail and office portfolios in deregulated US markets prioritize peak charge reduction through utility-controlled dispatch.
- Energy Management Systems:Integrated software platforms orchestrate generation forecasting, storage dispatch, and building automation from centralized control centers. German industrial complexes and US data center operators drive premium deployments seeking real-time optimization.
- Distributed Generation:On-site renewable and backup power systems with grid-synchronization capabilities serve reliability-critical facilities.
- Advanced Grid Analytics:Machine learning platforms for predictive maintenance and congestion forecasting extract value from smart meter data streams.
Enterprise buyers consolidate around Energy Management Systems. Mid-market adoption is climbing fastest in Demand Response.
End User:
Application maturity varies sharply by customer sophistication and regulatory exposure.
- Utilities:Transmission and distribution operators deploy grid-scale automation, DERMS platforms, and substation modernization programs under regulatory procurement mandates.
- Industrial Sector:Manufacturing complexes with high power quality requirements invest in on-site generation, storage co-location, and microgrid islanding capabilities.
- Commercial Buildings:Corporate real estate portfolios automate HVAC and lighting flexibility for demand response revenue and sustainability reporting.
- Residential Customers:Homeowners adopt rooftop solar, battery backup, and smart thermostats through utility rebate programs and financing partnerships.
Utilities command platform budgets. Commercial Buildings are expanding most quickly as net-zero commitments harden.
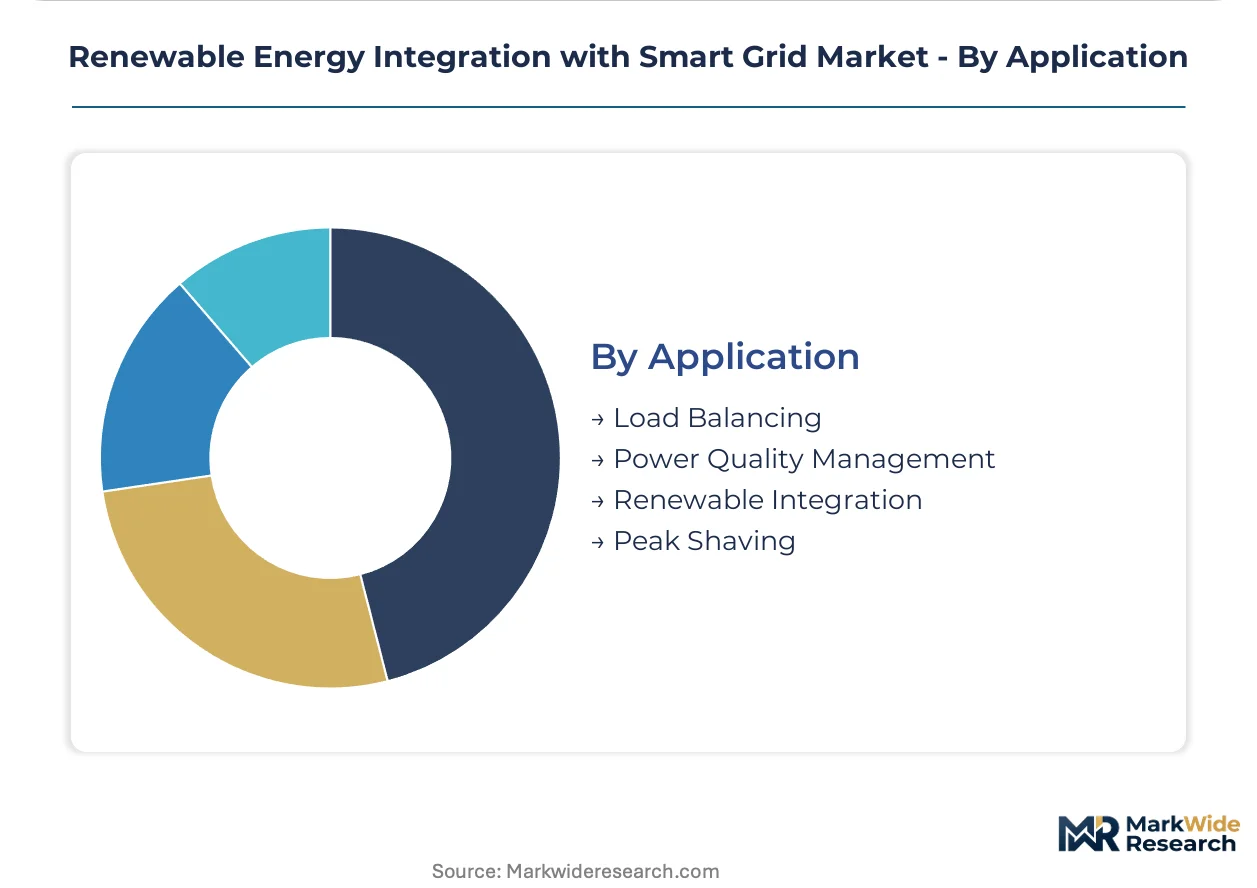
Application:
Volume concentration follows regulatory priority sequencing across grid services.
- Load Balancing:Real-time generation-demand matching through automated dispatch of distributed resources and storage assets maintains grid frequency within operational bands.
- Power Quality Management:Voltage regulation, harmonic filtering, and reactive power compensation protect sensitive industrial equipment from renewable-induced grid disturbances.
- Renewable Integration:Grid-code compliance, forecasting, and curtailment management enable high-penetration solar and wind without stability degradation.
- Peak Shaving:Storage discharge and load flexibility reduce maximum demand charges for commercial customers and defer utility infrastructure investment.
Renewable Integration absorbs current investment. Peak Shaving is emerging as the steepest expansion trajectory behind commercial electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart grid integration industry traces its commercial roots to German engineering conglomerates that pioneered IEC 61850 substation automation standards in the early 2000s. Utility-scale deployments subsequently migrated to North American and East Asian markets as renewable penetration mandates accelerated. Today, procurement concentrates in jurisdictions with the most aggressive interconnection reform timelines.
United States
FERC Order 2222 mandates distributed resource aggregation across wholesale markets, compelling grid operators to procure DERMS platforms and bidirectional metering infrastructure. The Inflation Reduction Act extends investment tax credits for storage co-location with solar assets. Texas ERCOT and California CAISO territories dominate deployment volumes as interconnection queue reforms prioritize hybrid renewable-plus-storage configurations.
Germany
Transmission system operators 50Hertz and TenneT deploy digital twin platforms for dynamic line rating and North Sea offshore wind integration. The EU Green Deal tightens grid-code standards for renewable asset interconnection under Network Codes CEP and DCC. Industrial clusters in Bavaria and North Rhine-Westphalia anchor demand for integrated energy management systems serving automotive and chemical manufacturing loads.
China
National Energy Administration GB/T standards enforce grid-code conformance for renewable inverters above specified capacity thresholds. Provincial grid companies in Jiangsu and Guangdong accelerate smart meter rollouts and distributed generation telemetry mandates. The Yangtze River Delta concentrates manufacturing of power conversion systems and lithium-ion battery modules for domestic and export markets.
India
Central Electricity Authority technical standards require remote monitoring systems for renewable generators above 25 MW capacity. State-level renewable purchase obligations in Gujarat and Karnataka drive utility procurement of substation automation and forecasting platforms. The National Smart Grid Mission funds pilot deployments in Maharashtra and Tamil Nadu targeting agricultural feeder segregation and peak load management.
United Kingdom
Ofgem's RIIO-ED2 price control framework incentivizes distribution network operators to deploy flexible connection solutions and active network management. Offshore wind clusters in the North Sea and Irish Sea require HVDC interconnectors and synchronized inverter controls. The Midlands and Scotland host grid-scale battery storage projects co-located with onshore wind farms under capacity market contracts.
Renewable Energy Integration with Smart Grid Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the renewable integration value chain. The market exhibits tiered consolidation, with integrated industrial conglomerates controlling high-voltage power electronics and submarine cable systems while specialized software vendors capture DERMS and analytics segments. Three archetypes dominate: diversified electrification majors with end-to-end portfolios, power electronics specialists with deep inverter expertise, and enterprise software vendors with utility cloud platforms. Competitive intensity centers on vertical integration into energy storage system assembly and strategic partnerships with offshore wind developers.
Among diversified industrial conglomerates, ABB, Schneider Electric, and Siemens exemplify distinct strategic positions. ABB anchors the high-voltage interconnector segment with positions in HVDC converter stations bridging offshore wind clusters to onshore load centers. Schneider Electric occupies the integrated energy management tier, spanning building automation through grid-edge orchestration. Siemens represents the digital grid software archetype, with utility-scale automation contracts concentrated in European transmission system operator modernization programs.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| General Electric |
| IBM Corporation |
| Cisco Systems |
| Honeywell International |
| Oracle Corporation |
| Itron |
| Others |
Value Network & Pricing Analysis
Lithium carbonate and rare earth oxide costs cascade through energy storage system pricing tiers, with Chinese processing dominance concentrating margin pressure on non-integrated Western assemblers while utility-scale buyers extract volume discounts through co-location mandates.
Pricing Analysis
Project-based contracting with long-term offtake guarantees dominates utility procurement, separating premium-tier integrated platform providers from standard-tier hardware vendors through FERC Order 2222 certification depth and after-sales service bundling. Cost compression in battery module assembly is intensifying because Chinese cell manufacturers are expanding capacity faster than non-Chinese demand growth. Commercial building operators exhibit highest price sensitivity, prioritizing peak charge reduction payback periods over upfront platform sophistication.
Supply Chain Analysis
Refurbishment flows for retired utility-scale inverters and power conversion systems are emerging as secondary supply channels, with remanufactured equipment capturing mid-market share in India and Southeast Asia. Manufacturing concentrates in China, South Korea, and Germany for power electronics, while lithium processing feeds from Chile, Australia, and Argentina. Single-source vulnerability in rare earth magnet supply creates exposure to export restriction shocks. Distribution runs through EPC contractors and direct utility procurement desks with multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because regulatory mandates for renewable interconnection create irreversible procurement obligations across transmission and distribution operators regardless of power price cyclicality.
For Market Incumbents: Deepen software-defined grid-edge capabilities through captive development of AI-driven forecasting modules, defending against specialized analytics entrants targeting congestion management. Prioritize backward integration into battery management system firmware to capture storage co-location margins tightening under IRA domestic content rules. For New Entrants and Emerging Players: Launch via utility pilot programs in India's National Smart Grid Mission jurisdictions, where remote monitoring mandates for renewable generators above 25 MW create immediate telemetry hardware demand with lower incumbent saturation than European or North American markets. Target agricultural feeder segregation applications in Maharashtra and Tamil Nadu as the most penetrable entry segment. For Investors and Strategic Acquirers: Roll-up economics work for specialized DERMS software vendors because utility procurement consolidation favors platforms with pre-certified interoperability across heterogeneous meter and inverter protocols. Five-to-ten year viability hinges on FERC Order 2222 implementation pace; monitor interconnection queue reform announcements from CAISO and ERCOT as inflection indicators for DERMS platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Scale Storage Co-location | Captures IRA investment tax credits while satisfying FERC frequency regulation mandates for hybrid renewable assets. |
| Digital Twin Platform Deployment | Compresses planning cycles for German TSOs managing North Sea offshore wind intermittency through real-time simulation. |
| DERMS Certification Investment | Secures utility automation contracts under Order 2222 aggregation requirements across ERCOT and CAISO territories. |
| HVDC Interconnector Expansion | Bridges offshore wind clusters to onshore load centers under EU Green Deal transmission reinforcement priorities. |
| AI Governance Function Establishment | Positions grid software vendors for EU AI Act conformity assessment on predictive load forecasting algorithms. |
Research Methodology
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators grounded qualitative findings, validated against EIA project databases, FERC interconnection queue filings, IEA renewable integration reports, and utility CAPEX disclosure statements. Bottom-up and top-down triangulation reconciled segment-level procurement patterns with aggregate market sizing.
Bottom-up modeling of technology deployments across wind turbine, solar panel, energy storage, and smart meter categories was cross-checked against top-down regulatory mandate trajectories over the projection horizon. Segmentation by solution architecture, end-user sophistication, and application priority shaped volume allocation. CAGRs derived from utility procurement pipeline analysis and interconnection reform timelines, with specific inputs from GB/T standard enforcement in China and CEA technical mandate implementation in India.
Forecast precision tightens around the base case; tail outcomes carry wider variance under critical mineral export restriction scenarios and interconnection queue processing delays. Practitioners should monitor lithium carbonate price volatility and FERC Order 2222 compliance deadline adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Smart Demand Response Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Microgrid Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
Smart Energy Switch Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
North America Smart Grid Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
Power Grid Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Smart Grid Communications Market
Smart Grid
India Smart Grid Network Market