
 Smart Gas Meter Market | 2026-2036
Smart Gas Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Gas Meter Market Intelligence
Advanced metering infrastructure with integrated pressure-monitoring and real-time anomaly detection is redrawing procurement standards across European utilities. Landis+Gyr leverages its manufacturing scale to dominate AMI deployments in Germany and the Nordics. Itron Inc. competes through wireless communication specialization that reduces installation costs for dense urban networks. Honeywell International Inc. anchors its position with sensor integration expertise spanning gas safety and HVAC adjacencies.
A smart gas meter is an electronic device that measures natural gas consumption through ultrasonic or diaphragm sensing technology, communicates usage data via RF mesh or cellular networks, and enables remote shutoff, leak alerts, and time-of-use billing for utilities and end customers. Residential meters lead volume shipments due to mass replacement programs, while industrial meters command premium pricing through high-flow accuracy requirements and hazardous-area certification. Wireless communication technology is gaining fastest as utilities abandon drive-by reading systems, though smart metering systems retain the largest installed base where AMI backhaul already exists.
Europe's F-Gas Regulation, CE marking under the Measuring Instruments Directive, and national metrology institute certifications in Germany, France, and the United Kingdom collectively mandate accuracy classes, data security protocols, and interoperability standards that determine market access. The EU AI Act introduces emerging compliance obligations for anomaly-detection algorithms embedded in next-generation devices. Stakeholders must monitor whether proposed amendments to the Gas Directive accelerate mandatory smart-meter penetration beyond current utility-led timelines.
Market Dynamics
AMI backhaul infrastructure investments by European distribution network operators are compressing replacement timelines and forcing meter vendors to certify integrated pressure-monitoring modules before contract eligibility.
Growth Catalysts
- F-Gas Regulation leak-detection mandates:The European framework requires remote anomaly identification capabilities, compelling utilities to specify ultrasonic sensing with embedded pressure transducers in procurement tenders.
- German metrology institute certification deadlines:Distribution operators in North Rhine-Westphalia and Bavaria face statutory rollout timelines that accelerate volume procurement through 2028.
- RF mesh network densification:Urban utilities are specifying wireless communication protocols that eliminate drive-by reading infrastructure and reduce operational expenditure.
Market Restraints
- Semiconductor component concentration:Meter manufacturers depend on a narrow supplier base for ultrasonic time-of-flight sensors, creating input cost volatility and allocation risk.
- CE marking complexity under MDR:The Measuring Instruments Directive's data security protocol requirements extend certification timelines by 8-14 months for new product introductions.
- Mechanical meter residual stock:Distribution network operators in Eastern European markets maintain inventories of diaphragm meters that delay AMI conversion programs.
Strategic Opportunities
- Net-zero building code integration:France's RE2020 regulation mandates gas consumption visibility for new construction, creating specification pull-through for multi-utility meters with HVAC interface capability.
- EU AI Act algorithmic compliance:Anomaly-detection software embedded in next-generation devices must meet emerging transparency requirements, favoring vendors with in-house data science capabilities.
- Industrial high-flow certification gaps:Hazardous-area meters for chemical processing facilities carry premium positioning with limited certified competition.
Industry Challenges
- Cybersecurity talent scarcity:Firmware engineering for encrypted RF communication protocols requires specialized expertise that meter OEMs struggle to secure against automotive and aerospace competition.
- Legacy system integration complexity:Head-end system compatibility with 15-20 year-old utility billing platforms demands custom middleware development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Gas Meter Market |
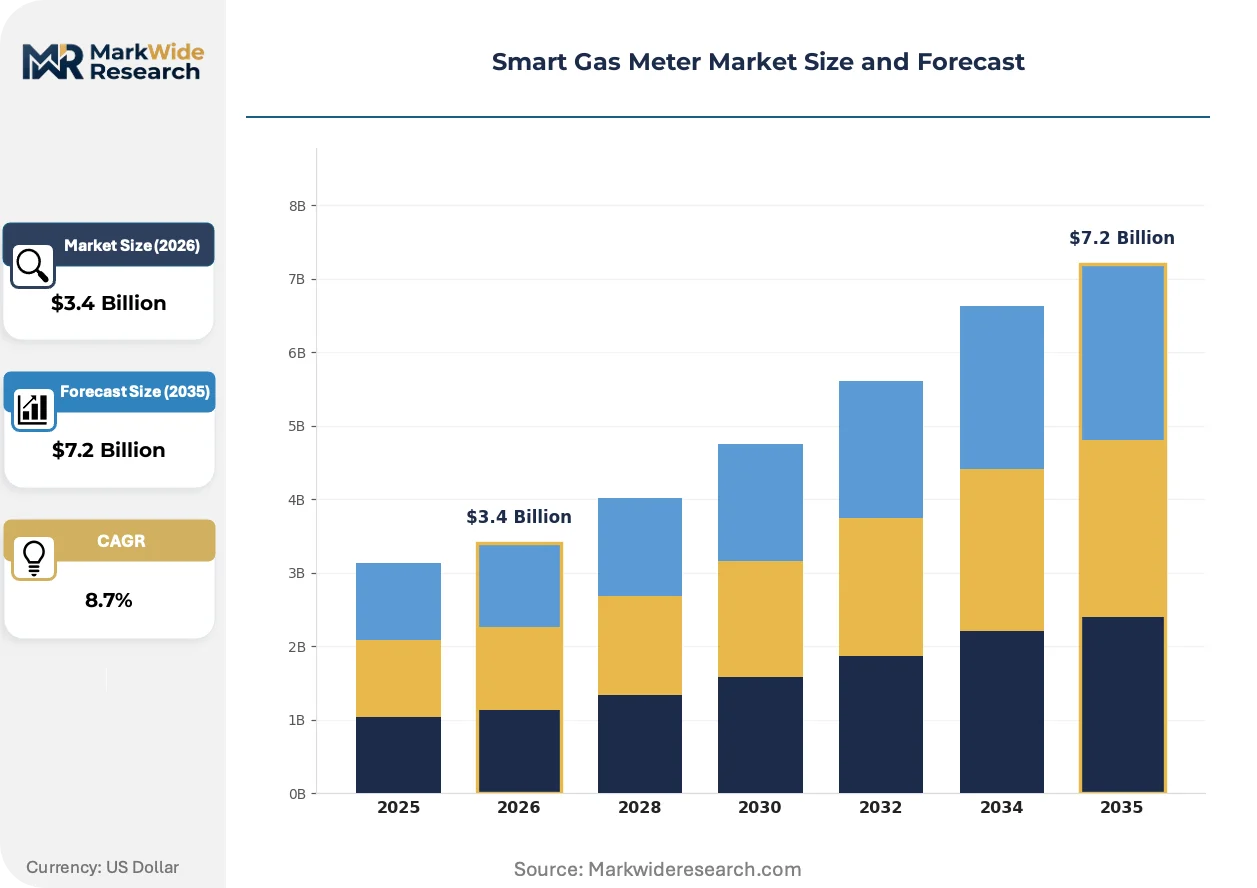
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Meters, Commercial Meters, Industrial Meters, Portable Meters Technology: Smart Metering Systems, Advanced Metering Infrastructure, Internet of Things, Wireless Communication End User: Utilities, Manufacturers, Service Providers, Residential Users Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Landis+Gyr, Itron Inc., Honeywell International Inc., Diehl Stiftung & Co. KG, Apator S.A., Sensus (Xylem Inc.), Aclara Technologies LLC, Schneider Electric SE, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Gas Meter Market Strategic Shifts & Innovations
Ultrasonic sensing architectures are redrawing procurement specifications as utilities abandon mechanical measurement. Regulatory pressure on methane leak detection is accelerating sensor integration roadmaps. Vendor competition is shifting from hardware cost to data platform stickiness.
Ultrasonic time-of-flight measurement is supplanting diaphragm displacement technology in residential meter specifications. German and Nordic utilities now require Class 1.5 accuracy with integrated temperature compensation as baseline procurement criteria. This transition is compressing margins for mechanical-component suppliers while favoring semiconductor-integrated designs with firmware-defined functionality.
The EU AI Act introduces conformity assessment obligations for machine-learning algorithms that flag consumption anomalies as potential leaks. Meter vendors must document training data provenance and algorithmic transparency to maintain CE marking validity. French and British distribution operators are front-loading procurement requirements to preempt compliance gaps in 2026 certification cycles.
Utility procurement teams are unbundling hardware purchase from data-analytics subscriptions, creating recurring revenue dependencies for meter vendors. Traditional equipment-sale contracts are fragmenting into device-as-a-service arrangements with 10-15 year telemetry commitments. This restructuring is most visible in United Kingdom rollout programs where Ofgem's price control framework favors operational expenditure accounting.
Smart Gas Meter Market Segmentation
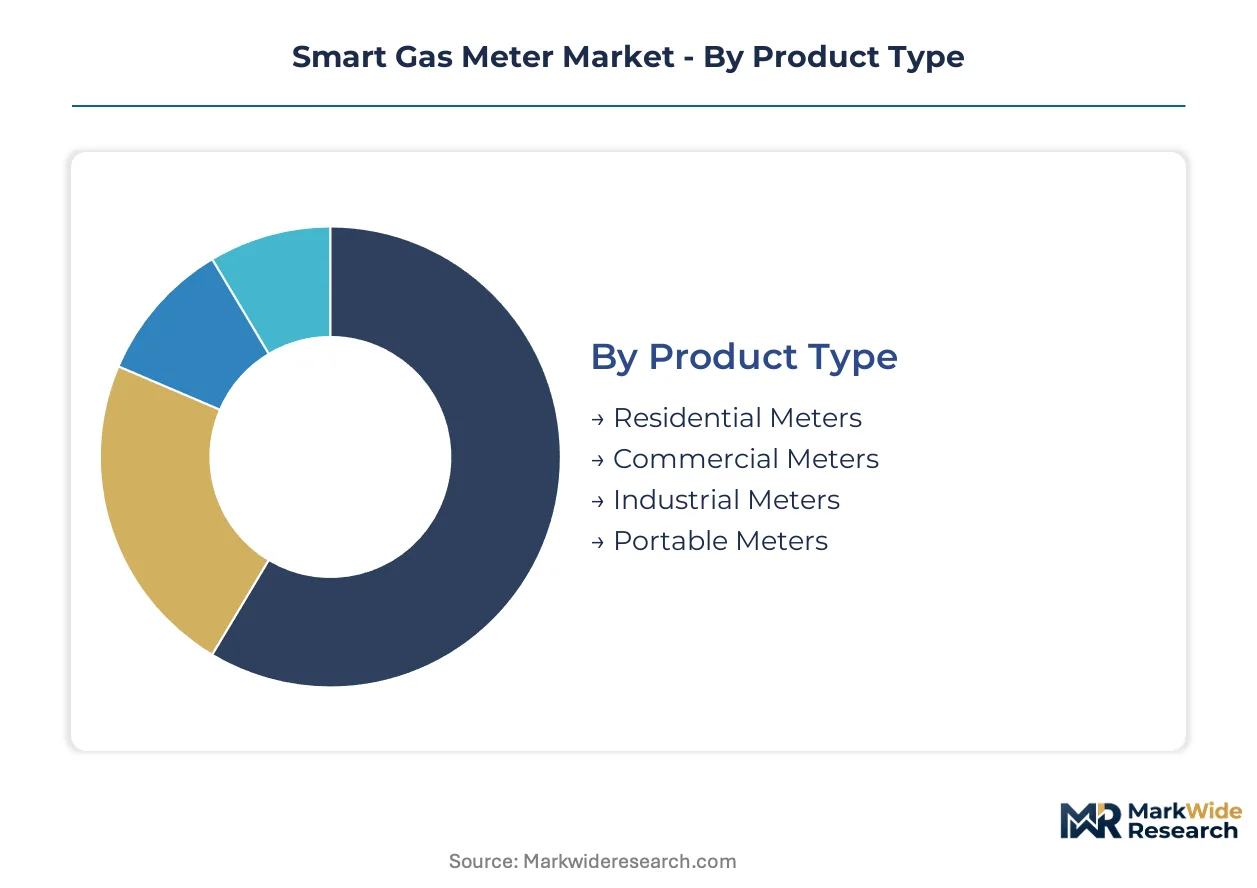
Smart gas meter procurement patterns diverge sharply across product tiers and technology architectures. Utilities structure replacement programs around distinct accuracy requirements, communication protocols, and integration complexity that reshape vendor competitive positioning.
Product Type:
Diaphragm meter residual stock in Eastern European utilities creates substitution pressure for mechanical segments while ultrasonic architectures displace legacy measurement across high-value contracts.
- Residential Meters:Ultrasonic time-of-flight sensors with Class 1.5 accuracy and integrated temperature compensation now dominate German and Nordic utility tenders. Mass replacement programs in North Rhine-Westphalia and Bavaria compress procurement timelines through statutory rollout deadlines.
- Industrial Meters:High-flow accuracy specifications and hazardous-area certifications for chemical processing facilities command premium positioning. Limited certified competition creates procurement bottlenecks for ATEX-compliant ultrasonic designs.
- Commercial Meters:Mid-scale flow measurement bridging residential and industrial specifications.
- Portable Meters:Temporary deployment units for network diagnostics and emergency response.
Residential meters anchor the volume base while industrial meters gain share at the steepest rate.
Technology:
Cost tier stratification separates integrated AMI deployments from modular retrofit solutions as utilities balance capital constraints against functionality requirements.
- Smart Metering Systems:Established AMI backhaul infrastructure retains the largest installed base where distribution network operators have already deployed head-end systems. Legacy system integration complexity demands custom middleware development for 15-20 year-old billing platforms.
- Wireless Communication:RF mesh and cellular protocols eliminate drive-by reading infrastructure and reduce operational expenditure. Urban utilities in dense German and United Kingdom networks specify wireless to accelerate deployment velocity.
- Advanced Metering Infrastructure:Integrated pressure-monitoring and real-time anomaly detection modules.
- Internet of Things:Cloud-native telemetry architectures with API-first data exchange.
Smart metering systems retain the largest revenue base while wireless communication expands most quickly.
End User:
Customer type maturity separates regulated utilities with mandated procurement timelines from price-sensitive residential adopters.
- Utilities:Distribution network operators in Germany, France, and the United Kingdom face statutory rollout deadlines that compress replacement cycles. F-Gas Regulation leak-detection mandates require remote anomaly identification capabilities in all new tenders.
- Residential Users:End-customer demand concentrates in France where RE2020 net-zero building codes mandate gas consumption visibility for new construction. Multi-utility meters with HVAC interface capability specification pull-through accelerates.
- Manufacturers:OEM integration of meter telemetry into building management systems.
- Service Providers:Third-party installation and maintenance contractors.
Utilities anchor procurement volume while residential users climb the fastest as building code mandates expand.
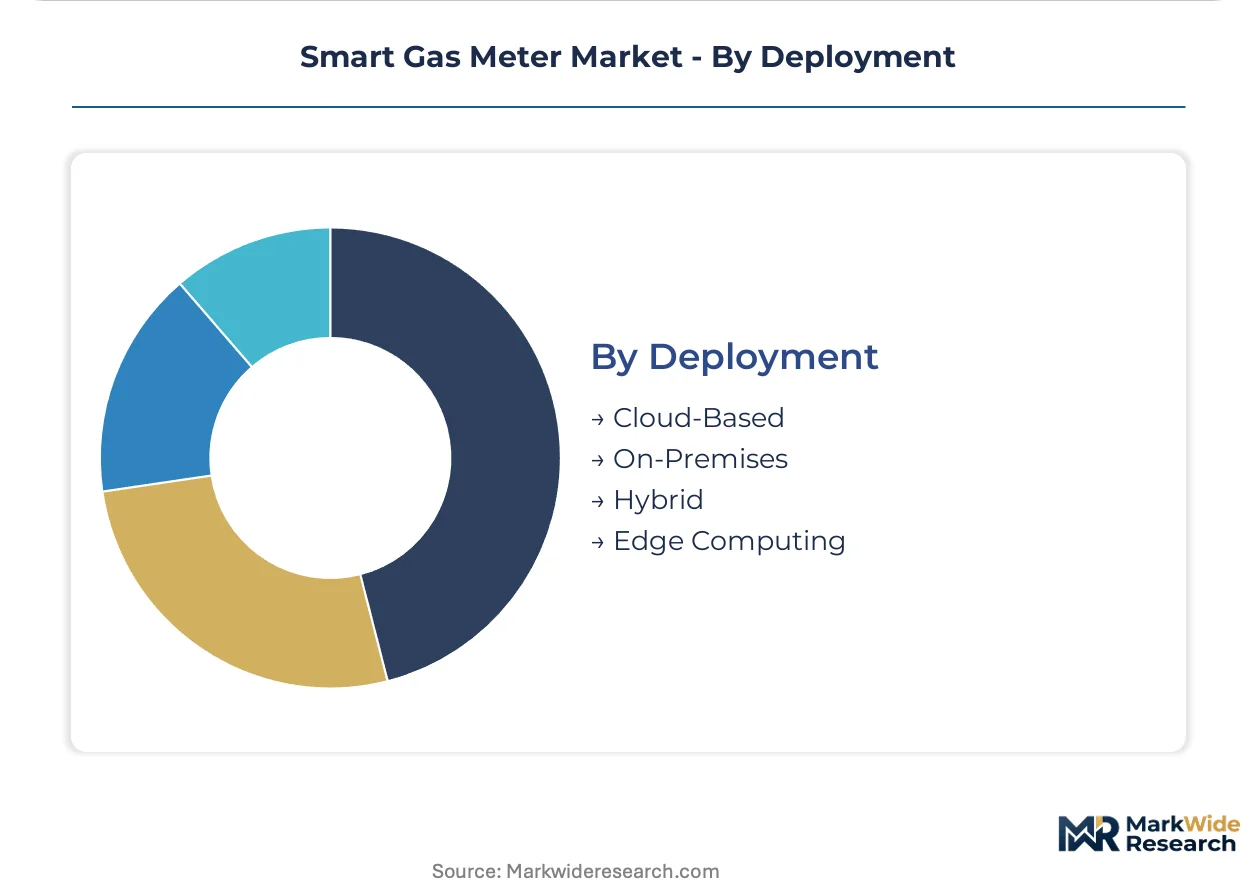
Deployment:
Supply concentration in cloud infrastructure vendors shapes hybrid and edge alternatives as utilities seek data sovereignty.
- Cloud-Based:Centralized telemetry platforms with subscription-based analytics access. United Kingdom Ofgem price control frameworks favor operational expenditure accounting that accelerates device-as-a-service contract structures.
- Hybrid:Split architectures combining on-premises head-end systems with cloud analytics layers.
- On-Premises:Fully captive data infrastructure for cybersecurity-sensitive distribution operators.
- Edge Computing:Localized anomaly detection processing to minimize latency for leak alert response.
Cloud-based deployment anchors new contract structures while hybrid configurations gain traction among security-conscious operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in smart gas meter equipment favor European manufacturing clusters, with component sourcing concentrated in German sensor foundries and final assembly distributed across Poland and Romania for cost optimization.
Germany
Distribution network operators in North Rhine-Westphalia and Bavaria face statutory rollout deadlines compressing procurement through 2028. The Physikalisch-Technische Bundesanstalt certification requirements mandate Class 1.5 accuracy standards that filter vendor eligibility. Manufacturing scale concentrates in Nuremberg and Stuttgart industrial corridors where ultrasonic sensor integration capabilities anchor production.
United Kingdom
Ofgem's price control framework favors operational expenditure accounting that accelerates device-as-a-service contract structures. The Smart Metering Implementation Programme mandates remote-read functionality across residential deployments. London and Greater Manchester utilities specify RF mesh protocols that eliminate drive-by reading infrastructure.
France
The RE2020 net-zero building code mandates gas consumption visibility for new construction, creating specification pull-through for multi-utility meters. ANSM data security protocols align with CE marking requirements under the Measuring Instruments Directive. Industrial demand clusters in Lyon and Marseille where chemical processing facilities require hazardous-area certification.
Italy
Distribution network operators in Lombardy and Piedmont accelerate AMI backhaul investments to compress replacement timelines. National metrology institute certification deadlines filter vendor participation in northern utility tenders. Milan-based system integrators specialize in middleware development for legacy billing platform compatibility.
Netherlands
Randstad utilities specify integrated pressure-monitoring modules to satisfy F-Gas Regulation leak-detection mandates. The national smart meter rollout program prioritizes wireless communication protocols for dense urban networks. Eindhoven sensor manufacturers supply ultrasonic time-of-flight components to broader European assembly operations.
Smart Gas Meter Market Key Industry Players
Concentration sits with diversified industrial conglomerates and specialized metering technology providers. The vendor base stratifies across three tiers: integrated AMI platform vendors with utility-scale deployment experience, component specialists with sensor integration expertise, and regional system integrators with legacy billing compatibility capabilities. Dominant competitive moves include certification pre-positioning ahead of regulatory deadlines and data-platform unbundling to capture recurring telemetry revenue.
Among the integrated platform tier, Landis+Gyr and Itron Inc. exemplify scale-driven positioning with manufacturing and wireless communication specializations respectively. Honeywell International Inc. occupies a position bridging sensor integration expertise across gas safety and HVAC adjacencies. These three represent the archetype of vendors capturing procurement volume through statutory rollout programs and F-Gas Regulation compliance positioning.
| Leading Market Players |
|---|
| Landis+Gyr |
| Itron Inc. |
| Honeywell International Inc. |
| Diehl Stiftung & Co. KG |
| Apator S.A. |
| Sensus (Xylem Inc.) |
| Aclara Technologies LLC |
| Schneider Electric SE |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Ultrasonic time-of-flight sensor adoption displacing mechanical diaphragm components simultaneously concentrates procurement leverage in German semiconductor foundries and compresses margin structures for legacy meter assemblers in Eastern Europe. This substitution dynamic reconfigures cost allocation toward firmware-defined functionality while eroding price premiums previously attached to mechanical precision engineering.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ATEX-certified hazardous-area meters commanding substantial premiums over residential Class 1.5 units. Price differentiation rests on certification grade and volume scale, with German PTB-certified designs sustaining margin premiums against uncertified alternatives. Cost compression in the residential tier intensifies because of statutory mass-replacement deadlines forcing procurement volume concentration. Utilities exhibit lowest price sensitivity due to regulatory compliance imperatives, while independent system integrators face acute margin pressure on retrofit installations.
Supply Chain Analysis
Strategic stockpiling of ultrasonic sensor components dominates procurement behavior as lead times for time-of-flight chips extend beyond meter assembly cycles. Manufacturing concentration centers on Germany, Poland, and Romania, with Nuremberg-Stuttgart corridors anchoring sensor integration and Polish final assembly operations optimizing labor cost structures. The supply chain draws from narrow semiconductor foundry sources for ultrasonic transducers, MEMS pressure sensors, and RF communication modules. Single-source vulnerability for time-of-flight sensor silicon creates allocation risk during capacity constraints. Distribution runs through utility-direct contracting for AMI deployments and regional system integrators for retrofit wireless installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across European metrology institutes creates specialization niches for vendors with jurisdiction-specific certification expertise. F-Gas Regulation leak-detection mandates and national rollout deadlines fragment procurement standards, enabling focused players to capture defensible positions.
For Market Incumbents: Fortify certification pre-positioning ahead of EU AI Act algorithmic transparency requirements by embedding documented training data provenance into anomaly-detection firmware. Prioritize in-house data science capabilities to preempt compliance gaps in CE marking renewal cycles. Consolidate middleware development partnerships with Milan-based system integrators to reduce legacy billing platform integration timelines that currently extend deployment schedules.
For New Entrants and Emerging Players: Anchor in industrial high-flow hazardous-area certification gaps where limited ATEX-compliant competition creates procurement bottlenecks for chemical processing facilities. Target Lyon and Marseille industrial clusters where premium positioning sustains margin structures unavailable in saturated residential segments. Pursue device-as-a-service contract structures aligned with United Kingdom Ofgem price control frameworks to bypass capital-intensive utility-direct procurement barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed metering specialists holding AMI deployment experience but lacking AI Act compliance roadmaps. Long-term viability hinges on recurring telemetry revenue capture rather than hardware sale multiples, favoring vendors with unbundled data-analytics subscription models. Monitor ANSM and CNIL enforcement patterns on data security protocols as early indicators of certification cost escalation that would reshape competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | EU AI Act compliance investment secures CE marking validity ahead of algorithmic transparency deadlines. |
| Sensor Integration Partnership | Eindhoven ultrasonic component alliances reduce allocation risk for time-of-flight transducer supply. |
| Middleware Development Capability | Milan-based system integration expertise compresses legacy billing platform compatibility timelines. |
| Device-as-a-Service Transition | Ofgem-aligned operational expenditure accounting captures recurring revenue in United Kingdom rollouts. |
| Industrial Certification Investment | ATEX hazardous-area positioning accesses premium pricing in Lyon chemical processing clusters. |
Research Approach
Initial hypotheses were tested against primary input from utility planning officers, meter OEM procurement directors, distribution network operator engineering leads, and national metrology institute certification specialists and refined through secondary validation. Sources included SEC filings from listed metering technology providers, CE marking documentation under the Measuring Instruments Directive, F-Gas Regulation implementation guidance, and customs records of ultrasonic sensor component trade flows. Bottom-up triangulation of utility tender volumes and top-down reconciliation against distribution network operator capital expenditure disclosures anchored market sizing.
Variance decomposition across product type, technology architecture, end-user segment, and deployment model structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume-demand modeling calibrated to statutory rollout timelines and replacement cycle compression. Forecast inputs incorporated AMI backhaul infrastructure investment trajectories, RF mesh network densification rates, and regulatory deadline clustering effects.
Decision-makers should treat outputs as directional under assumptions of continued F-Gas Regulation enforcement and stable semiconductor supply allocation; material deviation in either would warrant model refresh. Specific risks include tariff escalation on Chinese-sourced MEMS components and accelerated EU AI Act implementation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Power Monitoring System Market
Smart Meters
Power Quality Meter Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Solar Meter Market
Smart Meters
US Water Meter Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Power Metering Market
Smart Meters
Asia Pacific Water Meter Market