
 Power Monitoring System Market | 2026-2036
Power Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Power Monitoring System Market Analysis
Data center power density requirements is realigning procurement patterns across the Power Monitoring System Market as hyperscale operators seek granular visibility into kilowatt-level consumption. Schneider Electric leverages its EcoStruxure platform to anchor integrated monitoring architectures across colocation facilities. Siemens competes through its Sentron portfolio, which sustains strong positioning in industrial environments requiring IEC-compliant power quality analysis. ABB differentiates via its Ability Energy Manager, which dominates large-scale manufacturing deployments across Europe and Asia.
A power monitoring system comprises hardware and software assemblies that measure, record, and analyze electrical parameters including voltage, current, power factor, and harmonic distortion across distribution networks. These systems typically employ current transformers with accuracy classes from 0.5 to 1.0 and digital communication protocols such as Modbus or IEC 61850 to transmit data to centralized management platforms. Power meters and voltage sensors represent mature product categories with established margin pools, while communication devices and cloud-based installations are capturing accelerated growth as edge computing architectures proliferate. Remote monitoring applications are expanding fastest among the application segments, driven by predictive maintenance requirements in renewable energy plants.
Regulators including the EU through its Energy Efficiency Directive and Ecodesign framework, the US EPA through ENERGY STAR certification requirements for commercial buildings, and India's Bureau of Energy Efficiency through its Perform Achieve and Trade scheme are mandating granular energy disclosure and continuous monitoring. These frameworks compel facility operators to deploy certified metering infrastructure or face penalties and restricted market access. Stakeholders must evaluate how evolving cybersecurity standards for operational technology networks will reshape product certification requirements and procurement criteria for connected monitoring devices.
Market Dynamics
Data center rack densities exceeding 50kW per cabinet are forcing facility operators to abandon aggregate metering in favor of branch-circuit-level monitoring, compressing installation timelines and reshaping vendor qualification criteria across the Power Monitoring System Market.
Growth Catalysts
- EU Green Deal retrofit mandates:Germany, France, and Italy now require continuous energy disclosure in commercial buildings above specific thresholds, compelling landlords to install certified metering infrastructure or face occupancy restrictions.
- Industrial electrification programs:German manufacturing clusters are deploying distributed monitoring nodes to manage variable renewable integration and avoid peak demand penalties under national grid modernization frameworks.
- Edge computing proliferation:Hyperscale operators are instrumenting every rack with intelligent power distribution units that stream telemetry to cloud-based energy management platforms for real-time optimization.
Market Restraints
- Copper and rare earth input volatility:Current transformer cores and sensor housings depend on copper pricing that has fluctuated sharply, squeezing margin pools for hardware manufacturers.
- Semiconductor supply concentration:Analog-to-digital converters and communication chipsets for IEC 61850 compliance remain concentrated among a limited supplier base in East Asia.
- Legacy protocol fragmentation:Existing building automation systems running proprietary Modbus variants resist seamless integration with newer IP-based architectures, extending deployment timelines.
Strategic Opportunities
- Underpenetrated industrial SMEs:Mid-sized manufacturing facilities in Poland and the Czech Republic lack granular visibility into machine-level consumption, representing whitespace for retrofit-focused service models.
- Renewable plant predictive maintenance:Wind and solar operators are adopting remote monitoring applications to detect inverter faults and harmonic distortion before capacity degradation occurs.
- CSRD-aligned disclosure automation:The EU Corporate Sustainability Reporting Directive creates procurement pull for metering systems that generate audit-ready energy intensity metrics without manual intervention.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 compliance for operational technology networks requires extensive third-party validation, delaying product launches by six to twelve months.
- Legacy SCADA integration complexity:Brownfield industrial sites operate decades-old control systems that resist API-based data extraction, forcing costly gateway deployments or partial instrumentation.
- Field commissioning skill scarcity:Technicians capable of calibrating 0.5 accuracy class current transformers and verifying IEC 61850 communication mappings remain scarce across Central European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Monitoring System Market |
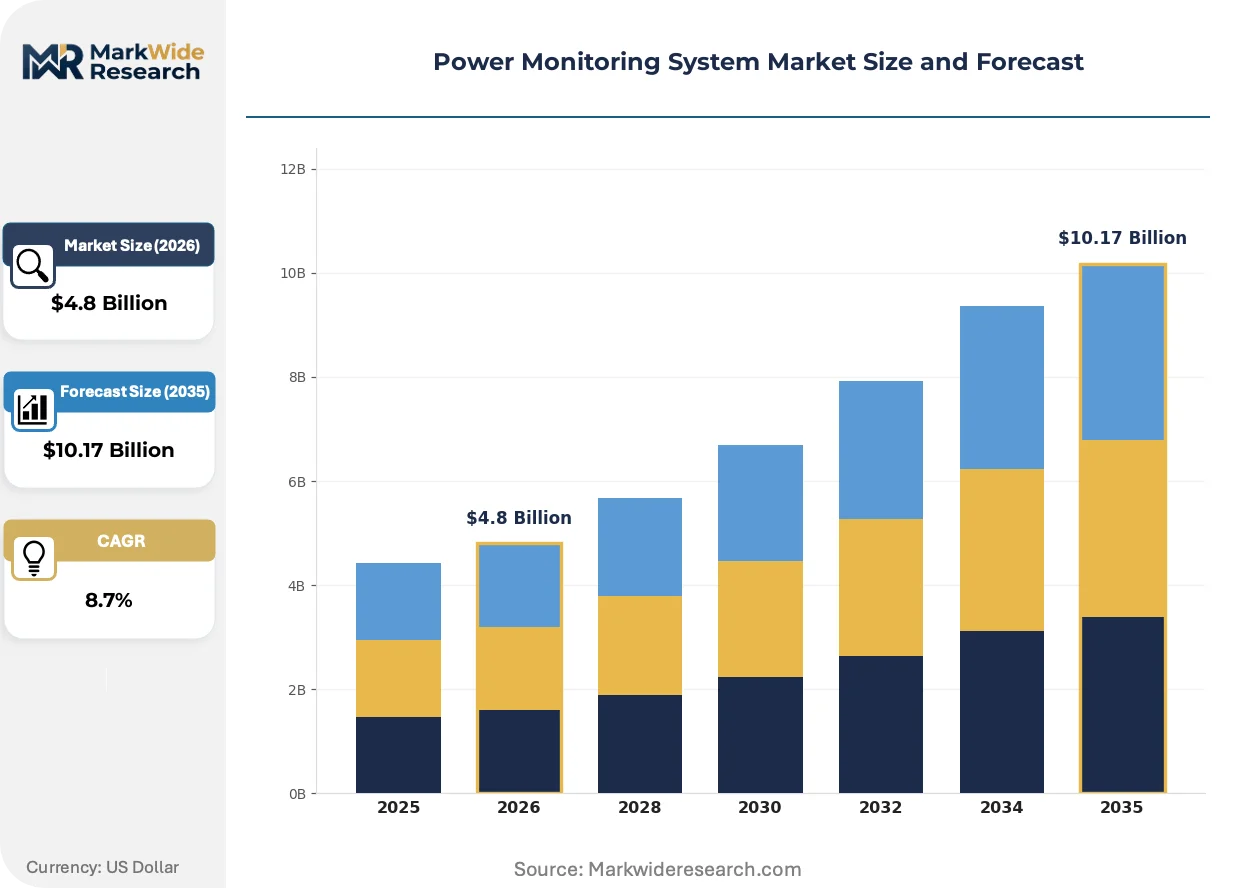
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Meters, Current Transformers, Voltage Sensors, Communication Devices End User: Manufacturing Facilities, Commercial Buildings, Renewable Energy Plants, Data Centers Application: Load Monitoring, Energy Management, Fault Detection, Remote Monitoring Installation: On-Premise, Cloud-Based, Integrated Systems, Distributed Networks |
| Companies Covered | ABB, Schneider Electric, Siemens, Eaton, General Electric, Emerson Electric, Rockwell Automation, Honeywell, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Monitoring System Market Emerging Trajectories
Power monitoring architectures are fragmenting into composable, software-defined layers that separate sensing hardware from analytics engines, enabling faster upgrades without full system replacement.
Intelligent power distribution units are modularizing around hot-swappable meter modules that slide into standard rack enclosures. Colocation providers in Frankfurt and Amsterdam are deploying these units to offer tenant-specific billing without rewiring entire rows. This modularity is compressing upgrade cycles from five-year replacements to incremental meter swaps as density requirements evolve.
REACH restrictions on certain flame-retardant additives are forcing enclosure manufacturers to reformulate housings for power meters and communication gateways. Industrial buyers in the EU are now requiring full material disclosure certificates before procurement approval, shifting competitive advantage toward vendors with established supply chain traceability systems.
Facility managers are unbundling hardware procurement from ongoing analytics subscriptions, treating power monitoring as an operational expense rather than capital investment. Energy service companies are capturing this demand in the Netherlands and Denmark by offering meter-as-a-service contracts where sensors remain vendor-owned. This shift is displacing traditional distributor channels and concentrating purchasing authority with procurement teams rather than engineering departments.
Power Monitoring System Market Segmentation
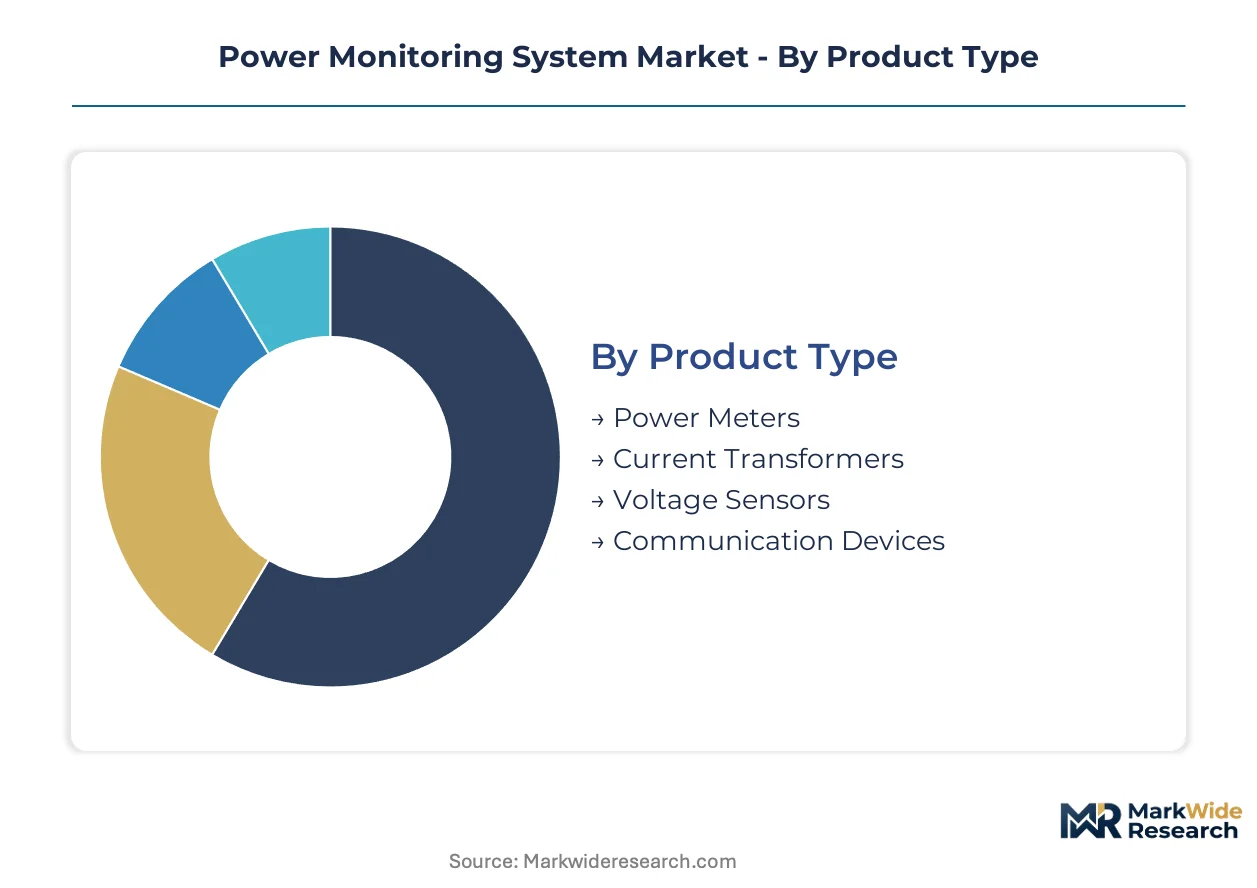
Power monitoring system procurement varies sharply by facility type, with data centers demanding rack-level granularity while manufacturing prioritizes machine-level integration. Segmentation reveals how hardware specifications, communication protocols, and deployment architectures must align with distinct operational constraints and regulatory exposure across end-use environments.
Product Type:
Buyers differentiate primarily by accuracy requirements and integration complexity, with industrial users tolerating higher upfront costs for certified precision while commercial building operators prioritize plug-and-play interoperability.
- Power Meters:Digital measurement devices capture voltage, current, power factor, and harmonic distortion with accuracy classes ranging from 0.5 to 1.0. Data center operators in Frankfurt and Amsterdam are specifying meters with sub-1% error margins to support tenant-specific billing under EU energy disclosure mandates.
- Current Transformers:These sensing elements step down high currents for safe measurement, with copper-core construction dominating industrial-grade applications. German manufacturing clusters are deploying 0.5 accuracy class units to avoid peak demand penalties under national grid modernization frameworks.
- Voltage Sensors:Capacitive and resistive divider technologies enable non-contact potential measurement across medium-voltage distribution networks.
- Communication Devices:Protocol gateways and edge controllers translate Modbus, IEC 61850, and proprietary signals into IP-ready streams for cloud analytics platforms.
Power meters lead volumes today; communication devices are gaining share fastest as edge computing architectures proliferate.
End User:
Facility scale and electrification intensity determine monitoring architecture complexity, with hyperscale data centers requiring branch-circuit visibility that manufacturing plants rarely need.
- Manufacturing Facilities:Heavy industrial sites deploy distributed monitoring nodes across machine lines to manage variable renewable integration and harmonic distortion from variable frequency drives. Polish and Czech mid-sized manufacturers represent underpenetrated whitespace for retrofit-focused service models.
- Data Centers:Hyperscale and colocation operators instrument every rack with intelligent power distribution units streaming telemetry to cloud-based energy management platforms. Rack densities exceeding 50kW per cabinet are forcing abandonment of aggregate metering in favor of branch-circuit-level monitoring.
- Commercial Buildings:Office and retail landlords install certified metering infrastructure to comply with EU Green Deal retrofit mandates requiring continuous energy disclosure above specific square footage thresholds.
- Renewable Energy Plants:Wind and solar operators adopt remote monitoring applications to detect inverter faults and harmonic distortion before capacity degradation occurs.
Manufacturing facilities lead volumes today; data centers are expanding most quickly as rack density requirements intensify.
Application:
Functional priority shapes sensor placement and data refresh rates, with fault detection demanding millisecond response while energy management tolerates minute-level aggregation.
- Remote Monitoring:Cloud-connected architectures enable predictive maintenance from centralized operations centers, with renewable plant operators adopting these applications fastest to detect inverter anomalies before capacity degradation.
- Energy Management:Real-time optimization platforms aggregate meter data to identify load shifting opportunities and automate demand response participation under utility incentive programs.
- Load Monitoring:Continuous tracking of consumption patterns supports capacity planning and prevents overload conditions in industrial distribution networks.
- Fault Detection:High-speed waveform capture identifies short circuits, ground faults, and arc flash conditions to trigger protective relaying and minimize equipment damage.
Energy management leads volumes today; remote monitoring is climbing the fastest as predictive maintenance requirements expand across renewable installations.
Installation:
Capital preference and IT security posture determine deployment architecture, with regulated industries favoring on-premise control while cloud-native operators prioritize subscription flexibility.
- Cloud-Based:Vendor-hosted analytics platforms eliminate capital expenditure and enable continuous feature updates, with Dutch and Danish energy service companies offering meter-as-a-service contracts where sensors remain vendor-owned.
- On-Premise:Local server deployments satisfy data sovereignty requirements and air-gapped security needs in defense, healthcare, and critical infrastructure facilities.
- Integrated Systems:Pre-engineered hardware-software bundles from single vendors reduce commissioning complexity and ensure warranty coverage across the full stack.
- Distributed Networks:Edge-computing architectures place analytics capability at substation or rack level to reduce latency and bandwidth requirements for time-sensitive applications.
On-premise installations lead volumes today; cloud-based deployments are expanding most quickly as facility managers unbundle hardware procurement from ongoing analytics subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers of power monitoring hardware face divergent compliance costs across jurisdictions, driving facility location decisions toward markets with harmonized certification requirements and established supply chains for copper-core transformers and IEC-compliant communication chipsets.
Germany
Industrial electrification programs and grid modernization frameworks are accelerating distributed monitoring node deployment across manufacturing clusters. The EU Green Deal and national efficiency mandates require continuous energy disclosure in commercial buildings above specific thresholds. The Rhine-Ruhr and Stuttgart industrial corridors are retrofitting machine lines with 0.5 accuracy class current transformers to manage variable renewable integration and avoid peak demand penalties.
United States
Hyperscale data center operators are driving branch-circuit-level monitoring adoption as rack densities exceed 50kW per cabinet. The EPA's ENERGY STAR certification requirements for commercial buildings mandate granular energy disclosure and continuous monitoring infrastructure. Northern Virginia's data center corridor and Dallas-Fort Worth are instrumenting every rack with intelligent power distribution units streaming telemetry to cloud-based platforms.
China
Dual carbon goals and national energy intensity reduction targets are compelling industrial facilities to deploy certified metering infrastructure for audit-ready disclosure. The country's national standardization administration enforces GB standards for power quality measurement in heavy industry. The Yangtze River Delta and Pearl River Delta manufacturing belts are adopting remote monitoring applications for predictive maintenance in renewable energy plants.
India
The Bureau of Energy Efficiency's Perform Achieve and Trade scheme mandates granular energy disclosure for designated consumers in energy-intensive sectors. Mid-sized manufacturing facilities lack visibility into machine-level consumption, representing whitespace for retrofit-focused service models. Gujarat and Maharashtra industrial clusters are deploying power monitoring systems to comply with mandatory energy audits and avoid trading scheme penalties.
Netherlands
Energy service companies are capturing demand for meter-as-a-service contracts where sensors remain vendor-owned, treating power monitoring as operational expense rather than capital investment. The EU Corporate Sustainability Reporting Directive creates procurement pull for metering systems generating audit-ready energy intensity metrics. Amsterdam's colocation market is deploying modular intelligent power distribution units to offer tenant-specific billing without rewiring entire rows.
Power Monitoring System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with industrial-grade precision requirements favoring established European and Japanese electrical equipment houses while commercial building retrofits attract modular hardware-as-a-service entrants. The vendor landscape organizes into three tiers: integrated platform providers bundling hardware-software stacks, component specialists supplying accuracy-class-certified transformers and meters, and energy service companies offering subscription-based monitoring outcomes. Consolidation pressure is intensifying as cybersecurity certification timelines for IEC 62443 compliance favor scaled players with dedicated compliance teams, while backward integration into copper-core transformer manufacturing is becoming a margin defense tactic.
Within the integrated platform tier, Schneider Electric, Siemens, and ABB represent divergent geographic and vertical anchoring strategies. The French multinational exemplifies the EcoStruxure-style bundled architecture play, the German engineering group occupies the IEC-compliant industrial power quality analysis position, and the Swiss-Swedish electrical equipment house anchors large-scale manufacturing deployments across Europe and Asia. These three firms sit within distinct competitive vectors despite overlapping product categories, with each representing a template that mid-cap specialists and regional challengers are attempting to replicate or undercut on specific performance dimensions.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| General Electric |
| Emerson Electric |
| Rockwell Automation |
| Honeywell |
| Mitsubishi Electric |
| Others |
Supply Flow & Price Mechanics
EU Green Deal retrofit mandates compelling certified metering infrastructure in commercial buildings above specific square footage thresholds are forcing enclosure manufacturers to reformulate housings for REACH compliance, elevating material disclosure requirements and compressing margin pools for hardware vendors unable to demonstrate supply chain traceability.
Pricing Analysis
Distributor margins on power meters and current transformers typically range from 15-25% for standard accuracy class products, while direct-to-OEM channels serving hyperscale data center operators command volume discounts that compress channel economics. Three-tier pricing structure across premium, standard, and economy levels separates 0.5 accuracy class IEC-certified industrial units from 1.0 class commercial building retrofit products and uncertified economy-tier alternatives. Pricing pressure stems from copper and rare earth input volatility squeezing transformer core manufacturing margins. Commercial building operators exhibit highest price sensitivity, prioritizing plug-and-play interoperability over precision certification, while data center procurement teams accept premium positioning for sub-1% error margins supporting tenant-specific billing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for intelligent power distribution units, while electrical distributors and system integrators serve fragmented commercial building retrofit markets across Germany, France, and Italy. Manufacturing concentration centers on Germany, China, and Japan for current transformer cores, copper windings, and IEC 61850-compliant communication chipsets. Raw material dependencies include copper for transformer construction, rare earth elements for sensor housings, and semiconductor substrates for analog-to-digital converters. Single-source vulnerability in East Asian semiconductor supply for IEC 61850 compliance creates procurement risk. Distribution runs through authorized electrical distributors, direct OEM relationships, and emerging meter-as-a-service energy service companies in the Netherlands and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Power Monitoring System Market functions as a regulatory compounder where the EU Corporate Sustainability Reporting Directive creates sustained procurement pull for metering systems generating audit-ready energy intensity metrics without manual intervention.
For Market Incumbents: To counter cybersecurity certification timeline delays from IEC 62443 compliance requirements, Schneider Electric, Siemens, and ABB should deepen backward integration into copper-core transformer manufacturing to defend margin position against input volatility. Investment in dedicated compliance teams accelerates product launches by compressing third-party validation cycles from twelve months toward six. For New Entrants and Emerging Players: Cloud-based analytics platforms delivered through meter-as-a-service contracts represent the most penetrable route into Dutch and Danish markets where facility managers treat power monitoring as operational expense rather than capital investment. Mid-sized manufacturing facilities in Poland and the Czech Republic lack machine-level consumption visibility, creating whitespace for retrofit-focused service models targeting industrial electrification programs. For Investors and Strategic Acquirers: Asymmetric upside sits with energy service companies offering subscription-based monitoring outcomes that displace traditional distributor channels and concentrate purchasing authority with procurement teams. Five-to-ten year viability hinges on CSRD-aligned disclosure automation capabilities. Watch for inflection when IEC 62443 certification timelines compress below six months, signaling scaled player advantage over mid-cap specialists.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Cybersecurity Certification | Accelerates product launches by compressing third-party validation timelines for operational technology networks. |
| Backward Integration into Transformer Manufacturing | Defends margin pools against copper and rare earth input volatility squeezing hardware economics. |
| Meter-as-a-Service Contract Expansion | Captures Dutch and Danish demand shift from capital expenditure to operational expense treatment of monitoring. |
| CSRD-Aligned Disclosure Automation | Generates audit-ready energy intensity metrics without manual intervention for EU corporate sustainability reporting. |
| Modular Intelligent Power Distribution Unit Development | Enables Frankfurt and Amsterdam colocation providers to offer tenant-specific billing without rewiring entire rows. |
Methodological Framework
Coverage spans Germany, the United States, China, India, and the Netherlands, with primary inputs from each market combining structured interviews with data center operations directors, industrial plant engineers, energy service company executives, and electrical distributor procurement managers alongside secondary validation from SEC filings, EU Ecodesign framework documentation, EPA ENERGY STAR certification databases, and Bureau of Energy Efficiency Perform Achieve and Trade scheme records. Bottom-up and top-down triangulation reconciles facility-level deployment estimates with national energy disclosure mandate compliance targets.
Granularity-level modeling captures product type segmentation across power meters, current transformers, voltage sensors, and communication devices; end user segmentation across manufacturing facilities, data centers, commercial buildings, and renewable energy plants; application segmentation across remote monitoring, energy management, load monitoring, and fault detection; and installation architecture segmentation across cloud-based, on-premise, integrated systems, and distributed networks. CAGRs were derived through regression analysis of historical deployment patterns against regulatory milestone timelines and industrial electrification program commitments. Industry-specific forecast inputs include rack density evolution curves for hyperscale data centers and variable renewable integration penetration rates for German manufacturing clusters.
The model assumes a particular technology adoption path; alternative pathways for edge-computing architectures placing analytics capability at substation or rack level would alter the outlook if latency requirements for time-sensitive applications shift faster than projected. Forecasts reflect stated assumptions regarding EU Green Deal implementation timelines, copper price stabilization, and semiconductor supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Solar Meter Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
US Smart Meter Data Management Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
Power Metering Market