
 Pressure Reducing Valve Market | 2026-2036
Pressure Reducing Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Reducing Valve Market Intelligence
REACH compliance is consolidating the cost-of-entry calculus for European valve manufacturers, forcing material certification upgrades and third-party testing investments that smaller foundries struggle to absorb. Emerson Electric Co. leverages its captive testing infrastructure to sustain margin stability across EU member states. KSB SE & Co. KGaA anchors its position through backward integration into precision casting operations in Germany. Spirax-Sarco Engineering plc differentiates via steam-specialized pilot-operated designs that navigate the interface between industrial process control and building services regulation.
A pressure reducing valve is a self-acting flow control device that maintains a constant downstream pressure regardless of upstream fluctuations, typically incorporating a diaphragm, spring, and poppet assembly with set-point adjustment ranges from 0.5 to 16 bar. Its primary industrial purpose is protecting downstream equipment from pressure surges while optimizing energy consumption in fluid distribution networks. Pilot-operated variants command the widest margin pools in high-flow industrial applications, whereas direct-acting assemblies dominate residential water supply installations where simplicity and fail-safe closure outweigh precision demands. Stainless steel material grades are displacing brass in potable water segments as lead-content restrictions tighten across multiple jurisdictions.
FDA standards for food-contact materials, EPA Lead and Copper Rule revisions, and ISO 9001 quality management frameworks collectively shape product liability exposure and procurement eligibility for valve suppliers serving North American infrastructure. The EU F-Gas Regulation indirectly pressures HVAC application demand by accelerating heat pump deployment, which requires compatible refrigerant pressure control components. Stakeholders must monitor how building decarbonization mandates in Germany, California, and Japan recalibrate the specification balance between water and gas control applications.
Market Dynamics
Water infrastructure decarbonization mandates across Germany, California, and Japan are recalibrating procurement specifications toward stainless steel valve assemblies with embedded pressure sensing capabilities. Municipal buyers now prioritize lifecycle carbon metrics alongside traditional performance benchmarks.
Growth Catalysts
- EU Green Deal water efficiency mandates:Tightening material specifications for brass and stainless steel variants are accelerating replacement cycles in European municipal systems.
- China's industrial corridor expansion:State-backed wastewater treatment programs in corridor cities require high-volume deployment of pilot-operated valve assemblies.
- Lead-content restrictions:Potable water segments are displacing traditional brass with certified stainless steel grades across multiple North American jurisdictions.
Market Restraints
- Copper and nickel price volatility:Brass foundries face margin compression from base metal input cost swings that municipal contract structures rarely index.
- REACH compliance concentration:Third-party testing investments and material certification upgrades consolidate manufacturing among capital-intensive European producers.
- Diaphragm elastomer supply:Specialized fluoroelastomer sourcing depends on a concentrated German and Japanese supplier base with limited geographic redundancy.
Strategic Opportunities
- India's smart city water distribution:Underpenetrated pressure management infrastructure creates demand for direct-acting valves with remote monitoring integration.
- Heat pump HVAC convergence:The EU F-Gas Regulation accelerates refrigerant-compatible pilot-operated valve deployment in building decarbonization projects.
- Digital twin integration:Convergence of IoT pressure sensors with predictive maintenance platforms enables outcome-based service contracting for industrial buyers.
Industry Challenges
- Precision casting talent scarcity:Germany's foundry sector faces recruitment gaps for multi-axis CNC machining and investment casting process engineering.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact, EPA Lead and Copper Rule, and ISO 9001 compliance extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Reducing Valve Market |
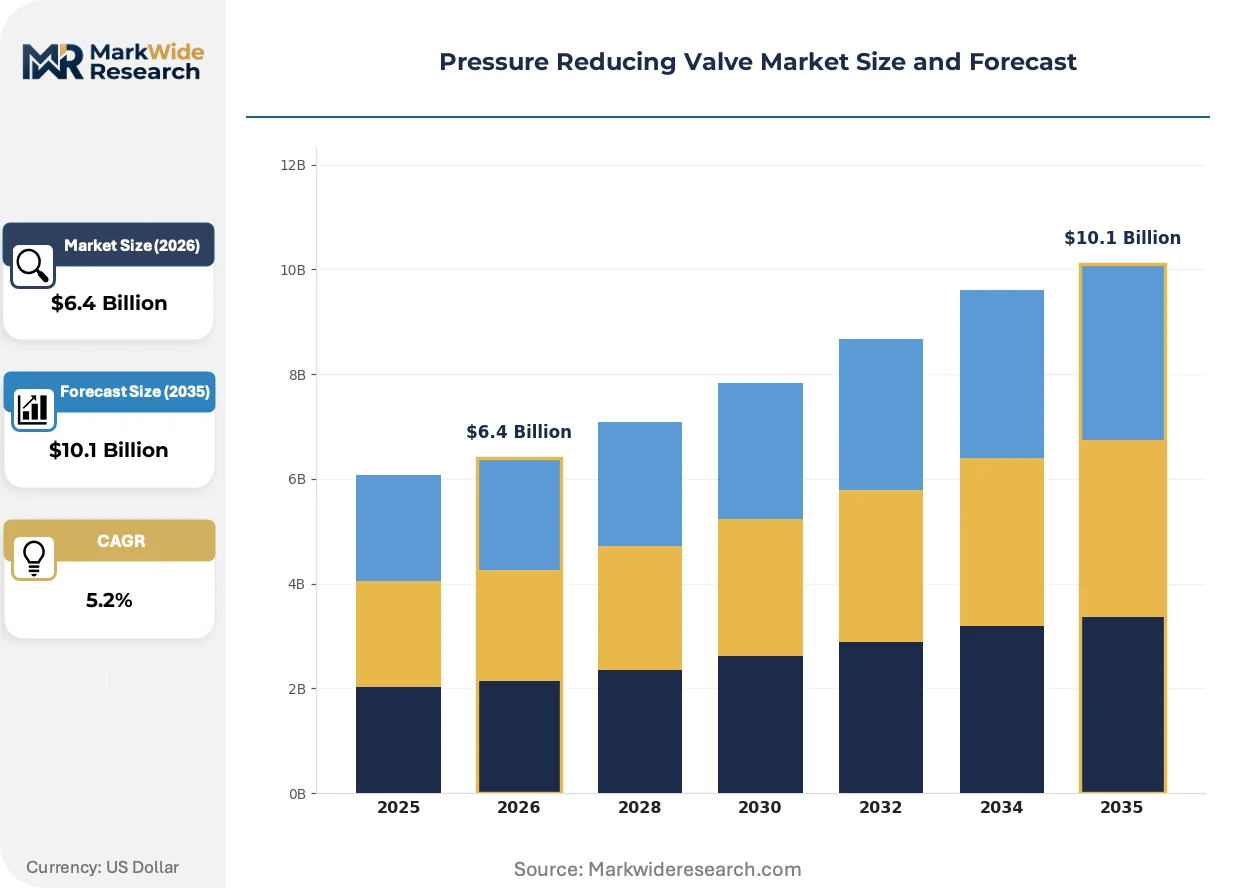
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
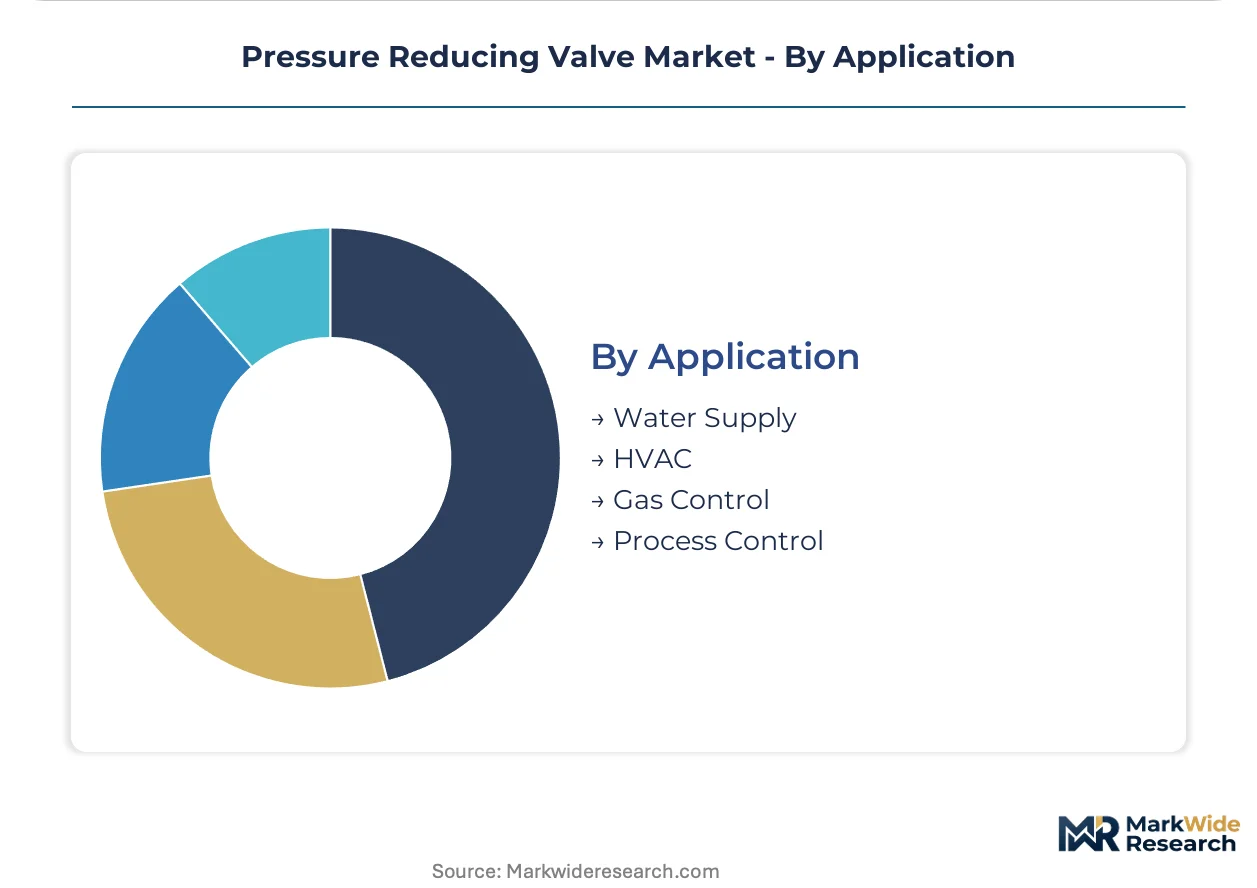
| Segmentation | Product Type: Balanced, Unbalanced, Direct Acting, Pilot Operated Material: Brass, Stainless Steel, Plastic, Bronze End User: Residential, Commercial, Industrial, Agricultural Application: Water Supply, HVAC, Gas Control, Process Control |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Spirax-Sarco Engineering plc, KSB SE & Co. KGaA, Eaton, Parker Hannifin Corporation, Watts Water Technologies, Apollo Valves, Singer Valve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Reducing Valve Market Strategic Shifts & Innovations
Pressure reducing valve architecture is converging with digital sensing and predictive analytics, transforming a mechanical component into a data-generating node within fluid distribution networks. Material science advances and regulatory chemistry restrictions are simultaneously reshaping the bill of materials.
Smart diaphragm assemblies with embedded piezoelectric pressure transducers are automating real-time set-point adjustment and leak detection in German industrial steam systems. Chemical processors and district heating operators are adopting these retrofittable sensor modules faster than anticipated, compressing the traditional maintenance interval from annual to condition-based intervention.
REACH substance restrictions on lead and cadmium content are forcing brass alloy reformulation across European supply chains. Foundries must recertify material grades under ECHA guidance while maintaining mechanical performance specifications, with potable water applications experiencing the most acute compliance timeline pressure.
Specification authority is migrating from municipal procurement officers to engineering-consultant consortia in China's wastewater treatment sector. These technical advisors unbundle valve selection from general contractor packages, demanding extended warranty terms and documented mean-time-between-failure data that smaller manufacturers struggle to provide.
Pressure Reducing Valve Market Segmentation
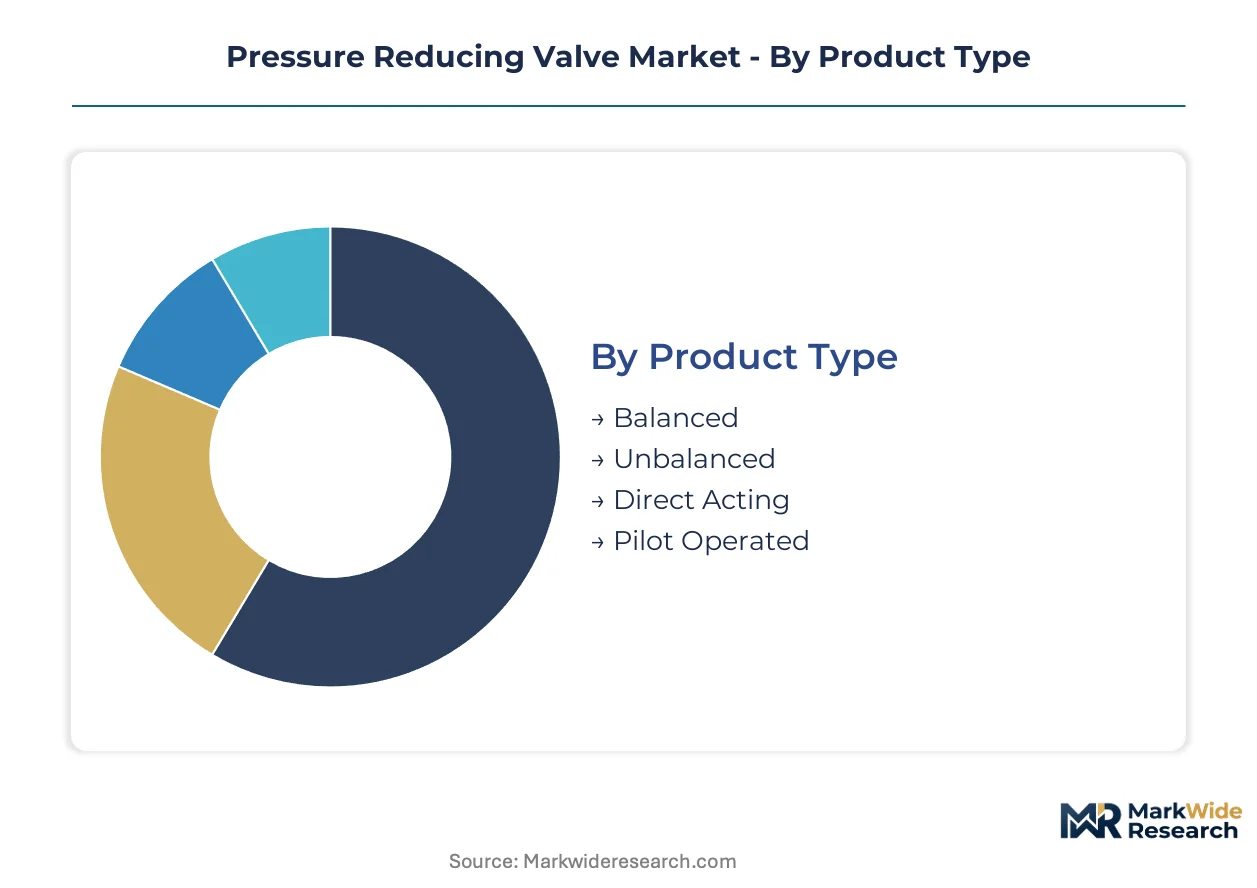
Pressure reducing valve specification varies sharply across pressure ranges, media compatibility, and control precision requirements. Procurement officers segment demand by operational criticality, with fail-safe performance commanding distinct material and architecture choices.
Product Type:
Valve architecture determines response speed, pressure stability, and maintenance complexity across installation scales.
- Pilot Operated:A two-stage configuration uses upstream pressure to amplify diaphragm force, enabling precise control across high-flow industrial distribution networks. Demand concentrates in China's state-backed wastewater treatment corridors, where specification authority has migrated to engineering-consultant consortia demanding documented mean-time-between-failure data.
- Direct Acting:Spring-loaded diaphragm assemblies respond immediately to downstream fluctuations without external sensing lines, prioritizing simplicity over precision. Residential water supply installations in India's smart city distribution networks favor these variants for remote monitoring integration and fail-safe closure characteristics.
- Balanced:Dual-diaphragm designs neutralize upstream pressure effects on set-point stability, serving critical process control environments.
- Unbalanced:Single-diaphragm construction suits low-differential applications where cost minimization outweighs precision requirements.
Mature deployment sits with Direct Acting valves in residential infrastructure. Newer deployment is concentrated in Pilot Operated assemblies for industrial process control.
Material:
Material selection tracks regulatory chemistry restrictions and lifecycle carbon accounting in municipal procurement frameworks.
- Stainless Steel:Austenitic and duplex grades eliminate lead-content liability while withstanding aggressive media and thermal cycling. Germany's water infrastructure decarbonization mandates prioritize these assemblies with embedded pressure sensing capabilities.
- Brass:Traditional copper-zinc alloys face REACH-driven reformulation as ECHA restrictions on lead and cadmium force foundry recertification. Brass retains cost advantage in non-potable HVAC applications across North American jurisdictions.
- Bronze:Copper-tin compositions offer seawater corrosion resistance for coastal and marine installations.
- Plastic:Polymer housings serve low-pressure, chemically aggressive environments where metal fatigue and galvanic corrosion present operational risks.
Brass dominates installed base volume. Stainless steel is gaining share fastest in potable water and food-contact segments.
End User:
Customer type dictates specification authority, warranty expectations, and service contract structures.
- Industrial:Continuous-process manufacturers require predictive maintenance integration and extended warranty coverage. District heating operators in Germany adopt smart diaphragm assemblies with embedded piezoelectric transducers for condition-based intervention.
- Commercial:Building services contractors balance first-cost constraints against energy efficiency certifications. California's building decarbonization mandates recalibrate HVAC specification toward refrigerant-compatible pilot-operated designs.
- Residential:Municipal procurement officers prioritize lifecycle cost over initial acquisition in water supply infrastructure upgrades.
- Agricultural:Irrigation system operators demand field-serviceable designs with minimal technical support requirements.
Industrial buyers anchor premium pricing. Commercial deployment is expanding most quickly under heat pump HVAC convergence.
Application:
Media characteristics and safety classification determine sealing technology, material grade, and certification requirements.
- Water Supply:Potable distribution networks face tightening lead-content restrictions across multiple North American jurisdictions. EPA Lead and Copper Rule revisions accelerate stainless steel displacement of traditional brass in municipal procurement.
- HVAC:Refrigerant pressure control requirements intensify under EU F-Gas Regulation acceleration of heat pump deployment. Japan's building decarbonization mandates similarly recalibrate specification balance toward gas-compatible components.
- Process Control:Chemical processors demand material certificates and elastomer compatibility documentation for aggressive media handling.
- Gas Control:Fuel gas distribution requires fail-safe closure and overpressure protection certification under national pressure equipment directives.
Water Supply commands the largest installed base. HVAC is climbing the fastest under building decarbonization policy convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial corridor cities concentrate procurement volume through state-backed wastewater treatment expansion. Germany's foundry sector anchors European supply capability. The United States, India, and Japan complete the geographic footprint with distinct regulatory and demand profiles.
United States
Municipal water infrastructure upgrades accelerate procurement of stainless steel valve assemblies across the Sun Belt and Rust Belt corridor cities. EPA Lead and Copper Rule revisions tighten material specifications for potable water applications. Texas and California municipalities prioritize lifecycle carbon metrics alongside traditional performance benchmarks in procurement frameworks.
Germany
District heating operators adopt smart diaphragm assemblies with embedded sensing capabilities for condition-based maintenance. EU Green Deal water efficiency mandates force brass alloy reformulation across foundry supply chains. Bavaria and North Rhine-Westphalia industrial clusters concentrate precision casting capability facing recruitment gaps for CNC machining talent.
China
State-backed wastewater treatment programs in Yangtze River Delta and Pearl River Delta corridor cities require high-volume deployment of pilot-operated valve assemblies. Engineering-consultant consortia now unbundle valve selection from general contractor packages. Shanghai and Shenzhen procurement offices demand extended warranty terms and documented reliability data.
India
Smart city water distribution programs create demand for direct-acting valves with remote monitoring integration in underpenetrated pressure management infrastructure. Bureau of Indian Standards certification requirements shape import eligibility and domestic manufacturing investment. Maharashtra and Gujarat urban clusters concentrate municipal procurement authority for infrastructure modernization.
Japan
Building decarbonization mandates recalibrate HVAC specification toward refrigerant-compatible pilot-operated designs in heat pump deployment. METI efficiency standards pressure building services contractors toward energy-certified component selection. Tokyo and Osaka metropolitan procurement frameworks prioritize embedded pressure sensing capabilities in new construction.
Pressure Reducing Valve Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure concentrates manufacturing among capital-intensive producers capable of absorbing multi-jurisdiction certification costs. Three archetypes dominate: integrated industrial conglomerates with captive testing infrastructure, precision casting specialists with backward integration into foundry operations, and steam-application specialists with process-control expertise. Competitive moves center on material certification upgrades and predictive maintenance platform integration.
Within the integrated industrial tier, Emerson Electric Co. and Honeywell International Inc. exemplify capital-intensive positioning through captive infrastructure deployment. Spirax-Sarco Engineering plc occupies a specialist position in steam-application engineering. KSB SE & Co. KGaA anchors German-origin manufacturing capability through in-house precision casting control. These three represent distinct strategic postures: diversified conglomerate, application specialist, and vertically integrated fabricator.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Spirax-Sarco Engineering plc |
| KSB SE & Co. KGaA |
| Eaton |
| Parker Hannifin Corporation |
| Watts Water Technologies |
| Apollo Valves |
| Singer Valve |
| Others |
Cost & Logistics Intelligence
Municipal procurement officers in China's Yangtze River Delta corridor wield outsized pricing leverage through consolidated state-backed wastewater treatment tenders, compressing margins for valve assemblies while rewarding suppliers with captive foundry capacity and multi-jurisdiction certification infrastructure.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to pilot-operated valve assemblies for urgent industrial retrofits, while spot inventory of direct-acting residential units trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant stainless steel variants command substantial markups over reformulated brass alternatives. Pricing pressure stems from copper and nickel input cost volatility that municipal contract structures rarely index, squeezing foundry margins. Commercial HVAC contractors exhibit highest price sensitivity due to first-cost procurement frameworks, whereas district heating operators prioritize lifecycle reliability over acquisition expenditure.
Supply Chain Analysis
Container freight rate fluctuations between German foundry clusters and Chinese industrial corridor cities directly impact landed cost competitiveness for precision-cast valve bodies. Manufacturing concentrates in Germany, China, and India, with Bavaria and North Rhine-Westphalia anchoring European precision casting capability. Raw material sourcing draws from Chilean copper concentrates, Indonesian nickel laterites, and domestic Chinese rare earth processing for specialized diaphragm elastomers. Single-source vulnerability pervades the concentrated German and Japanese fluoroelastomer supplier base. Distribution runs through engineering-consultant consortia in China and municipal procurement frameworks in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints across Germany's precision casting sector prop pricing stability, as recruitment gaps for multi-axis CNC machining talent limit output expansion regardless of order book depth.
For Market Incumbents: Acquire captive testing infrastructure and certification laboratories to defend margin stability against REACH compliance concentration that smaller European foundries cannot absorb. Deepen backward integration into precision casting operations to secure material grade control and recertification timelines. Prioritize smart diaphragm assembly development with embedded sensing capabilities, as district heating operators in Germany accelerate condition-based maintenance adoption. For New Entrants and Emerging Players: EPA Lead and Copper Rule revisions in the United States open a window for stainless steel valve specialists to displace traditional brass incumbents in potable water segments. Target India's smart city water distribution programs with direct-acting valve offerings featuring remote monitoring integration, as underpenetrated pressure management infrastructure creates first-mover positioning. Pursue partnership routes with engineering-consultant consortia rather than direct municipal contracting to bypass entrenched general contractor relationships. For Investors and Strategic Acquirers: The window for entry favors vertically integrated fabricators with in-house foundry control and established multi-jurisdiction certification portfolios. Long-term viability rests on manufacturers capable of spanning both water infrastructure decarbonization mandates and heat pump HVAC convergence applications. Watch for consolidation signals among mid-tier brass foundries facing ECHA reformulation deadlines and recertification cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive foundry control secures material grade certification timelines against REACH-driven recertification pressures. |
| Smart Diaphragm Assembly Development | Piezoelectric sensor integration enables condition-based service contracting with German district heating operators. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EPA, and ISO compliance accelerates procurement eligibility across North American infrastructure. |
| Heat Pump HVAC Component Repositioning | Refrigerant-compatible pilot-operated designs align with EU F-Gas Regulation and Japan METI efficiency standards. |
| Engineering-Consultant Channel Partnership | Direct technical advisor relationships in China bypass general contractor bundling and unlock specification authority. |
Research Approach
Independent corroboration across municipal procurement officers, foundry operations managers, and engineering-consultant technical advisors underwrites the qualitative findings, validated against customs trade data, ECHA substance restriction guidance, and SEC filings from diversified industrial conglomerates. Primary interviews with plant engineers at continuous-process manufacturers and aftermarket service heads at valve distributors informed operational demand patterns. Secondary sources included Bureau of Indian Standards certification records, EPA Lead and Copper Rule revision dockets, and district heating operator maintenance expenditure disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Comparable-period anchoring to historical infrastructure investment cycles and regulatory implementation timelines structured the projection horizon. The analytical framework modeled demand across product architecture, material grade, end-user vertical, and application media, with additional segmentation by regional procurement framework maturity. CAGRs derived from installed base replacement velocity, new build penetration rates, and policy-mandated upgrade schedules. Forecast inputs incorporated copper and nickel price scenario modeling, REACH substance restriction phase-in timelines, and heat pump deployment trajectories under building decarbonization mandates.
The model assumes a particular technology adoption path; alternative pathways for IoT-embedded pressure sensing and predictive maintenance platform integration would alter the outlook for service revenue capture and maintenance interval compression. Forecasts reflect assumptions regarding regulatory enforcement consistency, foundry capacity expansion feasibility, and elastomer supply chain resilience. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
One-Way Valve Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Valve Grinder Market
Valves
Top Drive Systems Market
Valves
Angle Opening Ball Locator Market
Valves
Float Traps Market
Valves
Supply Stop Valves Market
Valves
Pneumatic Slide Gates Market
Valves
Europe Butterfly Valve Market
Valves
Sandblast Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Degassing Valves Market
Valves
Oil Drain Valves Market
Valves
Fin Tube Market