
 Smart Utility Solutions Market | 2026-2036
Smart Utility Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Utility Solutions Market Insights
The capital-intensity divergence between players is rotating competitive advantage toward firms with captive semiconductor and firmware development capabilities. Siemens leverages its in-house silicon design for grid-edge controllers to sustain pricing power in European tenders. Schneider Electric anchors its position through deep backward integration into power electronics manufacturing for smart metering hardware. IBM competes via software-led architectures that extend analytics layers across multi-vendor device fleets.
Smart utility solutions encompass integrated hardware-software systems that monitor, control, and optimize electricity, gas, and water infrastructure through real-time data acquisition with sub-second telemetry refresh rates and cybersecurity protocols meeting IEC 62351 standards. Their primary commercial purpose is to reduce non-technical losses, defer capital-intensive peak capacity investments, and enable bidirectional energy flows in decarbonized networks. Smart Metering occupies the largest installed base but faces margin compression as commoditization spreads across basic AMI endpoints. Grid Management captures disproportionate value creation as utilities prioritize visibility into distributed solar and battery assets. AI within the Technology dimension represents the fastest-expanding capability layer, though Cloud Computing still leads in contract value due to multi-year enterprise SaaS commitments from major utilities.
FERC Order 2222, the EU Green Deal, and GDPR collectively shape product roadmaps by mandating interoperability, carbon accounting transparency, and consumer data sovereignty across utility platforms. The EPA's evolving power plant emissions standards further tighten the compliance envelope for fossil-dependent utilities evaluating upgrade cycles. Stakeholders must monitor whether NIST's forthcoming cybersecurity framework revisions for critical infrastructure will force hardware refresh timelines faster than planned depreciation schedules allow.
Market Dynamics
Grid-edge AI inference is compressing decision latency from minutes to milliseconds, forcing utilities to rebuild procurement specifications around real-time telemetry rather than batch-processing architectures.
Growth Catalysts
- FERC Order 2222:This US mandate requires regional transmission organizations to integrate distributed energy resources into wholesale markets, compelling utilities to deploy bidirectional communication infrastructure.
- Battery storage proliferation:Behind-the-meter lithium-ion installations are creating demand for sub-second load forecasting algorithms that optimize charge-discharge cycles.
- Germany's coal exit law:Binding municipal decarbonization timelines are accelerating tenders for grid management platforms that coordinate solar, wind, and demand response assets.
Market Restraints
- Semiconductor supply concentration:Taiwan-dominant foundry capacity for industrial-grade microcontrollers creates 18-24 month lead time volatility for smart meter deployments.
- GDPR compliance friction:Granular consumer energy data sovereignty requirements add architectural complexity to cross-border cloud analytics platforms serving European utilities.
- Copper and rare earth input costs:Power electronics manufacturing faces margin pressure from commodity price swings in transformer-grade copper and neodymium for grid hardware.
Strategic Opportunities
- Virtual power plant aggregation:Software platforms that pool rooftop solar and EV batteries into dispatchable capacity reserves represent an underpenetrated revenue model for European municipal utilities.
- India's PLI scheme:Domestic manufacturing incentives for advanced chemistry cell batteries are creating localized demand for compatible grid integration hardware.
- Digital twin convergence:The intersection of physics-based simulation with live SCADA feeds enables predictive maintenance contracts that shift revenue from capex to recurring service fees.
Industry Challenges
- Cybersecurity certification backlog:IEC 62351 compliance testing for grid-edge devices faces laboratory capacity constraints, stretching product launch timelines.
- Legacy SCADA integration:Proprietary protocols from 1990s-era control systems require expensive protocol translation layers that erode smart platform ROI calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Utility Solutions Market |
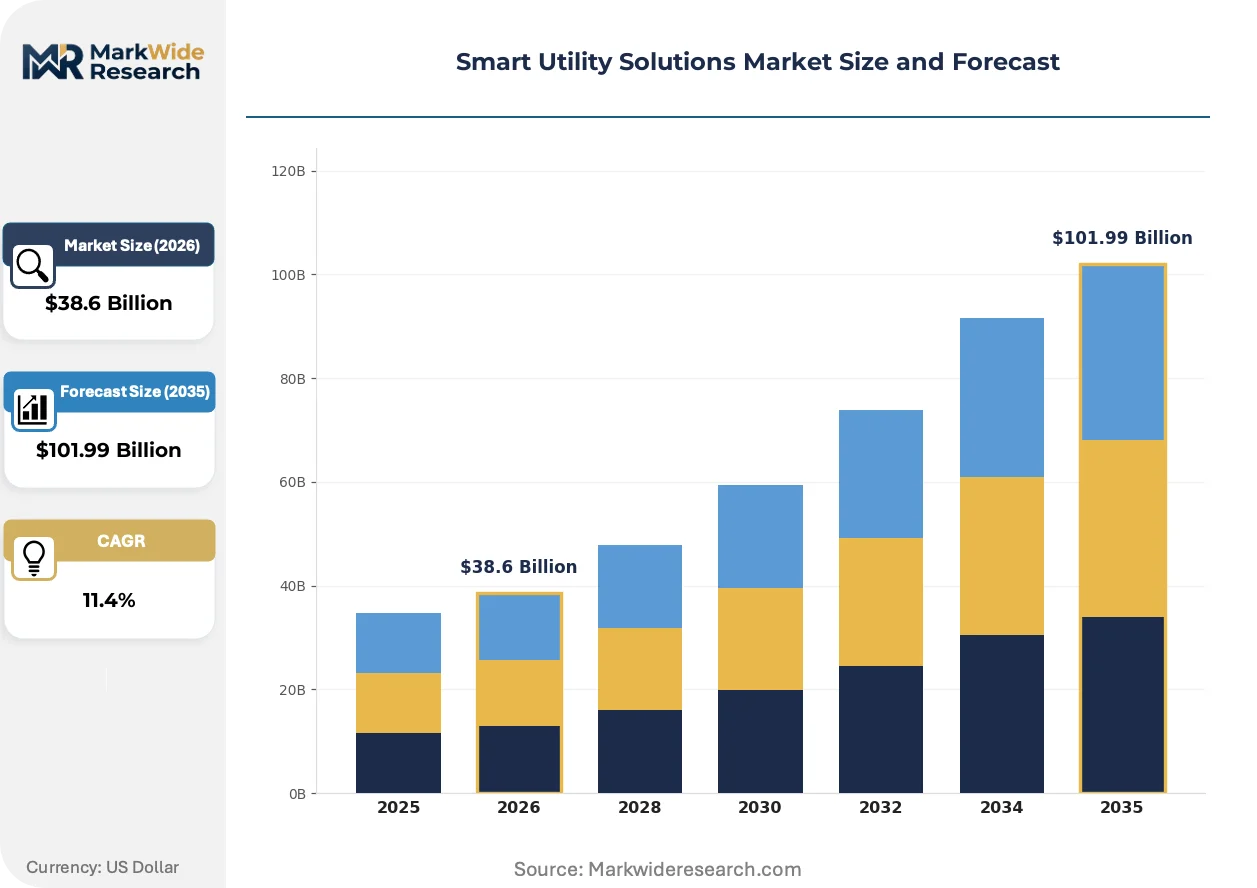
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Metering, Grid Management, Asset Analytics, Demand Response Technology: IoT, Cloud Computing, Big Data, AI End User: Utilities, Energy Companies, Municipalities, Enterprises Installation Type: On-Premises, Cloud-Based, Hybrid, Managed Service |
| Companies Covered | Siemens, Schneider Electric, ABB, General Electric, Itron, Honeywell International, IBM, Eaton, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Utility Solutions Market Trends and Innovations
Edge-native AI architectures are migrating inference workloads from centralized cloud instances to substation-housed GPUs, collapsing network bandwidth requirements while tightening cybersecurity perimeters.
Transformer-based neural networks for load forecasting are displacing traditional ARIMA statistical models in European distribution system operator procurement specifications. RWE and E.ON have both mandated deep-learning approaches in recent grid management tenders. This shift is compressing vendor differentiation around proprietary training datasets rather than algorithmic IP.
The EU AI Act's risk classification framework is imposing documentation burdens on high-stakes grid optimization algorithms. Automated decision systems managing critical infrastructure must now maintain audit trails and human oversight protocols. German transmission operators are responding by restructuring procurement contracts to allocate liability for algorithmic failures.
Performance-based service agreements are replacing traditional hardware-plus-software bundles in North American utility procurement. Duke Energy and Southern California Edison now structure vendor payments around measurable outcomes including outage duration reduction and peak demand deferral. This model concentrates most visibly in states with aggressive renewable portfolio standards where grid stability risks carry regulatory penalties.
Smart Utility Solutions Market Segmentation
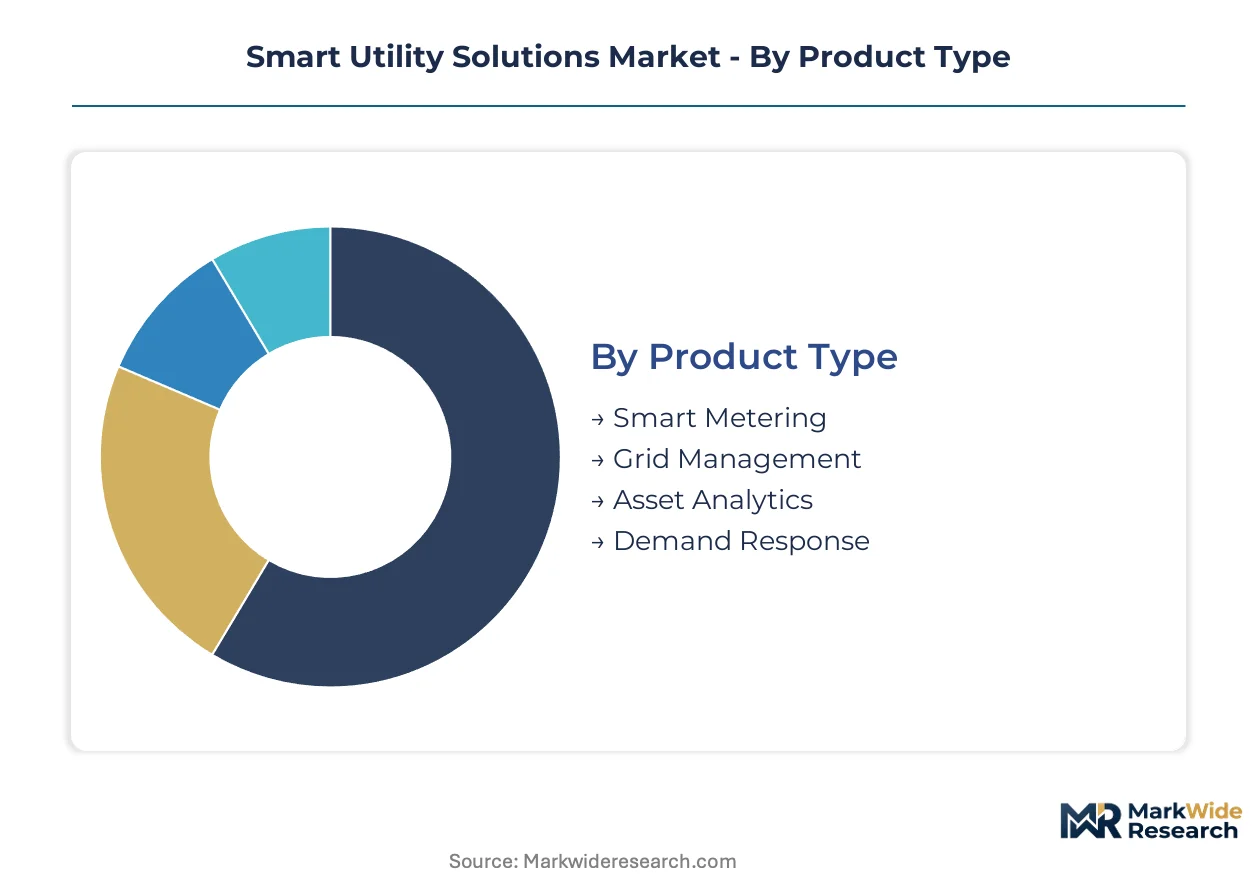
Segmentation in smart utility solutions determines procurement specifications, compliance pathways, and vendor selection criteria. Product architecture choices cascade into regulatory obligations under FERC Order 2222 and the EU Green Deal. Understanding where value concentrates across dimensions enables targeted platform investments.
Product Type:
FERC Order 2222 and Germany's coal exit law create divergent capability requirements across product categories, with grid management platforms facing stricter interoperability mandates than metering hardware.
- Smart Metering:AMI endpoints with sub-second telemetry refresh rates and IEC 62351 cybersecurity certification. Demand concentrates in Germany where municipal utilities face binding decarbonization timelines requiring granular consumption visibility for demand response programs.
- Grid Management:Distributed energy resource orchestration platforms enabling bidirectional power flows and real-time asset coordination. Procurement accelerates in the United States as regional transmission organizations comply with FERC Order 2222 wholesale market integration requirements.
- Asset Analytics:Predictive maintenance algorithms applied to transformer fleets and substation equipment.
- Demand Response:Load curtailment and shift optimization systems for commercial and industrial accounts.
Grid Management handles the majority of throughput; Grid Management is also the fastest mover on share as distributed solar and battery penetration deepens.
Technology:
Cost tier differentiation separates enterprise-grade deployments from municipal utility budgets, with cloud computing commanding multi-year SaaS commitments while edge AI requires capital-intensive GPU infrastructure.
- IoT:Sensor networks and communication modules for grid-edge telemetry. Deployment concentrates in European distribution system operator tenders specifying LPWAN and cellular connectivity for rural substations.
- Cloud Computing:Centralized data lakes and analytics platforms serving multi-tenant utility architectures. Contract value leadership reflects enterprise SaaS commitments from major North American utilities spanning 5-7 year terms.
- Big Data:Historical load pattern repositories supporting long-term infrastructure planning.
- AI:Machine learning inference for real-time grid optimization and load forecasting.
Cloud Computing anchors current procurement volumes; AI is expanding most quickly as transformer-based neural networks displace statistical forecasting models.
End User:
Customer type determines procurement complexity, with municipal utilities prioritizing GDPR-compliant data sovereignty while investor-owned utilities emphasize outcome-based vendor contracts.
- Utilities:Investor-owned and publicly held distribution system operators. Procurement in the United States increasingly structures payments around measurable outage reduction and peak demand deferral metrics.
- Energy Companies:Generation and retail power providers seeking grid-edge visibility. German municipal utilities under coal exit law timelines represent the most active tendering segment for integrated platform deployments.
- Municipalities:City-owned utility departments with constrained capital budgets.
- Enterprises:Large commercial and industrial accounts procuring behind-the-meter optimization.
Utilities command the dominant share of contract value; Energy Companies are climbing the fastest as vertical integration strategies expand platform ownership.
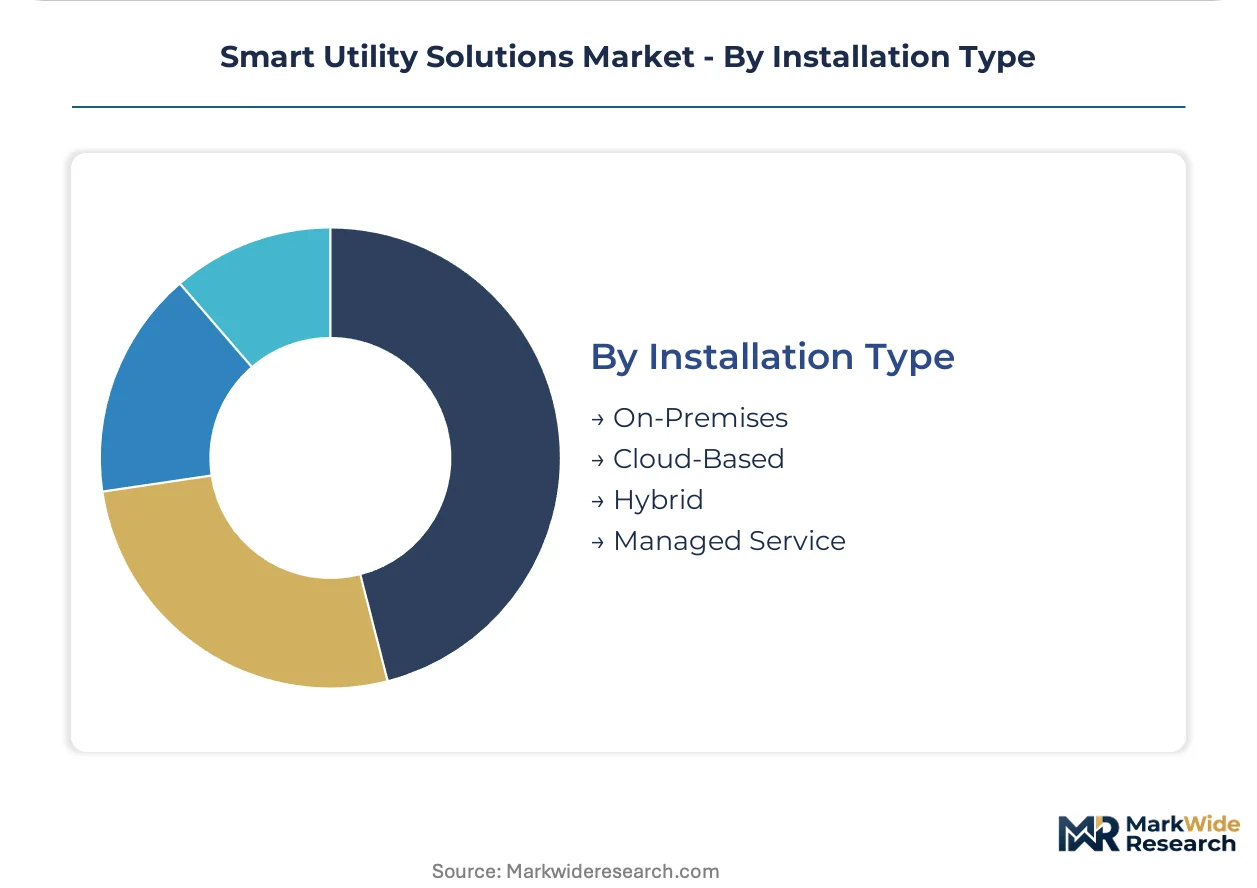
Installation Type:
Supply concentration in Taiwan-dominant semiconductor foundries creates 18-24 month lead time volatility that favors cloud-based and managed service models over on-premises hardware deployments.
- On-Premises:Dedicated hardware and software stacks within utility data centers. Preferred by German transmission operators responding to EU AI Act documentation burdens for high-stakes grid algorithms requiring localized audit trails.
- Cloud-Based:Multi-tenant SaaS architectures with utility-specific instance isolation. North American investor-owned utilities favor this model to accelerate deployment timelines despite cybersecurity perimeter expansion.
- Hybrid:Split architectures with sensitive control functions on-premises and analytics in cloud.
- Managed Service:Outsourced operations and maintenance with performance-based service level agreements.
Cloud-Based deployments handle the majority of new contract starts; Managed Service is gaining share fastest as outcome-based agreements replace traditional hardware-plus-software bundles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Municipal utilities in Germany absorb premium pricing for compliance-ready platforms, while Indian state electricity boards prioritize cost-optimized hardware under domestic manufacturing incentives.
United States
Regional transmission organizations drive procurement of bidirectional communication infrastructure. FERC Order 2222 mandates distributed energy resource integration into wholesale markets. Texas and California utilities lead deployment of grid-edge AI for sub-second load forecasting.
Germany
Municipal utilities face binding decarbonization timelines under the national coal exit law. The EU AI Act imposes documentation burdens on automated grid optimization systems. North Rhine-Westphalia transmission operators now structure procurement contracts to allocate algorithmic liability.
China
State Grid Corporation accelerates smart meter deployment under dual carbon goals. MIIT standards govern industrial-grade microcontroller specifications. Yangtze River Delta manufacturing clusters concentrate domestic production of power electronics for grid hardware.
India
State electricity boards expand AMI deployment under the National Smart Grid Mission. The PLI scheme for advanced chemistry cell batteries creates localized demand for compatible grid integration hardware. Maharashtra and Gujarat utilities tender for virtual power plant aggregation platforms.
United Kingdom
Distribution network operators prioritize cybersecurity-certified platforms under evolving critical infrastructure standards. Ofgem price control mechanisms shape procurement timelines for grid management upgrades. London and Southeast utilities concentrate demand for cloud-based analytics architectures.
Smart Utility Solutions Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive dynamic. The upper tier commands pricing power through captive semiconductor design and firmware development capabilities. Specialists compete on protocol expertise for legacy SCADA integration and narrow application domains. Dominant competitive moves include backward integration into power electronics manufacturing and outcome-based service contract restructuring.
Among European industrial conglomerates, Siemens and Schneider Electric exemplify the integrated archetype through in-house silicon and power electronics capabilities. IBM represents the software-led alternative, anchoring multi-vendor analytics architectures without captive hardware production.
| Leading Market Players |
|---|
| Siemens |
| Schneider Electric |
| ABB |
| General Electric |
| Itron |
| Honeywell International |
| IBM |
| Eaton |
| Oracle |
| Others |
Pricing and Supply Chain Analysis
Foundry scale economies in Taiwan and South Korea anchor cost floors for industrial-grade microcontrollers, compressing margin structures for smart meter hardware while elevating pricing power for vendors with captive silicon design capabilities.
Pricing Analysis
Recurring service revenue from predictive maintenance contracts and managed grid operations drives lifetime value capture beyond initial hardware deployment. Three-tier pricing structure across premium, standard, and economy levels segments buyers by cybersecurity certification tier and telemetry refresh rate specifications. Cost compression in basic AMI endpoints is intensifying because commoditization spreads across standardized communication modules. Municipal utilities in Germany exhibit lowest price sensitivity due to binding decarbonization compliance timelines, while Indian state electricity boards prioritize cost-optimized hardware under domestic manufacturing incentives.
Supply Chain Analysis
Strategic stockpiling of transformer-grade copper and neodymium magnets characterizes procurement behavior among European power electronics manufacturers facing commodity price volatility. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States for industrial-grade microcontrollers. Rare earth processing draws from Chinese refining capacity and Australian extraction operations. Single-source vulnerability in Taiwan-dominant foundry capacity creates procurement risk for grid-edge device deployments. Distribution runs through authorized systems integrators and direct utility procurement channels with multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FERC Order 2222 mandates distributed energy resource integration, creating a regulatory inflection that compresses deployment timelines and elevates platform interoperability requirements across wholesale market participants.
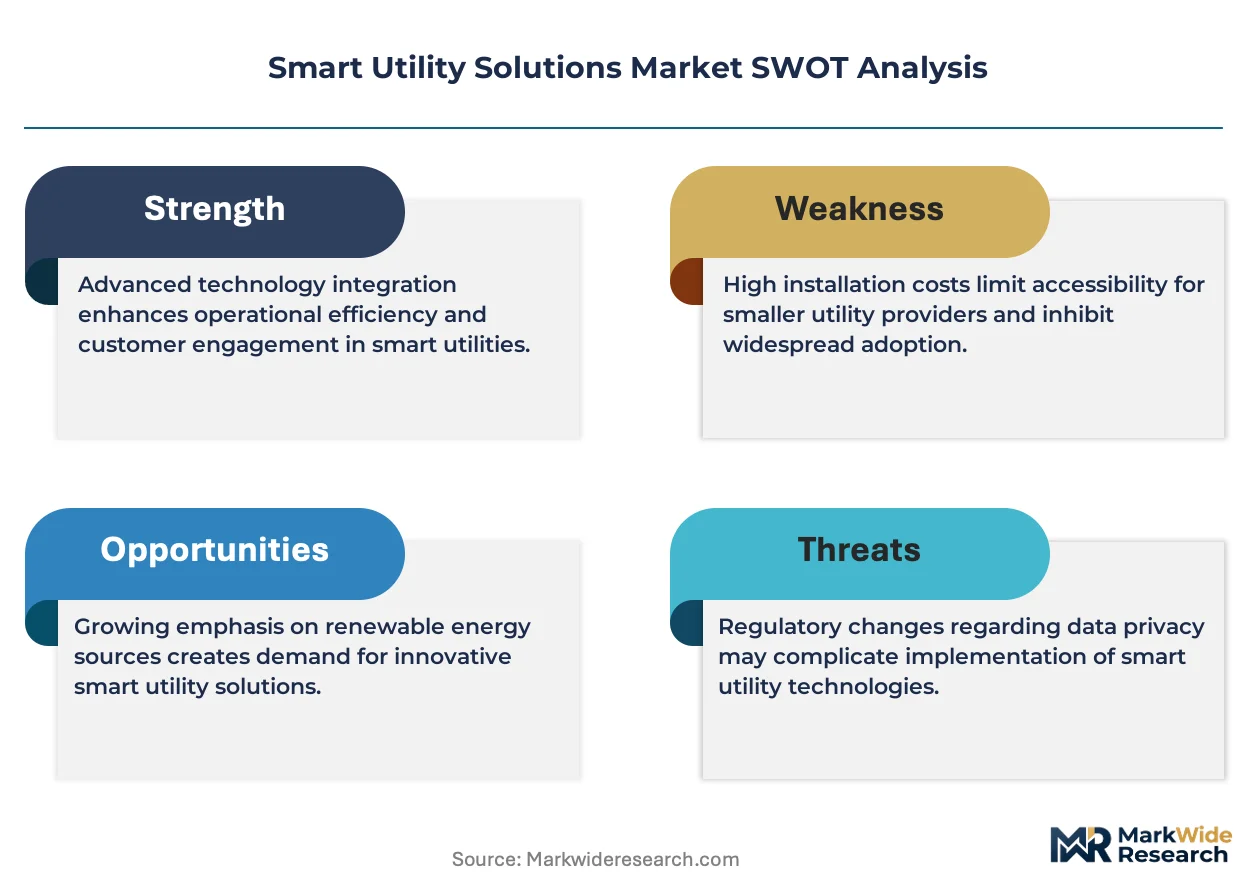
For Market Incumbents: Compound defensive positioning through backward integration into power electronics manufacturing and firmware development capabilities. Threats from software-led competitors like IBM intensify as analytics layers displace hardware-centric value capture. Prioritize IEC 62351 certification investment to maintain tender eligibility in European distribution system operator procurement.
For New Entrants and Emerging Players: Virtual power plant aggregation software represents a service-layer gap where incumbents under-serve European municipal utilities seeking dispatchable capacity reserves. White-space targets include behind-the-meter battery optimization algorithms and legacy SCADA protocol translation tools. Go-to-market through outcome-based service agreements with measurable peak demand deferral metrics.
For Investors and Strategic Acquirers: Edge-native AI architecture specialists with substation-housed GPU deployment capabilities represent the most attractive acquisition target archetype. Long-term viability hinges on regulatory enforcement of the EU AI Act's risk classification framework for critical infrastructure algorithms. Watch for NIST cybersecurity framework revisions forcing hardware refresh timelines as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Schneider Electric's captive manufacturing of smart metering hardware sustains margin capture against commoditized competitors. |
| Edge-Native AI Architecture Deployment | Migration of inference workloads to substation GPUs collapses bandwidth requirements for RWE and E.ON grid management tenders. |
| Outcome-Based Service Contract Restructuring | Duke Energy and Southern California Edison now tie vendor payments to measurable outage duration reduction metrics. |
| IEC 62351 Cybersecurity Certification Investment | Laboratory capacity constraints for grid-edge device compliance testing stretch product launch timelines for uncertified entrants. |
| Virtual Power Plant Platform Development | Maharashtra and Gujarat utilities tender for aggregation software pooling rooftop solar and EV batteries into dispatchable reserves. |
Research Methodology
A spread of perspectives from utility planning officers, grid operators, EPC contractors, and smart meter procurement managers converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation from FERC filings, EIA data, IEA reports, and project development databases. Bottom-up deployment tracking triangulated against top-down regulatory mandate analysis.
Segmentation dimensions modeled span product type, technology layer, end-user category, and installation architecture across the analysis window. CAGRs derived from utility capital expenditure trajectories and distributed energy resource penetration curves. Forecast inputs include regional transmission organization compliance timelines and municipal decarbonization binding commitments.
Forecasts assume regulatory continuity in FERC Order 2222 implementation and EU Green Deal enforcement; material policy shifts would require re-modeling of procurement volume assumptions. Revision becomes warranted when semiconductor foundry capacity utilization or critical mineral price volatility crosses thresholds affecting hardware deployment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Gas Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
United States Smart Meter Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
Plug in Power Meter Market
Smart Meters
US Smart Meter Data Management Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
North America Gas Meter Market
Smart Meters
Smart Water Metering Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Water Meter Market