
 US Water Meter Market | 2026-2036
US Water Meter Market Size, Share, and Industry Trends Forecast 2026-2036
US Water Meter Market Insights
Municipal utility procurement is expanding as smaller water districts consolidate into regional authorities seeking volume purchasing leverage. Badger Meter leverages its vertical manufacturing footprint to control component costs across the Midwest. Itron sustains technology leadership in cellular AMI communications, while Neptune Technology Group anchors its position in the southeastern states through deep distributor relationships.
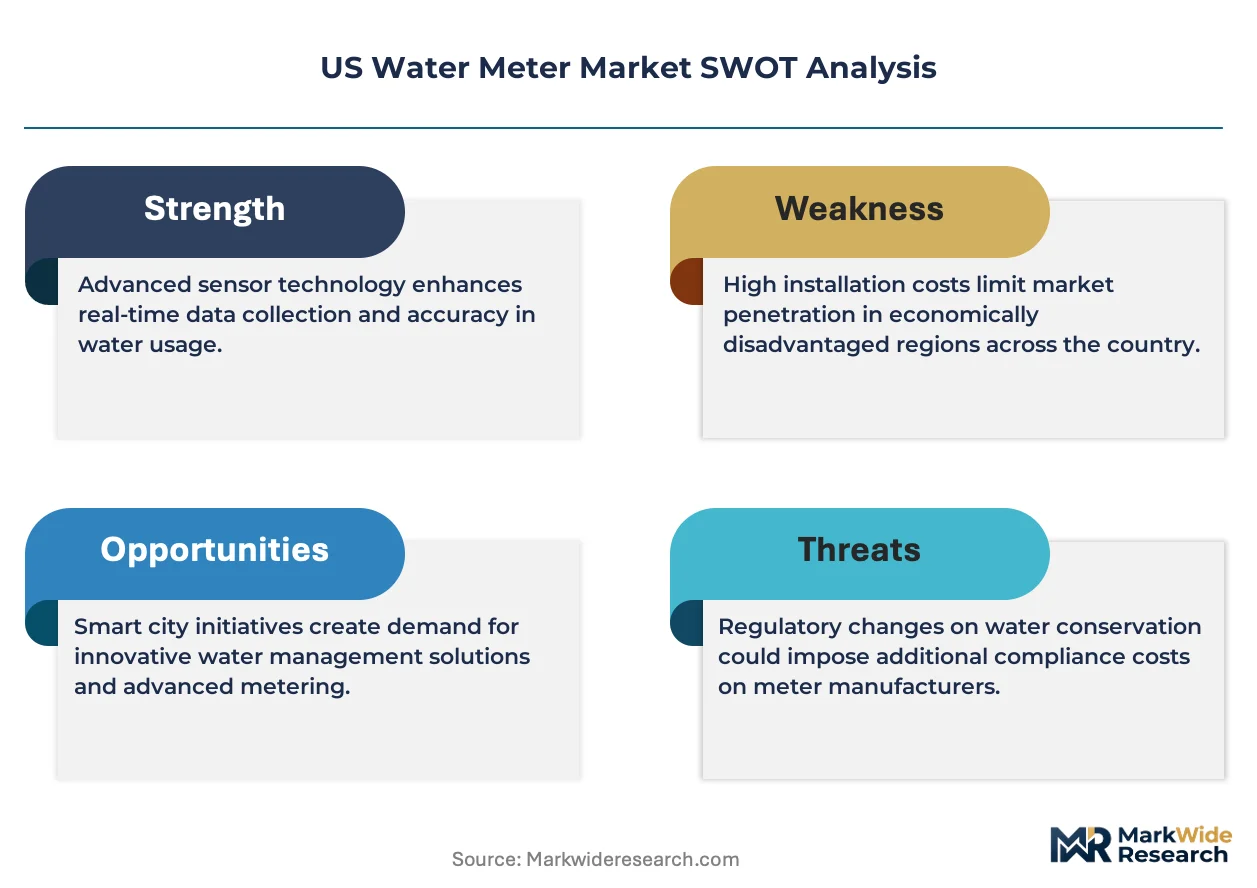
A water meter measures volumetric flow through potable water distribution systems, typically employing turbine, ultrasonic, or electromagnetic sensing principles with accuracy classes spanning ±1.5% to ±2% across nominal flow ranges. These devices enable billing reconciliation, leak detection, and conservation compliance for utility operators. Smart meters now lead product type growth as AMI infrastructure replaces mechanical units, while ultrasonic technology captures premium positioning in commercial and industrial end user segments where low-flow sensitivity determines tariff accuracy. Retrofit installation dominates volume as aging mechanical meter bases exceed calibrated life cycles, though new installation carries higher per-unit margins in greenfield suburban developments.
EPA drinking water standards, AWWA meter accuracy requirements, and state-level public utility commission conservation mandates collectively shape product certification and procurement specifications. The EPA's lead-and-copper rule revisions compel utilities to document service line materials, expanding meter replacement programs as access points for infrastructure inspection. Stakeholders must monitor FCC spectrum allocations for AMI communications and evolving state water loss audit requirements that predicate funding eligibility on metered system coverage.
Market Dynamics
AMI infrastructure rollouts are compressing replacement cycles across US municipal utilities as EPA lead-and-copper rule revisions mandate service line material documentation, forcing meter access points to serve dual inspection and billing functions simultaneously.
Growth Catalysts
- EPA Lead-and-Copper Rule Revisions:Federal mandates require utilities to inventory service line materials, accelerating meter replacement programs as infrastructure access points. Municipal procurement offices in drought-prone states prioritize AMI-enabled devices that support simultaneous compliance documentation.
- Cellular AMI Communications:Low-power wide-area network protocols reduce infrastructure capital requirements for rural water districts. Texas and Arizona utilities deploy LTE-M modules to bypass proprietary radio network buildouts entirely.
- Conservation Pricing Mandates:California Public Utilities Commission tiered rate structures require granular consumption data. Utilities replace mechanical meters with ultrasonic units capable of capturing low-flow leakage for penalty assessment accuracy.
Market Restraints
- Semiconductor Component Concentration:AMI module production depends on foundry capacity concentrated in East Asian supply chains. Lead times for cellular modem chipsets extend procurement planning horizons beyond traditional municipal budgeting cycles.
- Copper Service Line Replacement Backlogs:Pre-1950s infrastructure in Midwestern cities creates meter installation access conflicts. Crews cannot replace meters without triggering full lead service line replacement obligations under revised EPA guidance.
- Mechanical Meter Life Extension:Some utilities defer AMI migration by recalibrating existing turbine units. Third-party testing laboratories certify extended operational life, compressing near-term smart meter demand in budget-constrained districts.
Strategic Opportunities
- Small System Consolidation:Regional water authorities in Appalachia and the Mountain West aggregate purchasing volume for AMI vendors. Consolidated procurement contracts reduce per-unit installation costs below standalone municipal pricing thresholds.
- Industrial Ultrasonic Positioning:Food processing and semiconductor fabrication facilities in Arizona and Texas require ±0.5% accuracy for process water billing. Vendors capture premium positioning by certifying custody-transfer-grade measurement.
- FCC Spectrum Allocation Expansion:Unlicensed 900 MHz band modifications enable longer-range AMI transmissions. Rural cooperatives in the Great Plains deploy extended-range endpoints without cellular subscription overhead.
Industry Challenges
- AMI-Legacy Billing System Integration:Municipal IT departments struggle to synchronize interval data streams with decades-old customer information systems. Middleware development consumes implementation timelines and strains technical staffing capacity.
- Field Technician Training Gaps:Electromechanical meter repair skills do not transfer to ultrasonic sensor diagnostics. Workforce development programs at community colleges in California and Texas lag deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Water Meter Market |
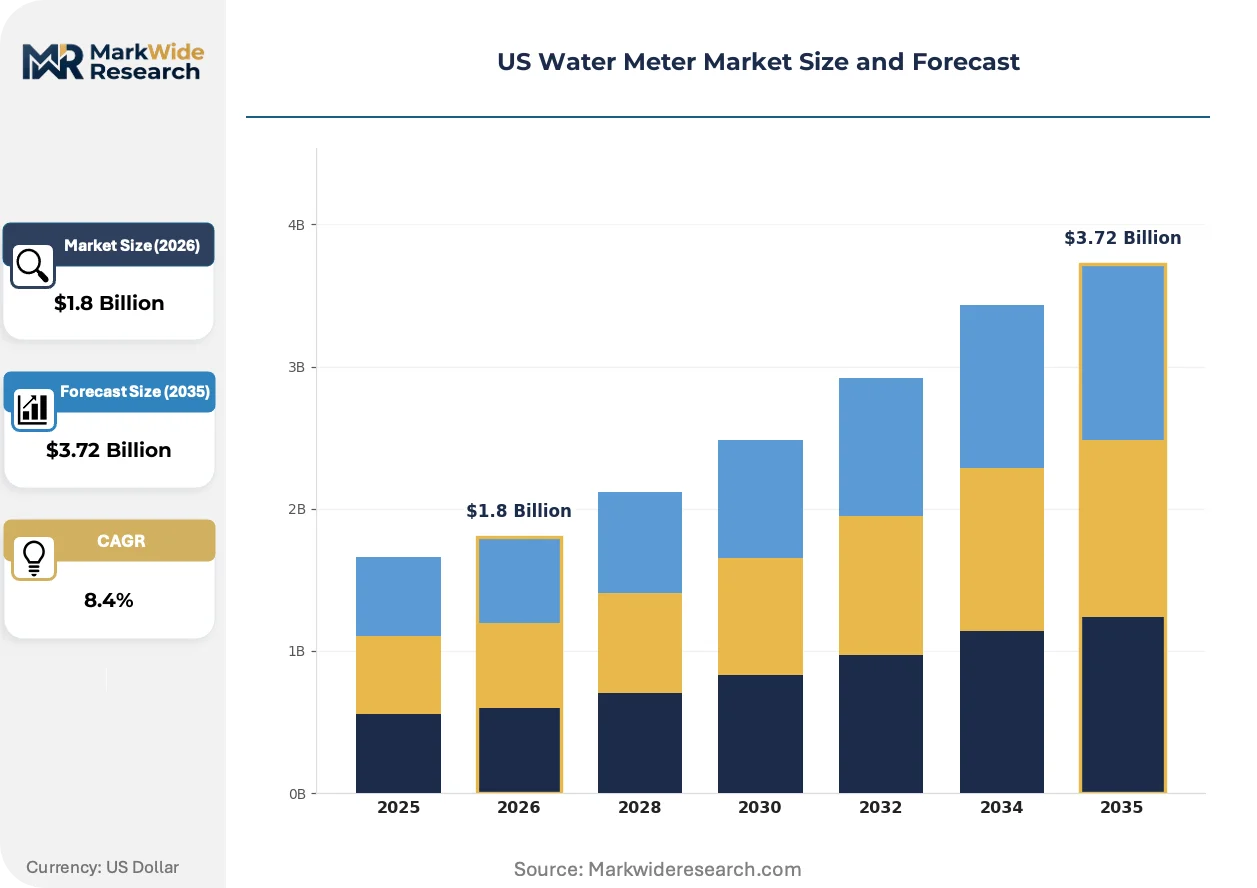
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Meters, Electronic Meters, Ultrasonic Meters, Smart Meters End User: Municipalities, Industrial Users, Commercial Users, Residential Users Technology: Automatic Meter Reading, Remote Sensing, Data Analytics, IoT Solutions Installation Type: Indoor Installation, Outdoor Installation, Retrofit Installation, New Installation |
| Companies Covered | Badger Meter Inc., Itron Inc., Sensus, Neptune Technology Group Inc., Mueller Water Products Inc., Xylem Inc., Honeywell International Inc., Diehl Metering GmbH, Kamstrup A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Water Meter Market Trends and Innovations
Digital measurement architectures are supplanting mechanical sensing across all utility scale tiers, with ultrasonic and electromagnetic principles capturing share from turbine designs as accuracy requirements tighten and data granularity becomes a regulatory compliance asset.
Ultrasonic flow measurement is absorbing demand from commercial and industrial segments where low-flow sensitivity determines tariff precision. Breweries, data centers, and semiconductor fabs in Texas and Arizona specify ±1% accuracy classes for process water accountability. The technology is absorbing margin compression in the premium meter tier as manufacturing scale reduces transducer costs below electromagnetic alternatives.
EPA drinking water infrastructure audits are reshaping procurement specifications nationwide. Revised lead-and-copper rules compel utilities to document service line materials at every customer connection point. California and Arizona water districts now specify AMI-enabled meters with integrated pressure and temperature logging to satisfy state water loss audit requirements that predicate funding eligibility on comprehensive system coverage.
Consolidated procurement through regional water authorities is displacing individual municipal purchasing patterns. Smaller districts in Colorado and Utah pool volumes to negotiate installation pricing and maintenance terms. This concentration is most visible in the Intermountain West where sparse population density previously isolated individual utilities from vendor attention and technical support resources.
US Water Meter Market Segmentation
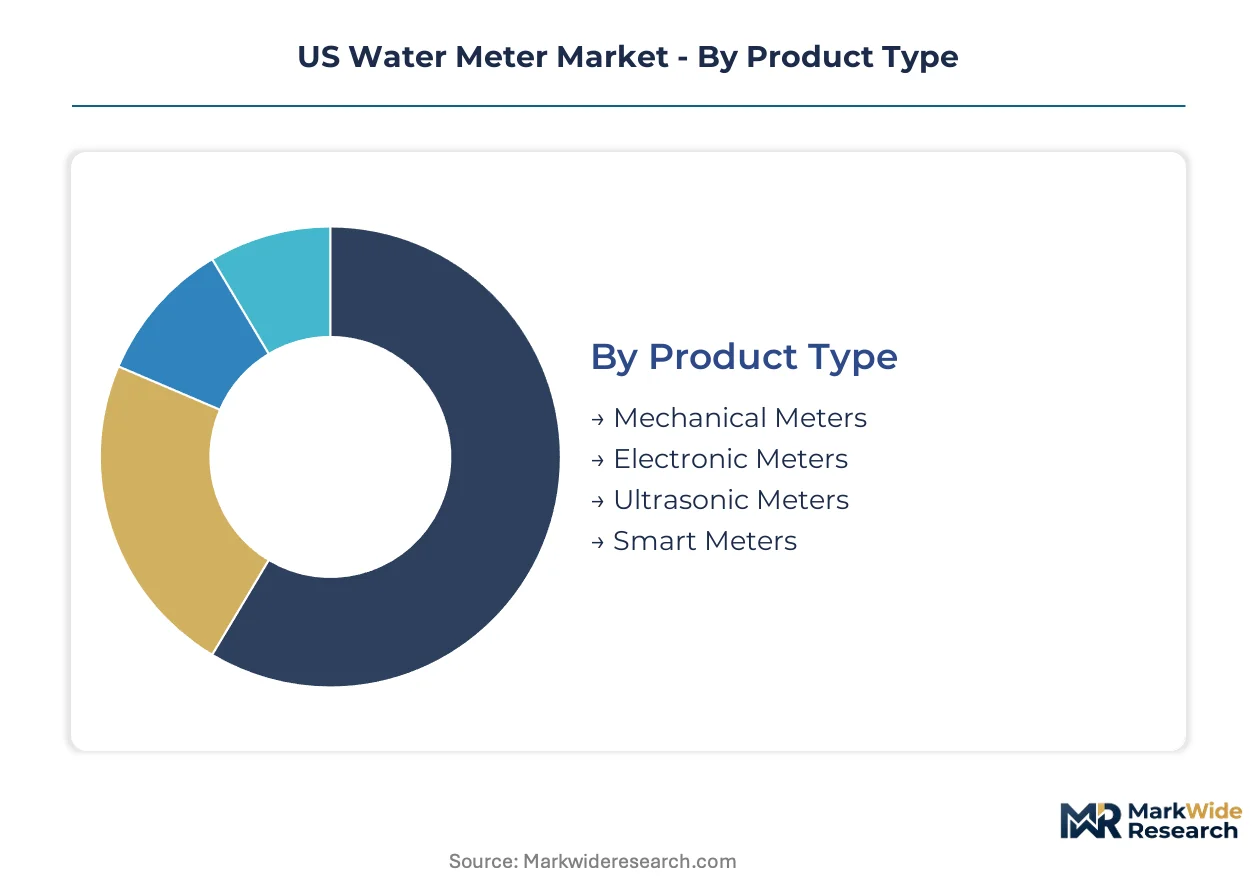
Water meter procurement patterns diverge sharply across product architectures, end-use applications, and deployment methodologies. Understanding these fault lines clarifies where infrastructure budgets flow and which technology transitions offer vendors the strongest positioning leverage.
Product Type:
Replacement cycles dominate volume allocation as aging mechanical infrastructure approaches calibrated end-of-life across municipal systems.
- Mechanical Meters:Turbine and positive displacement designs still account for the installed base majority in legacy systems. California and Texas utilities retain these units in low-priority service territories where AMI capital remains constrained.
- Electronic Meters:Solid-state measurement without moving parts extends operational lifespan in hard-water regions. Arizona water districts specify electromagnetic variants for agricultural metering where sediment abrasion degrades mechanical impellers.
- Ultrasonic Meters:Transit-time and Doppler principles achieve ±1% accuracy across extended flow ranges. Semiconductor fabrication facilities in Texas and Arizona demand custody-transfer-grade precision for process water accountability.
- Smart Meters:AMI-enabled endpoints integrate pressure sensing and temperature logging for leak detection algorithms. EPA lead-and-copper rule revisions accelerate deployment as utilities need meter access points for service line material documentation.
Volume placements concentrate in Mechanical Meters; the faster expansion belongs to Smart Meters.
End User:
Customer type determines data granularity requirements and procurement authority structures across the value chain.
- Municipalities:Regional water authorities in the Intermountain West consolidate purchasing volume for AMI vendors. Consolidated contracts reduce per-unit installation costs below standalone municipal pricing thresholds.
- Industrial Users:Food processing and data center operators in Arizona specify ±0.5% accuracy for tariff precision. Process water billing demands drive premium positioning for ultrasonic and electromagnetic technologies.
- Commercial Users:Multi-tenant properties require sub-metering granularity for conservation compliance. California's tiered rate structures compel shopping centers and office complexes to capture interval consumption data.
- Residential Users:Single-family homes dominate unit volume but generate thinner margins. Retrofit installation prevails as suburban developments built before 2010 lack AMI-ready infrastructure.
Residential Users absorb the highest unit volumes; Industrial Users command the steepest expansion trajectory.
Technology:
Communications architecture selection shapes infrastructure capital requirements and ongoing operational expenditure profiles.
- Automatic Meter Reading:Drive-by and walk-by radio frequency systems offer intermediate automation without full AMI investment. Rural cooperatives in the Great Plains deploy these as budget-constrained stepping stones.
- Remote Sensing:Pressure transducers and acoustic leak detectors extend meter functionality beyond volumetric measurement. Texas utilities integrate these sensors to satisfy state water loss audit requirements.
- Data Analytics:Consumption pattern algorithms identify non-revenue water and customer-side leakage. California water districts leverage these tools to enforce conservation mandates and tiered penalty structures.
- IoT Solutions:Cellular LTE-M modules bypass proprietary radio network buildouts entirely. Arizona utilities favor this approach for sparse rural service territories where fixed network infrastructure proves uneconomical.
Automatic Meter Reading retains the largest installed footprint; IoT Solutions are climbing the fastest.
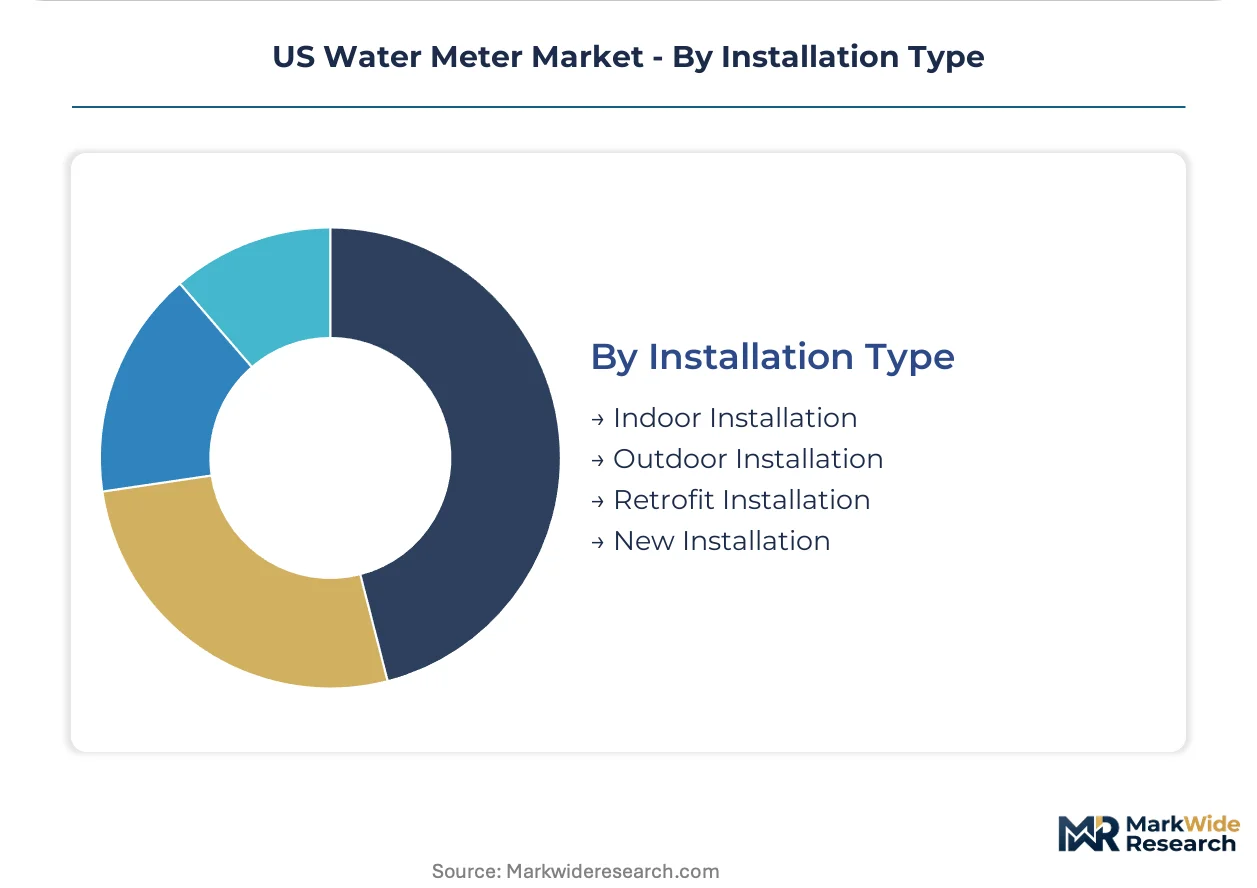
Installation Type:
Site conditions and existing infrastructure dictate labor intensity and margin realization for deployment contractors.
- Indoor Installation:Basement and utility room placements protect electronics from temperature extremes and vandalism. Midwestern cities with pre-1950s housing stock face access constraints that elevate labor costs.
- Outdoor Installation:Pit and curbstop configurations dominate Sun Belt regions with shallow frost lines. Arizona and Texas specifications prioritize UV-resistant enclosures and submersible-rated electronics.
- Retrofit Installation:Mechanical meter base reuse dominates volume as utilities maximize existing infrastructure. California's accelerated replacement programs target units exceeding 15-year calibrated lifecycles.
- New Installation:Greenfield suburban developments in Texas and Arizona carry higher per-unit margins. AMI-ready infrastructure specified at construction avoids costly subsequent upgrades.
Retrofit Installation generates the highest unit volumes; New Installation captures superior margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in drought-prone western states where water scarcity triggers tiered conservation pricing and accelerates AMI procurement cycles. California, Texas, and Arizona absorb the dominant share of smart meter deployments as municipal utilities face simultaneous EPA compliance deadlines and state-level water loss audit mandates.
California
The California Public Utilities Commission enforces tiered rate structures requiring granular consumption data from utilities. Los Angeles Department of Water and Power and San Diego County Water Authority deploy ultrasonic meters capable of capturing low-flow leakage for penalty assessment accuracy. EPA lead-and-copper rule revisions compel utilities to document service line materials at every customer connection point.
Texas
Texas utilities favor cellular LTE-M modules to bypass proprietary radio network buildouts in sparse rural service territories. The Texas Commission on Environmental Quality mandates water loss audits that predicate funding eligibility on comprehensive metered system coverage. Dallas-Fort Worth and Houston metropolitan water authorities consolidate procurement volumes to negotiate installation pricing below standalone municipal thresholds.
Arizona
Arizona water districts specify electromagnetic variants for agricultural metering where sediment abrasion degrades mechanical impellers. The Arizona Department of Water Resources administers conservation programs requiring sub-metering granularity for commercial properties. Semiconductor fabrication facilities in Phoenix and Tucson demand custody-transfer-grade precision for process water accountability.
Mountain West
Regional water authorities in Colorado and Utah aggregate purchasing volumes for AMI vendors as smaller districts consolidate. State water loss audit requirements in Nevada and New Mexico predicate federal funding eligibility on metered system coverage. Denver Water and Salt Lake City Public Utilities deploy extended-range endpoints utilizing unlicensed 900 MHz band modifications for rural cooperative service territories.
Southeast
Neptune Technology Group anchors distributor relationships across Florida, Georgia, and the Carolinas through deep technical support networks. State environmental agencies in the region lag California and Texas in conservation pricing mandates, preserving mechanical meter life extension programs. Atlanta and Charlotte utilities prioritize retrofit installation over greenfield AMI-ready infrastructure as suburban developments predate 2010 construction standards.
US Water Meter Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cellular communications and ultrasonic sensing specializations. The vendor base clusters around three archetypes: vertically integrated domestic manufacturers controlling component costs, technology leaders in AMI communications protocols, and regional specialists leveraging distributor relationships for geographic coverage. Consolidation through regional water authority contracts and strategic partnerships for middleware development represent the dominant competitive moves as municipal IT integration challenges strain implementation timelines.
Among domestic manufacturers, Badger Meter Inc. and Mueller Water Products Inc. exemplify the vertically integrated archetype with Midwest manufacturing footprints. Itron Inc. occupies a position within the technology leadership tier for cellular AMI communications. Neptune Technology Group Inc. anchors the regional specialist model through southeastern distributor networks. Xylem Inc. and Honeywell International Inc. represent diversified industrial conglomerates with water metering divisions. Diehl Metering GmbH and Kamstrup A/S illustrate European-headquartered competitors with US market presence.
| Leading Market Players |
|---|
| Badger Meter Inc. |
| Itron Inc. |
| Sensus |
| Neptune Technology Group Inc. |
| Mueller Water Products Inc. |
| Xylem Inc. |
| Honeywell International Inc. |
| Diehl Metering GmbH |
| Kamstrup A/S |
| Others |
Pricing and Supply Chain Analysis
Captive manufacturing of ultrasonic transducers and cellular modem assemblies anchors both supply security and margin control for leading AMI vendors. Midwest production footprints insulate domestic manufacturers from East Asian foundry bottlenecks while supporting premium positioning for custody-transfer-grade meters in Texas semiconductor fabs.
Pricing Analysis
Volume placements concentrate in retrofit mechanical replacements while margins concentrate in new-installation AMI-ready infrastructure. Three-tier pricing structure across premium custody-transfer, standard AMI-enabled, and economy mechanical levels tracks certification grade and after-sales service bundling. Price erosion runs through residential retrofit tiers as regional water authorities consolidate procurement volumes. Industrial users in Arizona and Texas show lowest price sensitivity due to process water accountability requirements.
Supply Chain Analysis
Workforce availability constraints in Midwestern manufacturing geographies tether production capacity to technical training pipeline outputs. Component sourcing draws from Taiwan for cellular modem chipsets, Mexico for brass valve castings, and domestic foundries for electromagnetic flow tubes. Single-source vulnerability concentrates in LTE-M module fabrication. Distribution runs through municipal procurement offices and regional water authority consolidated contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where AMI-legacy billing system integration complexity forces weaker players toward acquisition or exit.
For Market Incumbents: To counter middleware development delays that strain municipal IT departments, invest in pre-certified CIS integration partnerships and expand captive production of pressure-sensing modules to reduce East Asian chip dependency. For New Entrants and Emerging Players: Regional water authority procurement offices represent the most penetrable channel partner type for bypassing entrenched distributor relationships in the Intermountain West. Target small-system consolidation momentum with cellular LTE-M solutions that eliminate proprietary radio infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified industrial conglomerates seeking water metering divisions. Five-to-ten year viability favors vendors with ultrasonic custody-transfer certification and established California utility relationships. Watch FCC spectrum allocation rulings as inflection indicator for rural cooperative addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AMI-CIS Middleware Development | Pre-certified integration modules accelerate municipal deployment timelines and reduce implementation risk. |
| Ultrasonic Custody-Transfer Certification | Semiconductor fabrication facilities in Arizona and Texas require ±0.5% accuracy for tariff precision. |
| Regional Water Authority Partnership | Consolidated procurement contracts in Colorado and Utah reduce customer acquisition cost per unit. |
| Cellular LTE-M Module Production | Domestic manufacturing of cellular endpoints bypasses East Asian foundry lead time constraints. |
| Pressure-Sensing Integration | EPA lead-and-copper rule revisions compel utilities to document service line materials at access points. |
Research Methodology
Multi-period observation of municipal procurement cycles, AMI deployment timelines, and EPA compliance deadlines anchored the trend analysis, supplemented by interviews with utility planning officers, water district procurement managers, AMI integration specialists, and cellular module sourcing directors. Secondary validation drew from EPA enforcement guidance documents, FCC spectrum allocation rulings, state public utility commission conservation mandates, and AWWA meter accuracy standards. Bottom-up unit deployment estimates triangulated against top-down infrastructure budget allocations.
Input-output matrices mapped product type, end user category, technology architecture, and installation methodology against municipal budget flows and industrial facility capex patterns across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles and regulatory compliance deadlines. Forecast inputs incorporated drought severity indices, tiered rate structure adoption curves, and cellular network coverage expansion.
Caveats apply where semiconductor foundry capacity constraints, EPA rule implementation delays, or municipal IT staffing shortages could materially shift the outlook. Forecasts reflect assumptions about regional water authority consolidation momentum and FCC unlicensed spectrum modifications. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Electric Meter Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Power Quality Meter Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Watt Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
Gas Meters Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market