
 Single-Phase Anti-Theft Meter Market | 2026-2036
Single-Phase Anti-Theft Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Phase Anti-Theft Meter Market Insights
IEC 62052-11 certification is rotating the competitive field by disqualifying manufacturers lacking accredited tamper-detection validation. Landis+Gyr leverages its European testing infrastructure to sustain multi-market approvals. Wasion Group anchors its position through captive production of metrology-grade ASICs. Holley Technology Ltd. specializes in prepaid-integrated anti-theft designs for utility tenders across Africa and Southeast Asia.
A single-phase anti-theft meter is an electromechanical or solid-state revenue-grade device engineered to detect and log unauthorized bypassing, magnetic tampering, or cover-opening events through embedded sensors and secure communication modules, primarily deployed to reduce non-technical distribution losses in low-voltage networks. Smart meters now capture the fastest-expanding margin pool as utilities bundle remote disconnect and real-time anomaly detection into procurement specifications. Prepaid meters retain structural importance in markets where revenue collection risk exceeds hardware cost sensitivity. RFID and IoT technology segments are displacing legacy pulse-output architectures as AMI backhaul requirements harden in tender documents.
India's CEA mandates BIS certification for all grid-connected meters, while Brazil's ANEEL technical specifications require anti-tamper event logging with remote readability. The EU F-Gas Regulation indirectly shapes meter enclosure material choices as utilities phase out sealed housings with high global-warming-potential blowing agents. Stakeholders must monitor how distributed energy resource interconnection standards rewrite meter communication protocol requirements before committing to chipset roadmaps.
Market Dynamics
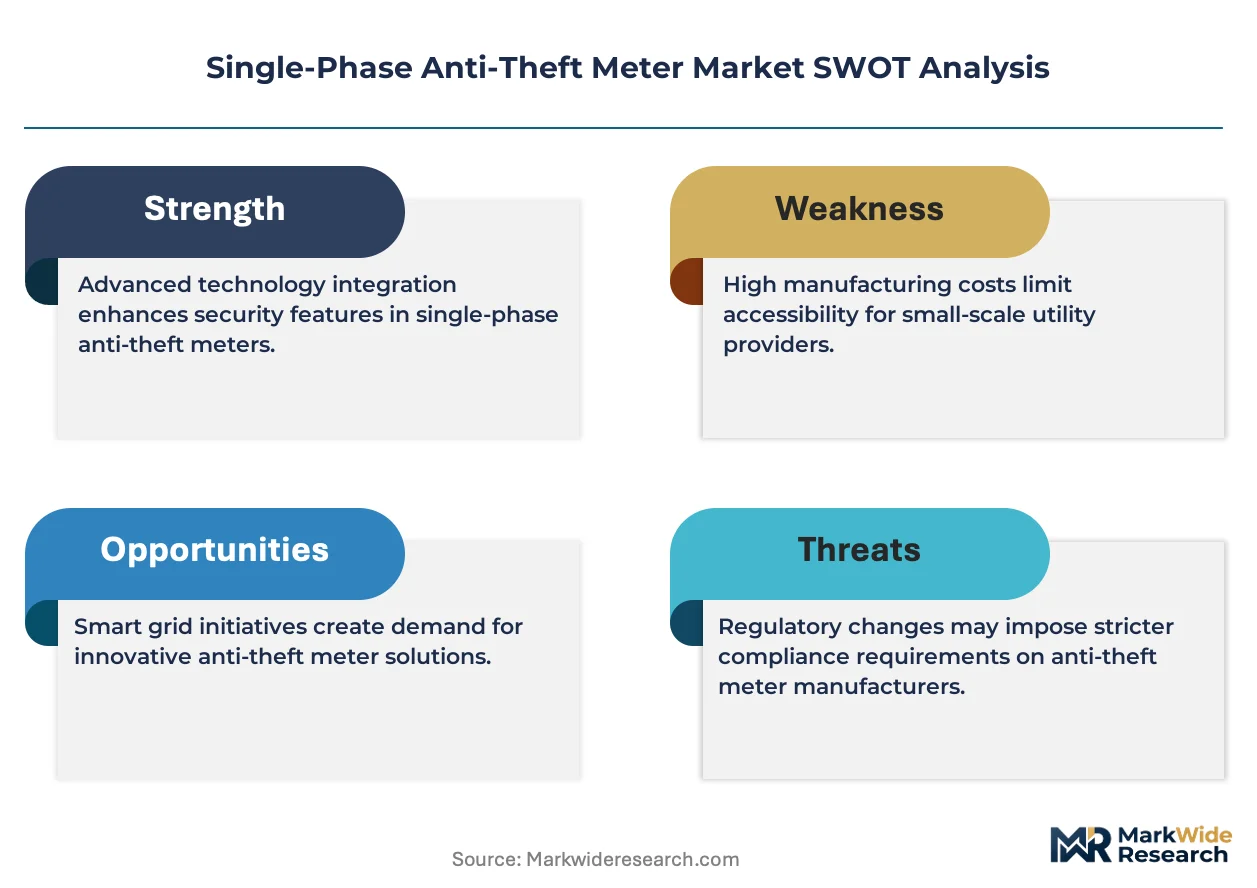
Grid modernization mandates across emerging economies are compressing tender cycles while hardening technical specifications for tamper-detection capabilities. Utilities now bundle remote disconnect and real-time anomaly detection into baseline procurement requirements, forcing meter architectures toward integrated smart functionality.
Growth Catalysts
- Smart meter mandates:Brazil's ANEEL technical specifications require anti-tamper event logging with remote readability, compelling utilities to replace legacy pulse-output devices.
- Distribution loss reduction targets:Utility operators in Sub-Saharan Africa face pressure from development finance institutions to cut non-technical losses below 15 percent.
- RFID integration:Automated meter reading infrastructure is displacing manual billing systems in South Asian urban clusters, creating pull for embedded secure communication modules.
Market Restraints
- ASIC supply concentration:Metrology-grade chipset fabrication concentrates among Taiwanese foundries, exposing meter manufacturers to capacity allocation volatility.
- Certification timeline friction:India's CEA mandates BIS certification for all grid-connected meters, adding six to nine months to product qualification cycles.
- Copper price volatility:Current transformer cores and terminal blocks constitute significant bill-of-materials exposure for electromechanical meter variants.
Strategic Opportunities
- Prepaid convergence:Revenue collection risk in Nigerian and Kenyan utilities is accelerating demand for integrated prepaid-anti-theft designs.
- EU F-Gas Regulation tailwind:Phasedown of high-global-warming-potential blowing agents is creating replacement demand for meter enclosures using alternative sealing technologies.
- AMI backhaul requirements:IoT protocol standardization is opening white space for communication module vendors to capture value previously held by meter OEMs.
Industry Challenges
- IEC 62052-11 compliance complexity:Accredited tamper-detection validation requires investment in European testing infrastructure that mid-tier manufacturers lack.
- Legacy system integration:Utilities with heterogeneous meter parks face protocol fragmentation when deploying unified head-end systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Phase Anti-Theft Meter Market |
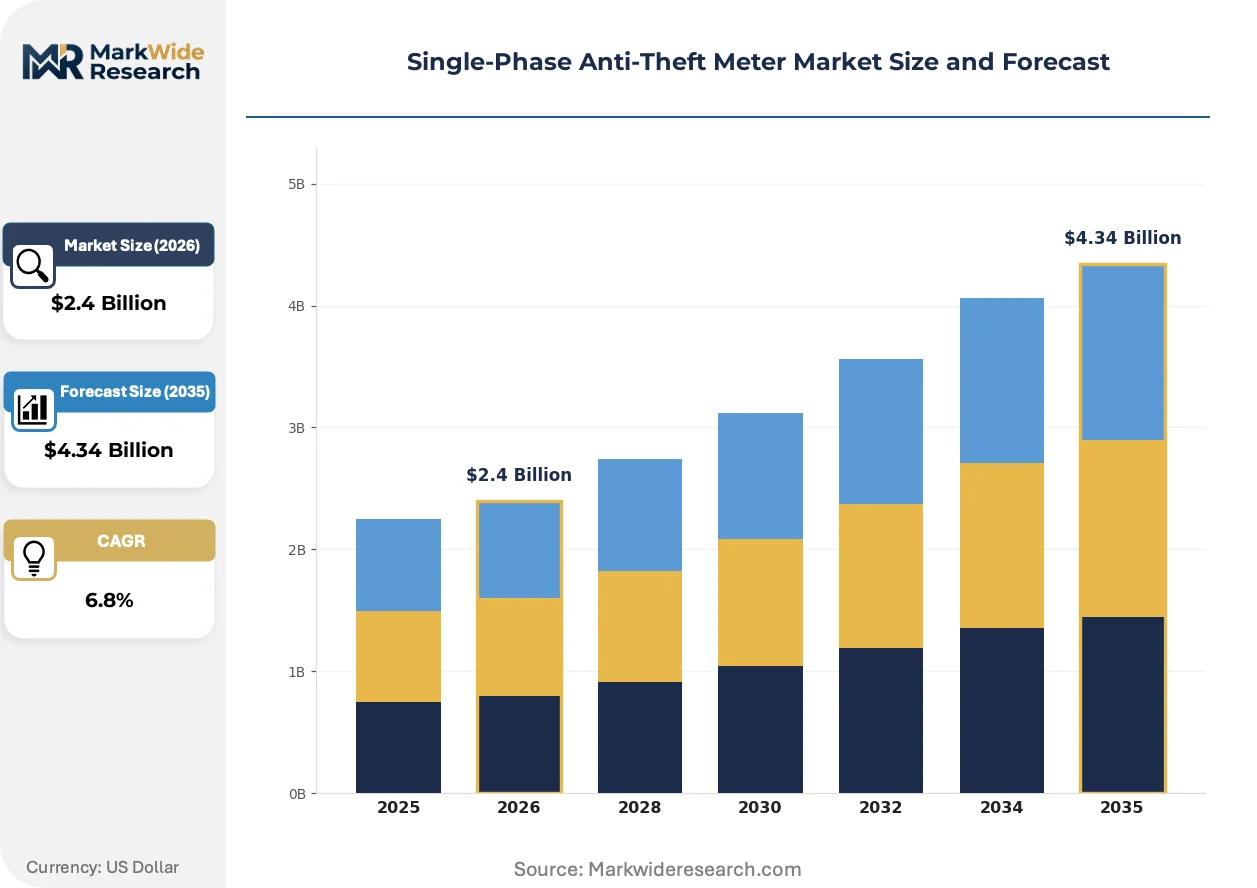
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Meters, Analog Meters, Smart Meters, Prepaid Meters End User: Residential, Commercial, Industrial, Utility Companies Technology: RFID, IoT, Remote Monitoring, Wireless Installation: Indoor, Outdoor, Wall-Mounted, Pole-Mounted |
| Companies Covered | Landis+Gyr, Itron Inc., ABB Ltd., Schneider Electric, General Electric, Wasion Group, Holley Technology Ltd., YTL, Londian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Phase Anti-Theft Meter Market Trends and Innovations
Product specifications are hardening around embedded intelligence and secure communication as utilities shift from revenue protection to revenue assurance paradigms. The competitive margin is migrating toward firmware and data analytics capabilities rather than hardware alone.
Metrology-grade ASICs with integrated tamper-detection logic are miniaturizing to single-chip implementations that combine measurement, security, and communication functions. Tier-one utilities in India and Brazil are specifying these consolidated architectures for new tenders. Component consolidation is compressing PCB real estate requirements and reducing per-unit bill-of-materials for solid-state meter designs.
The EU F-Gas Regulation is forcing enclosure manufacturers to reformulate polyurethane foam sealing systems using low-global-warming-potential alternatives. Meter OEMs sourcing housings from European suppliers must validate new material thermal cycling performance. Asian contract manufacturers are responding by accelerating adoption of thermoplastic elastomer gasket designs that bypass blowing agent constraints entirely.
Utility procurement departments are unbundling after-sales service contracts from hardware supply agreements, creating separate competitive arenas for meter asset management. African state-owned utilities are pioneering this split-tender approach to improve vendor accountability for field failure rates. Service contracts now specify mean-time-to-repair thresholds that favor vendors with localized technical support infrastructure over pure hardware exporters.
Single-Phase Anti-Theft Meter Market Segmentation
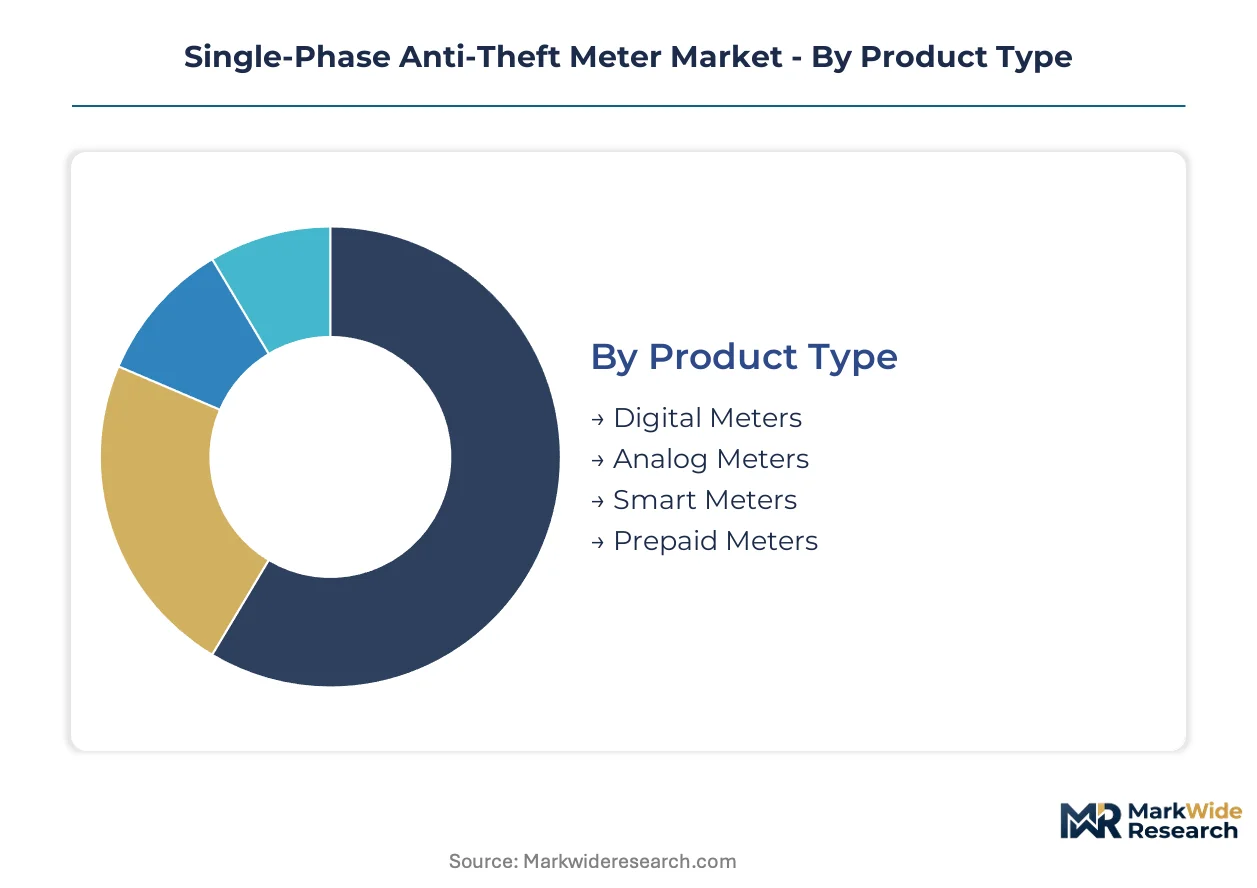
Segmentation in the single-phase anti-theft meter market reveals how procurement specifications diverge across utility types and infrastructure contexts. Product architecture, communication protocol, and mounting environment each create distinct competitive arenas with different margin profiles and certification requirements.
Product Type:
Smart meters face the most intense substitution pressure as prepaid-integrated designs and AMI-ready specifications displace legacy pulse-output architectures in emerging economy tenders.
- Digital Meters:Solid-state measurement cores with LCD displays and embedded tamper-detection logic replace electromechanical registers in grid modernization programs. Demand clusters in Indian state electricity boards and Brazilian distributors where ANEEL mandates remote readability.
- Analog Meters:Electromechanical induction-type devices with mechanical registers persist in cost-sensitive rural electrification schemes. Procurement concentrates in Sub-Saharan African utilities where development finance institutions prioritize unit economics over smart functionality.
- Smart Meters:Integrated architectures combining metrology, secure communication, and remote disconnect capabilities. Specifications harden around IEC 62052-11 tamper-detection validation.
- Prepaid Meters:Revenue-protection designs with token-based or STS-compliant credit management. Nigerian and Kenyan utilities drive specification convergence between prepaid and anti-theft functionality.
Analog meters retain volume leadership in absolute unit terms; smart meters hold the steepest expansion curve as AMI backhaul requirements harden.
End User:
Cost tier stratification separates premium-specification utility tenders from price-optimized residential deployments.
- Residential:Single-point metering for low-voltage consumer connections. Indian DISCOMs and Brazilian cooperatives specify compact DIN-rail designs for multi-dwelling installations.
- Commercial:Higher-current rated devices with enhanced tamper-detection sensitivity for small business premises. Demand concentrates in urban South Asian clusters with high revenue-collection risk.
- Industrial:Ruggedized enclosures and extended temperature specifications for workshop environments. Sub-Saharan African manufacturing zones drive procurement.
- Utility Companies:Bulk procurement with unified head-end integration requirements. State-owned African utilities pioneer split-tender approaches separating hardware from asset management services.
Utility companies dominate procurement volume; residential installations are climbing the fastest as rural electrification accelerates.
Technology:
Supply concentration in communication module fabrication is forcing meter OEMs to unbundle hardware from connectivity specifications.
- RFID:Short-range contactless reading for automated meter reading infrastructure. South Asian urban utilities deploy RFID-enabled handheld units to displace manual billing.
- IoT:Cellular or unlicensed-spectrum connectivity for real-time anomaly detection and remote firmware updates. Brazilian ANEEL specifications mandate IoT-ready communication modules.
- Remote Monitoring:Head-end system integration with event logging and alarm generation. Indian CEA mandates remote readability for all grid-connected meters.
- Wireless:Mesh or star-topology radio networks for AMI backhaul. African utilities with heterogeneous meter parks face protocol fragmentation challenges.
RFID retains installed-base dominance; IoT is gaining share fastest as cellular module costs decline and tender specifications harden.
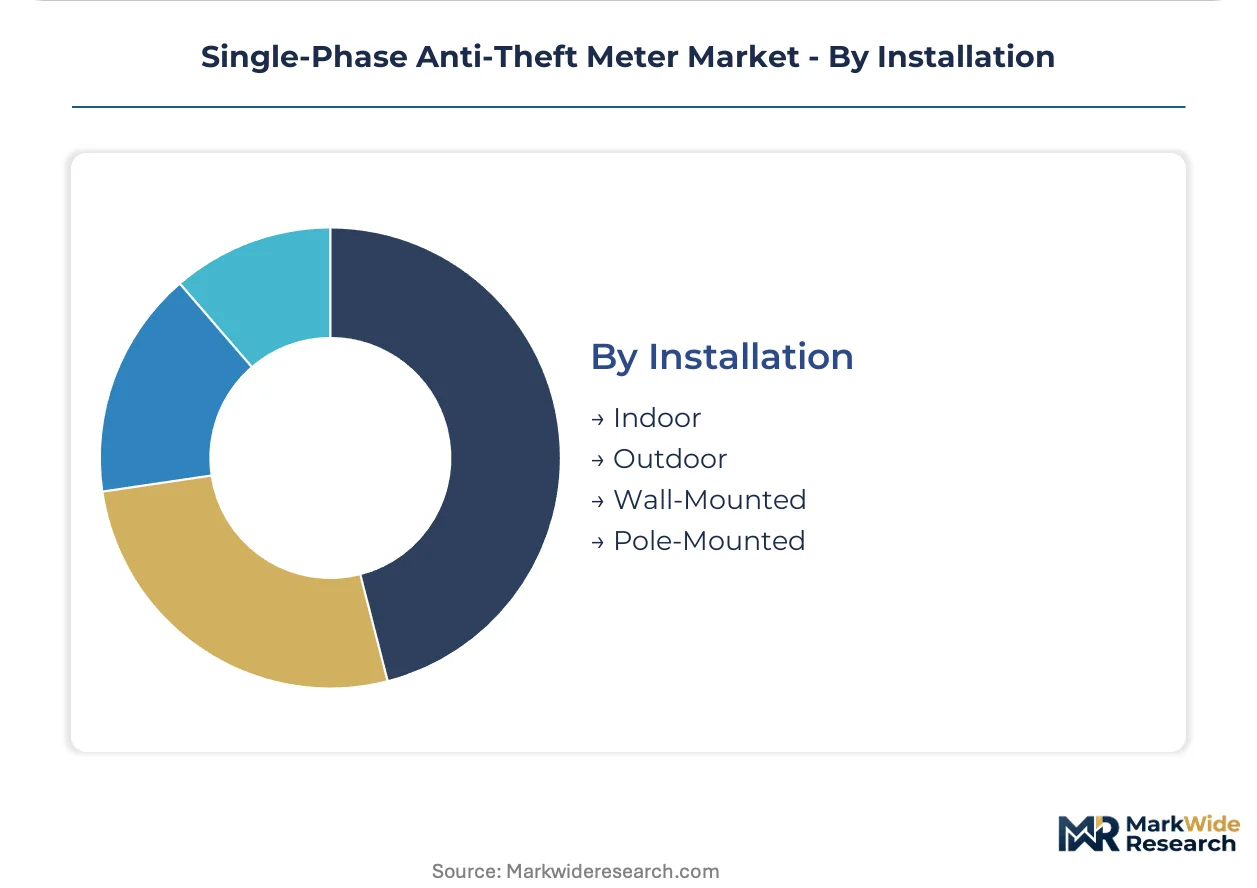
Installation:
Environmental exposure requirements differentiate enclosure sealing technologies and material choices under EU F-Gas Regulation constraints.
- Indoor:IP-rated enclosures for utility rooms and consumer premises. Indian residential specifications favor compact DIN-rail mounting.
- Outdoor:Weather-resistant housings with UV-stabilized polymers and gasketed sealing. Brazilian distribution networks require IP54 minimum for pole-mounted deployments.
- Wall-Mounted:Surface-installation designs with tamper-evident sealing. African prepaid meter programs specify wall-mounted units with integrated customer interfaces.
- Pole-Mounted:Elevated installation for distribution transformer secondaries and rural feeders. Sub-Saharan African utilities prioritize pole-mounted designs for theft deterrence.
Wall-mounted installations lead in unit volume; outdoor specifications are expanding most quickly as utilities harden infrastructure against environmental and tamper threats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart meter mandates and grid loss reduction targets are steering procurement volumes across emerging economies. Brazil's ANEEL specifications and India's CEA directives exemplify how technical hardening reshapes tender requirements. Utility modernization programs in Sub-Saharan Africa and South Asia concentrate demand in specific metropolitan distribution clusters.
Brazil
ANEEL technical specifications mandate anti-tamper event logging with remote readability for all new meter deployments. State distributors in São Paulo and Rio de Janeiro accelerate replacement of legacy pulse-output devices. The Southeast region's metropolitan utilities specify integrated prepaid-anti-theft designs for favela electrification programs.
India
CEA mandates BIS certification for all grid-connected meters, extending qualification cycles by six to nine months. State electricity boards in Maharashtra and Gujarat specify compact DIN-rail designs for multi-dwelling installations. The Delhi-NCR cluster drives demand for IoT-ready communication modules as AMI backhaul requirements harden.
Nigeria
Revenue collection risk in state-owned utilities accelerates procurement of prepaid-integrated anti-theft meters. The national electricity regulator pushes distribution companies to cut non-technical losses below 15 percent. Lagos and Abuja distribution zones specify wall-mounted units with integrated customer interfaces for urban metering.
South Africa
Eskom's grid modernization program prioritizes pole-mounted designs for rural feeder theft deterrence. Development finance institutions condition lending on distribution loss reduction targets. The Gauteng industrial corridor specifies ruggedized enclosures with extended temperature specifications for manufacturing zone deployments.
Kenya
Kenya Power's prepaid metering expansion targets informal settlement electrification with tamper-detection integration. The national energy regulator mandates remote readability for all new consumer connections. Nairobi's urban distribution network deploys RFID-enabled handheld units to displace manual billing systems.
Single-Phase Anti-Theft Meter Market Competitive Landscape
Player mix skews toward integrated meter OEMs with captive metrology capabilities and regional specialists with tariff-optimized designs. Market structure concentrates among European and Asian manufacturers with accredited testing infrastructure. Three archetypes dominate: vertically integrated conglomerates with multi-market approvals, metrology-focused specialists with ASIC design capabilities, and regional contract manufacturers serving price-sensitive tenders. Competitive moves center on unbundling after-sales service contracts from hardware supply and accelerating certification timeline compression through captive testing facilities.
Among European-headquartered conglomerates, Landis+Gyr and ABB Ltd. occupy positions anchored by multi-jurisdiction approval portfolios. Wasion Group and Holley Technology Ltd. represent the Asia-based specialist tier with captive production of metrology-grade components. These four exemplify how certification infrastructure and component integration separate sustainable competitors from tender-dependent assemblers.
| Leading Market Players |
|---|
| Landis+Gyr |
| Itron Inc. |
| ABB Ltd. |
| Schneider Electric |
| General Electric |
| Wasion Group |
| Holley Technology Ltd. |
| YTL |
| Londian |
| Others |
Pricing and Supply Chain Analysis
Six-to-nine-month certification timelines for BIS validation compress inventory turns and concentrate pricing power among manufacturers with captive European testing infrastructure. Meter OEMs lacking accredited IEC 62052-11 validation face margin compression as utilities harden technical specifications around tamper-detection capabilities.
Pricing Analysis
Certification grade creates the primary spread between accredited European test-house-validated meters and unverified Asian contract assemblies. Three-tier pricing structure separates premium IEC-validated smart meters from standard digital registers and economy analog induction devices. Price erosion runs through the analog tier as development finance institutions prioritize unit economics over smart functionality in Sub-Saharan African tenders. Utility companies exhibit lowest price sensitivity given bundled after-sales service requirements, while rural electrification schemes in Kenya and Nigeria drive acute cost optimization.
Supply Chain Analysis
Strategic stockpiling of metrology-grade ASICs dominates inventory strategy as Taiwanese foundry capacity allocation volatility exposes meter manufacturers to six-month order-to-delivery cycles. Component fabrication concentrates in Taiwan, China, and South Korea, with enclosure molding and final assembly distributed across India, Brazil, and Vietnam. Copper price volatility in current transformer cores and terminal blocks feeds from commodity exchange fluctuations. Single-source vulnerability in Taiwanese foundry capacity threatens production continuity. Distribution runs through utility tender procurement departments with unbundled service contracts creating separate competitive arenas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated prepaid-anti-theft designs threaten standalone anti-theft meter incumbents as Nigerian and Kenyan utilities converge functionality requirements. Manufacturers must navigate this substitution pressure while defending certification-derived margin premiums.
For Market Incumbents: Secure multi-jurisdiction approval portfolios through captive European testing infrastructure investment. Landis+Gyr's sustained market position demonstrates how IEC 62052-11 validation creates defensive moats against unaccredited competitors. Backward integration into metrology-grade ASIC design, as practiced by Wasion Group, anchors cost control against Taiwanese foundry pricing power.
For New Entrants and Emerging Players: Anchor in African prepaid-integrated tender specifications where revenue collection risk exceeds hardware cost sensitivity. Nigerian distribution companies and Kenya Power's informal settlement electrification programs present penetrable entry points. Target split-tender procurement structures separating hardware from asset management services to bypass incumbent service infrastructure advantages.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because IEC 62052-11 validation scarcity concentrates sustainable returns among European and Asian manufacturers with accredited testing infrastructure. Acquisition targets should display captive ASIC design capabilities or established multi-market approval portfolios. Monitor Brazilian ANEEL specification tightening as inflection indicator for smart meter substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62052-11 Certification Investment | Accredited European validation creates tender eligibility for Brazilian ANEEL and Indian CEA mandates. |
| Metrology-Grade ASIC Integration | Single-chip consolidation of measurement, security, and communication functions compresses PCB real estate requirements. |
| Prepaid-Anti-Theft Convergence | Revenue-protection integration addresses Nigerian and Kenyan utility revenue collection risk specifications. |
| After-Sales Service Unbundling | Separate competitive arenas for meter asset management improve vendor accountability for field failure rates. |
| EU F-Gas Compliant Enclosure Sourcing | Low-global-warming-potential sealing technologies satisfy utility procurement departments phasing legacy polyurethane foam. |
Research Methodology
A spread of perspectives from utility procurement officers, meter OEM product managers, metrology ASIC design engineers, and distribution network planners converged on the working assumptions underlying this analysis. Primary field engagement with state electricity boards in Maharashtra and Gujarat, alongside Brazilian distributors in São Paulo, grounded demand-side validation. Secondary sources encompassed ANEEL technical specifications, CEA BIS certification directives, IEC standard documentation, and utility tender databases. Bottom-up unit economics triangulated against top-down grid modernization program budgets.
Segmentation dimensions modeled span product architecture (smart, prepaid, digital, analog), communication protocol (IoT, RFID, wireless, remote monitoring), end-user category (residential, commercial, industrial, utility), and installation environment (indoor, outdoor, wall-mounted, pole-mounted). CAGRs were derived from utility procurement pipeline analysis and distribution loss reduction target trajectories across the projection horizon. Forecast inputs incorporated metrology-grade chipset cost curves and cellular module price decline rates.
Decision-makers should treat outputs as directional under assumptions of sustained grid modernization funding and stable copper pricing; material deviation in Taiwanese foundry capacity allocation or development finance institution lending conditions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Global Digital Power Meter Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Smart Gas Meter Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Europe Water Meter Market
Smart Meters
Power Monitoring System Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Water Meter Market
Smart Meters
Smart Water Metering Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Smart Meter Battery Market
Smart Meters
United States Smart Meter Market