
 Electricity Meters (Smart Meters) Market | 2026-2036
Electricity Meters (Smart Meters) Market Size, Share, and Industry Trends Forecast 2026-2036
Electricity Meters (Smart Meters) Market Foresight
Municipal authorities and renewable energy operators are reorganizing procurement priorities toward advanced metering infrastructure. Landis+Gyr Group AG leverages its European manufacturing footprint to serve utility-scale deployments. Kamstrup A/S dominates ultrasonic and smart heat metering adjacencies that extend into electricity applications. Siemens AG competes through integrated grid automation portfolios that bundle metering with switchgear and SCADA systems.
Electricity meters (smart meters) are digital measurement devices that record energy consumption at intervals of one hour or less and communicate data to utilities via embedded RF, cellular, or power-line communication modules. These instruments enable real-time load monitoring, remote disconnect capability, and time-differentiated billing to balance grid demand. Single-phase and three-phase product types occupy distinct positions, with three-phase meters capturing higher margins in commercial and industrial settings where power quality monitoring adds value. Cellular GSM and Wi-SUN communication technologies are gaining traction over legacy power-line carrier systems as utilities prioritize network reliability and last-mile coverage in dense urban deployments.
The Federal Energy Regulatory Commission in the United States and the European Union's CE marking and MDR frameworks shape product certification and data interoperability standards across jurisdictions. China's State Administration for Market Regulation enforces GB standards that govern metering accuracy and electromagnetic compatibility for domestic suppliers. Stakeholders must monitor evolving cybersecurity mandates and interoperability protocols as grid-edge digitization intensifies.
Market Dynamics
AMI deployment cycles are compressing as utilities face simultaneous pressure from grid-edge digitization mandates and cybersecurity hardening requirements, forcing vendor consolidation around integrated platform providers.
Growth Catalysts
- EU Clean Energy Package:Binding replacement deadlines for legacy meters across member states are accelerating procurement timelines for advanced metering infrastructure.
- Cellular GSM modules:Utilities in dense urban environments are prioritizing last-mile reliability over power-line carrier systems for mission-critical data transmission.
- Industrial power quality monitoring:Three-phase meter demand from manufacturing facilities is expanding as energy-intensive operations adopt time-differentiated billing structures.
Market Restraints
- Semiconductor component volatility:RF transceiver and power management IC shortages have extended lead times for communication module suppliers.
- GDPR-aligned data governance:Stringent personal data processing requirements in European deployments add compliance overhead and liability exposure for utilities.
- Technical limitation in rural coverage:Cellular dead zones and power-line noise in remote territories force hybrid infrastructure investments that dilute AMI economies of scale.
Strategic Opportunities
- Heat-to-electricity metering convergence:Ultrasonic heat meter specialists are extending platforms into electricity applications, creating cross-utility cross-selling potential.
- China's GB standard harmonization:Domestic electromagnetic compatibility certification alignment is opening procurement pathways for international component suppliers.
- SCADA integration bundles:Grid automation vendors are unbundling metering from switchgear packages, creating standalone AMI procurement channels for mid-size utilities.
Industry Challenges
- Cybersecurity certification timelines:FERC and EU Agency for Cybersecurity evaluation queues are delaying product launches by 8-14 months for new market entrants.
- Legacy system interoperability:Proprietary head-end systems from incumbent vendors create switching costs that fragment procurement decisions across utility departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electricity Meters (Smart Meters) Market |
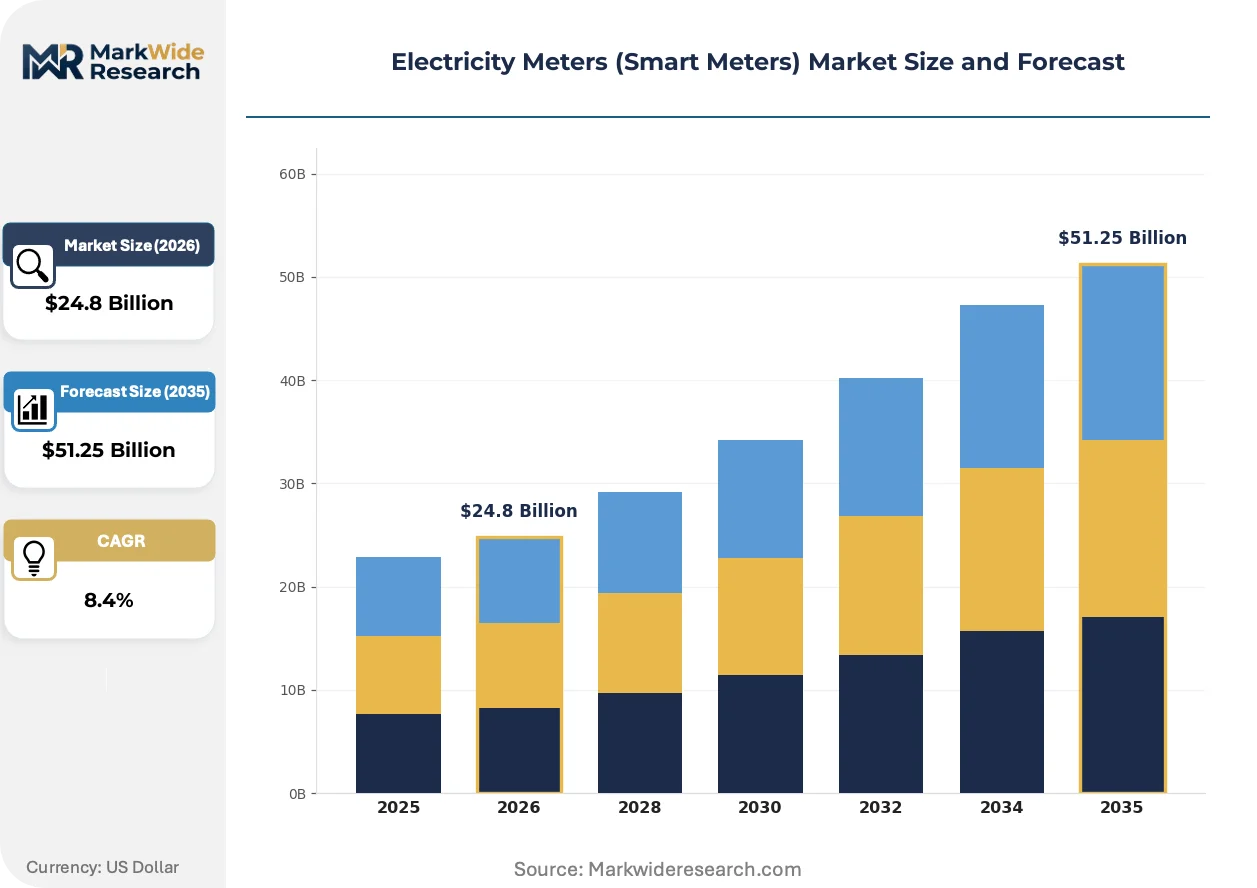
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-phase, Three-phase, Prepaid, Postpaid, Residential Grade, Commercial Grade Communication Technology: RF Mesh, Power Line Carrier, Cellular GSM, ZigBee, Wi-SUN, LoRaWAN Application: Energy Management, Demand Response, Load Monitoring, Grid Automation, Theft Detection, Time-of-Use Billing End User: Utility Providers, Energy Service Companies, Municipal Authorities, Industrial Facilities, Renewable Energy Operators |
| Companies Covered | Landis+Gyr Group AG, Itron Inc., Sensus USA Inc., Honeywell International Inc., Kamstrup A/S, Schneider Electric, Siemens AG, Sagemcom, Hexing Electrical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electricity Meters (Smart Meters) Market Shifts & Advancements
Wi-SUN mesh networking is gaining ground against cellular alternatives as utilities prioritize self-healing infrastructure and reduced recurring carrier fees. The competitive landscape is reorganizing around communication protocol choices rather than meter hardware differentiation.
Wi-SUN FAN 1.1 is fragmenting vendor ecosystems previously dominated by proprietary RF stacks. Municipal utilities in Germany and the United States are piloting neighborhood-area networks that bypass cellular dependencies entirely. This protocol shift is fragmenting procurement decisions, forcing meter manufacturers to support multiple radio configurations or cede share to specialized communication module suppliers.
CE marking under the EU's MDR framework is tightening electromagnetic immunity testing requirements for grid-edge devices. Manufacturers must now demonstrate resilience against intentional electromagnetic interference scenarios. Industrial three-phase meter categories face the steepest retesting burdens, with some suppliers withdrawing lower-volume SKUs rather than absorbing certification costs.
Buyer concentration among national utility champions is compressing vendor margins through framework agreements that lock in pricing for 5-7 year horizons. Aggregated procurement platforms in France and Spain are displacing bilateral negotiations for residential meter rollouts. This purchasing consolidation is most visible in Western European markets where state-owned incumbents control distribution infrastructure.
Electricity Meters (Smart Meters) Market Segmentation
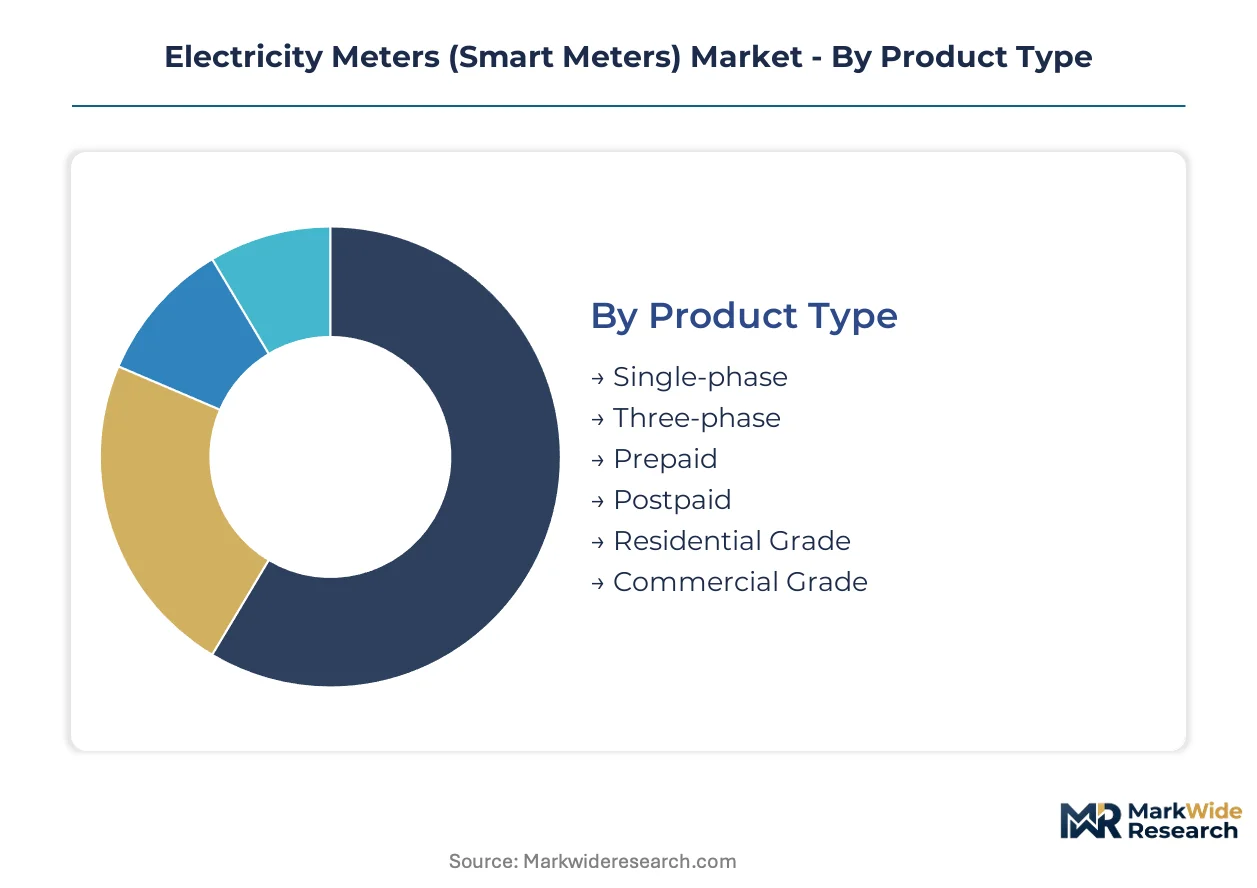
Smart meter procurement channels diverge sharply by segment, with utility-scale tenders favoring three-phase and cellular-equipped units while municipal rollouts prioritize single-phase RF mesh configurations. Understanding these channel dynamics exposes where margin pools concentrate and which technology bets carry replacement-cycle exposure.
Product Type:
Channel mix splits between utility-direct procurement for commercial-grade three-phase meters and aggregated municipal frameworks for residential single-phase units, with prepaid configurations gaining traction in emerging market deployments.
- Single-phase:These meters measure consumption in residential and small commercial installations with one live conductor. Demand concentrates in German municipal housing associations and Spanish aggregated procurement platforms where framework agreements compress vendor margins.
- Three-phase:Designed for industrial and large commercial sites with three live conductors, these units incorporate power quality monitoring capabilities. Manufacturing facilities in China's Jiangsu province and Germany's Ruhr industrial cluster drive procurement as time-differentiated billing structures expand.
- Prepaid:Coin and smart-card operated meters requiring advance payment, prevalent in utility-managed social housing programs.
- Postpaid:Traditional billing-cycle meters dominating established Western European and North American utility infrastructures.
- Residential Grade:Standardized units for household deployment, subject to CE marking and electromagnetic immunity testing under EU MDR frameworks.
- Commercial Grade:Higher-specification meters with enhanced accuracy classes and remote disconnect capability for business premises.
Single-phase meters dominate installed base. Three-phase configurations are where expansion concentrates.
Communication Technology:
Cost tiering separates premium cellular GSM modules from economy power-line carrier systems, with mid-tier RF mesh and Wi-SUN options capturing municipal utility preference for reduced recurring carrier fees.
- RF Mesh:Self-healing neighborhood-area networks using proprietary or standardized radio stacks. German Stadtwerke and US municipal utilities in California deploy these to bypass cellular dependencies.
- Power Line Carrier:Data transmission over existing electrical wiring, cost-effective but vulnerable to noise interference in rural territories with aging distribution infrastructure.
- Cellular GSM:Embedded mobile modules providing last-mile reliability in dense urban environments. Chinese State Grid deployments in Shanghai and Shenzhen prioritize these for mission-critical transmission despite recurring carrier costs.
- ZigBee:Short-range wireless protocol for home-area network integration with smart appliances and distributed energy resources.
- Wi-SUN:Open-standard mesh networking gaining ground against cellular alternatives as Wi-SUN FAN 1.1 fragments previously proprietary vendor ecosystems.
- LoRaWAN:Low-power wide-area protocol for rural coverage extension where cellular dead zones force hybrid infrastructure investments.
Power-line carrier retains legacy installed base. Cellular and Wi-SUN configurations are climbing the fastest as utilities prioritize network reliability.
Application:
Application maturity varies by grid modernization phase, with energy management and time-of-use billing representing established deployments while theft detection and advanced demand response functions require regulatory tariff reform to unlock scale.
- Energy Management:Real-time consumption visibility enabling consumer behavioral adjustment. China's dual carbon goals accelerate deployment in Beijing and Guangdong province commercial districts.
- Demand Response:Automated load curtailment during peak periods. German industrial clusters participate in ancillary service markets through aggregated meter-controlled flexibility.
- Load Monitoring:Distribution operator visibility into transformer-level consumption patterns for network planning.
- Grid Automation:Integration with SCADA and distribution management systems, bundling metering with switchgear in Siemens-led integrated portfolios.
- Theft Detection:Anomaly algorithms identifying tampering or bypass events, critical in markets with high non-technical loss rates.
- Time-of-Use Billing:Dynamic tariff structures balancing grid demand, expanding in US states with FERC-aligned retail market reforms.
Energy management dominates functional deployment. Demand response is gaining share fastest where ancillary service markets mature.
End User:
Customer type determines procurement scale and technical specification, with national utility champions driving volume through multi-year framework agreements while industrial facilities and renewable operators generate higher-margin specialized demand.
- Utility Providers:State-owned and investor-owned distribution operators conducting mass residential rollouts. EDF in France and Enel in Italy consolidate purchasing through aggregated platforms.
- Energy Service Companies:Third-party aggregators financing and operating meter assets under performance contracting arrangements.
- Municipal Authorities:City-owned utilities with localized procurement autonomy, prevalent in German Stadtwerke structures.
- Industrial Facilities:Energy-intensive manufacturing sites requiring three-phase power quality monitoring. Chemical and steel operations in Germany's North Rhine-Westphalia specify premium accuracy classes.
- Renewable Energy Operators:Solar and wind asset managers needing generation-side metering for grid compliance and settlement.
Utility providers dominate installed base. Industrial facilities and renewable operators are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility champions and municipal aggregators concentrate procurement across five national markets where grid modernization mandates and regulatory deadlines compress replacement cycles. State-owned incumbents and Stadtwerke structures dominate volume, while industrial clusters generate premium three-phase demand.
United States
FERC-aligned retail market reforms accelerate time-of-use billing deployments across investor-owned utilities. State-level renewable portfolio standards in California and Texas drive AMI integration with distributed solar assets. Municipal utilities in California pilot Wi-SUN mesh networks to bypass cellular dependencies entirely.
Germany
Stadtwerke structures consolidate residential single-phase procurement through framework agreements spanning five-to-seven-year horizons. The EU Clean Energy Package binds member states to legacy meter replacement deadlines by 2027. North Rhine-Westphalia's chemical and steel operations specify premium three-phase accuracy classes for power quality monitoring.
China
State Grid Corporation prioritizes cellular GSM modules in Shanghai and Shenzhen for mission-critical transmission reliability. SAMR-enforced GB standards govern electromagnetic compatibility certification for domestic suppliers. Jiangsu province manufacturing facilities expand three-phase deployments under time-differentiated billing structures.
France
EDF's aggregated procurement platforms displace bilateral negotiations for residential meter rollouts at national scale. CE marking under the EU MDR framework tightens electromagnetic immunity testing requirements for grid-edge devices. Île-de-France commercial districts accelerate energy management deployments aligned with building efficiency mandates.
Italy
Enel consolidates purchasing through centralized platforms similar to French utility structures. GDPR-aligned data governance adds compliance overhead for European-wide deployments. Lombardy industrial zones drive three-phase meter demand as manufacturing operations adopt demand response participation in ancillary service markets.
Electricity Meters (Smart Meters) Market Competitive Landscape
Player mix skews toward integrated grid automation providers and specialized communication module suppliers rather than pure-play meter manufacturers. Market structure exhibits moderate consolidation around European and Asian industrial conglomerates with captive distribution networks. Two strategic archetypes dominate: full-stack automation vendors bundling metering with switchgear and SCADA, and RF communication specialists extending into mesh networking protocols. Competitive moves concentrate on protocol standardization alliances and certification pre-emption in cybersecurity evaluation queues.
Among European-based industrial conglomerates, Landis+Gyr Group AG and Siemens AG occupy positions representing the integrated automation archetype, while Kamstrup A/S exemplifies specialists extending ultrasonic metering platforms into adjacent electricity applications. These three entities anchor the competitive landscape through manufacturing footprint scale and regulatory certification depth rather than hardware differentiation alone. Their positioning reflects the broader industry shift toward communication protocol choices as the primary procurement decision variable.
| Leading Market Players |
|---|
| Landis+Gyr Group AG |
| Itron Inc. |
| Sensus USA Inc. |
| Honeywell International Inc. |
| Kamstrup A/S |
| Schneider Electric |
| Siemens AG |
| Sagemcom |
| Hexing Electrical |
| Others |
Supply & Pricing Matrix
CE marking under the EU MDR framework gates both supplier qualification and price differentiation simultaneously, as electromagnetic immunity testing requirements force tiered certification investments that stratify vendor access to European utility procurement channels. This regulatory barrier compresses margins for uncertified entrants while enabling premium positioning for manufacturers with pre-existing GB standard alignment in China or FERC cybersecurity clearance in the United States.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate utility-scale tenders, where RF transceiver and power management IC volatility passes through to final meter pricing. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked industrial three-phase units from residential single-phase configurations and unbranded emerging market alternatives. Pricing pressure stems from aggregated procurement platforms in France and Spain that lock in five-to-seven-year framework pricing. Municipal utilities exhibit highest price sensitivity, while industrial facilities in Germany's chemical clusters prioritize accuracy class over unit cost.
Supply Chain Analysis
China and Germany anchor smart meter final assembly, with RF module production concentrated in Taiwan and South Korea. The supply chain draws from silicon wafers, RF transceivers, and power management ICs as critical inputs. Single-source vulnerability in cellular modem chipsets creates procurement risk for utilities prioritizing GSM configurations. Distribution runs through national utility champions and municipal Stadtwerke structures, with direct OEM relationships displacing traditional distribution intermediaries in Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electricity meters market represents high-growth disruption as Wi-SUN FAN 1.1 protocol standardization fragments previously proprietary vendor ecosystems and forces wholesale communication technology transitions across utility procurement cycles.
For Market Incumbents: Fortify certification depth in cybersecurity evaluation queues as FERC and EU Agency for Cybersecurity timelines delay new entrant product launches by eight to fourteen months. Expand in-house production of RF communication modules to reduce exposure to semiconductor component volatility. Prioritize backward integration into power management IC sourcing through captive foundry relationships or strategic supply agreements with Taiwanese semiconductor houses.
For New Entrants and Emerging Players: SCADA integration gaps in mid-size municipal utilities present white-space opportunity, as Siemens-led bundled offerings leave standalone AMI procurement underserved. Target German Stadtwerke structures with Wi-SUN mesh configurations that bypass cellular dependencies and reduce recurring carrier fees. Pursue heat-to-electricity metering convergence as ultrasonic specialists extend platforms, leveraging cross-utility cross-selling potential absent from pure-play electricity vendors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across communication module suppliers as protocol standardization commoditizes hardware differentiation. Long-term viability across the analysis window favors vertically integrated grid automation providers with captive certification capabilities over pure-play meter manufacturers. Monitor Wi-SUN FAN 1.1 adoption velocity in German and California municipal pilots as inflection indicator for protocol shift timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Standardization Alliance | Wi-SUN FAN 1.1 adoption fragments proprietary RF ecosystems and reshapes vendor competitive positioning. |
| Cybersecurity Certification Pre-emption | Early FERC and EU Agency for Cybersecurity clearance creates eight-to-fourteen-month launch advantage. |
| Heat-to-Electricity Platform Extension | Kamstrup's ultrasonic expertise enables cross-utility cross-selling beyond traditional electricity-only vendors. |
| Aggregated Procurement Platform Participation | EDF and Enel centralized purchasing locks in volume but compresses margins through five-to-seven-year pricing. |
| Cellular Module Backward Integration | In-house RF transceiver production mitigates semiconductor shortage exposure and stabilizes lead times. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility planning officers, AMI procurement managers, grid operators, and RF communication module suppliers; and secondary validation through FERC filings, EIA deployment databases, EU Clean Energy Package regulatory texts, and State Grid Corporation tender announcements. Bottom-up triangulation across meter shipment volumes by communication technology and top-down reconciliation against national grid modernization program budgets anchored value estimates.
Across the projection horizon, the analytical framework modeled segmentation by product type, communication technology, application function, and end-user archetype. CAGRs derived from replacement cycle compression analysis under EU Clean Energy Package deadlines and China's dual carbon goals. Forecast inputs incorporated utility capital expenditure plans, semiconductor lead time trajectories, and protocol migration curves from power-line carrier to cellular and Wi-SUN configurations.
Underlying assumptions cover regulatory deadline adherence, semiconductor supply normalization, and cybersecurity certification queue stability, with deviation risk concentrated in GDPR enforcement intensity and Wi-SUN ecosystem fragmentation velocity. Recalibration cycles align with material shifts in EU member state transposition timelines and State Grid procurement schedule revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Meter Data Management Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Smart Water Metering Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Gas Meters Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Digital Water Meters Market
Smart Meters
Power Metering Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
North America Gas Meter Market