
 AMI Smart Water Meter Market | 2026-2036
AMI Smart Water Meter Market Size, Share, and Industry Trends Forecast 2026-2036
AMI Smart Water Meter Market Insights
Municipal water utilities is realigning the customer base as cities replace manual read systems with automated infrastructure. Itron leverages its RF mesh expertise to anchor large-scale deployments across North American utilities. Badger Meter competes through cellular-optimized endpoints that sustain recurring data revenue streams.
An AMI smart water meter is a networked measurement device that transmits consumption data through cellular, RF, or mesh protocols to central utility systems, typically operating at pressure ratings up to 150 psi and flow ranges of 0.25 to 20 gallons per minute for residential units. Its core purpose is to eliminate manual meter reading, enable real-time leak detection, and support dynamic pricing models for water conservation. Digital meters are capturing margin pools from mechanical predecessors as utilities prioritize remote disconnect and flow analytics capabilities. Cellular connectivity leads in greenfield deployments where RF infrastructure is absent, while RF dominates retrofit scenarios with existing network density.
EPA drinking water regulations, AWWA metering standards, and state-level water conservation mandates collectively shape product specifications and procurement criteria for AMI deployments. The EPA's lead and copper rule revisions force accelerated replacement timelines, directly expanding addressable meter volume. Stakeholders must monitor FCC spectrum allocations for RF-based systems and evolving state-level data privacy requirements governing utility customer consumption patterns.
Market Dynamics
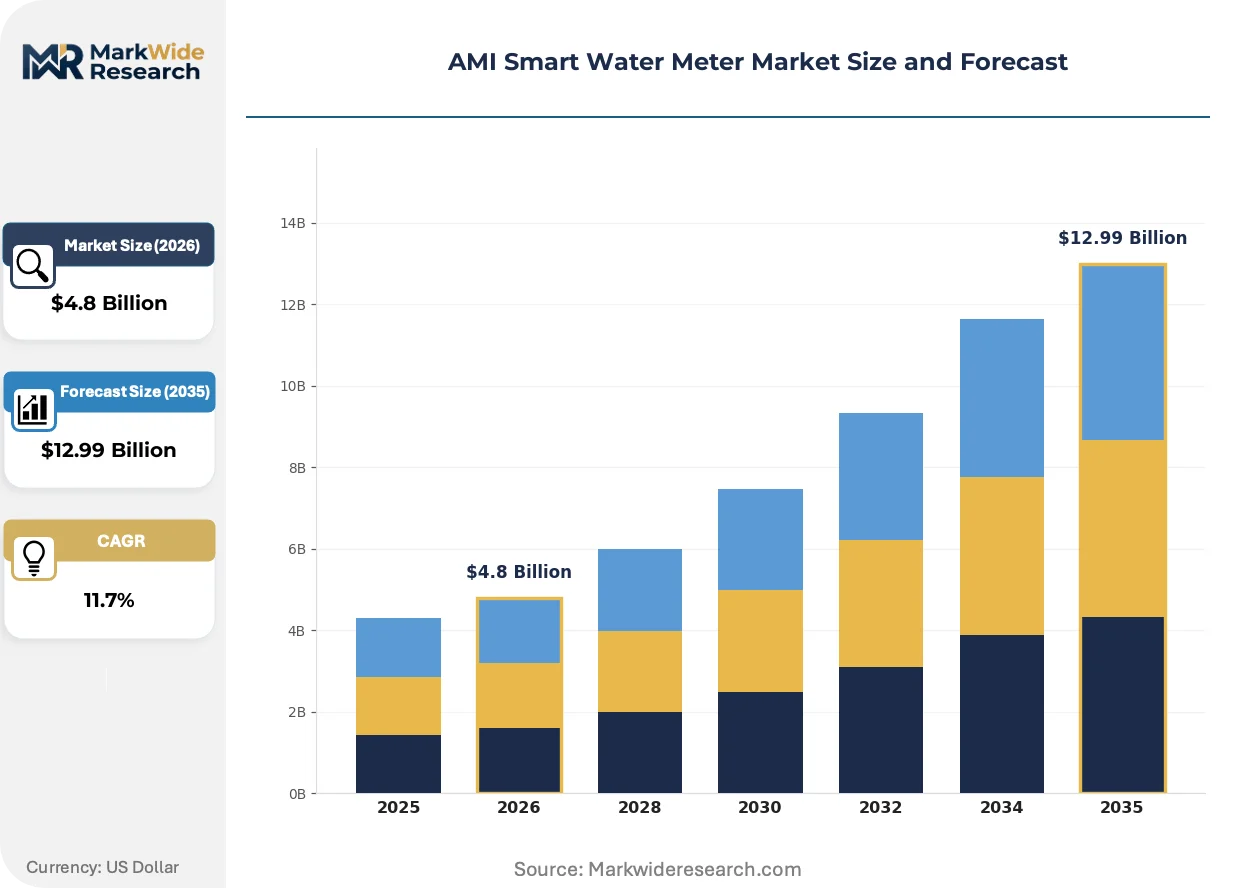
AMI smart water meter deployment momentum hinges on municipal capital cycles converging with federal infrastructure mandates. EPA lead and copper rule revisions compress replacement timelines while utilities face simultaneous pressure to reduce non-revenue water losses below 10% thresholds.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:Accelerated replacement mandates in the United States expand addressable meter volume for utilities serving aging lead service lines.
- Cellular LPWAN Protocols:NB-IoT and LTE-M deployments eliminate RF infrastructure buildout costs in greenfield municipal systems.
- Drought-Intensified Conservation Mandates:California, Texas, and Florida utilities face binding water-use reduction targets that demand granular consumption data.
Market Restraints
- Semiconductor Supply Concentration:RF transceiver and cellular module fabrication concentrates in East Asian foundries, exposing AMI manufacturers to allocation volatility.
- Copper and Polymer Input Costs:Meter body materials face commodity price swings that compress hardware margins on fixed municipal contracts.
- Legacy AMR System Stranding:Drive-by radio read infrastructure represents sunk capital that slows full AMI conversion economics.
Strategic Opportunities
- Underserved Small and Medium Utilities:Municipal systems serving 10,000 to 50,000 connections lack capital planning expertise for AMI procurement.
- Cloud-Native Meter Data Management:SaaS analytics platforms displace on-premise MDM installations and capture recurring revenue streams.
- Bipartisan Infrastructure Law Funding:Federal water infrastructure grants reduce utility borrowing costs for meter replacement programs.
Industry Challenges
- Cybersecurity Certification Complexity:State-level data privacy frameworks governing consumption patterns create overlapping compliance obligations for utilities.
- Integration with SCADA and Billing Systems:AMI head-end platforms require custom middleware development to synchronize with legacy utility IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AMI Smart Water Meter Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Meters, Portable Meters, Mechanical Meters, Digital Meters Installation Type: Indoor, Outdoor, Underground, Above Ground Connectivity: Cellular, RF, Wi-Fi, Zigbee End User: Municipalities, Industries, Commercial Building, Residential |
| Companies Covered | Itron, Badger Meter, Sensus (Xylem), Kamstrup, Diehl Stiftung, Neptune Technology Group, Landis+Gyr, Aclara Technologies, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AMI Smart Water Meter Market Trends and Innovations
AMI smart water meter technology is converging around unified data platforms that collapse operational silos between distribution network monitoring and customer engagement systems. Vendors are racing to embed edge computing capabilities that enable localized leak detection without cloud dependency.
Edge AI inference engines embedded directly in meter endpoints are unifying pressure transient detection with consumption anomaly classification. California utilities are piloting these capabilities to pinpoint distribution main breaks within 15 minutes. The technology is compressing response times that previously required centralized SCADA polling cycles.
EPA's lead service line inventory mandates are forcing utilities to document material composition of every connection point. This regulatory pressure accelerates meter replacement programs in Midwestern and Northeastern states where lead service lines concentrate. Manufacturers are responding with integrated sampling ports that streamline compliance testing workflows.
Buying patterns among municipal procurement officers are tilting toward performance-based specifications rather than hardware-centric RFPs. Texas and Florida utilities now require guaranteed accuracy drift rates and minimum battery life warranties as contractual terms. Channel relationships are shifting from distributor-led to direct manufacturer engagement for systems integration support.
AMI Smart Water Meter Market Segmentation
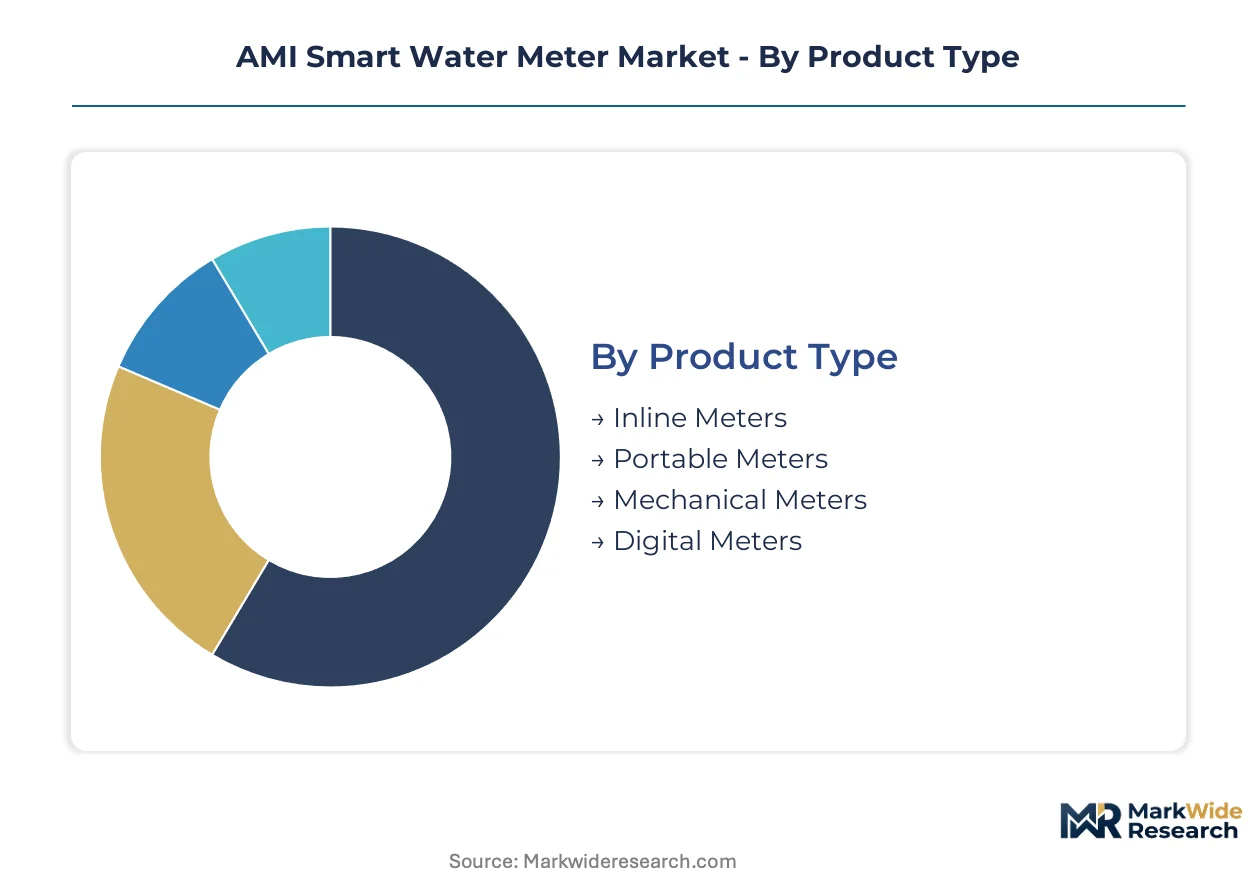
AMI smart water meter segmentation reveals distinct procurement patterns across product architecture, deployment environment, communication protocol, and customer scale. Understanding these divides clarifies where cellular connectivity commands premium pricing versus where RF mesh retains cost advantages.
Product Type:
Volume concentrates in inline and digital configurations, while portable and mechanical units serve specialized or transitional niches.
- Inline Meters:Fixed-position units with integrated flow sensors and pressure transducers rated for continuous municipal distribution networks. Demand clusters in California and Texas utilities replacing aging mechanical infrastructure under drought mandates and EPA lead service line requirements.
- Digital Meters:Solid-state ultrasonic or electromagnetic measurement devices with embedded edge computing for leak detection and flow analytics. North American utilities prioritize these for remote disconnect capabilities and real-time consumption visibility in conservation pricing programs.
- Portable Meters:Temporary clamp-on or insertion units for construction sites, seasonal irrigation, and emergency bypass applications.
- Mechanical Meters:Legacy positive displacement or turbine designs with AMI retrofit modules attached; transitional category declining as full digital replacement accelerates.
Mature deployment sits with mechanical meters in legacy AMR conversions. Newer deployment is concentrated in digital meters with native AMI architecture.
Installation Type:
Cost tier separates indoor residential endpoints from hardened outdoor and underground configurations requiring environmental sealing.
- Outdoor:NEMA-rated enclosures with IP68 sealing against freeze-thaw cycles and UV exposure; standard for single-family residential curb stops and commercial service connections across sunbelt states.
- Underground:Submersible pit-set meters with corrosion-resistant polymer bodies and remote antenna extensions; dominates frost-prone Midwestern and Northeastern utilities where above-ground vaults risk winter damage.
- Indoor:Basement or utility room installations in multi-family buildings and legacy housing stock; lowest hardware cost but highest truck-roll frequency for maintenance access.
- Above Ground:Wall-mounted or pedestal configurations for industrial campuses and agricultural irrigation points requiring frequent manual verification.
Above-ground installations dominate industrial retrofit scenarios. Underground deployment is expanding fastest in freeze-zone municipal contracts.
Connectivity:
Application context determines whether cellular LPWAN or RF mesh delivers superior total cost of ownership.
- Cellular:NB-IoT and LTE-M endpoints eliminating infrastructure buildout; greenfield utilities in rural Texas and Florida counties select these where RF tower density is insufficient.
- RF:Proprietary mesh networks leveraging existing utility-owned infrastructure; retrofit deployments in established North American systems with sunk RF capital.
- Wi-Fi:Consumer-grade connectivity for campus and building-level submetering in multi-tenant commercial properties.
- Zigbee:Low-power mesh for integrated home area network pilots linking consumption displays with utility portals.
RF connectivity anchors established utility territories. Cellular endpoints are climbing fastest in greenfield municipal procurements.
End User:
Customer type governs data granularity requirements and procurement decision complexity.
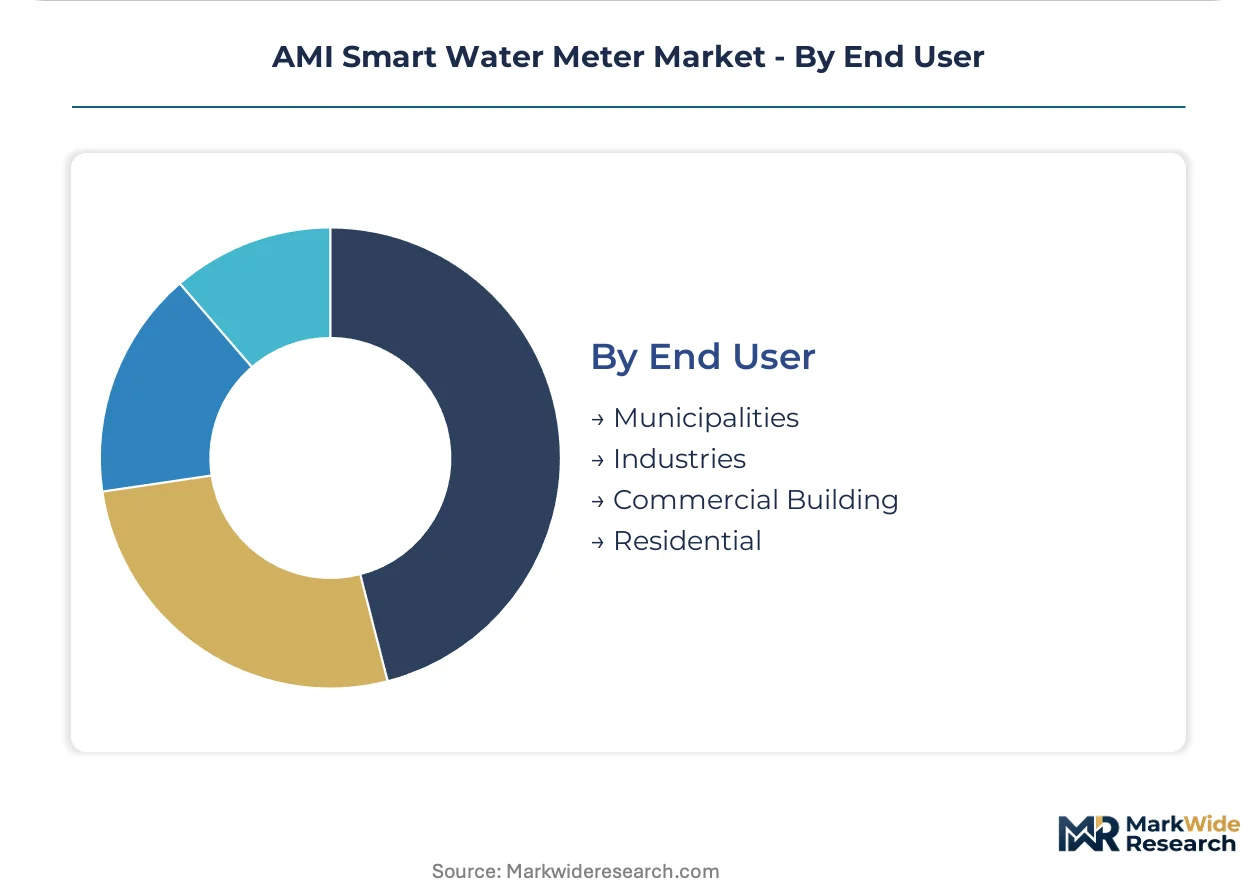
- Municipalities:City and county water departments serving 10,000 to 500,000 connections; largest addressable volume with longest sales cycles and strictest compliance documentation for EPA and state conservation mandates.
- Residential:Single-family and multi-family billing endpoints; highest unit volume with standardized specifications and strongest price sensitivity to per-meter hardware costs.
- Industries:Manufacturing, power generation, and extraction facilities requiring high-flow meters with SCADA integration and certified accuracy for trade measurement.
- Commercial Building:Office, retail, and hospitality properties with submetering for tenant billing and LEED water performance tracking.
Municipal procurement dominates established replacement cycles. Commercial building deployment is gaining share fastest in sustainability-driven urban cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Opportunity Zones and California enterprise districts concentrate AMI smart water meter deployment capital, channeling federal infrastructure grants toward drought-stressed municipal utilities.
United States
EPA lead and copper rule revisions compress replacement timelines across Midwestern and Northeastern utilities. California drought mandates drive granular consumption tracking requirements in Los Angeles and San Diego metro areas. Texas rural counties select cellular LPWAN endpoints where RF tower density remains insufficient.
Germany
REACH compliance pressures accelerate mechanical meter phase-out in industrial Rhine-Ruhr corridors. ECHA chemical safety standards govern polymer body specifications for submersible pit-set installations. Bavarian municipal utilities pilot edge-AI leak detection in Munich and Nuremberg distribution networks.
China
Dual carbon goals intensify smart city water efficiency mandates in Yangtze River Delta megacities. MIIT IoT standards harmonize NB-IoT endpoint specifications across provincial water bureaus. Shenzhen and Shanghai utilities deploy integrated sampling ports for lead service line inventory compliance.
Australia
Murray-Darling Basin conservation targets force real-time consumption visibility in New South Wales and Victorian irrigation districts. The country's national water regulator enforces non-revenue water thresholds below 10%. Sydney Water and Melbourne metropolitan utilities anchor cellular-optimized procurement volumes.
United Kingdom
Ofwat price review cycles align AMI capital planning with five-year asset management periods. Environment Agency drought permits trigger mandatory metering in Southeast England water-stressed zones. Thames Water and Anglian Water service territories concentrate RF mesh retrofit deployments.
AMI Smart Water Meter Market Competitive Landscape
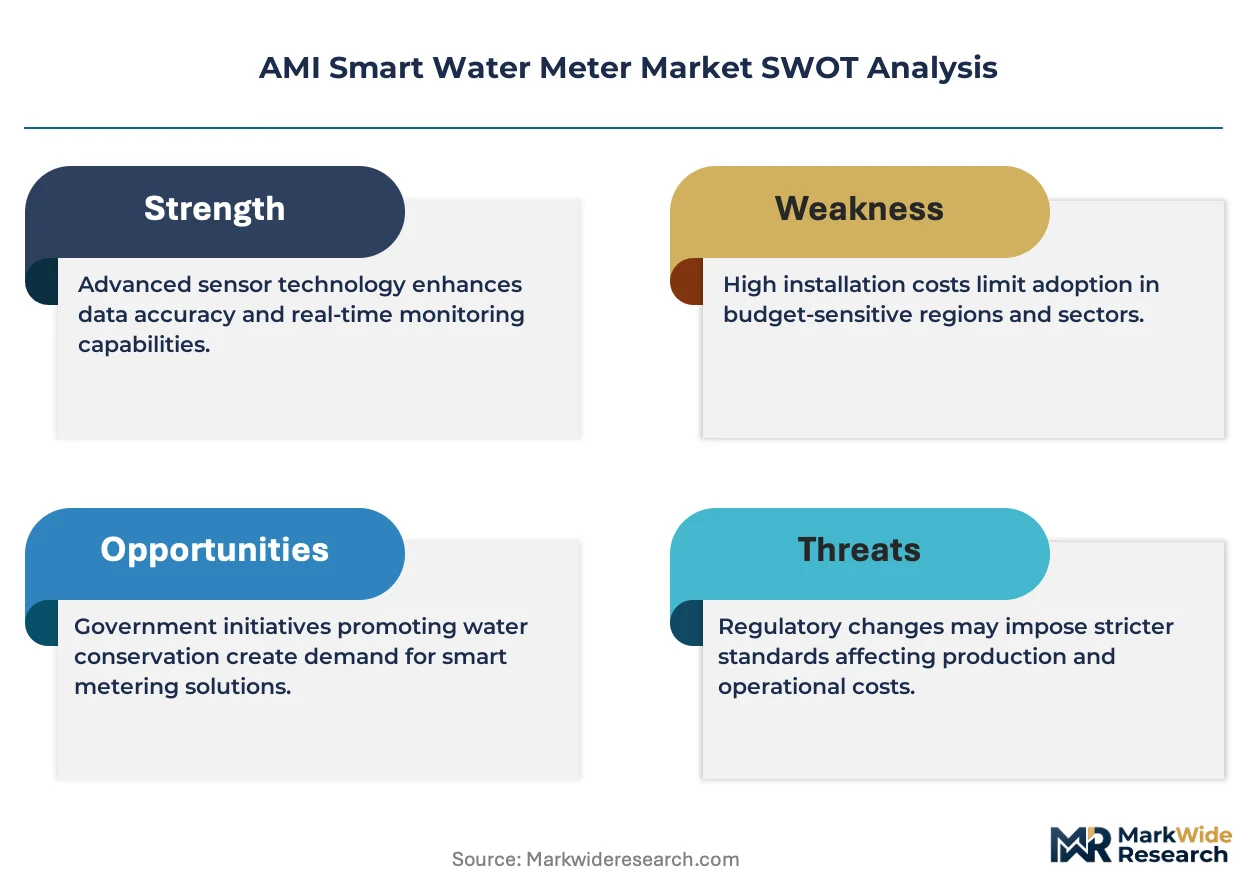
Top-tier vendors anchor large-scale municipal contracts, while mid-tier specialists compete on cellular-optimized endpoints and cloud-native data platforms. The market structure tilts toward consolidated procurement relationships given decade-long asset lifecycles and utility risk aversion. Three archetypes dominate: RF mesh heritage players, cellular-native challengers, and integrated sampling port specialists. Competitive moves center on strategic partnerships for SCADA integration and portfolio diversification into SaaS analytics.
Within the RF mesh heritage tier, Itron and Badger Meter exemplify established positioning. Itron occupies a position representing North American utility-owned infrastructure expertise. Badger Meter sits within the cellular-optimized endpoint archetype, anchoring recurring data revenue models. Sensus, operating as a Xylem subsidiary, represents the integrated water technology conglomerate structure.
| Leading Market Players |
|---|
| Itron |
| Badger Meter |
| Sensus (Xylem) |
| Kamstrup |
| Diehl Stiftung |
| Neptune Technology Group |
| Landis+Gyr |
| Aclara Technologies |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
Municipal procurement officers in drought-stressed states anchor pricing power through volume-scale contracts that compress hardware margins while elevating SaaS-tiered data platform subscriptions. This buyer concentration forces manufacturers to absorb commodity volatility in meter bodies while capturing recurring revenue through cellular connectivity and analytics software.
Pricing Analysis
Short lead-time premiums apply to cellular-optimized endpoints where semiconductor allocation constraints strain municipal replacement schedules. Three-tier pricing structure across premium, standard, and economy levels separates edge-AI enabled meters with integrated sampling ports from basic ultrasonic units and mechanical retrofit modules. Pricing pressure stems from fixed municipal contract terms that lock hardware costs amid copper and polymer input swings. Small utilities serving 10,000 to 50,000 connections exhibit highest price sensitivity, while metropolitan systems in California and Texas prioritize performance warranties over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements for RF transceivers and cellular modules mandate multi-supplier qualification across Taiwanese and South Korean foundries, reducing single-source vulnerability. Meter body fabrication draws from Chinese polymer molding and German precision machining for pressure-rated components. Supply chain risk centers on East Asian semiconductor allocation volatility exposed by municipal capital cycle timing. Distribution runs through authorized utility distributors shifting toward direct manufacturer engagement for systems integration support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AMI smart water meter technology sits in a transition phase where edge-AI inference engines displace centralized SCADA polling for leak detection and pressure transient classification.
For Market Incumbents: Extend RF mesh infrastructure expertise into cloud-native meter data management platforms that capture recurring SaaS revenue. Deepen backward integration into cellular module sourcing to offset East Asian foundry allocation risk. Prioritize certification investment for EPA lead service line inventory compliance to anchor Midwestern and Northeastern replacement cycles.
For New Entrants and Emerging Players: The price-point gap between premium edge-AI meters and economy mechanical retrofits opens white-space targeting of small and medium utilities lacking capital planning expertise. Cellular-native endpoints for greenfield rural deployments in Texas and Florida counties offer lowest competitive density. Pursue direct engagement with municipal procurement officers through performance-based RFP response rather than distributor channel dependence.
For Investors and Strategic Acquirers: The window for entry favors cloud-native SaaS analytics specialists with SCADA integration capabilities over hardware-centric meter manufacturers. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Monitor FCC spectrum allocation decisions for RF-based systems as inflection indicator for mesh versus cellular protocol dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Capability Integration | Embedded inference engines compress leak detection response times below 15 minutes for California utilities. |
| Cellular LPWAN Partnership | NB-IoT and LTE-M alliances eliminate RF infrastructure buildout costs in greenfield municipal systems. |
| Integrated Sampling Port Development | Streamlined EPA lead service line compliance testing accelerates Midwestern and Northeastern replacement programs. |
| Cloud-Native MDM Platform Launch | SaaS analytics displace on-premise installations and capture recurring revenue from 10,000 to 50,000 connection utilities. |
| Direct Municipal Engagement Model | Manufacturer-led systems integration support responds to Texas and Florida performance-based procurement specifications. |
Research Methodology
Multi-period observation of municipal capital expenditure cycles, EPA regulatory revision timelines, and cellular module allocation patterns anchored the trend analysis, supplemented by interviews with utility planning officers, AMI program managers, RF network engineers, and municipal procurement directors. Secondary validation drew from EPA drinking water regulation filings, FCC spectrum allocation records, AWWA metering standards documentation, and state-level water conservation mandate databases. Bottom-up unit deployment estimates triangulated against top-down infrastructure spending forecasts.
Input-output matrix modeling connected endpoint shipment volumes to connectivity protocol mix, installation type distribution, and customer scale segmentation across the projection horizon. The analytical framework incorporated product architecture, deployment environment, communication protocol, and end-user type dimensions. CAGRs were derived from regression analysis of historical replacement cycles against regulatory mandate acceleration and drought-intensified conservation targets. Forecast inputs included semiconductor foundry capacity utilization and municipal bond issuance rates for water infrastructure.
Inputs from EPA regulatory filings and municipal procurement databases were available through the study window; gaps in real-time utility capital commitment data introduce uncertainty bands around near-term deployment timing. Forecasts reflect documented assumptions regarding federal infrastructure grant disbursement velocity and state-level data privacy framework adoption. Deviation in FCC spectrum reallocation or East Asian semiconductor export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Utility Solutions Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
Europe Water Meter Market
Smart Meters
United States Smart Meter Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Watt Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Power Metering Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Power Quality Meter Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
Smart Water Metering Market
Smart Meters
North America Gas Meter Market