
 South and Central America Smart Metering Market | 2026-2036
South and Central America Smart Metering Market Size, Share, and Industry Trends Forecast 2026-2036
South and Central America Smart Metering Market Insights
Aftermarket service revenue is tilting from hardware replacement cycles toward data analytics and grid optimization contracts. Landis+Gyr Group AG leverages its regional service footprint to capture recurring software revenues across Brazilian utilities. Itron Inc. anchors its position through deep AMI integration with Latin American distribution network operators. Schneider Electric competes by specializing in cloud-based deployment architectures that reduce on-site infrastructure costs for mid-sized municipal utilities.
Smart metering encompasses digitally instrumented measurement devices that record utility consumption at intervals as brief as fifteen minutes, then transmit data through RF mesh, cellular, or power-line carrier networks to centralized management platforms. Electric meters dominate installed volume across South and Central America, though AMI technology is gaining fastest as utilities replace first-generation AMR systems with two-way communicative infrastructure. Water meters command premium pricing in drought-prone zones such as Chile's central valley, where leakage detection drives deployment urgency.
ANEEL in Brazil mandates technical standards for remote disconnect capability and data interoperability, while Argentina's ENRE enforces similar metering modernization timelines for Buenos Aires distribution concessions. These frameworks shape procurement specifications and lock out non-compliant vendors from concession renewals. Stakeholders must monitor how evolving cybersecurity certification requirements from regional energy regulators alter vendor qualification thresholds and deployment timelines.
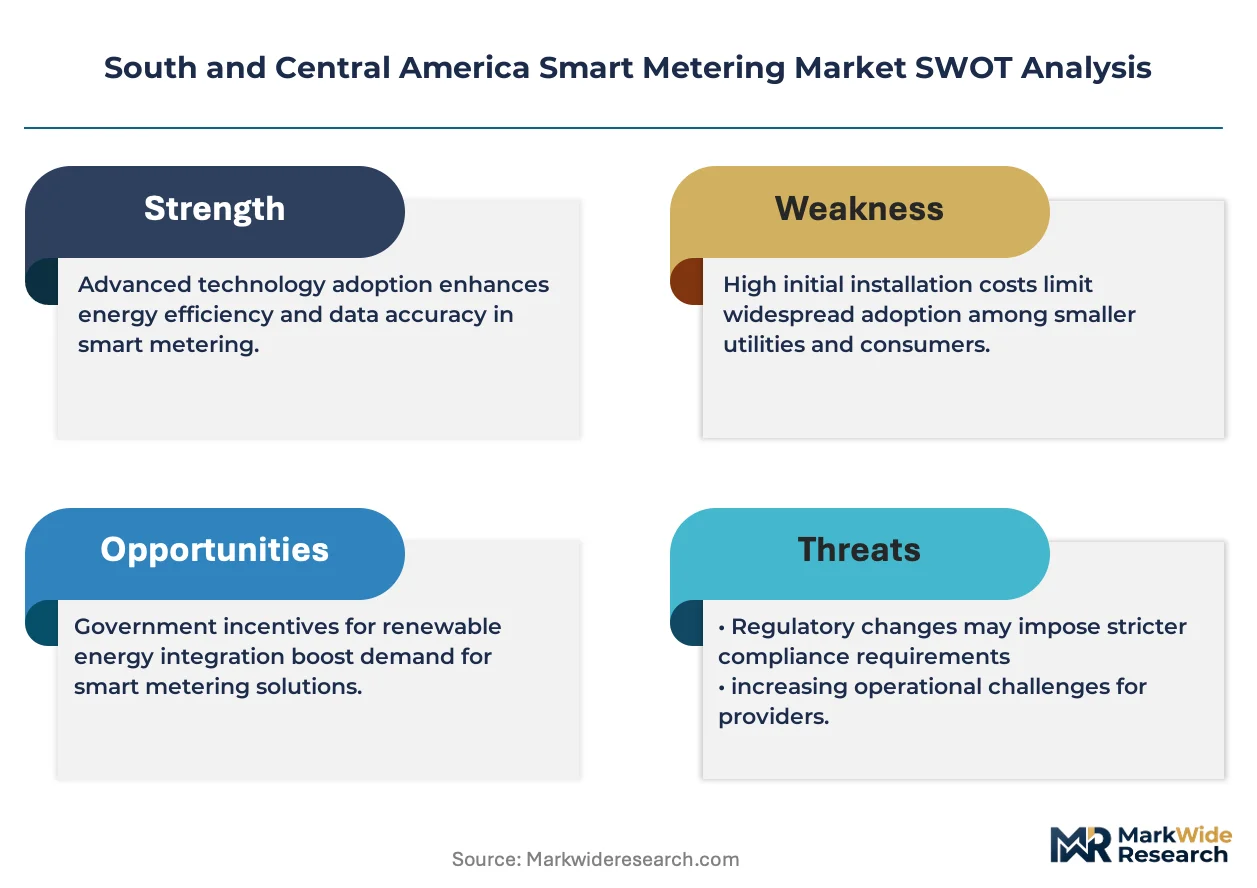
Market Dynamics
ANEEL's technical mandates for remote disconnect capability and data interoperability are compressing procurement cycles across Brazilian distribution concessions, forcing state-owned utilities toward accelerated AMI replacement schedules.
Growth Catalysts
- ANEEL Automated Billing Mandates:Brazil's national electricity regulator enforces automated meter reading infrastructure for all major distribution concessions, eliminating manual collection routes and reducing operational overhead for utilities serving São Paulo's metropolitan zones.
- RF Mesh Network Maturation:Proprietary radio-frequency mesh protocols now achieve 99.5% data transmission reliability in dense urban environments, enabling utilities to deploy AMI without cellular subscription dependencies that strain municipal budgets.
- Chilean Water Scarcity Pressures:Drought conditions in Chile's central valley drive premium pricing for acoustic leak-detection meters, accelerating replacement of mechanical water meters with pressure-sensing digital units in agricultural and municipal distribution networks.
Market Restraints
- Semiconductor Supply Concentration:AMI meter production depends on specialized communication chipsets sourced predominantly from East Asian foundries, exposing Brazilian and Argentine assembly plants to lead-time volatility and customs clearance delays.
- Cellular Subscription Cost Burden:Utilities in secondary Colombian and Peruvian cities face recurring operational expenditure pressures from 4G/LTE data plans required for cellular-communicative meters, constraining deployment scale outside capital regions.
- First-Generation AMR Stranded Assets:Existing one-way automatic meter reading infrastructure in Uruguay and Paraguay lacks firmware upgrade paths, forcing complete hardware replacement rather than modular AMI retrofits and extending payback periods.
Strategic Opportunities
- Argentina ENRE Modernization Timelines:Buenos Aires distribution concession renewals mandate full AMI coverage by 2028, creating immediate procurement windows for networked meter ecosystems with integrated prepayment functionality.
- Cloud-Native Deployment Architectures:Mid-sized municipal utilities across Brazil's Northeast region bypass on-premise server infrastructure through software-as-a-service meter data management platforms, reducing upfront capital requirements by eliminating physical data center construction.
- Hybrid RF-PLC Convergence:Manufacturers combining radio-frequency neighborhood area networks with power-line carrier backhaul penetrate rural Brazilian concessions where cellular coverage remains intermittent and satellite connectivity proves cost-prohibitive.
Industry Challenges
- Cybersecurity Certification Complexity:Evolving ANEEL and ENRE cybersecurity frameworks require third-party penetration testing and firmware signing protocols that extend vendor qualification timelines by 8-14 months for non-established suppliers.
- Integration with Prepayment Legacy:Brazilian utilities operating token-based electricity vending systems must engineer dual-protocol gateways to bridge magnetic stripe and STS-standard keypad meters with modern AMI headends, multiplying deployment engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South and Central America Smart Metering Market |
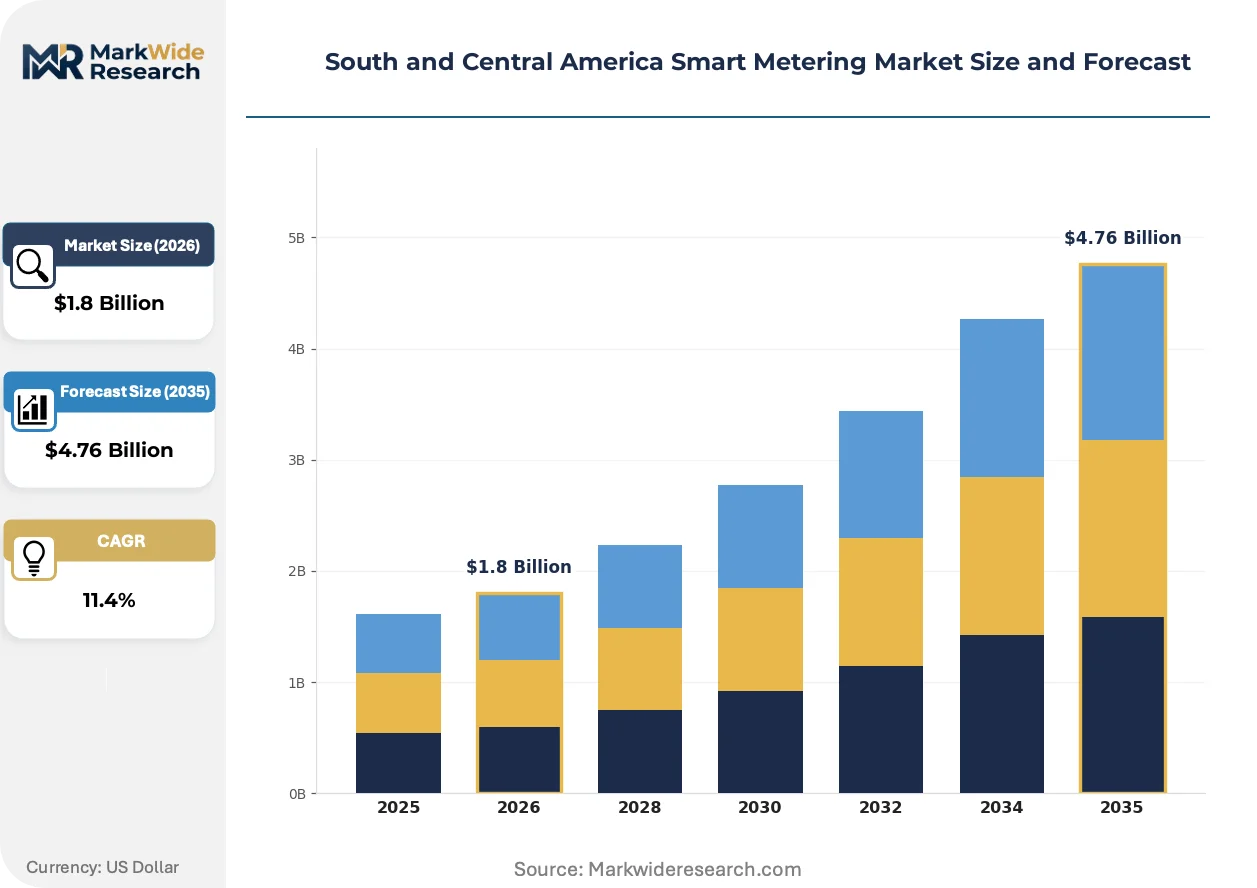
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
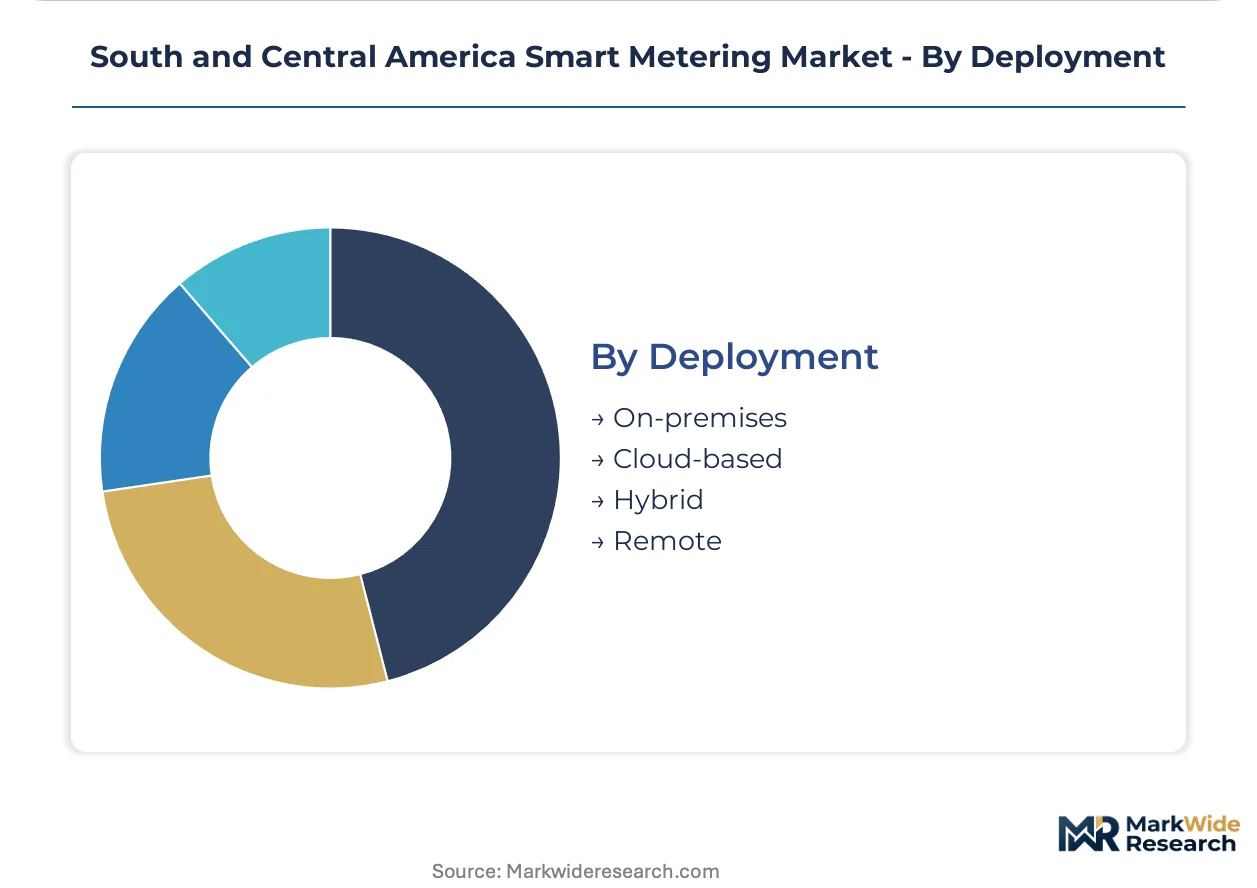
| Segmentation | Product Type: Electric Meters, Water Meters, Gas Meters, Heat Meters Technology: AMR, AMI, Networking, Communication Protocols End User: Utilities, Residential Consumers, Commercial Entities, Industrial Clients Deployment: On-premises, Cloud-based, Hybrid, Remote |
| Companies Covered | Landis+Gyr Group AG, Itron Inc., Honeywell International Inc., Kamstrup A/S, Sensus, Schneider Electric, Siemens, ABB, Enel Group, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South and Central America Smart Metering Market Trends and Innovations
Software-defined meter functionality and edge-computing architectures are compressing hardware refresh cycles while expanding data monetization possibilities for distribution network operators.
Edge intelligence firmware is virtualizing traditional meter hardware boundaries. AMI endpoints in São Paulo and Rio de Janeiro concessions now execute localized load-disconnect decisions and power-quality analytics without centralized cloud polling. CPFL and Enel deployment teams report 60% reduction in backhaul bandwidth consumption. This distributed processing architecture is virtualizing the historical distinction between smart meters and dedicated grid sensors, collapsing two hardware categories into single-unit deployments.
ANEEL Resolution 1,000 establishes mandatory cybersecurity certification for all networked metering equipment entering Brazilian distribution concessions. The framework requires firmware signing, secure boot protocols, and annual penetration testing reports submitted to national laboratories. Vendors without pre-established certification relationships face extended qualification timelines, advantaging incumbent suppliers with existing ANEEL-approved test histories and locking out newer market entrants from state-owned utility tenders.
Utility procurement teams are unbundling hardware supply from software service contracts. Brazilian distributors now separate AMI endpoint purchases from multi-year meter data management subscriptions, enabling competitive rebidding of analytics platforms without stranded meter assets. This contractual fragmentation appears most advanced in Minas Gerais and Paraná state concessions, where municipal regulators mandate transparent pricing decomposition to prevent vendor lock-in across concession renewal periods.
South and Central America Smart Metering Market Segmentation
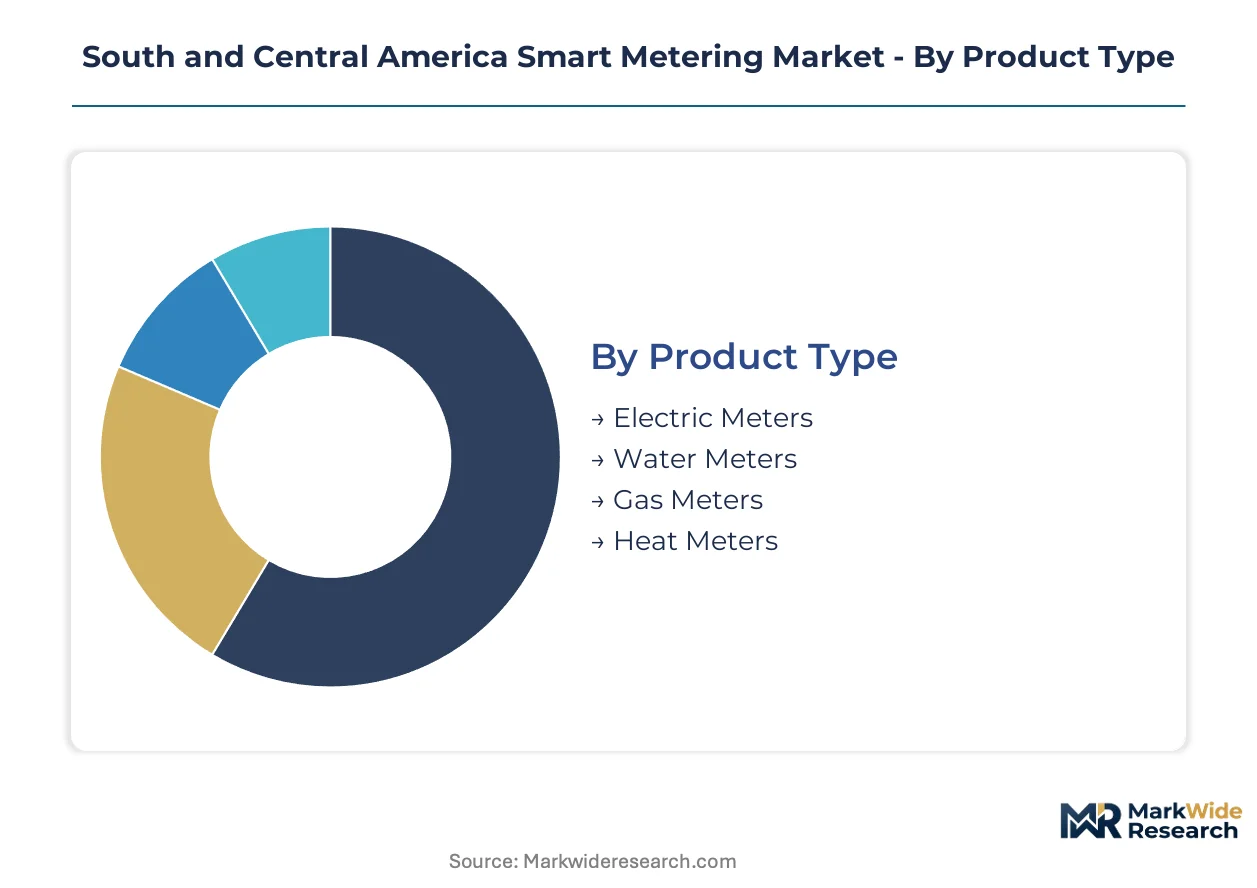
Smart metering segmentation reveals how procurement priorities diverge across utility infrastructure layers. Product type, technology architecture, end-user requirements, and deployment models each reshape vendor qualification criteria and contract value distribution across Brazilian, Argentine, and Chilean concessions.
Product Type:
Use-case spectrum spans residential electricity billing, agricultural water conservation, urban gas safety monitoring, and district heating optimization across divergent climatic zones.
- Electric Meters:Digitally instrumented units record consumption at fifteen-minute intervals with RF mesh or power-line carrier transmission. São Paulo metropolitan concessions drive concentrated demand as ANEEL mandates eliminate manual reading routes across Enel and CPFL distribution zones.
- Water Meters:Pressure-sensing digital units with acoustic leak-detection capabilities command premium positioning. Chile's central valley agricultural networks accelerate replacement cycles as drought conditions intensify monitoring requirements for municipal and irrigation distribution systems.
- Gas Meters:Safety-focused units integrate remote shutoff valves and pressure anomaly alerts. Deployment concentrates in Buenos Aires metropolitan concessions where ENRE modernization timelines mandate networked infrastructure with integrated prepayment functionality.
- Heat Meters:Thermal energy measurement devices serve district heating networks in southern cone urban centers. Limited penetration reflects minimal district heating infrastructure across the region's predominantly cooling-dominated climate zones.
Established volume favors Electric Meters; emerging adoption favors Water Meters.
Technology:
Cost tier stratification separates legacy one-way infrastructure from two-way communicative systems with edge-computing capabilities.
- AMR:One-way automatic meter reading systems transmit consumption data through drive-by radio frequency collection. Stranded asset risk looms across Uruguay and Paraguay where firmware limitations prevent modular AMI upgrade paths.
- AMI:Advanced metering infrastructure enables two-way communication, remote disconnect, and distributed analytics. Brazilian state-owned utilities accelerate replacement schedules as ANEEL technical mandates compress procurement cycles for full-networked ecosystems.
- Networking:Neighborhood area network equipment manages mesh topology and gateway aggregation. Hybrid RF-PLC convergence gains traction in rural Brazilian concessions where cellular coverage gaps persist.
- Communication Protocols:Standardized data transmission specifications ensure interoperability between meter endpoints and headend systems. ANEEL Resolution 1,000 mandates firmware signing and secure boot protocols that extend vendor qualification timelines.
Procurement momentum concentrates in AMI; networking components gain share fastest as deployment scale expands.
End User:
Customer type determines contract structure, with utilities procuring at enterprise scale and fragmented residential segments driving service revenue diversification.
- Utilities:Distribution network operators deploy AMI at concession-scale with multi-year meter data management subscriptions. Brazilian distributors in Minas Gerais and Paraná unbundle hardware from software contracts to enable competitive rebidding.
- Residential Consumers:Individual households receive prepayment-enabled or credit-based metering through utility-managed programs. Token-based electricity vending systems in Brazilian municipalities require dual-protocol gateway engineering.
- Commercial Entities:Mid-sized businesses demand granular consumption analytics for demand response participation. Cloud-native deployment architectures reduce upfront capital requirements for municipal utility customers.
- Industrial Clients:Large power consumers integrate meter data with energy management systems for load scheduling. Premium pricing reflects power quality monitoring and sub-metering requirements.
Utility procurement dominates contract value; commercial segment expansion accelerates as SaaS platforms penetrate mid-sized municipal distributors.
Deployment:
Supply concentration in cloud infrastructure is displacing on-premise server construction across budget-constrained regional utilities.
- On-premises:Physical data center construction with dedicated server infrastructure for meter data management. Capital intensity constrains adoption to large state-owned distributors with established IT departments.
- Cloud-based:Software-as-a-service platforms eliminate physical infrastructure requirements. Brazilian Northeast region municipalities bypass server construction through subscription-based meter data management.
- Hybrid:Split architectures retain critical control functions locally while outsourcing analytics to cloud environments. Edge intelligence firmware enables localized load-disconnect decisions that reduce backhaul bandwidth consumption.
- Remote:Fully outsourced meter data management with third-party hosting and security operations. Cybersecurity certification complexity from ANEEL and ENRE frameworks limits vendor eligibility.
Cloud-based deployment climbs the fastest; hybrid architectures stabilize as edge computing matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration in East Asian semiconductor foundries exposes Brazilian and Argentine assembly plants to lead-time volatility. Distribution concessions across the region source specialized communication chipsets through consolidated supply channels. This dependency shapes deployment timelines for utilities in São Paulo, Buenos Aires, and Santiago metropolitan zones.
Brazil
ANEEL mandates for automated billing and remote disconnect capability compress procurement cycles across state-owned distributors. Resolution 1,000 establishes mandatory cybersecurity certification with firmware signing and secure boot protocols. São Paulo's metropolitan concession areas concentrate deployment activity where Enel and CPFL deploy networked meter ecosystems at scale.
Argentina
ENRE modernization timelines for Buenos Aires distribution concessions mandate full AMI coverage by 2028. The regulator enforces similar metering modernization requirements for concession renewals, locking out non-compliant vendors. Metropolitan Buenos Aires drives immediate procurement windows for networked meter ecosystems with integrated prepayment functionality.
Chile
Drought conditions in the central valley intensify monitoring requirements for municipal and irrigation distribution networks. Acoustic leak-detection meters command premium positioning as agricultural networks accelerate replacement of mechanical water meters. Santiago's urban concessions and surrounding agricultural zones concentrate deployment urgency for pressure-sensing digital units.
Colombia
Utilities in secondary cities face recurring operational expenditure pressures from 4G/LTE data plans required for cellular-communicative meters. Cellular subscription cost burdens constrain deployment scale outside capital regions. Bogotá's metropolitan utilities anchor concentrated demand while secondary municipalities defer full-networked ecosystem rollouts.
Uruguay
Existing one-way automatic meter reading infrastructure lacks firmware upgrade paths, forcing complete hardware replacement rather than modular AMI retrofits. Stranded asset risk extends payback periods for state-owned distribution operators. Montevideo's concession areas concentrate legacy system exposure while rural distribution networks face intermittent cellular coverage gaps.
South and Central America Smart Metering Market Competitive Landscape
Full-service solution providers and specialized component suppliers split the market across hardware manufacturing and software service layers. The competitive structure tilts toward established incumbents with pre-existing regulatory certification relationships. Three archetypes dominate: integrated AMI platform vendors, networking equipment specialists, and cloud-native software providers. Consolidation pressure intensifies through strategic partnerships between meter manufacturers and regional system integrators, while technology licensing agreements accelerate firmware standardization.
Within the integrated platform tier, Landis+Gyr Group AG and Itron Inc. occupy positions shaped by deep AMI integration with Latin American distribution network operators. Schneider Electric exemplifies the cloud-native deployment archetype, reducing on-site infrastructure costs for mid-sized municipal utilities. These three entities represent distinct competitive vectors: hardware-anchored recurring revenue, deep utility system integration, and subscription-based software delivery.
| Leading Market Players |
|---|
| Landis+Gyr Group AG |
| Itron Inc. |
| Honeywell International Inc. |
| Kamstrup A/S |
| Sensus |
| Schneider Electric |
| Siemens |
| ABB |
| Enel Group |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian semiconductor foundries is compressing component pricing for Brazilian assembly plants while simultaneously extending supplier payment terms to 90-120 days. This utilization dynamic shifts bargaining power toward meter manufacturers who can consolidate chipset orders across multiple concession deployments.
Pricing Analysis
After-sales service contracts and multi-year meter data management subscriptions now capture the majority of lifetime value in AMI deployments. Three-tier pricing structure across premium certified, standard compliant, and economy unbundled levels separates vendors with ANEEL pre-certification from aspirants facing extended qualification timelines. Cost compression in hardware tiers is intensifying because Brazilian utilities unbundle endpoint purchases from software subscriptions. Municipal distributors in Brazil's Northeast region exhibit highest price sensitivity, while Enel and CPFL concessions in São Paulo demonstrate lowest sensitivity due to scale efficiencies.
Supply Chain Analysis
Extended payment terms from East Asian foundries now stretch to 120 days for Brazilian meter assemblers, reflecting semiconductor oversupply conditions. Specialized communication chipsets draw from Taiwan, South Korea, and China, while RF mesh radio modules and power-line carrier components rest on German and US supplier bases. Single-source vulnerability concentrates in advanced metering system-on-chip designs where firmware signing capabilities are limited to two qualified foundries. Distribution runs through regional system integrators who manage ANEEL certification logistics and concession-specific customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South and Central America Smart Metering Market represents an early-cycle expansion story where ANEEL Resolution 1,000 cybersecurity mandates are forcing replacement of first-generation AMR infrastructure across Brazilian state-owned distributors.
For Market Incumbents: Harden certification moats by accelerating ANEEL Resolution 1,000 penetration testing submissions for next-generation firmware architectures. Deepen backward integration into edge-computing chip design to reduce exposure to East Asian foundry lead-time volatility. Lock in multi-year meter data management subscriptions with São Paulo metropolitan utilities before competitive rebidding mandates spread to Paraná and Minas Gerais. For New Entrants and Emerging Players: Pursue cloud-native deployment architectures targeting mid-sized municipal utilities in Brazil's Northeast region where on-premise server construction costs block incumbent solutions. Target secondary Colombian and Peruvian cities where cellular subscription cost burdens have stalled AMI rollouts, offering hybrid RF-PLC convergence products that bypass 4G/LTE dependencies. Lead with software-as-a-service meter data management platforms that eliminate upfront capital requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software tiers as subscription delivery displaces physical data center construction. Five-to-ten year viability favors vendors with established ANEEL certification histories and recurring revenue bases above 60% of total contract value. Target acquisition archetypes include regional system integrators with concession relationships in Buenos Aires and Santiago. Watch for inflection when Brazilian Northeast municipalities accelerate SaaS procurement beyond pilot phases.| Strategic Initiative | Industry Significance |
|---|---|
| ANEEL Cybersecurity Certification Acceleration | Pre-qualification through national laboratories locks out non-compliant vendors from São Paulo tenders. |
| Cloud-Native Meter Data Management Deployment | SaaS platforms enable Paraná municipal utilities to bypass physical infrastructure capital requirements. |
| Hybrid RF-PLC Convergence Product Development | Combined radio-frequency and power-line carrier architectures penetrate rural Brazilian concessions with cellular gaps. |
| After-Sales Service Contract Unbundling | Separate hardware supply from multi-year analytics subscriptions enables competitive rebidding in Minas Gerais. |
| Edge-Computing Firmware Virtualization | Localized load-disconnect decisions reduce backhaul bandwidth consumption 60% for Enel and CPFL deployments. |
Research Methodology
Cross-validation between primary interviews with utility planning officers and secondary validation through ANEEL regulatory filings anchors the qualitative findings. Conversations with distribution network operators, AMI deployment engineers, concession procurement managers, and meter data management software vendors combined with bottom-up triangulation against customs records, EIA electricity distribution data, and SEC filings from publicly traded meter manufacturers. Top-down calibration against national electrification statistics and regulatory modernization timelines completed the validation framework.
Calibration against historical deployment curves and concession renewal schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, deployment model, and utility ownership structure. CAGRs were derived from fitted adoption curves weighted by regulatory mandate enforcement timelines. Key inputs incorporated ANEEL Resolution 1,000 implementation pace, ENRE 2028 AMI coverage deadlines, and Chilean central valley drought severity indices.
Sensitivities concentrate around semiconductor supply normalization timelines and Brazilian federal budget allocation shifts for state-owned distributor capital programs. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and concession renewal schedules. Macroeconomic volatility affecting municipal utility borrowing costs, cybersecurity certification requirement expansion, or cellular data plan pricing spikes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Global Smart Energy Meters Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
Power Monitoring System Market
Smart Meters
Solar Meter Market
Smart Meters
Power Metering Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
United States Smart Meter Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Water Meter Market