
 Smart Fleet Management Market | 2026-2036
Smart Fleet Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fleet Management Market Intelligence
Software-defined subscription tiers is realigning how fleet vendors monetize capability access. Geotab leverages its open-platform architecture to sustain integration partnerships across telematics ecosystems. Samsara anchors its competitive position through in-house IoT hardware production and real-time video analytics. Motive differentiates by dominating compliance automation for hours-of-service regulations in North American trucking corridors.
Smart Fleet Management encompasses integrated systems combining GPS tracking, onboard diagnostics, cloud computing, and AI-driven analytics to monitor, coordinate, and optimize vehicle fleet operations in real time. These systems process telemetry data at sub-second intervals to enable predictive maintenance, fuel efficiency algorithms, and driver safety scoring across commercial transport applications. Hardware components retain the largest installed base but carry thinning margins as commoditization accelerates. Cloud-based deployment is expanding fastest as fleet operators abandon capital-intensive on-premise infrastructure for elastic, API-accessible platforms.
The EPA regulates heavy-duty vehicle emissions thresholds that directly shape fleet replacement cycles and telematics investment timing. NHTSA mandates electronic logging device compliance that standardizes data capture formats across interstate carriers. The EU Green Deal's CO2 performance standards for commercial vehicles are forcing cross-border operators to adopt unified sustainability tracking. Fleet stakeholders must monitor how divergent EPA and EU regulatory timelines will fragment platform certification requirements and reshape vendor geographic prioritization.
Market Dynamics
Fleet operators face simultaneous pressure from EPA emissions mandates and EU Green Deal CO2 performance standards, forcing unified telematics architectures that bridge transatlantic compliance requirements.
Growth Catalysts
- AI-powered route optimization:Logistics carriers deploy machine learning algorithms that reduce fuel consumption and idle time across distribution networks.
- EU Green Deal commercial vehicle standards:Cross-border operators must install unified sustainability tracking systems to meet binding emissions reduction targets.
- German automotive OEM integration:Fleet operators in Stuttgart and Munich anchor telematics adoption by embedding compliance frameworks directly into vehicle procurement specifications.
Market Restraints
- Semiconductor supply concentration:Telematics control unit production depends on foundry capacity concentrated in East Asian manufacturing clusters.
- On-premise infrastructure stranded costs:Capital-intensive legacy server installations create switching friction for mid-sized fleet operators.
- Cellular connectivity tariff volatility:Data transmission costs for real-time video analytics fluctuate with carrier pricing renegotiations.
Strategic Opportunities
- Electrification compliance platforms:Battery electric vehicle fleets require new telematics modules that monitor state-of-charge and charging infrastructure availability.
- India logistics corridor expansion:Cold-chain and e-commerce fulfillment networks in Maharashtra and Karnataka lack integrated fleet visibility systems.
- NHTSA hours-of-service automation:Electronic logging device mandates create captive demand for compliance-integrated dispatch software in interstate trucking.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for sub-second telemetry processing outpaces vocational training pipeline output.
- Multi-protocol integration complexity:Fleet operators struggle to unify J1939, OBD-II, and proprietary OEM data streams into single analytics platforms.
- CSRD sustainability reporting alignment:European operators must reconcile telematics data formats with corporate sustainability disclosure requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fleet Management Market |
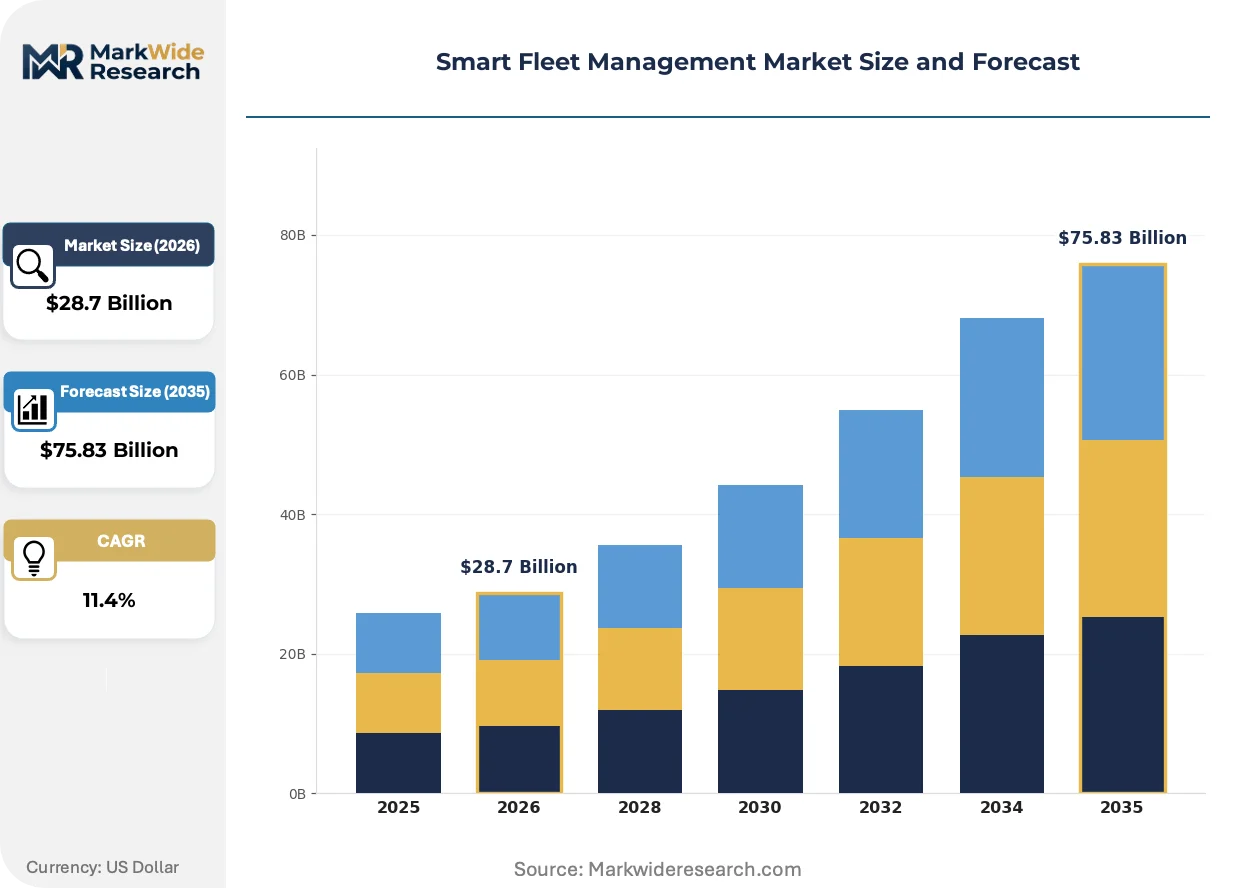
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Telematics, GPS tracking, Cloud Computing, AI Solutions End User: Logistics Companies, Public Transportation, Delivery Services, Fleet Operators Component: Hardware, Software, Services, Connectivity Modules Deployment: On-Premise, Cloud-Based, Hybrid, Mobile-Based |
| Companies Covered | Geotab, Lytx, FleetRabbit, Teletrac Navman, Fleetio, Samsara, Verizon Connect, Azuga, Motive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fleet Management Market Strategic Shifts & Innovations
Cloud-native telemetry architectures are compressing deployment timelines while regulatory pressure fuses emissions tracking with operational optimization into single platform mandates.
Edge computing nodes installed directly on commercial vehicles process diagnostic data locally before transmitting compressed insights to central clouds. Long-haul trucking fleets in North American corridors adopt these units fastest, reducing cellular data costs by filtering redundant engine status pings. Real-time predictive maintenance is overtaking scheduled service intervals as the dominant fleet uptime strategy.
EPA heavy-duty vehicle emissions thresholds now trigger telematics investment synchronized with fleet replacement cycles rather than ad hoc upgrades. The regulatory timeline forces carriers to justify hardware expenditures through combined compliance and fuel efficiency gains. Interstate operators subject to NHTSA electronic logging mandates face compressed procurement windows that favor pre-certified integrated platforms over modular best-of-breed assemblies.
Subscription-based capability access replaces perpetual license purchases across mid-market fleet operators. Third-party logistics providers in German industrial clusters lead this transition, treating telematics as operational expenditure rather than capital deployment. Procurement committees now weight API extensibility and partner ecosystem breadth above standalone feature checklists when selecting vendors.
Smart Fleet Management Market Segmentation
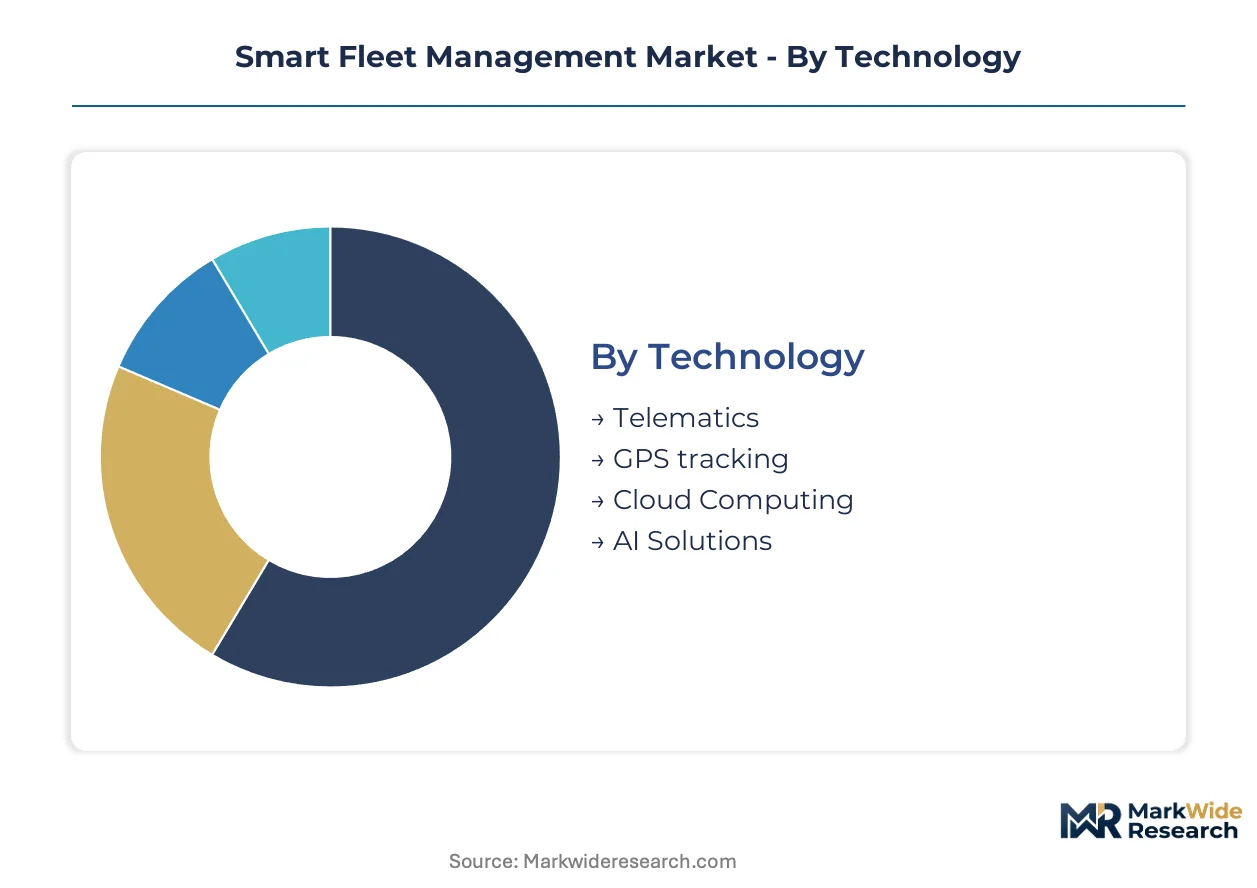
Segmentation in Smart Fleet Management reveals how procurement priorities diverge across buyer archetypes. Technology choices separate data-native operators from legacy-dependent carriers. Component preferences expose margin compression in hardware versus recurring revenue capture in software tiers.
Technology:
Deployment sophistication distinguishes buyers by their tolerance for integration complexity and latency requirements.
- AI Solutions:Machine learning platforms process route, fuel, and driver behavior data to generate predictive recommendations. Demand concentrates among German automotive OEMs integrating sustainability compliance frameworks with operational optimization mandates.
- Telematics:Onboard diagnostic and location tracking systems form the foundational data layer for fleet visibility. Logistics carriers across interstate North American corridors anchor procurement here due to NHTSA electronic logging device mandates.
- GPS tracking:Satellite-based positioning enables real-time vehicle location monitoring with meter-level accuracy.
- Cloud Computing:Elastic infrastructure supports API-accessible analytics without capital-intensive server deployment.
Telematics leads volumes today; AI Solutions is gaining share fastest.
End User:
Operational scale and regulatory exposure shape how each buyer type weights compliance automation against fuel efficiency gains.
- Fleet Operators:Dedicated vehicle fleet managers combine owned assets with outsourced maintenance to optimize total cost of ownership. German industrial clusters in Stuttgart and Munich embed telematics specifications directly into procurement cycles.
- Logistics Companies:Third-party carriers coordinate multi-client distribution networks requiring unified visibility across heterogeneous vehicle pools. Cross-border operators under EU Green Deal mandates drive demand for emissions-integrated platforms.
- Public Transportation:Municipal and regional transit authorities manage fixed-route services with unionized workforce constraints.
- Delivery Services:Last-mile fulfillment networks prioritize stop-density optimization and customer notification automation.
Fleet Operators dominate current deployment; Logistics Companies show the steepest expansion trajectory.
Component:
Margin structure varies dramatically between capital goods and recurring service revenue streams.
- Software:Subscription-based capability access replaces perpetual licenses across mid-market buyers. Procurement committees weight API extensibility above standalone feature checklists.
- Hardware:Telematics control units and onboard sensors carry thinning margins as commoditization accelerates in East Asian manufacturing clusters.
- Services:Implementation, training, and ongoing support packages attach to platform deployments.
- Connectivity Modules:Cellular and satellite transmission hardware enables real-time data pipelines.
Hardware retains the largest installed base; Software is climbing the fastest.
Deployment:
Infrastructure preference signals buyer maturity and IT resource availability.
- Cloud-Based:Elastic, API-accessible platforms eliminate capital-intensive server investments. Fleet operators abandon on-premise infrastructure fastest where cellular connectivity tariffs stabilize.
- Hybrid:Mixed architectures preserve sensitive data locally while pushing analytics workloads to central clouds. Mid-sized operators with stranded legacy investments favor this transitional posture.
- On-Premise:Capital-intensive server installations create switching friction for operators with sunk infrastructure costs.
- Mobile-Based:Smartphone-dependent deployments suit small fleets with limited dedicated hardware budgets.
On-Premise still anchors legacy installations; Cloud-Based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates telematics procurement through automotive OEM supply chains while the United States anchors interstate trucking compliance demand. Divergent regulatory timelines between EPA emissions thresholds and EU Green Deal mandates force cross-border operators toward unified platform architectures.
United States
Interstate carriers under NHTSA electronic logging device mandates drive telematics hardware procurement through compressed replacement cycles. EPA heavy-duty vehicle emissions thresholds synchronize fleet investment timing with compliance deadlines. Dallas-Fort Worth logistics clusters anchor demand for hours-of-service automation platforms.
Germany
Automotive OEMs in Stuttgart and Munich embed sustainability tracking specifications directly into vehicle procurement frameworks. EU Green Deal CO2 performance standards force cross-border operators toward unified emissions reporting architectures. Bavarian industrial corridors concentrate demand for AI-powered route optimization integrated with compliance dashboards.
United Kingdom
Post-Brexit regulatory divergence creates dual-certification burdens for fleet operators serving EU-UK corridors. DVSA enforcement of driver hours rules sustains demand for electronic logging systems with cross-border data portability. Midlands distribution hubs anchor cold-chain fleet visibility investments.
India
E-commerce fulfillment networks in Maharashtra and Karnataka lack integrated telematics coverage for last-mile optimization. The country's national automotive regulator pushes commercial vehicle safety standards that favor onboard diagnostic adoption. Mumbai-Pune logistics corridors drive initial demand for cloud-based fleet visibility among third-party carriers.
Japan
Precision logistics requirements in automotive just-in-time supply chains sustain demand for sub-second telemetry accuracy. METI efficiency standards for commercial vehicle fleets mandate fuel consumption monitoring systems. Nagoya industrial clusters anchor integration of telematics with manufacturing execution systems.
Smart Fleet Management Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with software-native platforms capturing recurring revenue while hardware-anchored vendors defend installed base positions. The vendor landscape organizes into three tiers: cloud-native specialists with API-first architectures, vertically integrated players controlling in-house hardware production, and legacy telematics providers transitioning from perpetual licenses. Consolidation pressure concentrates among mid-scale operators seeking scale economies in cellular connectivity procurement. Strategic moves center on platform ecosystem expansion through integration partnerships and subscription tier restructuring to capture mid-market migration from on-premise deployments.
Among North American platform specialists, Geotab, Samsara, and Motive occupy distinct competitive positions. Geotab exemplifies the open-platform archetype through its integration partnership strategy across telematics ecosystems. Samsara represents vertically integrated hardware-software convergence with in-house IoT device production capabilities. Motive anchors the compliance-automation specialization targeting hours-of-service regulatory workflows in trucking corridors.
| Leading Market Players |
|---|
| Geotab |
| Lytx |
| FleetRabbit |
| Teletrac Navman |
| Fleetio |
| Samsara |
| Verizon Connect |
| Azuga |
| Motive |
| Others |
Cost & Logistics Intelligence
Fleet operator migration from perpetual licenses to subscription-based capability access is forcing hardware vendors to absorb upfront production costs while software tiers capture recurring revenue streams.
Pricing Analysis
Capacity additions in East Asian manufacturing clusters are reshaping price floors for telematics control units as commoditization accelerates. Three-tier pricing structure across premium, standard, and economy levels separates API-extensible platforms from modular hardware bundles. Cost compression in hardware tiers is intensifying because semiconductor foundry output expansion outpaces differentiated firmware development. Mid-sized fleet operators with stranded on-premise investments exhibit highest price sensitivity; German automotive OEMs anchoring sustainability compliance specifications show lowest.
Supply Chain Analysis
Certification bottlenecks for NHTSA electronic logging device compliance and EU Green Deal emissions tracking standards gate vendor market access. Telematics hardware production draws from Taiwan, South Korea, and China for semiconductor foundry capacity. Critical inputs include GPS chipsets, cellular modems, and onboard diagnostic sensors. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through automotive OEM procurement channels and third-party logistics provider direct sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart Fleet Management operates as a regulatory compounder where EPA heavy-duty emissions thresholds and EU Green Deal mandates synchronize procurement cycles with compliance deadlines.
For Market Incumbents: Acquire embedded systems engineering talent pools to defend against firmware development scarcity threatening sub-second telemetry processing capabilities. Secure captive supply of telematics control unit manufacturing capacity in East Asian clusters to offset semiconductor allocation volatility. Consolidate mid-scale competitors to achieve scale economies in cellular connectivity procurement. For New Entrants and Emerging Players: Enter via cloud-native platform architectures targeting India logistics corridors in Maharashtra and Karnataka where cold-chain and e-commerce fulfillment networks lack integrated fleet visibility. White-space opportunity concentrates in battery electric vehicle telematics modules monitoring state-of-charge and charging infrastructure availability. Go-to-market leverage rests on API-first integration partnerships with existing telematics ecosystems. For Investors and Strategic Acquirers: Asymmetric upside sits with software-native specialists capturing recurring subscription revenue from mid-market fleet operator migration away from capital-intensive on-premise deployments. Long-term viability favors vendors with demonstrated EU Green Deal compliance certification and NHTSA electronic logging device pre-certification. Acquisition target archetype: vertically integrated platforms controlling in-house IoT hardware production. Signal to watch: EPA emissions threshold timeline adjustments triggering synchronized fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API extensibility anchors vendor selection criteria for German automotive OEM procurement committees. |
| Acquisition of Specialist Firm | Embedded firmware capabilities address talent scarcity constraining sub-second telemetry development pipelines. |
| Geographic Expansion | India logistics corridors in Maharashtra and Karnataka present underpenetrated cloud-native deployment opportunities. |
| Strategic Partnership | Charging infrastructure alliances enable battery electric vehicle fleet telematics module market entry. |
| Product Launch | Unified sustainability tracking platforms bridge divergent EPA and EU Green Deal compliance requirements. |
Research Approach
Direct dialogue with fleet operations directors, telematics platform engineers, automotive OEM procurement managers, and third-party logistics carrier executives grounded qualitative findings in operational reality. Secondary validation drew from NHTSA regulatory filings, EPA emissions compliance databases, EU Green Deal implementation guidelines, and automotive production registration data. Bottom-up unit economics triangulated against top-down market sizing across deployment models, fleet scales, and regional regulatory clusters.
Segment-level outputs across the analysis window reflect modeled interactions between technology adoption curves, compliance mandate timelines, and infrastructure investment cycles. Dimensions included deployment architecture, fleet operator scale, vehicle propulsion type, integration complexity tier, and regional regulatory framework. CAGRs were derived from regression analysis of historical telematics penetration rates against regulatory enforcement phases. Forecast inputs incorporated cellular connectivity tariff trajectories and semiconductor foundry capacity expansion announcements.
Inputs from fleet operator procurement committees and automotive OEM specification documents were available through the study window; gaps in real-time charging infrastructure deployment data introduce uncertainty bands for electrification compliance platform adoption curves. Forecasts reflect documented assumptions regarding EPA and EU regulatory timeline synchronization. A model refresh is warranted upon material change in NHTSA electronic logging device mandate enforcement schedules or EU Green Deal CO2 performance standard acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Europe Passenger Information System Market