
 Big Data Analytics in Transportation Market | 2026-2036
Big Data Analytics in Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Analytics in Transportation Market Analysis
Data science talent scarcity is bifurcating the competitive landscape between vendors with captive AI labs and those dependent on contracted engineering. SAP SE leverages its deep enterprise install base to embed transportation analytics within broader supply chain suites. Oracle Corporation anchors its position through database-to-cloud integration that captures streaming telematics at scale. INRIX specializes in probe-data aggregation, competing on real-time road network coverage rather than enterprise software breadth.
Big Data Analytics in Transportation encompasses the collection, processing, and algorithmic interpretation of high-velocity, high-variety datasets generated by vehicles, infrastructure sensors, mobile devices, and logistics systems to optimize movement, predict failures, and automate routing decisions. The discipline relies on distributed computing frameworks, streaming ingestion pipelines, and machine learning models trained on historical traffic patterns, vehicle diagnostics, and cargo conditions to deliver sub-second operational recommendations. Predictive Analytics and Machine Learning command the largest technology investment pools, though Edge Computing deployments are gaining traction where latency constraints prevent cloud round-trips. Fleet Management and Route Optimization applications absorb the majority of current spending, while Predictive Maintenance represents the fastest-expanding application segment as asset-heavy operators seek to convert downtime data into preemptive service scheduling.
The EU AI Act imposes risk-classification requirements on automated transport decision systems, compelling vendors to document algorithmic transparency and human oversight protocols. The US Department of Transportation coordinates with the FAA and NHTSA on data standards for autonomous and connected vehicle corridors, shaping interoperability mandates that determine market access for analytics platforms. ISO and IEC frameworks for smart city data governance further constrain how cross-border traffic datasets may be pooled and processed. Stakeholders must monitor whether emerging national data localization requirements fragment cloud-based analytics architectures or accelerate hybrid deployment models that retain sensitive vehicle data within jurisdictional boundaries.
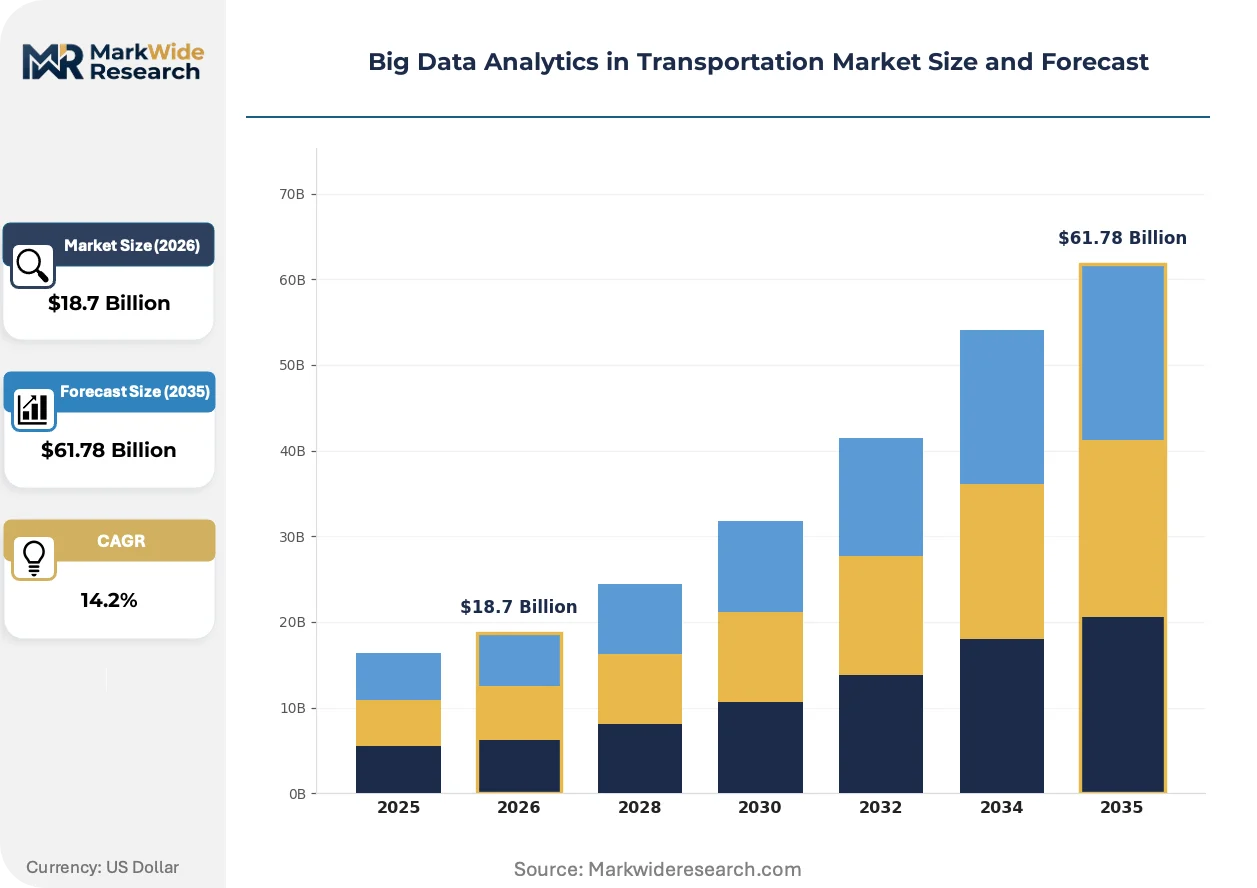
Market Dynamics
Edge computing architectures are compressing latency requirements for real-time fleet decisions, forcing transport operators to reconfigure data pipelines away from centralized cloud processing toward distributed inference nodes.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification rules for automated transport systems are accelerating procurement of explainable machine learning platforms that document algorithmic transparency and human oversight protocols.
- Predictive maintenance adoption:Asset-heavy freight operators are converting vehicle downtime telemetry into preemptive service scheduling, expanding software subscription revenue pools for analytics vendors.
- German automotive OEM investment:Stuttgart and Munich-based manufacturers anchor advanced telematics deployment, creating reference architectures that cascade through European logistics networks.
Market Restraints
- GDPR data localization friction:Cross-border traffic dataset pooling faces jurisdictional constraints that fragment cloud-based analytics architectures and inflate compliance overhead.
- Specialized data science scarcity:Shortages of engineers proficient in distributed computing frameworks and streaming ingestion pipelines compress implementation timelines for mid-tier operators.
- Silicon supply concentration:Edge computing hardware deployment depends on semiconductor fabrication capacity concentrated in East Asian foundries, exposing fleet operators to input volatility.
Strategic Opportunities
- Indian logistics digitization:National highway corridor modernization and freight digitization initiatives create greenfield deployment opportunities for predictive routing algorithms.
- ISO/IEC smart city standards:Emerging frameworks for urban data governance are mandating interoperable traffic sensor networks, opening specification influence channels for analytics platform vendors.
- Digital twin convergence:Integration of physics-based vehicle simulation with live telematics streams enables synthetic training environments that accelerate machine learning model deployment.
Industry Challenges
- Legacy fleet integration complexity:Heterogeneous vehicle communication protocols and proprietary OEM data formats obstruct unified analytics layer deployment across mixed-age fleets.
- Model validation timelines:Safety-critical algorithm certification for autonomous decision systems requires extensive field testing that extends product development cycles.
- Cross-functional talent gaps:Shortage of professionals bridging transportation operations expertise with machine learning engineering obstructs pilot-to-production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Analytics in Transportation Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Predictive Analytics, Data Mining, Visualization Tools Application: Fleet Management, Traffic Management, Predictive Maintenance, Route Optimization End User: Logistics Providers, Public Transport Authorities, Ride-sharing Services, Freight Forwarders Deployment: On-premises, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | SAP SE, Oracle Corporation, IBM Corporation, Microsoft Corporation, TomTom, INRIX, Blue Yonder, Siemens Mobility, Kinaxis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Analytics in Transportation Market Emerging Trajectories
Federated learning architectures and on-vehicle inference chips are redistributing computational load across the transport technology stack, compressing the traditional cloud-centric analytics model.
Edge-native inference engines are displacing centralized cloud round-trips for latency-sensitive applications including collision avoidance and real-time cargo condition monitoring. Fleet operators with high-frequency routing requirements are deploying graphics processing units directly within vehicle cabins and depot gateways. This architectural shift is compressing bandwidth costs while enabling sub-50-millisecond decision loops that cloud pipelines cannot sustain.
The EU AI Act's risk-tier classification system is mandating algorithmic documentation and human-in-the-loop protocols for automated transport decisions. Vendors must now maintain technical files demonstrating conformity with transparency requirements before deploying predictive models in commercial fleets. German freight operators and Dutch port authorities are pioneering compliance frameworks that other European jurisdictions are adopting as reference standards.
Subscription-based analytics procurement is replacing perpetual license models as fleet operators demand usage-aligned pricing tied to vehicle-miles or data-ingestion volumes. Tier-one logistics providers in North America are unbundling software from telematics hardware, selecting best-of-breed algorithmic layers while commoditizing sensor infrastructure. This purchasing pattern shift is most pronounced among e-commerce fulfillment operators with seasonal volume volatility.
Big Data Analytics in Transportation Market Segmentation
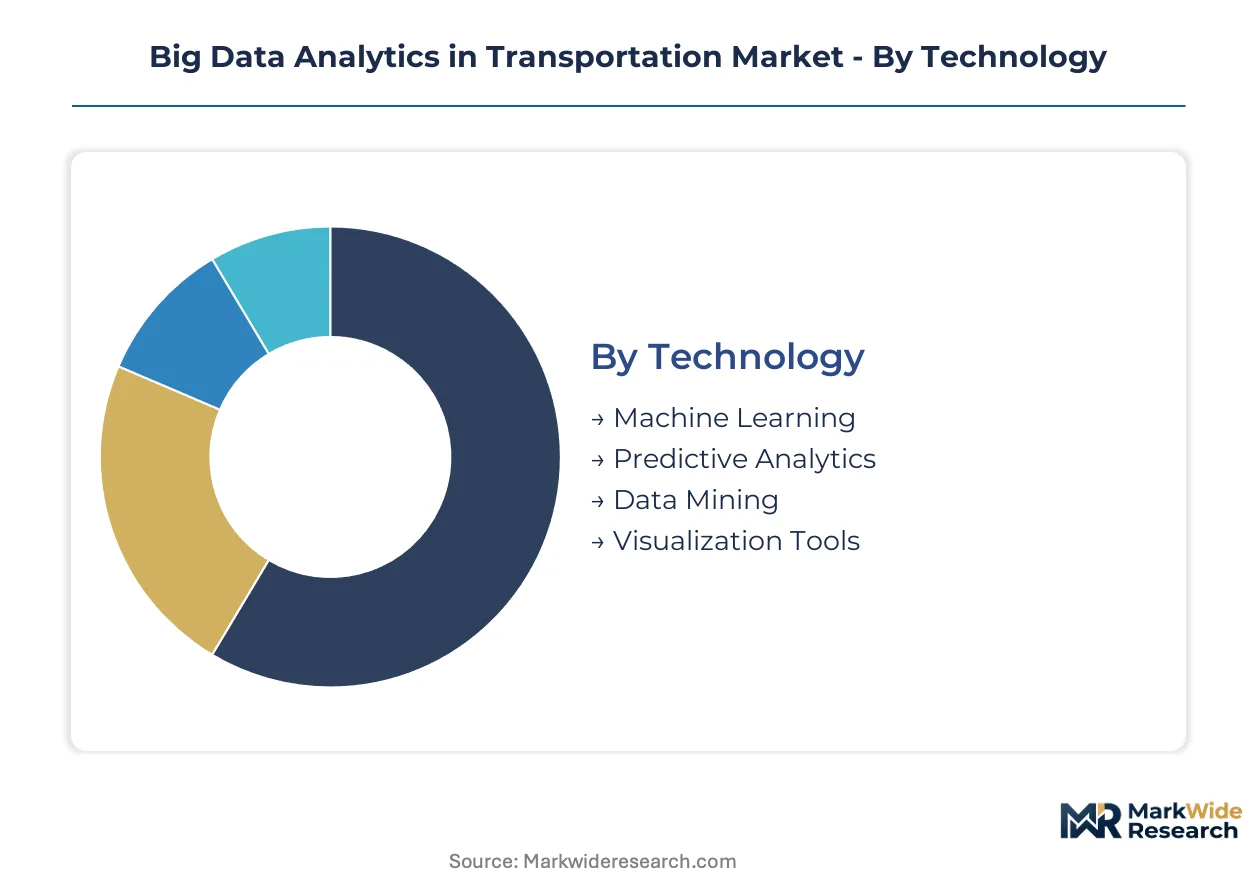
Transportation analytics vendors structure product portfolios around distinct technology capabilities, operational use cases, and infrastructure deployment models. Understanding where margin pools concentrate within each dimension enables targeted resource allocation and partnership prioritization.
Technology:
Margin concentration favors platforms that embed proprietary algorithms rather than commodity visualization layers, with machine learning commanding premium pricing through differentiated predictive accuracy.
- Machine Learning:Neural network architectures and ensemble methods process streaming telematics to forecast vehicle failures and traffic congestion. German freight operators and Dutch port authorities anchor demand as EU AI Act compliance requirements elevate explainable model procurement.
- Predictive Analytics:Statistical forecasting engines project demand volatility, fuel consumption patterns, and maintenance intervals from historical operational datasets. Asset-heavy logistics providers in North America convert downtime telemetry into preemptive service scheduling, expanding recurring software revenue.
- Data Mining:Pattern recognition algorithms extract behavioral insights from unstructured driver logs and cargo manifests.
- Visualization Tools:Dashboard and geospatial mapping interfaces translate complex datasets into operational decision support.
Predictive Analytics holds installed capacity. Machine Learning is rotating up the share rankings.
Application:
Application segmentation reflects operational priorities across asset ownership models, with fleet-intensive operators prioritizing real-time visibility while infrastructure managers emphasize network flow optimization.
- Fleet Management:Real-time vehicle tracking, driver behavior monitoring, and compliance reporting systems integrate telematics hardware with centralized command platforms. Stuttgart and Munich-based automotive OEMs anchor advanced deployment, creating reference architectures that cascade through European logistics networks.
- Route Optimization:Dynamic pathfinding algorithms balance fuel efficiency, delivery windows, and regulatory constraints against live traffic conditions. E-commerce fulfillment operators with seasonal volume volatility drive procurement of usage-aligned pricing models.
- Traffic Management:Urban signal coordination and congestion pricing systems process probe data from connected vehicle fleets.
- Predictive Maintenance:Sensor fusion models detect component degradation before functional failure triggers unplanned downtime. This segment is expanding most quickly as operators seek to convert vehicle health data into scheduled service intervals.
Fleet Management holds installed capacity. Predictive Maintenance is rotating up the share rankings.
End User:
End user segmentation reveals divergent procurement authority structures, with centralized public agencies favoring multi-year framework contracts while private operators prioritize agile pilot-to-production scaling.
- Logistics Providers:Third-party freight operators deploy unified visibility platforms across heterogeneous vehicle fleets and subcontractor networks. Indian national highway corridor modernization creates greenfield deployment opportunities for predictive routing algorithms.
- Freight Forwarders:Intermodal coordinators optimize cargo handoffs across sea, rail, and road legs through shipment-level tracking integration. Cross-border operators face GDPR data localization friction that fragments cloud-based analytics architectures.
- Public Transport Authorities:Municipal and regional transit agencies coordinate fixed-route and on-demand services through ridership forecasting and fleet repositioning systems.
- Ride-sharing Services:Mobility platforms match driver supply with demand surges using dynamic pricing and ETA prediction engines.
Logistics Providers hold installed capacity. Freight Forwarders is rotating up the share rankings.
Deployment:
Deployment architecture selection trades latency sensitivity against capital intensity, with sub-50-millisecond decision requirements pushing computational load toward distributed inference nodes.
- Edge Computing:On-vehicle and depot-gateway inference engines process sensor streams locally, eliminating cloud round-trip delays for collision avoidance and cargo condition alerts. Graphics processing unit deployment within vehicle cabins depends on semiconductor fabrication capacity concentrated in East Asian foundries.
- Cloud-based:Centralized data lakes and model training pipelines aggregate fleet-wide datasets for longitudinal pattern detection. Subscription-based procurement is displacing perpetual licenses as operators demand usage-aligned pricing.
- Hybrid:Architectures partition sensitive vehicle data within jurisdictional boundaries while pushing anonymized aggregates to centralized analytics layers.
- On-premises:Dedicated infrastructure retains full data sovereignty for defense and critical infrastructure operators with strict security requirements.
Cloud-based holds installed capacity. Edge Computing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European regulatory momentum for algorithmic transparency in transport systems, while German automotive OEMs anchor investment concentration for advanced telematics infrastructure.
Germany
Stuttgart and Munich-based manufacturers drive predictive fleet analytics procurement through integrated supply chain platforms. The KBA enforces type-approval standards for connected vehicle systems that shape vendor compliance documentation. The Baden-Württemberg automotive cluster generates reference architectures cascading through European logistics networks.
United States
E-commerce fulfillment operators with seasonal volume volatility demand usage-aligned pricing for routing algorithms. The NHTSA coordinates with the FAA on data standards for autonomous vehicle corridors that determine platform interoperability. Silicon Valley cloud providers and Detroit automotive engineering centers concentrate edge computing deployment for real-time cargo monitoring.
China
National highway corridor digitization and smart city infrastructure programs expand probe-data aggregation demand. The MIIT issues GB standards for vehicle-to-everything communication protocols that constrain foreign platform market access. The Yangtze River Delta logistics hubs deploy hybrid architectures retaining sensitive vehicle data within jurisdictional boundaries.
India
National freight digitization initiatives create greenfield opportunities for predictive routing algorithms across fragmented carrier networks. The BIS develops smart city data governance frameworks mandating interoperable traffic sensor specifications. The Delhi-Mumbai Industrial Corridor anchors telematics investment concentration among third-party logistics providers.
Netherlands
Rotterdam port authorities pioneer EU AI Act compliance frameworks for automated cargo handling decision systems. GDPR data localization requirements push transport operators toward hybrid cloud architectures with jurisdictional data partitioning. The Randstad logistics cluster integrates multimodal shipment tracking across North Sea shipping lanes and continental road networks.
Big Data Analytics in Transportation Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure where scale determines platform breadth and niche expertise commands vertical premiums. Enterprise software conglomerates leverage captive cloud infrastructure and database integration to capture streaming telematics at scale. Specialist probe-data aggregators compete on real-time road network coverage rather than enterprise suite breadth. Dominant competitive moves include strategic partnerships between automotive OEMs and cloud providers, plus portfolio diversification into edge-native inference engines.
Within the enterprise software tier, SAP SE and Oracle Corporation represent integrated platform providers embedding transportation analytics within broader supply chain suites. INRIX occupies a position exemplifying the probe-data specialist archetype, competing on real-time traffic coverage rather than enterprise software breadth. IBM Corporation and Microsoft Corporation anchor positions among cloud-native providers with distributed computing infrastructure for streaming ingestion pipelines.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Microsoft Corporation |
| TomTom |
| INRIX |
| Blue Yonder |
| Siemens Mobility |
| Kinaxis Inc. |
| Others |
Supply Flow & Price Mechanics
Edge-native inference chips substituting for centralized cloud processing are redrawing procurement geography and compressing subscription economics across the analytics stack. This hardware migration simultaneously elevates capital intensity for fleet operators and fragments vendor pricing power between semiconductor suppliers and software platforms.
Pricing Analysis
Geographic price spreads separate German freight operators paying premium rates for EU AI Act-compliant explainable models from Indian logistics providers procuring standardized cloud analytics at lower tiers. Subscription-based SaaS pricing dominates, with differentiation hinging on ISO 27001 certification tiers and real-time data ingestion volumes. Cost compression in the mid-market tier is intensifying because graphics processing unit deployment costs are tethered to East Asian foundry capacity. E-commerce fulfillment operators with seasonal volume volatility exhibit highest price sensitivity; defense and critical infrastructure operators demonstrate lowest sensitivity due to on-premises sovereignty requirements.
Supply Chain Analysis
Taiwan and South Korea anchor advanced semiconductor fabrication for edge computing inference engines, while China and Germany concentrate telematics hardware assembly and sensor manufacturing. The supply chain draws from silicon wafers, rare earth magnet components, and specialized automotive-grade memory modules. Single-source vulnerability in advanced node chip production exposes fleet operators to input volatility. Distribution runs through direct enterprise sales teams for tier-one logistics providers and cloud marketplace channels for mid-tier operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across legacy fleet integration complexity creates niche opportunities for specialists bridging heterogeneous vehicle protocols. The shift toward explainable algorithmic systems under EU AI Act mandates is spawning demand for compliance-focused analytics layers.
For Market Incumbents: Secure algorithmic transparency documentation capabilities before EU AI Act enforcement timelines compress procurement windows. Consolidate edge computing partnerships with automotive OEMs to lock in reference architecture status. Vertical integration into on-vehicle inference hardware mitigates silicon supply concentration risk from East Asian foundries.
For New Entrants and Emerging Players: Differentiate on federated learning architectures that enable cross-border dataset pooling without GDPR localization violations. Target Indian freight digitization initiatives as the most penetrable geography, where fragmented carrier networks lack unified visibility platforms. Pursue pilot-to-production scaling through usage-aligned pricing models that align with seasonal volume volatility among e-commerce fulfillment operators.
For Investors and Strategic Acquirers: The market sits at a compliance-driven consolidation phase that favors explainable AI specialists with captive data science talent. Long-term viability over the next decade hinges on regulatory certification moats rather than raw algorithmic performance. Acquisition candidates should demonstrate documented EU AI Act conformity assessment procedures. Monitor KBA type-approval standard revisions as the signal indicating when compliance investments convert to pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Inference Engine Development | Sub-50-millisecond decision loops for collision avoidance exceed cloud pipeline capabilities. |
| EU AI Act Compliance Certification | KBA and Dutch port authority frameworks establish reference standards across European logistics networks. |
| Federated Learning Architecture Deployment | Cross-border dataset pooling without GDPR localization friction unlocks fragmented freight markets. |
| Automotive OEM Strategic Partnership | Stuttgart and Munich-based manufacturers cascade reference architectures through supplier networks. |
| Indian Logistics Corridor Market Entry | Delhi-Mumbai Industrial Corridor digitization creates greenfield predictive routing opportunities. |
Methodological Framework
Operator-level perspectives from fleet managers, telematics procurement officers, data science directors at logistics providers, and compliance leads at automotive OEMs anchored the qualitative base. These primary interviews combined with secondary validation from SEC filings of enterprise software vendors, EU regulatory documentation on AI Act implementation, NHTSA autonomous vehicle corridor standards, and IHS Markit vehicle production databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across technology, application, end user, and deployment dimensions.
Sensitivity analysis tested forecast robustness against edge computing adoption velocity, EU AI Act enforcement timing, and semiconductor supply volatility across the projection horizon. The analytical framework modeled machine learning platform penetration, predictive maintenance adoption curves, fleet management software deployment, and route optimization algorithm procurement by logistics provider scale, freight forwarder network complexity, public transport authority jurisdiction, and ride-sharing platform data ingestion volumes. CAGRs derived from longitudinal pattern detection in historical telematics investment cycles and regulatory compliance spending trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory momentum, continued East Asian semiconductor supply concentration, or accelerated Indian infrastructure digitization would require recalibration. Forecasts reflect documented assumptions regarding edge computing cost curves and explainable AI development timelines. Specific risk factors include GDPR data localization fragmentation, legacy fleet integration complexity, and cross-functional talent scarcity obstructing pilot-to-production scaling. Recalibration cycles align with material shifts in EU AI Act enforcement guidance and MIIT V2X protocol standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Asia Pacific Hyperloop Technology Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Car E-Hailing Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market