
 Parking Finder Apps Market | 2026-2036
Parking Finder Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Parking Finder Apps Market Analytics
Fragmentation across municipal buyers is restructuring how parking finder platforms secure long-term contracts. SpotHero leverages direct partnerships with commercial garage operators to sustain pricing control in dense urban corridors. Parkopedia Parking anchors its position through granular coverage of street-level parking regulations across European capitals. ParkMobile competes aggressively on transaction volume with city-branded white-label deployments.
Parking finder applications are digital platforms that aggregate real-time space availability, pricing data, and reservation functionality through GPS-enabled mobile interfaces, typically processing payments via encrypted cloud gateways. Their primary commercial purpose is reducing search traffic and monetizing underutilized parking inventory for asset owners. The mobile app segment dominates transaction volume due to native push notifications and wallet integration, while the fleet management software category captures premium margin pools through multi-vehicle routing optimization and consolidated billing. IoT integration represents the fastest-expanding technology dimension as sensor networks eliminate manual space-status updates, though GPS tracking remains the baseline infrastructure layer across all deployments.
The EU Green Deal's urban mobility framework, alongside GDPR data-handling requirements and local municipal procurement standards, shapes product architecture and market access conditions for platform vendors. FCC guidelines on location-service accuracy influence US deployment specifications, while BIS data-localization norms affect cloud architecture decisions in India. Stakeholders must monitor how evolving smart-city procurement mandates redistribute contract authority between transportation agencies and private parking asset managers.
Market Dynamics
Municipal procurement fragmentation is restructuring how parking finder platforms secure recurring revenue, as transportation departments in Berlin, Munich, and Amsterdam consolidate vendor selection under smart-city frameworks that privilege IoT-native architectures over legacy GPS-only systems.
Growth Catalysts
- EU Green Deal urban mobility directives:European cities face binding congestion-reduction targets that mandate real-time parking data integration into multimodal transport platforms, accelerating municipal procurement cycles for sensor-enabled management systems.
- Fleet electrification mandates:Commercial vehicle operators across Germany and the Netherlands require parking applications that reserve charging-capable spaces, expanding addressable market beyond traditional garage inventory.
- Sensor network densification:Low-power wide-area networks in Barcelona and Copenhagen enable sub-minute space-status updates, eliminating manual verification costs for asset owners and improving utilization metrics.
Market Restraints
- GDPR data-localization compliance costs:Cross-border cloud architectures face mandatory EU data-residency requirements that fragment platform infrastructure and inflate operational overhead for multi-country deployments.
- Street-level regulation heterogeneity:Parking rule variations across municipal boundaries force vendors to maintain expensive localized content teams rather than deploying standardized software modules.
- Garage operator consolidation resistance:Independent asset owners in Southern Europe refuse API access to pricing data, limiting coverage depth in high-demand urban corridors.
Strategic Opportunities
- Curbside management integration:Loading zone and passenger pickup reservation modules address municipal revenue leakage from commercial vehicle dwell time, opening new subscription tiers for logistics operators.
- Dynamic pricing algorithm exports:Yield management tools developed for airport and stadium parking apply directly to emerging micromobility docking networks in Paris and Milan.
- White-label municipal deployments:City-branded applications in Stockholm and Vienna demonstrate path to exclusive provider status through deep ERP integration with transportation authority billing systems.
Industry Challenges
- Legacy payment gateway fragmentation:Municipal procurement specifications mandate support for region-specific wallet standards that delay product launches and inflate QA cycles.
- Sensor calibration talent scarcity:Deployment velocity depends on field technicians capable of optimizing magnetic and camera-based detection systems, with certification programs lagging demand in Eastern European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parking Finder Apps Market |
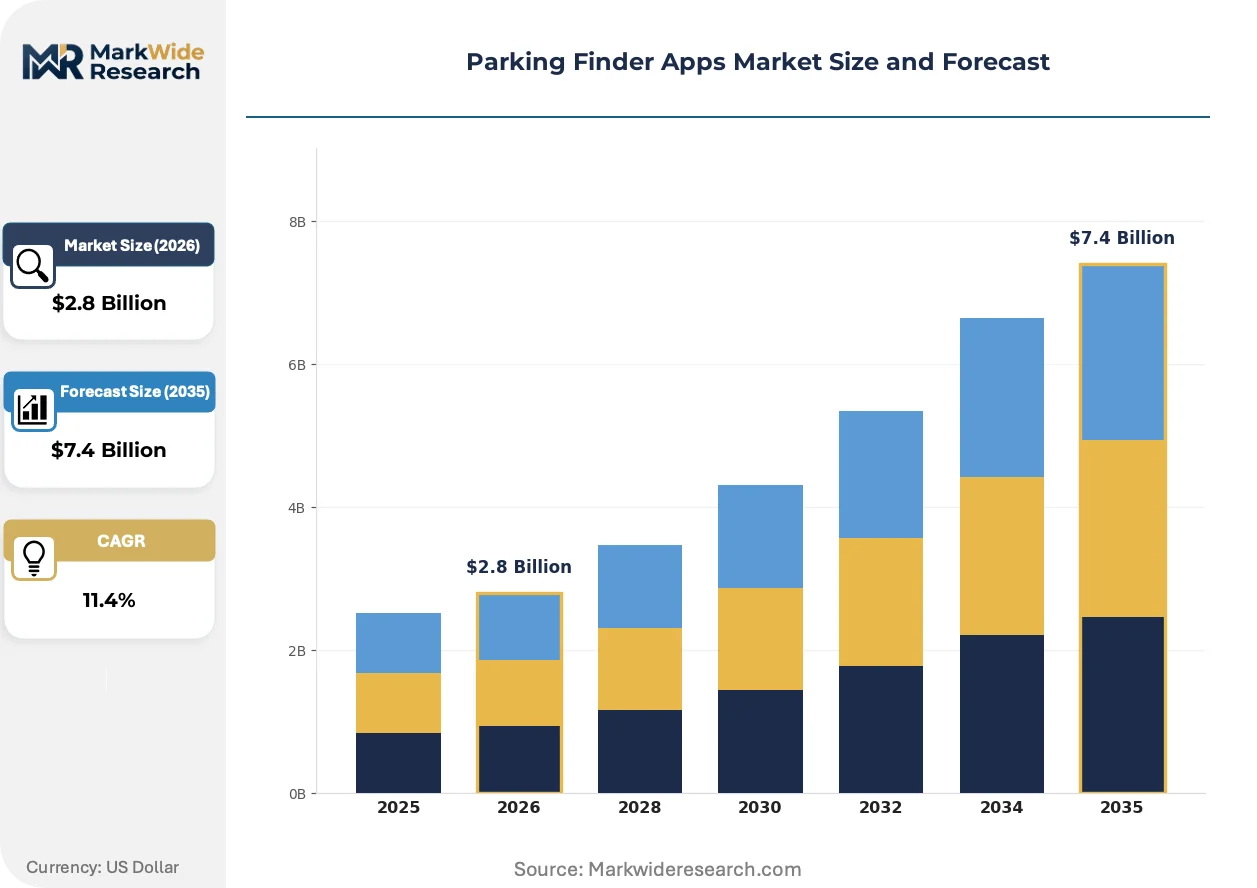
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Mobile App, Web App, Fleet Management Software, Integrated Systems User Type: Individual Users, Corporate Clients, Municipalities, Transportation Services Technology: GPS Tracking, Cloud Computing, IoT Integration, Machine Learning Payment Model: Subscription-Based, Pay-Per-Use, Freemium, One-Time Payment |
| Companies Covered | ParkWhiz, Parkopedia Parking, SpotHero, SpotAngels, Parking Panda, ParkMobile, ParkMe, Parkt, BestParking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parking Finder Apps Market Evolving Landscape
Edge-computing architectures and computer vision deployments are compressing the latency between space vacancy detection and consumer notification, eliminating the manual verification bottleneck that has constrained dynamic pricing granularity.
Computer vision is rewriting how parking assets report real-time availability. Municipal operators in Rotterdam and Hamburg deploy camera-based detection systems that classify vehicle occupancy without embedded ground sensors. The technology enables sub-minute pricing adjustments based on block-level demand patterns, compressing revenue leakage from underpriced peak inventory.
GDPR Article 25 data-protection-by-design mandates force vendors to rearchitect cloud storage with EU-resident processing nodes. The regulation elevates compliance costs for multi-territory platforms while creating competitive moats for European-native providers with established data-residency infrastructure. German transportation authorities now embed privacy certification requirements directly into smart-city procurement scoring matrices.
Subscription-based fleet management contracts displace per-transaction pricing for commercial vehicle operators. Logistics coordinators in the Netherlands and Belgium negotiate consolidated billing across multi-vehicle routing platforms, unbundling parking reservations from fuel and toll reconciliation services. The shift compresses vendor margins on individual transactions while extending contract duration and switching costs.
Parking Finder Apps Market Segmentation
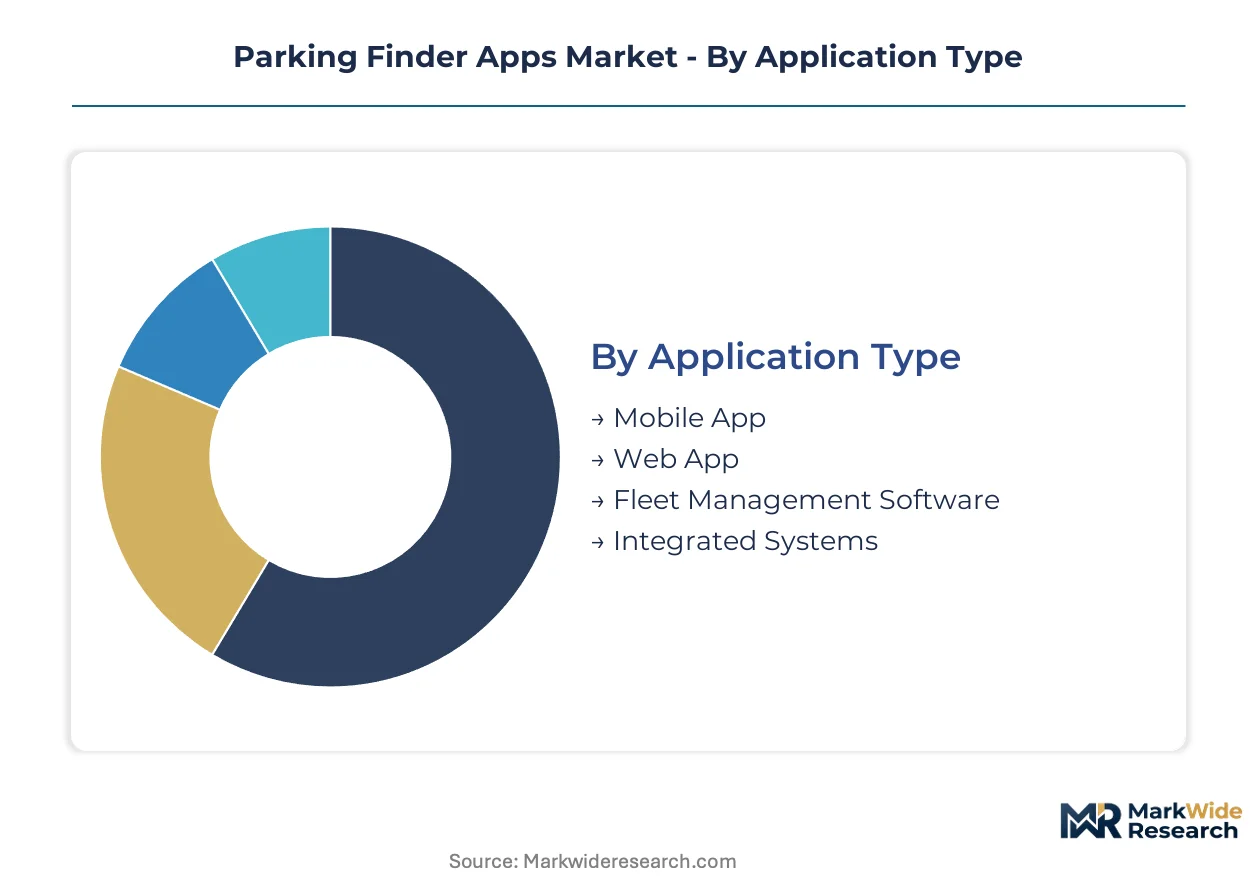
Parking finder platforms fragment across four distinct dimensions that reshape vendor architecture and monetization strategy. Application type determines infrastructure investment priorities, while payment model governs customer lifetime value calculations. Technology stack and user type further differentiate competitive positioning across urban deployment contexts.
Application Type:
Buyers select platforms based on integration depth with existing mobility workflows and hardware ecosystems.
- Mobile App:Native iOS and Android applications leverage GPS positioning, push notifications, and digital wallet integration to minimize friction in on-street parking discovery. Demand concentrates among individual commuters in Berlin and Munich where real-time space availability reduces search time in dense commercial districts.
- Fleet Management Software:Multi-vehicle routing platforms consolidate parking reservations with toll reconciliation and charging station scheduling for logistics operators. German and Dutch commercial vehicle fleets drive procurement as electrification mandates require guaranteed access to charging-capable spaces.
- Web App:Browser-based interfaces serve occasional users and enterprise procurement teams managing centralized billing across distributed vehicle pools.
- Integrated Systems:ERP-connected platforms embed parking data directly into municipal transportation authority dashboards and smart city command centers.
Mobile App leads on scale; Fleet Management Software leads on momentum.
User Type:
Procurement authority varies sharply across customer categories, with municipalities commanding longest contract durations and strictest technical specifications.
- Municipalities:Transportation departments in Amsterdam, Copenhagen, and Vienna issue multi-year smart city tenders that mandate IoT sensor compatibility, GDPR-compliant data residency, and open API architectures for multimodal platform integration. EU Green Deal congestion targets accelerate procurement cycles.
- Corporate Clients:Fleet operators and commercial real estate managers negotiate volume-based pricing for centralized parking inventory across distributed office locations. Dutch logistics coordinators prioritize consolidated billing features that unbundle parking from fuel and toll reconciliation.
- Individual Users:Occasional parkers select platforms based on coverage density and transaction fee transparency.
- Transportation Services:Ride-hail and car-share operators require dynamic pricing APIs and guaranteed space reservations for high-turnover commercial zones.
Municipalities anchor contract value; Corporate Clients expand most quickly.
Technology:
Platform selection increasingly hinges on latency requirements and data sovereignty constraints rather than baseline location accuracy.
- IoT Integration:Magnetic sensors, camera-based detection, and low-power wide-area networks enable sub-minute vacancy updates that support dynamic pricing algorithms. Barcelona and Rotterdam deployments demonstrate revenue gains from eliminating manual space-status verification.
- Machine Learning:Predictive demand models forecast peak occupancy patterns and optimize pricing recommendations for asset owners. German airport and stadium operators deploy yield management tools that adapt directly to micromobility docking networks.
- GPS Tracking:Satellite positioning remains the baseline infrastructure layer for consumer-facing space discovery across all deployment scales.
- Cloud Computing:Distributed processing architectures face mandatory EU data-residency requirements under GDPR Article 25 that fragment infrastructure and elevate compliance costs.
IoT Integration commands premium pricing; Machine Learning gains share fastest.
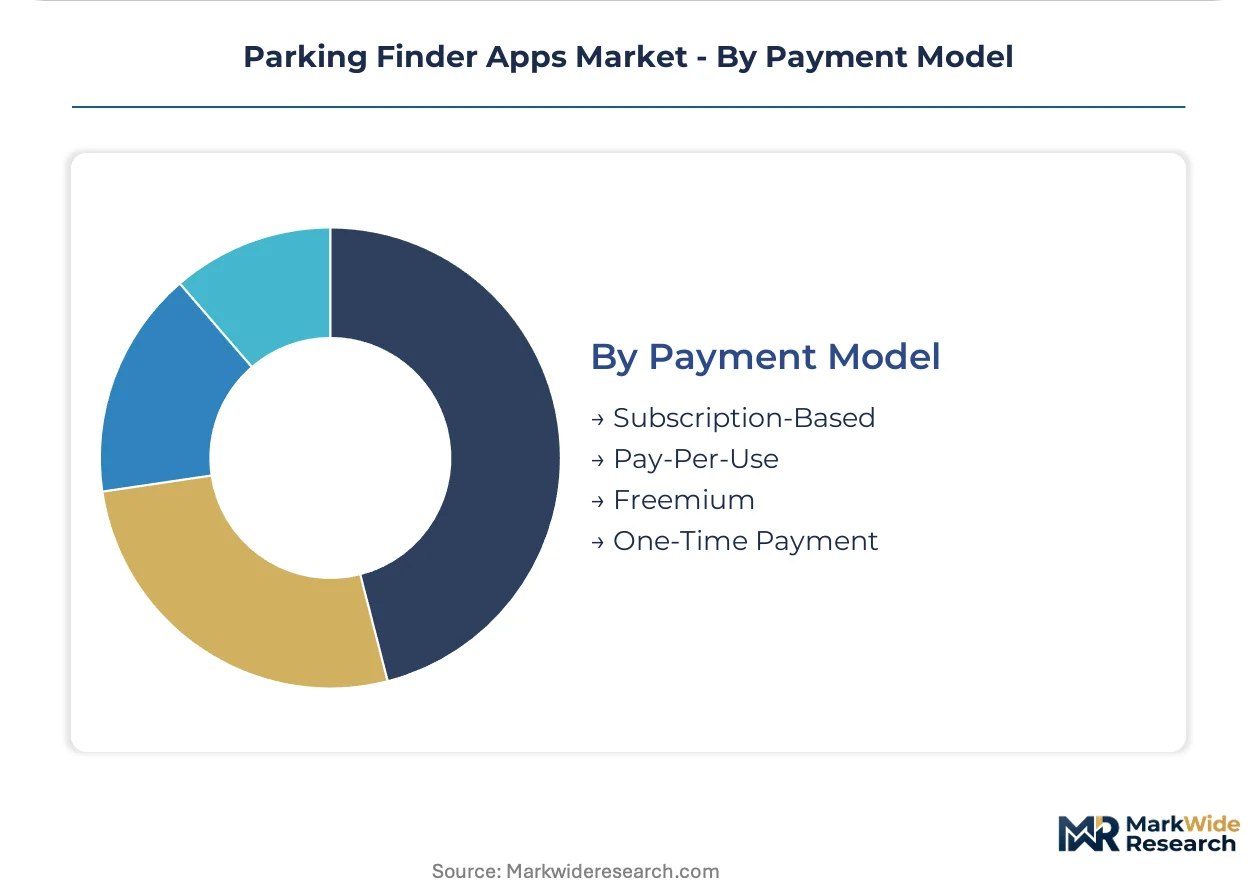
Payment Model:
Revenue predictability and customer acquisition cost tradeoffs dominate model selection for platform operators.
- Subscription-Based:Monthly and annual contracts for fleet operators and municipal white-label deployments extend duration and switching costs while compressing per-transaction margins. Stockholm and Vienna city-branded applications demonstrate path to exclusive provider status.
- Pay-Per-Use:Per-reservation fees align revenue with transaction volume for occasional individual users.
- Freemium:Basic discovery features with premium upgrades for reservation guarantees and dynamic pricing alerts.
- One-Time Payment:Perpetual licenses for integrated ERP deployments in transportation authority billing systems.
Subscription-Based locks in recurring revenue; Pay-Per-Use scales with transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in smart-city parking procurement velocity, while the Netherlands compresses deployment timelines through centralized municipal frameworks. National regulatory architectures and urban density patterns reshape vendor prioritization across European markets.
Germany
Berlin and Munich drive demand through billion-euro smart-city investments targeting congestion reduction. EU Green Deal urban mobility directives bind municipalities to real-time parking data integration, accelerating tender cycles. Bavaria's sensor network deployments in Munich demonstrate sub-minute vacancy detection at scale.
Netherlands
Amsterdam and Rotterdam prioritize curbside management platforms that monetize loading zones and passenger pickup dwell time. GDPR Article 25 data-residency requirements elevate compliance costs for foreign vendors. Randstad logistics corridors deploy fleet management contracts that consolidate parking with toll and charging reconciliation.
France
Paris and Lyon anchor procurement through multimodal transport platform mandates under national decarbonization targets. CNIL privacy certifications embed directly into municipal scoring matrices. Île-de-France micromobility docking networks import yield management algorithms originally developed for airport parking.
United Kingdom
London transportation authorities issue white-label tenders that privilege ERP integration with legacy billing systems. Post-Brexit data localization debates fragment cloud architecture decisions. Greater Manchester's sensor calibration programs address technician scarcity through vendor-funded certification pipelines.
Spain
Barcelona's low-power wide-area networks enable dynamic pricing granularity unmatched in Southern Europe. Independent garage operators in Madrid resist API access, constraining coverage depth. Catalan municipal procurement specifications mandate open architectures that prevent vendor lock-in.
Parking Finder Apps Market Competitive Landscape
North American platforms anchor the transaction-volume tier; European specialists hold the regulatory-compliance and data-granularity positions. Market structure fragments across three distinct layers: white-label municipal deployments, direct garage operator partnerships, and fleet management consolidators. Dominant competitive moves include sensor network densification partnerships and dynamic pricing algorithm licensing to adjacent mobility verticals.
Within the direct garage partnership tier, SpotHero and ParkMobile occupy positions that emphasize pricing control and transaction scale respectively. Parkopedia Parking sits within the regulatory-granularity archetype, leveraging street-level coverage depth across European capitals. These three entities exemplify how geographic origin and partnership architecture determine competitive moat durability.
| Leading Market Players |
|---|
| ParkWhiz |
| Parkopedia Parking |
| SpotHero |
| SpotAngels |
| Parking Panda |
| ParkMobile |
| ParkMe |
| Parkt |
| BestParking |
| Others |
Value Network & Pricing Analysis
Municipal transportation departments in Germany and the Netherlands concentrate procurement authority under smart-city frameworks, locking in subscription-based SaaS pricing for IoT-native parking platforms while compressing per-transaction margins for legacy GPS-only providers.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for sensor-enabled parking management systems. Three-tier pricing structure across premium, standard, and economy levels separates municipal white-label deployments from fleet management consolidators and individual pay-per-use transactions. Price differentiation rests on GDPR certification grade and ERP integration depth. Cost compression in the mid-market tier is intensifying because Randstad logistics coordinators negotiate consolidated billing unbundling parking from toll reconciliation. Individual users show highest price sensitivity; municipal buyers demonstrate lowest sensitivity due to multi-year contract lock-in.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Spain anchor hardware procurement for sensor network deployments. Component sourcing draws from Chinese magnetic sensor manufacturers, Taiwanese edge-computing chip suppliers, and German camera-based detection system integrators. Single-source vulnerability concentrates in low-power wide-area network module supply. Distribution runs through municipal procurement frameworks that mandate EU-resident cloud processing nodes under GDPR Article 25.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
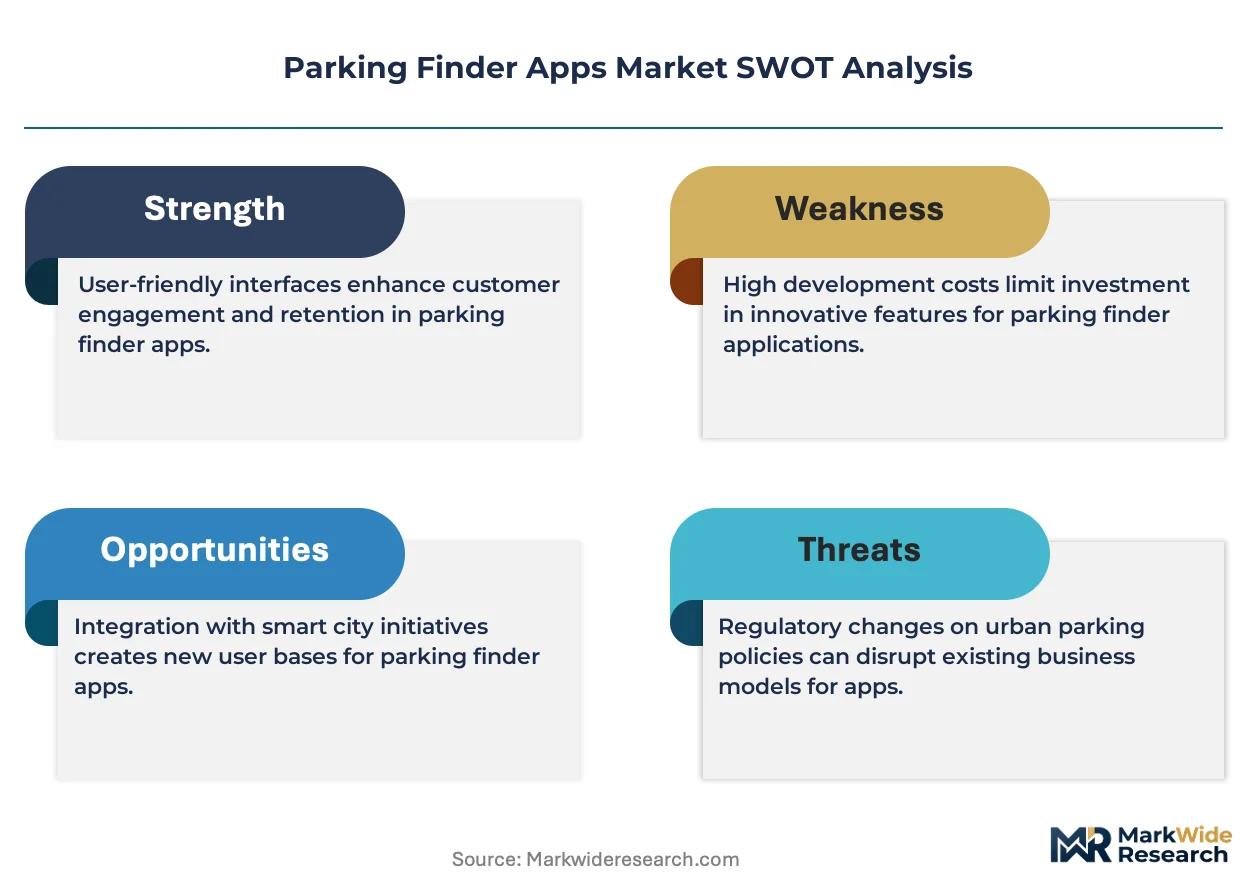
The parking finder apps market compounds steadily as EU Green Deal urban mobility directives bind municipalities to real-time data integration, creating recurring revenue visibility for compliant vendors.
For Market Incumbents: Hedge against margin erosion in the pay-per-use tier by deepening ERP integration with transportation authority billing systems in Stockholm and Vienna. Prioritize sensor network densification partnerships in Barcelona and Copenhagen to sustain dynamic pricing algorithm premiums. Counter emerging white-label municipal competitors through exclusive data-sharing agreements with commercial garage operators.
For New Entrants and Emerging Players: Enter via curbside management modules targeting loading zone and passenger pickup reservation demand in Amsterdam and Rotterdam. White-label municipal deployments in Eastern European markets offer lowest competitive density. Lead with GDPR data-residency infrastructure to satisfy procurement scoring matrices in German smart-city tenders.
For Investors and Strategic Acquirers: Fleet management software consolidators are the most active acquirer in this space, driven by electrification mandates requiring charging-capable space guarantees. Long-term viability favors platforms with established IoT sensor calibration capabilities and municipal white-label reference contracts. Watch for inflection when sensor network deployment velocity outpaces technician certification program expansion in target markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Network Densification Partnership | Barcelona and Hamburg deployments demonstrate sub-minute vacancy detection revenue gains. |
| Dynamic Pricing Algorithm Licensing | Yield management tools from German airport parking apply directly to Paris micromobility networks. |
| White-Label Municipal Deployment | Stockholm and Vienna city-branded applications secure exclusive provider status through ERP integration. |
| GDPR Data-Residency Infrastructure Investment | EU-resident processing nodes satisfy Article 25 mandates embedded in procurement scoring matrices. |
| Fleet Management Consolidation | Dutch logistics coordinators negotiate multi-vehicle routing contracts extending duration and switching costs. |
Research Methodology
Direct dialogue with municipal transportation procurement officers, smart city program directors, commercial garage operators, fleet management coordinators, and parking platform product managers combined with secondary validation from EU tender databases, GDPR compliance registries, SEC filings of listed mobility platforms, and smart city investment disclosures. Bottom-up and top-down triangulation cross-checked transaction volume estimates against sensor network deployment counts and municipal contract award values.
Bottom-up modeling aggregated individual country-level procurement cycles while top-down analysis calibrated aggregate market expansion against EU Green Deal implementation timelines across the analysis window. Segmentation dimensions included application type, user category, technology stack, and payment model, with IoT integration penetration and fleet electrification mandate progression as industry-specific forecast inputs. CAGRs derived from weighted average of historical tender cycle acceleration and projected sensor network densification curves.
The model holds under continued EU Green Deal enforcement and stable municipal procurement budget allocation; deviation in national data-localization regulation stringency or garage operator API access willingness would shift vendor market share distribution. Forecasts reflect documented assumptions regarding smart-city investment continuity and sensor calibration talent pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Scooter Sharing Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
E-Scooter Sharing Market