
 Smart Fleet-On-Board Devices Market | 2026-2036
Smart Fleet-On-Board Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fleet-On-Board Devices Market Outlook
Automotive-grade telematics certification is bifurcating the competitive landscape into fleet-validated suppliers and consumer-electronics entrants. Geotab sustains its position through deep backward integration into cloud analytics infrastructure for commercial vehicle fleets. Samsara differentiates by occupying the integrated video-telematics layer with AI-enabled dashcam platforms. Cubic Transportation Systems Limited anchors its presence in government transit fleets through specialized on-board validators and passenger information systems.
Smart fleet-on-board devices comprise embedded computing modules, sensors, and communication hardware installed in commercial vehicles to capture real-time operational data including GPS coordinates, engine diagnostics, accelerometer readings, and driver behavior metrics. These systems transmit information via cellular or satellite networks to centralized fleet management platforms, enabling route optimization, predictive maintenance scheduling, and regulatory compliance automation. Telematics units lead product category adoption due to their role as the central data aggregation hub, while IoT sensors represent the fastest-expanding segment as fleets add tire pressure, cargo condition, and environmental monitoring endpoints. GPS technology dominates the connectivity layer for location services, though cellular modules are displacing older radio-frequency systems as 5G network coverage expands along major freight corridors.
The Federal Motor Carrier Safety Administration's electronic logging device mandate continues to shape baseline demand across the United States by requiring hours-of-service tracking in interstate commerce. The National Highway Traffic Safety Administration's crash avoidance standards and the Environmental Protection Agency's Phase 3 greenhouse gas rules for heavy-duty vehicles are pushing manufacturers to integrate more sophisticated on-board diagnostics and emissions monitoring capabilities. Stakeholders must monitor how emerging cybersecurity frameworks from the National Institute of Standards and Technology reshape device authentication requirements and data transmission protocols before committing to long-term hardware refresh cycles.
Market Dynamics
Cellular module consolidation is compressing hardware margins while forcing fleet operators to renegotiate connectivity contracts as 5G coverage expands along interstate freight corridors. This infrastructure shift is redistributing value from device manufacturers toward network operators and cloud analytics platforms.
Growth Catalysts
- FMCSA electronic logging device mandate:Hours-of-service tracking requirements sustain baseline replacement demand across interstate freight carriers in the United States.
- EPA Phase 3 greenhouse gas rules:Heavy-duty vehicle emissions monitoring obligations are expanding sensor integration requirements for on-board diagnostic systems.
- Video-telematics convergence:AI-enabled dashcam platforms are pulling fleet safety budgets toward integrated hardware-software bundles.
Market Restraints
- Semiconductor input volatility:Automotive-grade GPS and cellular chip supply remains concentrated among Taiwanese foundry operators.
- Cybersecurity compliance friction:NIST framework authentication requirements are extending hardware refresh timelines for budget-constrained municipal fleets.
- Radio-frequency substitution:Legacy satellite messaging systems face displacement by cellular networks in lower-latency applications.
Strategic Opportunities
- Underpenetrated cold-chain monitoring:Pharmaceutical and food logistics fleets in India represent untapped demand for cargo-condition IoT sensors.
- EU Green Deal alignment:Carbon reporting mandates for commercial transport operators in Germany and France are creating regulatory tailwinds for emissions-tracking hardware.
- Edge-computing convergence:On-board processing modules combining telematics with AI inference engines are opening new service revenue streams.
Industry Challenges
- Embedded systems engineering scarcity:Fleet operators struggle to recruit firmware developers capable of integrating multi-sensor arrays with legacy vehicle CAN bus architectures.
- Automotive-grade certification timelines:AEC-Q100 validation cycles for temperature-hardened components delay product launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fleet-On-Board Devices Market |
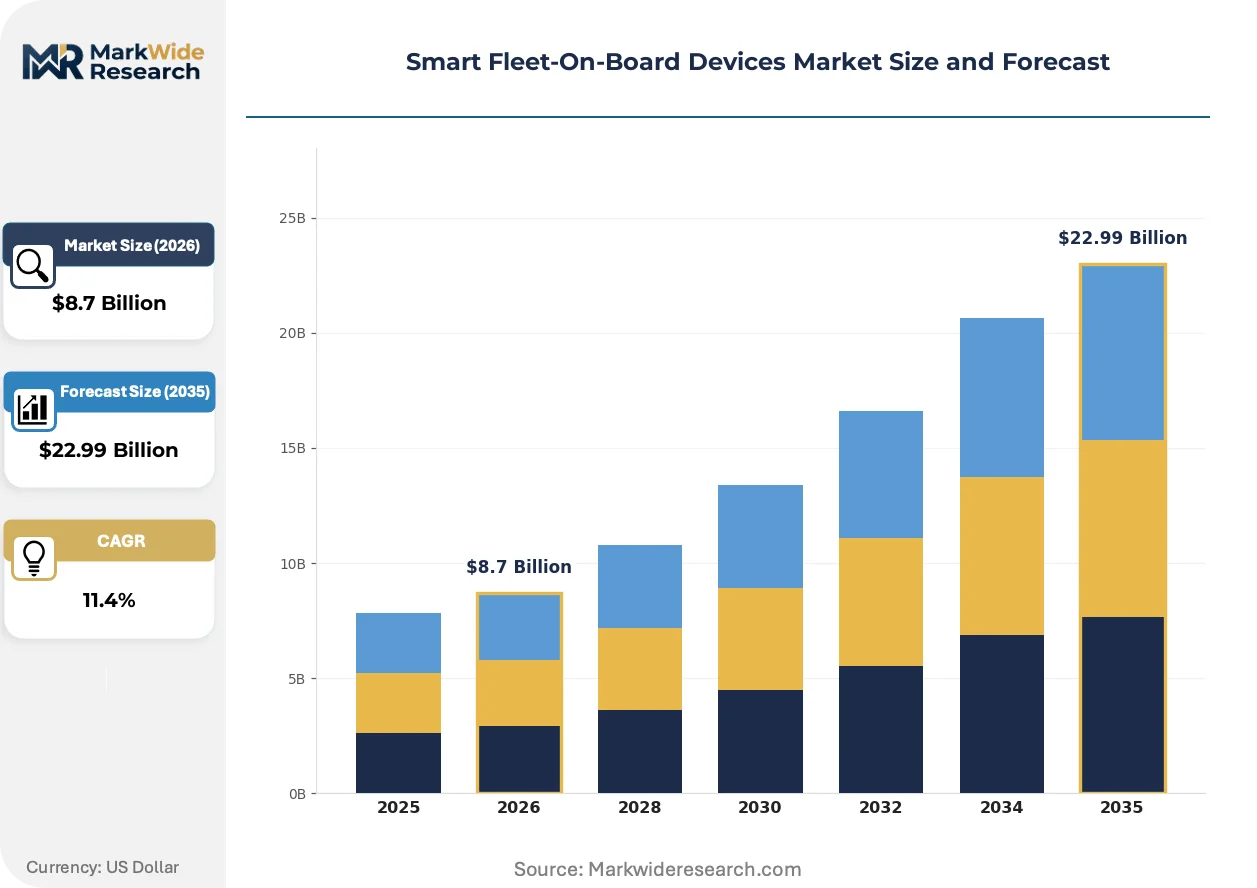
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics Unit, Dashcam, Fleet Management Software, IoT Sensors Technology: GPS, RFID, Cellular, Wi-Fi End User: Logistics Companies, Transportation Providers, Delivery Services, Government Fleets Application: Vehicle Tracking, Driver Behavior Monitoring, Maintenance Management, Fuel Management |
| Companies Covered | Televic N.V., Xerox Corporation, Trapeze Software Inc., Cubic Transportation Systems Limited, Clever Devices Ltd, DILAX Intelcom GmbH, Eurotech, Inc., Geotab, Samsara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fleet-On-Board Devices Market Strategic Shifts
Hardware-software unbundling is fragmenting supplier value chains as fleet buyers separate device procurement from platform subscriptions. This decoupling is accelerating specialization among component vendors and cloud-native service providers.
Edge AI processors are decomposing the traditional telematics unit architecture by enabling real-time inference for driver behavior analysis and collision prediction directly on vehicle-mounted hardware. Regional freight carriers with 50-500 vehicle fleets are adopting these systems fastest to reduce cellular data transmission costs. The shift is compressing margins for pure connectivity providers while expanding addressable market for semiconductor suppliers with automotive thermal specifications.
REACH substance restrictions are forcing component manufacturers to reformulate solder alloys and conformal coatings used in on-board device assemblies. The industrial consequence is extended qualification timelines for European market entry and accelerated supplier audits. Heavy-duty OEMs serving German and French logistics markets are responding by consolidating procurement around pre-certified module vendors with established EU compliance documentation.
Fleet procurement teams are consolidating vendor relationships around integrated platform providers capable of spanning telematics, video, and maintenance scheduling. The distributor channel serving independent operators is losing share to direct OEM partnerships and manufacturer-authorized installation networks. This concentration is most visible in the United States where large for-hire carriers with over 1,000 power units are negotiating enterprise-wide platform contracts with multi-year hardware refresh commitments.
Smart Fleet-On-Board Devices Market Segmentation
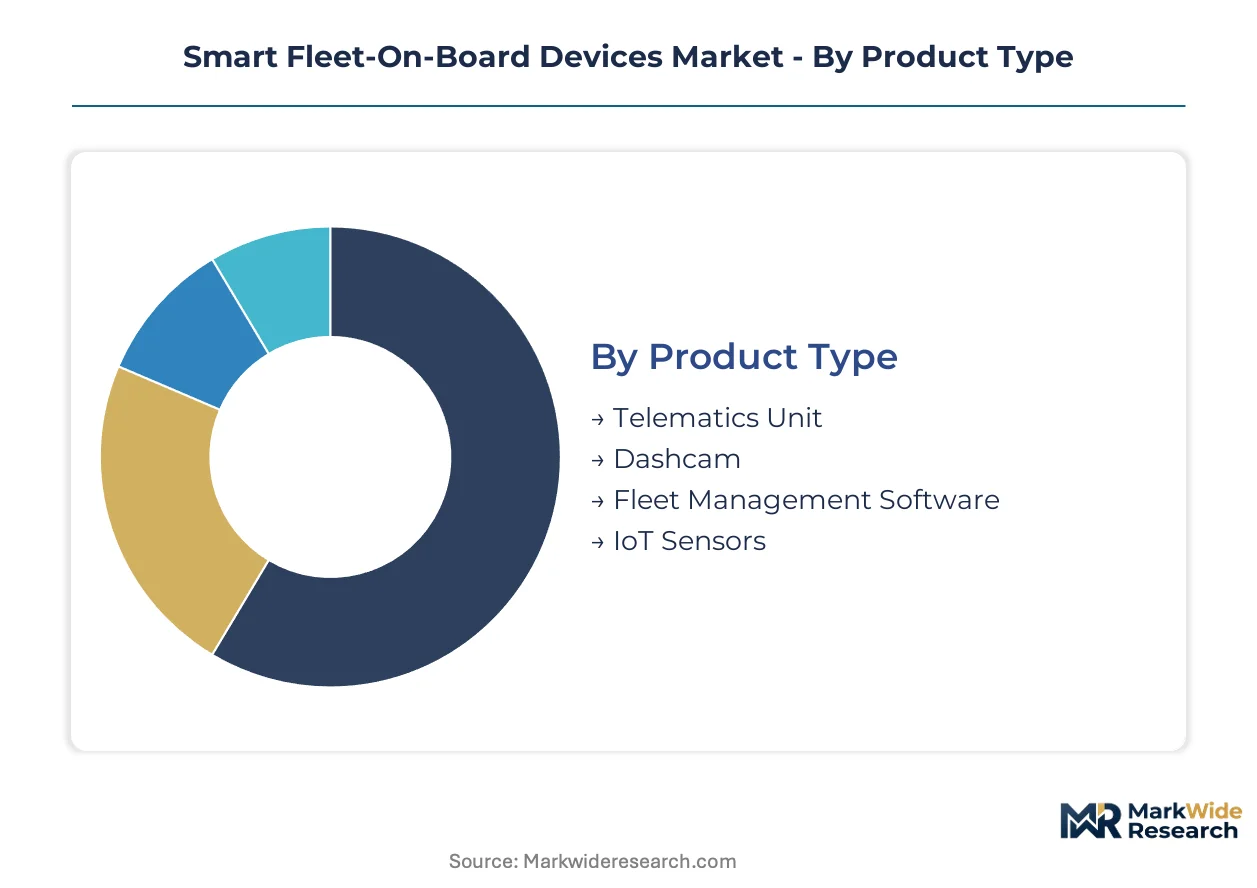
Fleet procurement teams segment on-board device investments by functional priority and integration complexity. Procurement patterns diverge sharply between carriers seeking standalone hardware versus integrated platform bundles.
Product Type:
Telematics units concentrate manufacturing in Taiwan and South Korea for GPS-cellular module integration, while dashcam assembly has shifted to Vietnam and Mexico for cost-sensitive fleet operators. Domestic production of fleet management software dominates in the United States and Germany where cloud infrastructure investments anchor development.
- Telematics Unit:Embedded computing modules aggregate GPS coordinates, engine diagnostics, and accelerometer data through hardened vehicle-mounted hardware. Demand concentrates among United States interstate freight carriers facing FMCSA electronic logging device compliance deadlines, with replacement cycles accelerating as 5G modules displace legacy cellular radios.
- Dashcam:AI-enabled video capture systems integrate driver-facing and road-facing cameras with edge inference processors for real-time safety alerts. Adoption is climbing fastest among regional United States carriers with 50-500 vehicle fleets seeking insurance premium reductions through documented incident footage.
- Fleet Management Software:Cloud-native platforms ingest telematics streams for route optimization and predictive maintenance scheduling.
- IoT Sensors:Tire pressure, cargo condition, and environmental monitoring endpoints expand data granularity beyond core telematics.
Telematics units hold the largest share; momentum sits with IoT sensors.
Technology:
Cost tiers separate precision-grade GPS receivers from commodity cellular modules, with RFID occupying a narrowing middle band in asset-tracking applications.
- GPS:Multi-constellation receivers leveraging United States NAVSTAR, European Galileo, and Russian GLONASS satellite networks deliver meter-level positioning accuracy for geofencing and route compliance. United States long-haul carriers mandate dual-frequency units for tunnel and urban canyon performance, driving specification upgrades across replacement cycles.
- Cellular:LTE-M and 5G modules displace older radio-frequency systems as network coverage expands along interstate freight corridors. German and French logistics operators are prioritizing cellular-over-satellite architectures to reduce latency in emissions reporting applications mandated by EU Green Deal alignment.
- RFID:Passive and active radio-frequency identification supports yard management and trailer tracking in closed-loop depot operations.
- Wi-Fi:Short-range connectivity enables high-bandwidth data offload at fleet terminals and maintenance facilities.
GPS dominates installed base; cellular modules are climbing the fastest.
End User:
Application requirements vary by fleet scale, with government operators prioritizing cybersecurity certification and commercial carriers emphasizing total cost of ownership.
- Logistics Companies:Third-party freight carriers operating 1,000-plus power units negotiate enterprise-wide platform contracts with multi-year hardware refresh commitments. United States for-hire trucking fleets anchor procurement volume as electronic logging device mandate enforcement eliminates non-compliant operators from interstate commerce.
- Transportation Providers:Bus and motorcoach operators integrate passenger information systems with on-board validators for fare collection and real-time arrival displays. Cubic Transportation Systems Limited anchors government transit fleet deployments through specialized hardware meeting municipal procurement specifications.
- Delivery Services:Last-mile parcel carriers optimize stop sequencing and proof-of-delivery capture through compact telematics units.
- Government Fleets:Municipal and federal vehicle pools face extended hardware refresh timelines due to NIST cybersecurity framework compliance friction and budget constraints.
Logistics companies hold the largest share; delivery services are gaining share fastest.
Application:
Maturity curves separate regulatory-mandated tracking from discretionary safety and efficiency investments.
- Vehicle Tracking:Real-time location monitoring constitutes the baseline functionality required for hours-of-service compliance and asset recovery. United States interstate carriers treat GPS tracking as non-negotiable infrastructure following FMCSA mandate implementation, with specification emphasis shifting toward breadcrumb frequency and geofencing precision.
- Driver Behavior Monitoring:Accelerometer-based harsh event detection and AI-enabled video analysis identify risky patterns for coaching intervention. Samsara occupies the integrated video-telematics layer as fleet safety budgets consolidate around hardware-software bundles replacing standalone dashcam deployments.
- Maintenance Management:Predictive algorithms process engine diagnostic codes and sensor trends to schedule service before component failure.
- Fuel Management:Consumption monitoring and idle-time tracking target operating cost reduction in thin-margin freight operations.
Vehicle tracking holds the largest share; driver behavior monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in fleet telematics hardware while importing specialized cellular modules from Taiwan and South Korea. Export volumes concentrate in cloud-native fleet management platforms serving Canadian and Mexican cross-border operators. Import dependency for automotive-grade GPS chipsets creates supply vulnerability during Taiwanese foundry capacity constraints.
United States
Interstate freight carriers with 1,000-plus power units drive replacement demand as FMCSA electronic logging device enforcement eliminates non-compliant operators from commerce. The EPA Phase 3 greenhouse gas rules mandate expanded emissions monitoring capabilities for heavy-duty vehicles. Dallas-Fort Worth anchors procurement volume where enterprise carriers negotiate multi-year platform contracts with integrated hardware-software bundles.
Germany
Logistics operators prioritize cellular-over-satellite architectures to reduce latency in carbon reporting applications mandated by EU Green Deal alignment. The KBA enforces type-approval standards for aftermarket telematics installations in commercial vehicle fleets. The Rhine-Ruhr corridor concentrates deployment activity as freight carriers retrofit existing fleets ahead of 2027 emissions reporting deadlines.
China
Domestic module manufacturers capture share in commercial vehicle telematics as MIIT pushes connected-vehicle standards for heavy-duty trucks. GB standards for vehicle network security reshape device authentication requirements and data transmission protocols. The Yangtze River Delta hosts assembly operations for cost-optimized telematics units serving Southeast Asian export markets.
India
Pharmaceutical and food logistics fleets represent underpenetrated demand for cargo-condition IoT sensors in cold-chain monitoring applications. The PLI scheme for automotive components incentivizes domestic production of vehicle-mounted computing modules. Maharashtra anchors early deployment activity where Mumbai-based third-party logistics operators pilot temperature-tracking endpoints for vaccine distribution networks.
Canada
Cross-border carriers operating into the United States adopt FMCSA-compatible systems to maintain interstate commerce eligibility. Health Canada coordinates with transport regulators on cybersecurity frameworks for connected commercial vehicles. The Greater Toronto Area concentrates procurement decisions for national fleet operators managing transcontinental routes.
Smart Fleet-On-Board Devices Market Competitive Environment
Listed leaders compete with private specialists across cloud analytics infrastructure and integrated video-telematics layers. The vendor base splits between vertically integrated platform providers and component-focused module suppliers. Three archetypes dominate: fleet-validated incumbents with deep backward integration, AI-enabled video specialists, and government transit contractors with municipal procurement relationships. Competitive moves center on hardware-software bundling and direct OEM partnerships displacing traditional distributor channels.
Within the fleet-validated tier, Geotab and Samsara exemplify divergent specialization strategies. Geotab occupies a position anchored in cloud analytics infrastructure for commercial vehicle operators. Samsara represents the integrated video-telematics archetype with AI-enabled safety platforms. Cubic Transportation Systems Limited sits within the government contractor segment, anchoring presence in municipal transit fleets through specialized hardware meeting public procurement specifications.
| Leading Market Players |
|---|
| Televic N.V. |
| Xerox Corporation |
| Trapeze Software Inc. |
| Cubic Transportation Systems Limited |
| Clever Devices Ltd |
| DILAX Intelcom GmbH |
| Eurotech, Inc. |
| Geotab |
| Samsara |
| Others |
Value Chain & Pricing Dynamics
AEC-Q100 automotive-grade certification gates both supplier qualification timelines and price stratification across thermal-hardened component tiers. Fleet operators face extended validation cycles that compress margins for uncertified entrants while allowing validated incumbents to command premium positioning for temperature-resilient modules.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on AEC-Q100 certification grade and volume scale commitments from large for-hire carriers. Cost compression in the economy tier is intensifying because cellular module consolidation forces hardware vendors to absorb connectivity contract renegotiations. Municipal government fleets exhibit highest price sensitivity due to budget-constrained procurement cycles, while enterprise logistics operators with 1,000-plus power units demonstrate lowest sensitivity through multi-year platform bundling.
Supply Chain Analysis
Strategic stockpiling of automotive-grade GPS and cellular chipsets dominates inventory strategy as Taiwanese foundry capacity constraints create procurement uncertainty. Manufacturing concentrates in Taiwan, South Korea, and Vietnam for module integration and dashcam assembly. Raw material dependencies include GPS chipsets, 5G cellular radios, and temperature-hardened solder alloys reformulated for REACH compliance. Single-source vulnerability around Taiwanese semiconductor fabrication poses structural risk. Distribution runs through direct OEM partnerships and manufacturer-authorized installation networks displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—specifically FMCSA mandate compliance—locks in incumbent positions through switching costs that deter fleet operator migration.
For Market Incumbents: Compound cloud analytics infrastructure depth to deepen data moats against AI-enabled video specialists encroaching on the integrated platform layer. Prioritize backward integration into 5G cellular module sourcing to defend margin position against connectivity contract renegotiations. Lock in municipal fleet relationships before NIST cybersecurity framework compliance extends refresh timelines.
For New Entrants and Emerging Players: Differentiate on edge-computing convergence by embedding AI inference engines directly into vehicle-mounted hardware for regional carriers with 50-500 vehicle fleets. Target cold-chain monitoring applications in Indian pharmaceutical logistics as the most penetrable white-space segment. Pursue direct partnerships with heavy-duty OEMs serving German and French markets to bypass consolidated distributor channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet management software platforms lacking integrated video-telematics capabilities. Long-term viability hinges on regulatory mandate durability and 5G infrastructure rollout density. The signal to watch is EPA Phase 3 enforcement stringency as an inflection indicator for emissions-tracking hardware replacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processor Integration | Enables real-time driver behavior inference on vehicle-mounted hardware for cost-sensitive regional fleets. |
| 5G Cellular Module Migration | Displaces legacy radio-frequency systems along interstate freight corridors per carrier connectivity contract demands. |
| REACH-Compliant Component Reformulation | Extends European market entry timelines while consolidating procurement around pre-certified module vendors. |
| Direct OEM Partnership Consolidation | Bypasses distributor channel erosion by embedding hardware-software bundles into vehicle factory installations. |
| Cold-Chain IoT Sensor Expansion | Captures underpenetrated pharmaceutical and food logistics demand in Indian vaccine distribution networks. |
Study Parameters
A spread of perspectives from fleet operations directors, telematics procurement managers, automotive Tier 1 supplier engineers, and cloud platform architects converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FMCSA enforcement disclosures, EPA regulatory filings, SEC 10-K hardware vendor reports, and IHS Markit commercial vehicle production databases. Bottom-up unit shipment modeling triangulated against top-down fleet management software revenue aggregation.
Segmentation dimensions modeled include product type, connectivity technology, fleet scale tier, and application priority across the projection horizon. CAGRs derived from replacement cycle analysis, mandate compliance deadlines, and cellular infrastructure rollout curves. Industry-specific forecast inputs incorporated hours-of-service enforcement intensity and EU Green Deal carbon reporting mandate adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement, stable semiconductor supply, and 5G coverage expansion would require recalibration. Forecasts reflect documented assumptions around mandate implementation schedules and fleet operator technology refresh propensity. Revision becomes warranted when Taiwanese foundry capacity utilization or EPA enforcement stringency crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Smart Roads Market