
 Global Electric Public Transport Market | 2026-2036
Global Electric Public Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Public Transport Market Intelligence
The EU Green Deal, with its ambitious emissions reduction targets for urban mobility, is shifting procurement priorities for transport authorities across Europe. Chinese manufacturers like BYD Company Limited and Yutong Bus Co., Ltd. leverage significant domestic scale to compete on a global stage. Meanwhile, Volvo Group AB differentiates through its focus on integrated e-mobility solutions and safety systems for developed markets.
Electric public transport encompasses vehicles such as buses, trams, and shuttles powered partially or fully by electricity stored in onboard systems. These systems often utilize high-capacity lithium-ion battery packs, requiring charging infrastructure with power ratings from 50kW for plug-in chargers to over 600kW for pantograph-based fast charging. Battery electric buses dominate the vehicle type segment due to operational flexibility and declining battery costs. Within service models, city transit applications represent the largest volume, while airport shuttle services are a high-growth niche.
Regulatory frameworks from China's Ministry of Ecology and Environment (MEE) and the United States Environmental Protection Agency (EPA) set stringent emissions standards that incentivize fleet conversion. In Europe, CE marking conformity assessments ensure that vehicles and charging components meet safety and performance requirements for market access. The key decision for operators now revolves around balancing initial capital outlay for charging infrastructure against long-term total cost of ownership benefits.
Market Dynamics
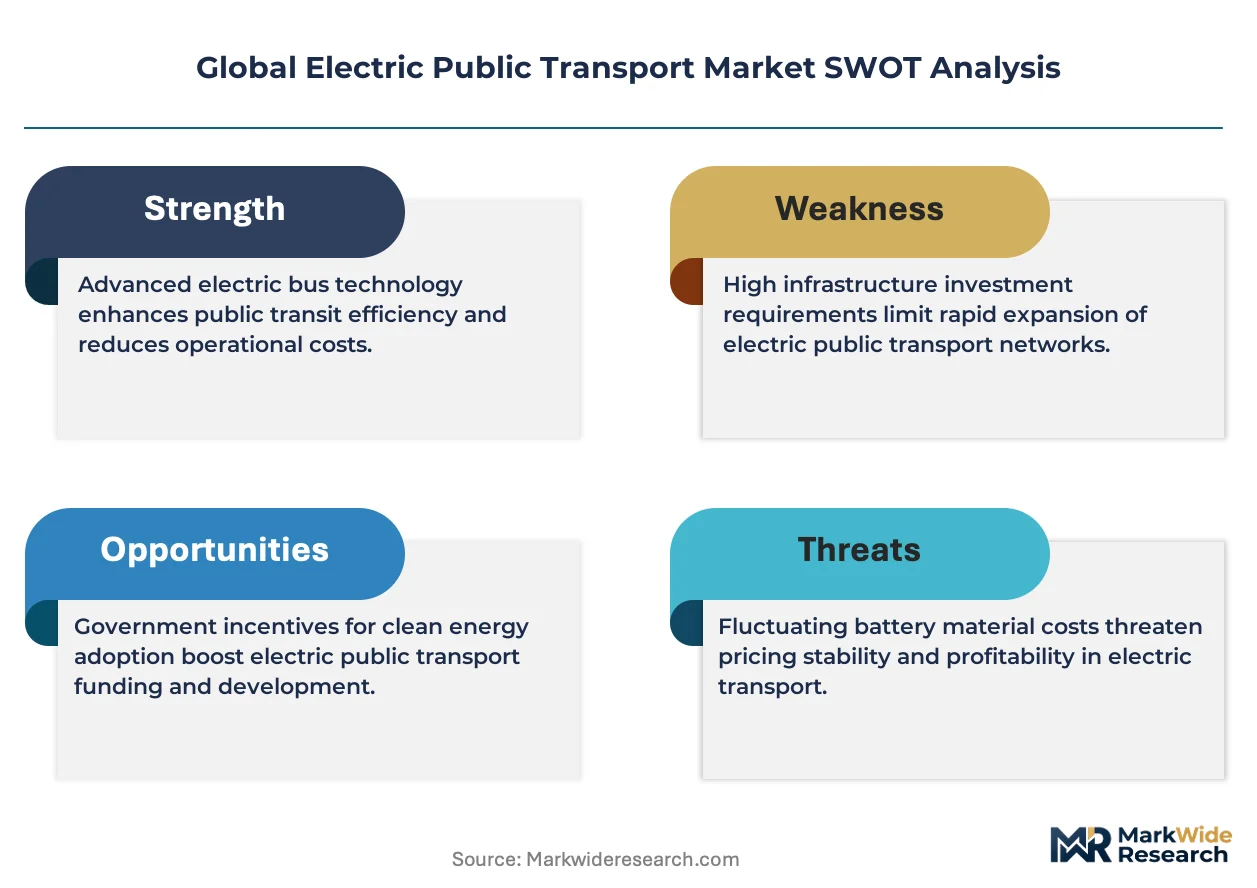
The convergence of stringent urban emission regulations and significant reductions in battery production costs forms the central force shaping the market. This dual pressure compels municipal transport authorities globally to move beyond pilot programs and commit to large-scale fleet electrification.
Growth Catalysts
- Policy Mandates:National and supranational frameworks, including the EU Green Deal and China's dual carbon goals, establish binding targets for zero-emission urban mobility, compelling public transport authorities to accelerate fleet conversion timelines.
- Favorable TCO Economics:Declining lithium-ion battery costs, combined with lower fuel and maintenance expenditures compared to diesel counterparts, are improving the total cost of ownership (TCO) for electric buses, making them economically viable.
- Urban Air Quality Initiatives:Citizen and regulatory pressure to reduce transport-related pollution in megacities like Delhi and Mexico City drives demand for zero tailpipe emission vehicles as a primary public health intervention.
Market Restraints
- Grid Infrastructure Limitations:The deployment of high-power charging for large bus fleets frequently requires costly and time-consuming substation upgrades, with grid capacity constraints acting as a significant bottleneck in many municipalities.
- Battery Raw Material Volatility:Supply chain dependency on geographically concentrated critical minerals such as cobalt and lithium exposes battery manufacturers and vehicle OEMs to significant price volatility and geopolitical supply risks.
- Charging Protocol Fragmentation:A lack of universal standardization between competing charging systems, such as CCS plug-in and pantograph-based opportunity charging, hinders interoperability and complicates long-term infrastructure planning for operators.
Strategic Opportunities
- Vehicle-to-Grid Integration:Developing business models where electric bus fleets provide ancillary grid services, such as frequency regulation, offers a new revenue stream for transport operators and helps utilities manage renewable energy intermittency.
- Electrification in Emerging Economies:Rapidly urbanizing regions in Latin America and Southeast Asia represent major volume opportunities for electric bus adoption, driven by the need to expand public transit capacity while mitigating pollution.
- Dedicated Airport Transit:The conversion of airport shuttle bus fleets is a high-growth niche, as predictable routes and centralized depot charging align perfectly with the operational capabilities of current battery electric vehicle technology.
Industry Challenges
- Specialized Workforce Shortages:A deficit of technicians and maintenance personnel trained to service high-voltage electric drivetrains and battery management systems presents a critical operational challenge for transit agencies transitioning their fleets.
- High Initial Capital Outlay:The substantial upfront investment required for charging infrastructure, including depot modifications and grid connection fees, remains a primary financial hurdle for many public transport operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Public Transport Market |
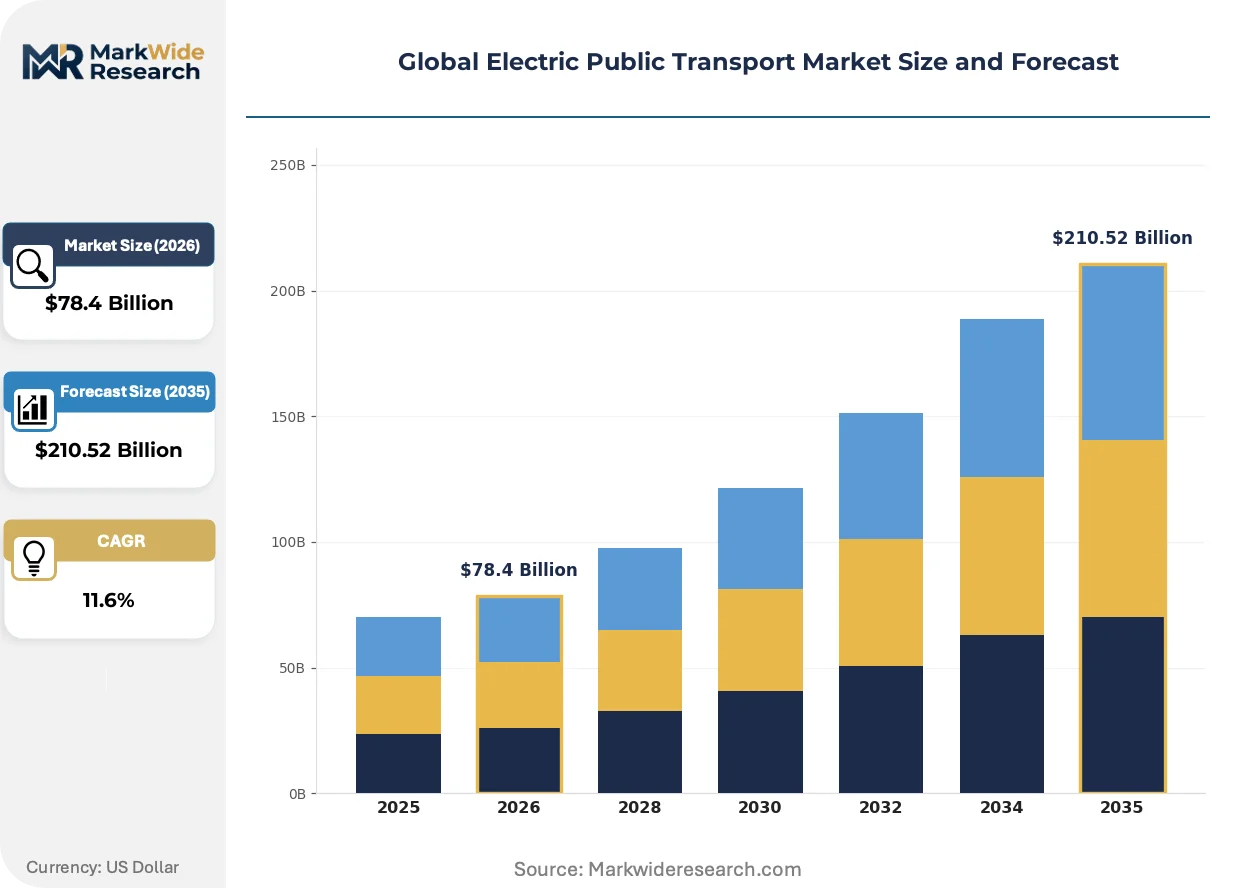
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $210.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Bus, Trolleybus, Hybrid Electric Bus, Electric Tram, Fuel Cell Electric Bus Charging Infrastructure: Overhead Line, Inductive Charging, Fast Charging Station, Wireless Charging Pad, Plug-in Charger Service Model: City Transit, Airport Shuttle, Intercity Transport, University Shuttle, Corporate Commute End User: Municipal Transport Authorities, Private Transit Operators, Universities, Airports, Corporate Fleets |
| Companies Covered | BYD Company Limited, Yutong Bus Co., Ltd., CRRC Electric Vehicle Co., Ltd., Volvo Group AB, Daimler Buses, IVECO Bus, ABB E-Mobility, Tata Motors Ltd., VDL Groep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Public Transport Market Strategic Shifts & Innovations
The market is shifting from a hardware-centric focus on vehicles to a systems-level approach emphasizing operational efficiency. Data analytics and software platforms are becoming integral for managing charging, optimizing routes, and ensuring fleet availability in complex urban environments.
Autonomous Depot Management Systems are a key technological evolution. These platforms use AI to coordinate vehicle movements, charging schedules, and pre-trip diagnostics within the depot. Transit agencies in Europe and China are early adopters, seeking to maximize vehicle uptime. This technology is automating labor-intensive overnight processes, thereby reducing operational costs and improving overall fleet readiness.
Regulatory incentives like the United States Inflation Reduction Act (IRA) are directly influencing procurement decisions. The IRA provides significant tax credits for commercial clean vehicles and charging infrastructure, which accelerates adoption timelines for US-based transit authorities. Domestic bus manufacturers are the primary beneficiaries, as certain provisions favor vehicles with high local content and assembly.
A notable shift in acquisition models involves operators moving toward comprehensive service contracts instead of simple vehicle purchases. This "e-mobility as a service" approach bundles the bus, charging, energy, and maintenance into a single, long-term operational fee, transferring technology and residual value risk to the manufacturer. This trend is most pronounced in European cities where transport authorities prioritize budget predictability.
Global Electric Public Transport Market Segmentation
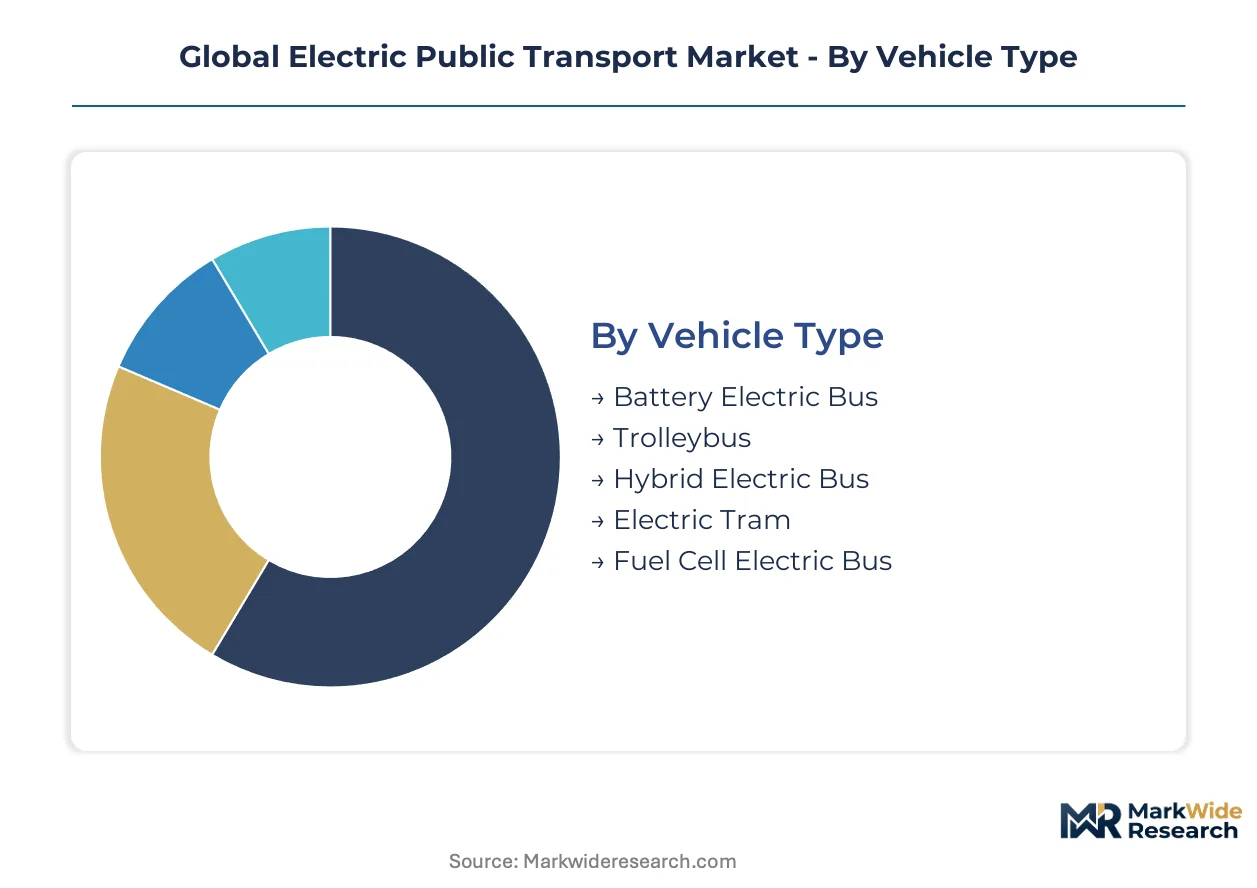
The Global Electric Public Transport Market exhibits diverse segments reflecting varying technological applications, operational requirements, and end-user priorities. Understanding these distinctions helps stakeholders tailor solutions and investment strategies for optimal impact across urban and regional transport networks. This segmentation highlights where demand concentrates and how different solutions address specific public mobility challenges.
Vehicle Type:
Buyers in the vehicle type segment prioritize operational flexibility and route characteristics when selecting electric public transport solutions.
- Battery Electric Bus:Lithium-ion battery packs power these vehicles for zero tailpipe emissions, offering significant environmental benefits. Demand concentrates in major Chinese cities like Shenzhen and Beijing due to strong policy support and declining battery costs.
- Trolleybus:These electric buses draw power from overhead lines, offering continuous operation without battery range concerns in established networks.
- Hybrid Electric Bus:Combining electric motors with internal combustion engines, these buses provide flexibility and reduced emissions for varied routes.
- Electric Tram:Fixed-route urban transport systems running on rails, trams offer high passenger capacity and integrate into city infrastructure.
- Fuel Cell Electric Bus:These vehicles generate electricity from hydrogen, producing only water vapor and offering longer range. Adoption is growing in regions like Europe where hydrogen infrastructure is developing, offering longer range and faster refueling.
Battery Electric Bus leads volumes today; Fuel Cell Electric Bus is gaining share fastest.
Charging Infrastructure:
The cost tier for charging infrastructure varies significantly based on power requirements and installation complexity for electric public transport fleets.
- Overhead Line:This infrastructure provides continuous power to trolleybuses and trams, eliminating the need for onboard batteries for propulsion.
- Inductive Charging:Embedded coils transfer energy wirelessly to vehicles, suitable for fixed routes and quiet urban environments.
- Fast Charging Station:These high-power units, often 600kW for pantograph systems, enable rapid energy replenishment during short stops. Municipal transport authorities in Europe are investing heavily to support opportunity charging for their bus fleets.
- Wireless Charging Pad:These ground-embedded systems offer convenient, cable-free charging for smaller electric shuttles and passenger vehicles.
- Plug-in Charger:Standardized connectors deliver power from 50kW upwards, primarily for overnight depot charging. This infrastructure type is foundational for fleet electrification across developed markets due to its widespread applicability.
Plug-in Charger installations represent the largest volume, while Fast Charging Station deployments pose higher grid integration complexity.
Service Model:
Application dictates the required vehicle capacity and operational cadence for electric public transport service models.
- City Transit:This model involves scheduled routes within urban areas, demanding high passenger capacity and frequent stops. Public transport authorities in cities like London and Paris are electrifying these fleets to meet urban emission targets.
- Airport Shuttle:Operating on predictable routes within airport complexes, these services benefit from centralized charging and consistent schedules. This niche is experiencing rapid conversion to electric vehicles due to environmental commitments from airport operators.
- Intercity Transport:Longer-distance routes connect different urban centers, requiring vehicles with extended range and passenger comfort features.
- University Shuttle:Dedicated transport for university campuses provides frequent, localized service, often with smaller electric bus models.
- Corporate Commute:Businesses offer these services to transport employees, often prioritizing comfort and punctual, eco-friendly travel.
City Transit models demand significant operational flexibility, whereas Airport Shuttle services benefit from highly predictable routes.
End User:
Customer type influences procurement processes and long-term fleet management strategies for electric public transport.
- Municipal Transport Authorities:These government bodies manage public transport networks within cities, driving large-scale fleet electrification programs. Their procurement decisions are heavily influenced by policy mandates like the EU Green Deal and local air quality initiatives.
- Private Transit Operators:Companies contracted by municipalities or other entities manage and operate vehicle fleets, increasingly adopting electric solutions. They often seek "e-mobility as a service" models to mitigate upfront capital outlay for charging infrastructure.
- Universities:Educational institutions operate dedicated shuttle services for students and staff, often prioritizing sustainability in their vehicle choices.
- Airports:Major transportation hubs deploy electric shuttles for passenger and staff movement, aligning with broader environmental goals.
- Corporate Fleets:Businesses use electric vehicles for employee transport and campus circulation, enhancing their corporate social responsibility profiles.
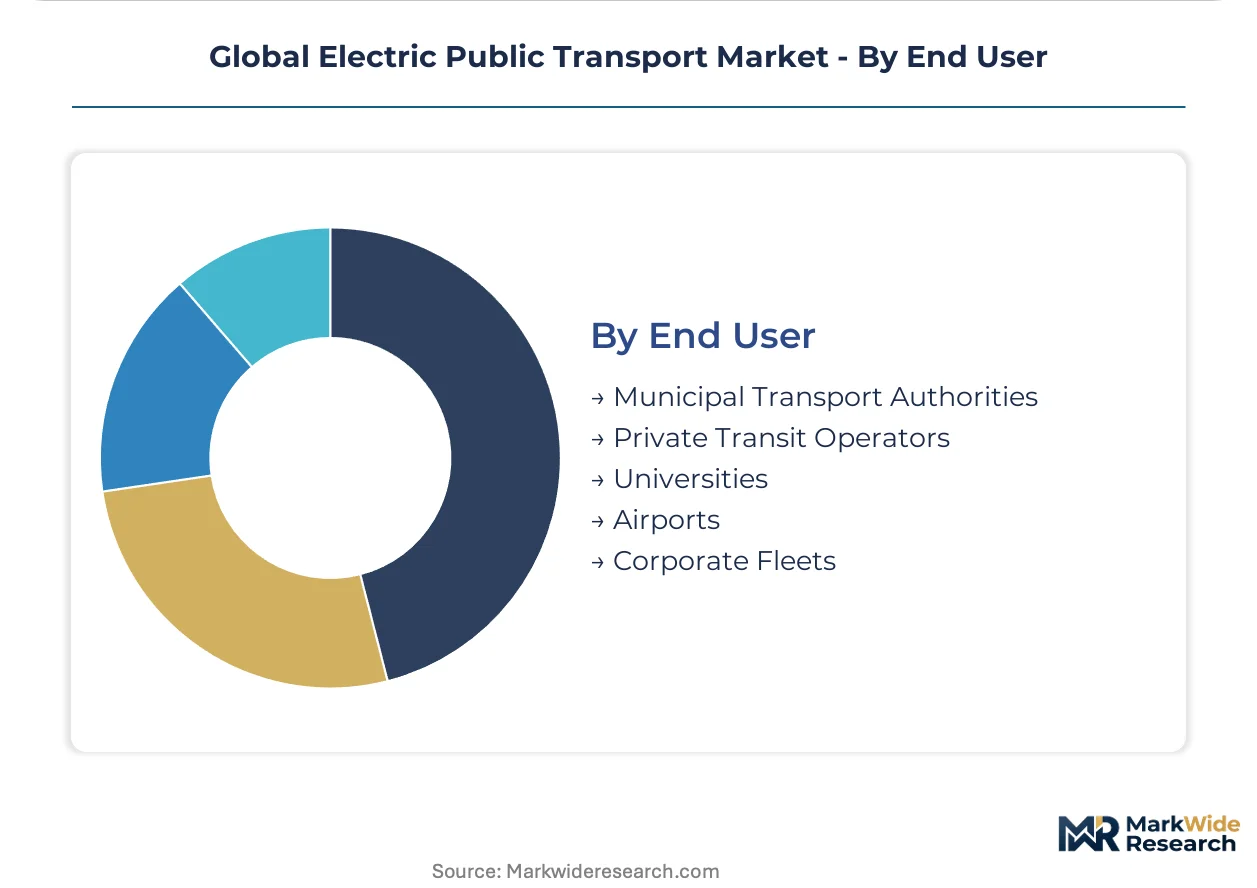
Municipal Transport Authorities are strategically important for market volumes, while Airports represent a high-growth niche for dedicated electrified services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric public transport industry initially scaled in Europe, where early trolleybus networks provided foundational infrastructure for urban mobility. This historical investment now supports new electrification initiatives across major cities. China later became a key manufacturing hub, rapidly accelerating global adoption.
China
China's dual carbon goals significantly drive demand for electric public transport. The Ministry of Ecology and Environment (MEE) sets stringent emissions standards, compelling fleet conversion in major urban centers. Shenzhen exemplifies this trend, operating one of the world's largest fully electric bus fleets.
Germany
Germany prioritizes sustainable urban mobility, fueling demand for advanced electric bus and tram systems. The EU Green Deal mandates ambitious emissions reductions, influencing procurement decisions by German transport authorities. Hamburg is expanding its electric bus fleet, integrating sophisticated charging infrastructure.
United States
The United States is experiencing rising demand for zero-emission transit solutions, particularly in densely populated areas. The Inflation Reduction Act (IRA) provides substantial tax credits for clean commercial vehicles and charging infrastructure, accelerating fleet electrification. California's transit agencies are leading adoption, driven by strong state-level environmental policies.
India
India's rapidly expanding urban centers generate significant demand for efficient and environmentally friendly public transport. National policies, including various FAME (Faster Adoption and Manufacturing of Electric Vehicles) schemes, incentivize electric bus procurement. Delhi is actively converting its bus fleet, aiming to mitigate severe air pollution challenges.
Brazil
Brazil's large metropolitan areas are increasingly seeking electric public transport to address urban congestion and pollution. Local government initiatives and sustainability targets encourage the adoption of electric buses in major cities. São Paulo is a primary focus for electrification efforts, with pilot projects paving the way for larger fleet conversions.
Global Electric Public Transport Market Key Industry Players
Premium-margin players sit above commodity-margin players across the technology and integration dimension. The market exhibits a tiered structure, with established automotive groups alongside specialized electric vehicle manufacturers. Strategic archetypes include full-service e-mobility providers, component specialists, and high-volume vehicle producers. Dominant competitive moves involve strategic partnerships for technology development and geographic expansion into emerging markets.
Among the high-volume vehicle producers, China-based BYD Company Limited and Yutong Bus Co., Ltd. represent significant global scale. Volvo Group AB occupies a position among the established automotive groups, focusing on integrated e-mobility solutions for developed markets. These entities exemplify the diverse approaches to market penetration and technology leadership.
| Leading Market Players |
|---|
| BYD Company Limited |
| Yutong Bus Co., Ltd. |
| CRRC Electric Vehicle Co., Ltd. |
| Volvo Group AB |
| Daimler Buses |
| IVECO Bus |
| ABB E-Mobility |
| Tata Motors Ltd. |
| VDL Groep |
| Others |
Cost & Logistics Intelligence
Municipal Transport Authorities' increasing commitment to fleet electrification is forcing manufacturers to offer comprehensive e-mobility service contracts. This shifts financial risk to suppliers and influences long-term pricing structures.
Pricing Analysis
Long-term service contracts, bundling vehicles, charging, and maintenance, define the dominant pricing model for electric public transport. Price differentiation stems from integrated e-mobility solutions, advanced safety systems, and comprehensive after-sales support. Pricing pressure stems from the substantial initial capital outlay required for charging infrastructure. Municipal Transport Authorities are highly sensitive to upfront costs, while private operators prioritize predictable operational expenditures.
Supply Chain Analysis
Logistics costs significantly impact the delivery of electric public transport components and finished vehicles, particularly for heavy battery packs. Supply concentrates heavily in China for battery production and vehicle assembly, alongside European manufacturers for specialized systems. The market draws from critical minerals like lithium and cobalt, exposing it to raw material volatility and geopolitical supply risks. Distribution runs through direct sales channels to municipal transport authorities and private operators, often involving local service partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric public transport market represents a stable compounder, driven by persistent global mandates for zero-emission urban mobility. Stringent environmental regulations provide a consistent tailwind for fleet electrification programs worldwide.
For Market Incumbents:Anchor existing market share by deepening integrated e-mobility solutions and expanding comprehensive service contracts. This counters fragmentation from specialized EV manufacturers and addresses operator concerns about initial capital outlay. Invest in R&D for advanced battery management systems and AI-driven depot optimization software. Strengthen partnerships with charging infrastructure providers to mitigate grid integration challenges for municipal transport authorities.
For New Entrants and Emerging Players:A price-point gap exists between established premium providers and high-volume commodity offerings, creating opportunities for new players. Target rapidly urbanizing regions in Latin America and Southeast Asia, where public transit capacity needs expansion. Airport shuttle services represent a highly penetrable niche due to predictable routes and centralized charging. Offer comprehensive "e-mobility as a service" models to mitigate upfront capital outlay for operators.
For Investors and Strategic Acquirers:Asymmetric upside sits with component specialists and software providers enabling fleet electrification over the next decade. The market offers long-term viability driven by sustained policy mandates and urban air quality imperatives. Identify acquisition targets with proven expertise in high-power charging solutions or AI-driven fleet optimization platforms. The commercial viability of Vehicle-to-Grid integration projects signals a major inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Charging Infrastructure Partnerships | This accelerates fleet conversion for Municipal Transport Authorities by addressing grid capacity constraints. |
| Invest in Battery Technology R&D | This improves vehicle range and reduces total cost of ownership for public transport operators. |
| Develop AI-driven Fleet Management Software | This optimizes route planning and charging schedules, enhancing operational efficiency for transit agencies. |
| Offer E-mobility as a Service Contracts | This lowers initial capital outlay, making fleet electrification more accessible for private transit operators. |
| Geographic Expansion into Emerging Markets | This captures volume opportunities in rapidly urbanizing regions like Latin America and Southeast Asia. |
Research Approach
Direct dialogue with municipal transport authority directors, fleet managers, charging infrastructure developers, and battery manufacturers grounded this analysis. This primary research combined with secondary validation from MEE reports, EPA emissions standards, and EU Green Deal documents. The study employed a bottom-up approach to segment volumes and a top-down method for market sizing, triangulating data for robust estimation.
A bottom-up analytical framework projected market volumes across the analysis window, while a top-down approach validated total market value. Segmentation dimensions included vehicle type, charging infrastructure, service model, end user, and regional adoption patterns. Compound annual growth rates were derived from historical trends, policy mandates like the EU Green Deal, and technological advancements. Key inputs included battery cost reduction trajectories and grid upgrade timelines.
Caveats apply where battery raw material price volatility, geopolitical shifts, or unforeseen technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and infrastructure development. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
GCC Electronic Toll Collection Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Road Asset Management Software Market