
 Automatic Identification Systems (AIS) Market | 2026-2036
Automatic Identification Systems (AIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Identification Systems (AIS) Market Outlook
Project finance and leasing structures for vessel electronics retrofits is narrowing the competitive field to suppliers with balance-sheet depth. Saab AB leverages its defense contracting relationships to sustain long-term service agreements with Nordic coast guards. Kongsberg Gruppen ASA anchors its position through captive manufacturing of transceiver modules. Garmin Ltd. competes aggressively in the recreational marine segment where price sensitivity favors its consumer-electronics supply chain.
Automatic Identification Systems constitute VHF maritime radio transceivers operating on 161.975 MHz and 162.025 MHz channels, broadcasting vessel identity, position, course, and speed via self-organizing time-division multiple access protocols to prevent collisions and enable shore-side traffic management. Product type segmentation shows transceivers commanding the core value pool while software solutions for fleet analytics represent the fastest-expanding margin category. Application segmentation reveals maritime navigation as the mature installed base whereas freight tracking applications for intermodal containers are gaining traction among logistics providers seeking real-time visibility.
The International Maritime Organization's SOLAS Convention Chapter V mandates AIS carriage for vessels exceeding 300 gross tonnage on international voyages, directly compelling shipping companies into replacement cycles. The US Coast Guard enforces these provisions domestically through NVIC 01-04 and subsequent equipment approvals, while the EU Maritime Safety Agency coordinates cross-border vessel data exchange under its SafeSeaNet infrastructure. Stakeholders must monitor pending spectrum reallocation debates and next-generation VDES standardization timelines that could obsolete current hardware investments.
Market Dynamics
The Automatic Identification Systems market is consolidating around vessel-tracking mandates that compel hardware refresh cycles while spectrum reallocation debates threaten to strand installed transceiver bases before their operational end-of-life.
Growth Catalysts
- SOLAS Convention Chapter V:The International Maritime Organization mandate for AIS carriage on vessels exceeding 300 gross tonnage on international voyages creates replacement demand across commercial fleets.
- Freight tracking applications:Logistics providers deploying AIS-enabled intermodal container visibility systems are expanding addressable market beyond maritime navigation into land-based supply chain orchestration.
- East Asian shipbuilding clusters:South Korean and Japanese newbuild yards concentrate installation demand for Class A transceivers during vessel construction phases.
Market Restraints
- VDES standardization uncertainty:Pending next-generation VHF Data Exchange System timelines create hardware obsolescence risk that freezes capital commitment from risk-averse fleet operators.
- Semiconductor input volatility:Transceiver module production depends on specialized RF component supply chains concentrated in Taiwan and South Korea, exposing margins to foundry capacity constraints.
- Satellite AIS substitution:Space-based vessel detection services from commercial constellation operators are capturing traffic management functions previously requiring shore-based receiver networks.
Strategic Opportunities
- Fleet analytics software:Margin expansion concentrates in predictive maintenance and route optimization platforms layered atop raw AIS data feeds from installed transceiver bases.
- Recreational marine penetration:Class B transceiver adoption among pleasure craft remains underdeveloped in Mediterranean and Caribbean charter markets where collision avoidance awareness is rising.
- EU SafeSeaNet integration:The European Maritime Safety Agency's cross-border vessel data exchange infrastructure creates service contract opportunities for shore-side system integrators.
Industry Challenges
- Legacy system integration:Retrofit installations aboard aging tonnage require bridging protocols between AIS transceivers and existing radar/ECDIS architectures, extending commissioning timelines.
- Type approval certification:US Coast Guard NVIC 01-04 equipment approval processes and subsequent amendments impose documentation burdens that delay product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Identification Systems (AIS) Market |
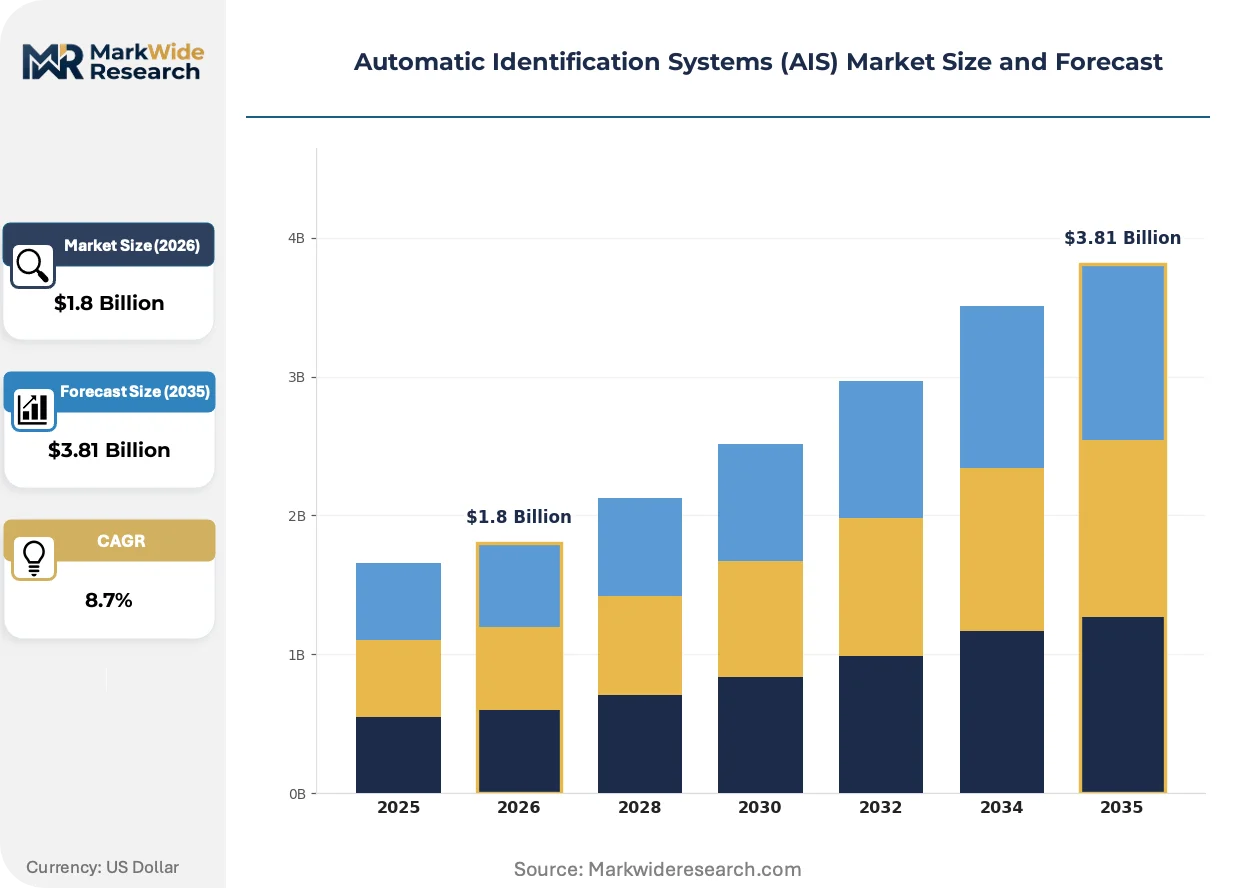
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radio Frequency Identification, Barcode Scanning, Biometric Recognition, Optical Character Recognition, Magnetic Stripe, Smart Card Application: Maritime Navigation, Freight Tracking, Port Security, Supply Chain Management, Asset Monitoring, Vehicle Fleet Management Product Type: Transceivers, Receivers, Antennas, Repeaters, Software Solutions, Integration Platforms End User: Shipping Companies, Logistics Providers, Port Authorities, Customs Agencies, Transportation Operators, Emergency Responders |
| Companies Covered | Furuno Electric Co., Ltd., Saab AB, L3Harris Technologies, Inc., Kongsberg Gruppen ASA, Orbcomm Inc., Japan Radio Co., Ltd., Garmin Ltd., ExactEarth Ltd., True Heading AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Identification Systems (AIS) Market Strategic Shifts
Hardware commoditization is pushing value capture toward software layers and data services, while regulatory technology mandates accelerate replacement velocity beyond traditional maritime electronics cycles.
Satellite-AIS fusion architectures are migrating from experimental coastal pilot programs to operational status in major port authorities. The Port of Rotterdam and Singapore Maritime and Port Authority are deploying hybrid terrestrial-satellite receiver networks that eliminate coverage gaps in offshore traffic lanes. This migration from ground-only infrastructure is compressing addressable market for pure-play shore station suppliers while expanding data service margins for integrated platform operators.
The International Maritime Organization's ongoing VDES standardization process is forcing transceiver manufacturers to engineer dual-mode hardware capable of operating on both legacy AIS channels and future VHF Data Exchange spectrum allocations. Shipowners in European Union waters face particular exposure given EU Maritime Safety Agency coordination requirements under SafeSeaNet. Manufacturers with modular RF front-end designs are securing advance purchase commitments from Scandinavian and German container lines seeking regulatory optionality.
Charter fleet operators are unbundling AIS hardware procurement from integrated bridge system packages, reversing decades of bundled electronics purchasing. Greek and Singapore-based tanker and bulker managers are sourcing transceivers through specialized marine electronics distributors rather than shipyard specification channels. This disintermediation is most visible in the Mediterranean wet-bulk segment where spot-market vessel operators prioritize rapid installation turnaround over OEM warranty integration.
Automatic Identification Systems (AIS) Market Segmentation
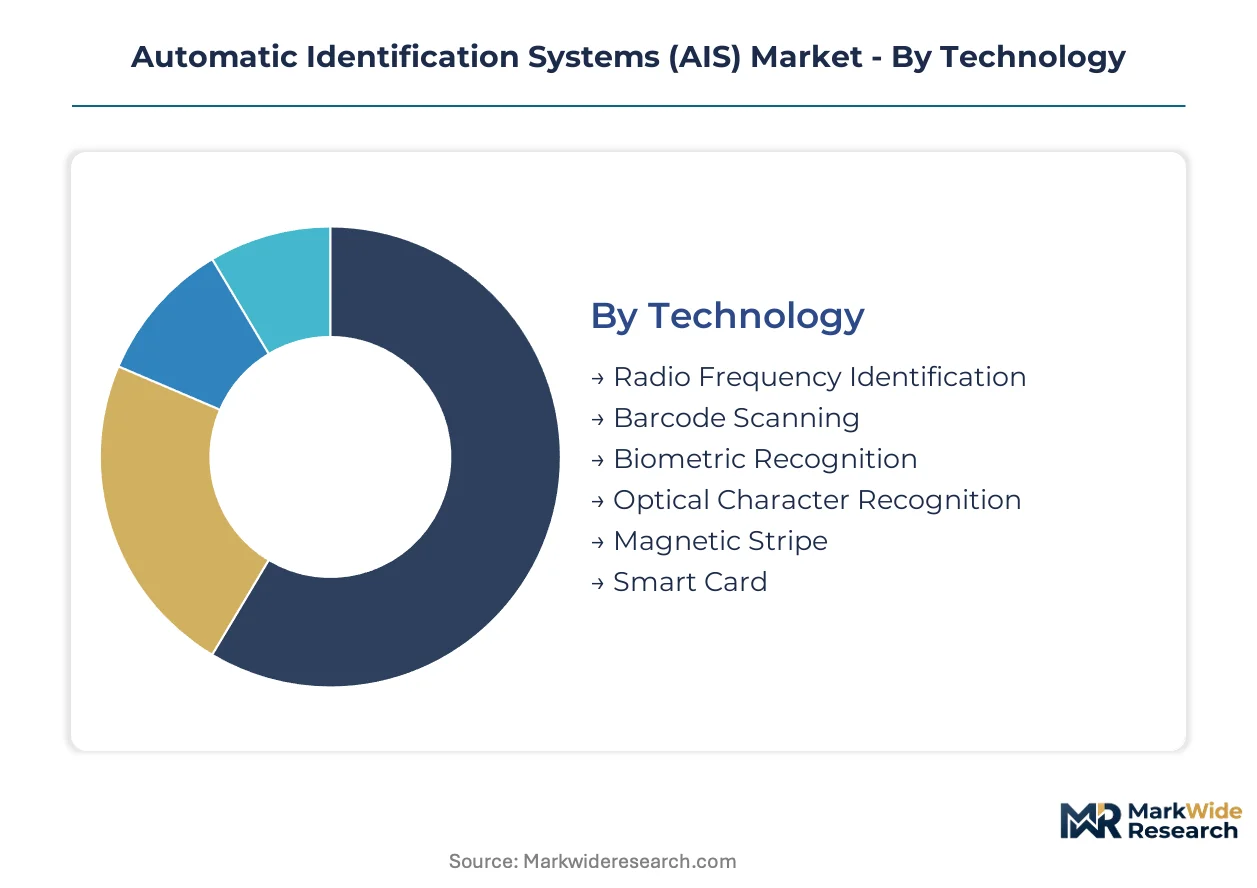
AIS market segmentation reveals distinct value capture patterns across hardware commoditization curves and software margin expansion. Technology and application dimensions separate mature navigation infrastructure from emerging data-service revenue pools.
Technology:
The maturity spectrum spans legacy optical systems to emerging biometric interfaces, with radio-frequency platforms anchoring maritime-specific deployment.
- Radio Frequency Identification:Dominant maritime implementation uses VHF bands at 161.975 MHz and 162.025 MHz for vessel-to-vessel and vessel-to-shore broadcasting. SOLAS-mandated installations across South Korean and Japanese newbuild yards sustain demand concentration for Class A transceiver modules.
- Barcode Scanning:Container-level tracking in intermodal logistics relies on optical barcode systems paired with AIS data correlation for freight visibility. Mediterranean and Caribbean charter markets are expanding adoption as logistics providers seek land-sea shipment continuity.
- Biometric Recognition:Crew identity verification systems for port access control.
- Optical Character Recognition:Automated container number reading at terminal gates.
- Magnetic Stripe:Legacy crew credentialing systems in aging port infrastructure.
- Smart Card:Seafarer identification document integration with shore-side access systems.
Radio Frequency Identification retains volume leadership; Biometric Recognition holds the steepest expansion curve.
Application:
Cost tier separation distinguishes mandated navigation equipment from discretionary freight analytics investments.
- Maritime Navigation:Collision avoidance and vessel traffic management constitute the installed base core. SOLAS Chapter V compliance drives replacement cycles across commercial fleets exceeding 300 gross tonnage on international voyages.
- Freight Tracking:Intermodal container visibility systems integrate AIS position data with land-based logistics orchestration. Logistics providers in Rotterdam and Singapore are deploying hybrid terrestrial-satellite receiver networks to eliminate coverage gaps.
- Port Security:Perimeter monitoring and vessel identification for restricted zone enforcement.
- Supply Chain Management:End-to-end shipment visibility platforms layering predictive analytics atop raw AIS feeds.
- Asset Monitoring:Offshore equipment and buoy tracking in coastal waters.
- Vehicle Fleet Management:Harbor craft and pilot boat coordination within port precincts.
Maritime Navigation dominates capital deployment; Freight Tracking is climbing the fastest.
Product Type:
Margin concentration shifts from hardware transceivers toward software layers as fleet analytics unbundle from bridge system packages.
- Transceivers:VHF maritime radio units operating on self-organizing time-division multiple access protocols. Greek and Singapore-based tanker operators are sourcing through specialized distributors rather than shipyard channels, accelerating installation turnaround.
- Software Solutions:Predictive maintenance and route optimization platforms represent the fastest-expanding margin category. Fleet analytics layered atop installed transceiver bases capture recurring revenue from shipping companies seeking operational efficiency.
- Receivers:Shore-based station equipment for port authority traffic management.
- Antennas:Specialized RF front-end components for maritime environments.
- Repeaters:Range extension units for coastal coverage gaps.
- Integration Platforms:Bridge system middleware connecting AIS to radar and ECDIS architectures.
Transceivers command installed base volume; Software Solutions gain share fastest.
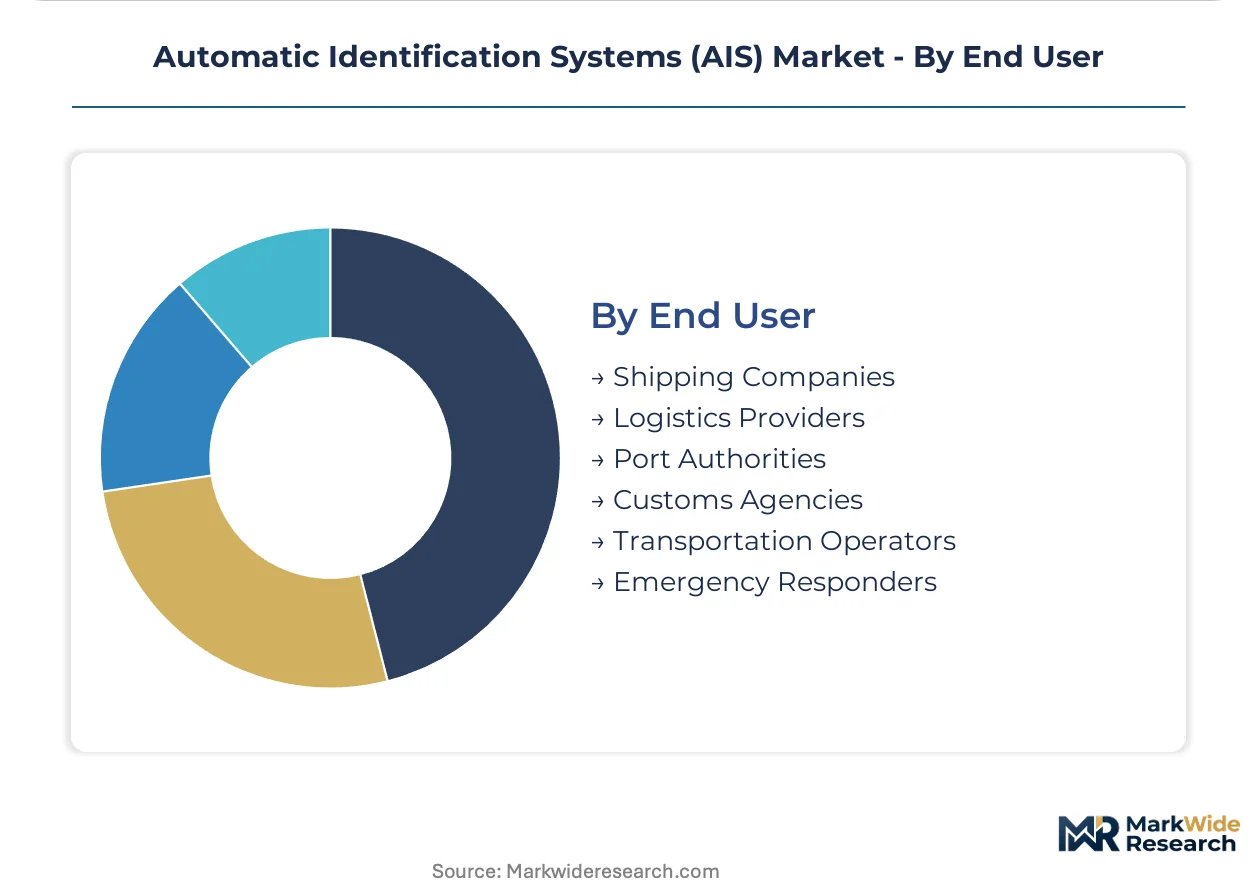
End User:
Procurement authority separates vessel owners from shore-side infrastructure operators with diverging specification priorities.
- Shipping Companies:Fleet-wide AIS carriage mandates under SOLAS Convention Chapter V compel hardware refresh cycles. Scandinavian and German container lines are securing advance purchase commitments for dual-mode transceivers capable of legacy AIS and future VDES spectrum operation.
- Port Authorities:Shore-side receiver network deployment and traffic management system integration. Rotterdam and Singapore Maritime and Port Authority hybrid terrestrial-satellite architectures are eliminating coverage gaps in offshore traffic lanes.
- Logistics Providers:Freight visibility platform operators seeking real-time intermodal container tracking.
- Customs Agencies:Vessel arrival notification and cargo manifest verification systems.
- Transportation Operators:Harbor craft, pilot services, and coastal ferry coordination.
- Emergency Responders:Search and rescue coordination using AIS position data for distressed vessel location.
Shipping Companies retain procurement volume leadership; Port Authorities hold the steepest service contract expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and South Korean manufacturing clusters where transceiver module production achieves scale economies, while European system integrators capture premium margins through service bundling. East Asian shipyards dominate newbuild installation volumes. Mediterranean retrofit markets exhibit price compression from distributor competition.
Japan
Domestic shipbuilding and electronics manufacturing sustain integrated supply chains for Class A transceiver production. The country's national maritime regulator enforces SOLAS Convention Chapter V compliance through stringent type approval processes. Yokohama and Nagoya harbor industrial clusters where bridge system integrators coordinate with shipyards on newbuild specifications.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor global newbuild demand for SOLAS-mandated equipment. Korean Register of Shipping certification requirements shape transceiver specifications for export vessels. Busan and Ulsan shipbuilding zones concentrate installation demand during construction phases.
Germany
Scandinavian and German container lines drive advance procurement of dual-mode VDES-capable hardware. The Federal Maritime and Hydrographic Agency coordinates EU SafeSeaNet data exchange obligations. Hamburg and Bremen port authorities deploy hybrid terrestrial-satellite receiver networks for traffic management.
Singapore
The Maritime and Port Authority mandates AIS carriage for harbor craft and pilot services beyond SOLAS minimums. Port infrastructure investments prioritize real-time vessel tracking for terminal optimization. The Tuas mega-port development expands shore-side receiver network deployment.
United States
The US Coast Guard enforces NVIC 01-04 equipment approvals that delay product launches from foreign manufacturers. Domestic inland waterway operators expand Class B transceiver adoption for collision avoidance. Houston and Los Angeles port complexes upgrade traffic management systems with satellite-AIS fusion architectures.
Automatic Identification Systems (AIS) Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in RF module manufacturing. The market structures around three tiers: defense contractors with coast guard relationships, marine electronics OEMs with shipyard channels, and consumer-electronics distributors serving recreational segments. Consolidation pressure favors balance-sheet depth for project finance and leasing structures. Dominant competitive moves include captive manufacturing of transceiver modules and strategic disintermediation through specialized marine electronics distributors.
Among Nordic defense-electronics conglomerates, Saab AB and Kongsberg Gruppen ASA exemplify platform integrators leveraging long-term service agreements and captive component supply. Garmin Ltd. occupies a position in recreational marine distribution where consumer-electronics supply chains enable price-competitive Class B offerings. Japanese electronics manufacturers including Furuno Electric Co., Ltd. and Japan Radio Co., Ltd. anchor the newbuild specification channel through integrated bridge system bundling.
| Leading Market Players |
|---|
| Furuno Electric Co., Ltd. |
| Saab AB |
| L3Harris Technologies, Inc. |
| Kongsberg Gruppen ASA |
| Orbcomm Inc. |
| Japan Radio Co., Ltd. |
| Garmin Ltd. |
| ExactEarth Ltd. |
| True Heading AB |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Taiwanese RF component foundries determines both three-tier pricing structure across premium, standard, and economy levels and supply chain resilience strategies among transceiver manufacturers. VDES standardization uncertainty compounds this structural vulnerability by freezing procurement timelines and compressing margin buffers across installation tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on certification grade and after-sales service bundling. SOLAS-mandated Class A units command premium positioning through Japan Radio Co. and Furuno Electric type approvals, while distributor-sourced Class B hardware faces price erosion from Greek and Singapore-based tanker operators prioritizing rapid turnaround. Price differentiation stems from vertical integration depth and volume scale, with Scandinavian container lines securing advance commitments for dual-mode VDES-capable units. Cost compression in the standard tier is intensifying because charter fleet disintermediation bypasses shipyard specification channels.
Supply Chain Analysis
Export-control restrictions on specialized RF semiconductors limit component flows from Taiwan and South Korea to transceiver assembly operations in Japan and South Korea. Manufacturing draws from gallium arsenide substrates, surface acoustic wave filters, and precision oscillator crystals concentrated in East Asian foundries. Single-source vulnerability pervades the RF front-end module tier where captive supply agreements dominate. Distribution runs through shipyard specification channels for newbuilds and specialized marine electronics distributors for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-mode VDES engineering capability sits in scarce supply relative to replacement cycle demand, constraining competitive entry and amplifying incumbent pricing power across the forecast horizon.
For Market Incumbents: Entrench position through captive manufacturing of transceiver modules and long-term service agreements with Nordic coast guards facing satellite-AIS substitution threats. Secure advance purchase commitments from German and Scandinavian container lines by offering modular RF front-end designs that preserve regulatory optionality against VDES timeline uncertainty. Deepen backward integration into specialized RF component supply to buffer Taiwan foundry capacity constraints. For New Entrants and Emerging Players: Mediterranean recreational marine penetration remains underdeveloped relative to collision avoidance awareness growth among charter operators. Target Caribbean bareboat fleets with rapid-install Class B transceivers distributed through independent marine electronics channels rather than shipyard bundling. Pursue white-space in freight tracking software layers where predictive maintenance platforms atop raw AIS feeds capture recurring revenue without hardware certification burdens. For Investors and Strategic Acquirers: The market sits at a hardware commoditization phase that favors platform integrators with coast guard relationships over component specialists. Long-term viability hinges on recurring software revenue attachment rates rather than transceiver shipment volumes. Monitor satellite-AIS fusion architecture adoption at Rotterdam and Singapore port authorities as inflection signal for shore-side receiver network obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode VDES Hardware Development | Preserves regulatory optionality for Scandinavian and German container lines facing EU SafeSeaNet coordination requirements. |
| Fleet Analytics Software Platform Launch | Captures recurring revenue from shipping companies seeking predictive maintenance layered atop installed transceiver bases. |
| Specialized Marine Electronics Distribution Partnership | Accelerates installation turnaround for Greek and Singapore-based tanker operators disintermediating shipyard channels. |
| Hybrid Terrestrial-Satellite Receiver Network Deployment | Eliminates coverage gaps for Rotterdam and Singapore port authorities expanding traffic management infrastructure. |
| Long-Term Service Agreement with Coast Guard | Sustains revenue visibility for Nordic defense-electronics suppliers leveraging existing contracting relationships. |
Study Parameters
Desk research of International Maritime Organization regulatory filings, EU SafeSeaNet technical specifications, and US Coast Guard NVIC equipment approval records preceded structured interviews with shipyard electronics specification engineers, fleet technical managers at container lines, port authority traffic system operators, and marine electronics distributors. Primary fieldwork across the analysis window combined with secondary validation against customs trade data and SEC filings from listed marine electronics OEMs. Bottom-up transceiver shipment estimates and top-down fleet compliance requirements were triangulated to constrain forecast variance.
Assumptions held SOLAS Convention Chapter V enforcement intensity and VDES standardization timelines within observed regulatory patterns while varying East Asian shipbuilding output and charter fleet disintermediation velocity across scenarios. The analytical framework modeled technology transitions, application migrations from navigation to freight tracking, product type shifts from hardware to software, and end-user procurement authority evolution. CAGRs were derived from installed base replacement cycles and newbuild installation rates applied to vessel fleet growth projections. Forecast inputs incorporated semiconductor foundry capacity utilization and satellite-AIS fusion architecture adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by commercial constellation operators or accelerated VDES mandates would shift outcomes. Material shifts in spectrum reallocation timelines or foundry capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market