
 Smart Transportation Solution Market | 2026-2036
Smart Transportation Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Transportation Solution Market Insights
Modular bundling of traffic management systems with V2X communication platforms is expanding buyer choice across municipal procurement cycles. Siemens AG leverages its rail-automation heritage to anchor integrated corridor contracts in European transit hubs. Thales Group competes through signaling-to-payments convergence in multimodal platforms. Cisco Systems, Inc. specializes in edge-networking layers that sustain real-time data throughput for connected vehicle ecosystems.
Smart transportation solutions encompass IoT-enabled infrastructure, AI-driven predictive analytics, and cloud-native fleet orchestration architectures designed to optimize mobility flows across congested urban networks. These systems integrate sensor fusion, edge computing nodes, and 5G backhaul to enable sub-second latency for safety-critical vehicle-to-infrastructure coordination. Traffic Management Systems dominate capital deployment as cities prioritize congestion reduction, while V2X Communication Systems represent the fastest-expanding technology layer as automotive OEMs mandate connected-vehicle readiness. Big Data Analytics concentrates margin pools where predictive maintenance and demand-forecasting modules command premium pricing from logistics operators.
The US Department of Transportation coordinates with the FAA and NHTSA to mandate connected-vehicle standards that shape product certification timelines for domestic suppliers. In Europe, the EU AI Act and GDPR impose algorithmic transparency requirements on automated traffic decision systems, restricting black-box AI deployment in public safety contexts. China's MIIT enforces GB standards for V2X protocol interoperability that condition market access for foreign equipment vendors. Stakeholders must monitor divergent certification pathways as regulatory fragmentation across Washington, Brussels, and Beijing threatens interoperability roadmaps for cross-border fleet operators.
Market Dynamics
The EU Green Deal's emissions mandates and the US IRA's clean transit incentives are forcing public transportation agencies to restructure procurement criteria toward electrified, connected infrastructure platforms.
Growth Catalysts
- EU Green Deal mandates:The framework's binding emissions targets compel municipal transit authorities to accelerate deployment of integrated traffic management systems with embedded carbon monitoring capabilities.
- Edge computing nodes:Sensor fusion architectures with sub-second latency are absorbing capital from legacy signal systems as cities prioritize real-time vehicle-to-infrastructure coordination.
- Singapore metro corridors:Dense urban networks in Southeast Asian hubs generate concentrated demand for multimodal orchestration platforms that unify rail, bus, and micro-mobility flows.
Market Restraints
- 5G backhaul deployment costs:Fiber densification requirements for connected vehicle ecosystems impose capital intensity that fragments municipal budget cycles across mid-sized cities.
- Semiconductor supply concentration:Edge-computing chip fabrication concentrates in East Asian foundries, exposing traffic management system integrators to geographic supply risk.
- GDPR algorithmic transparency:The EU AI Act's black-box restrictions create compliance friction for predictive analytics vendors serving automated traffic decision systems.
Strategic Opportunities
- São Paulo metro expansion:Latin America's largest urban corridor presents underpenetrated demand for cloud-native fleet orchestration architectures.
- US IRA clean transit incentives:Tax credit structures for electrified infrastructure create procurement tailwinds for integrated corridor contracts spanning multiple transit modes.
- V2X-to-payments convergence:Thales Group's signaling heritage demonstrates how multimodal platforms can monetize fare integration across autonomous and human-driven vehicle fleets.
Industry Challenges
- Cyber-physical systems engineering:Safety-critical vehicle coordination demands scarce talent pools fluent in both embedded systems and automotive functional safety standards.
- GB standards interoperability:China's MIIT protocol requirements force foreign equipment vendors to maintain parallel certification tracks, compressing margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Transportation Solution Market |
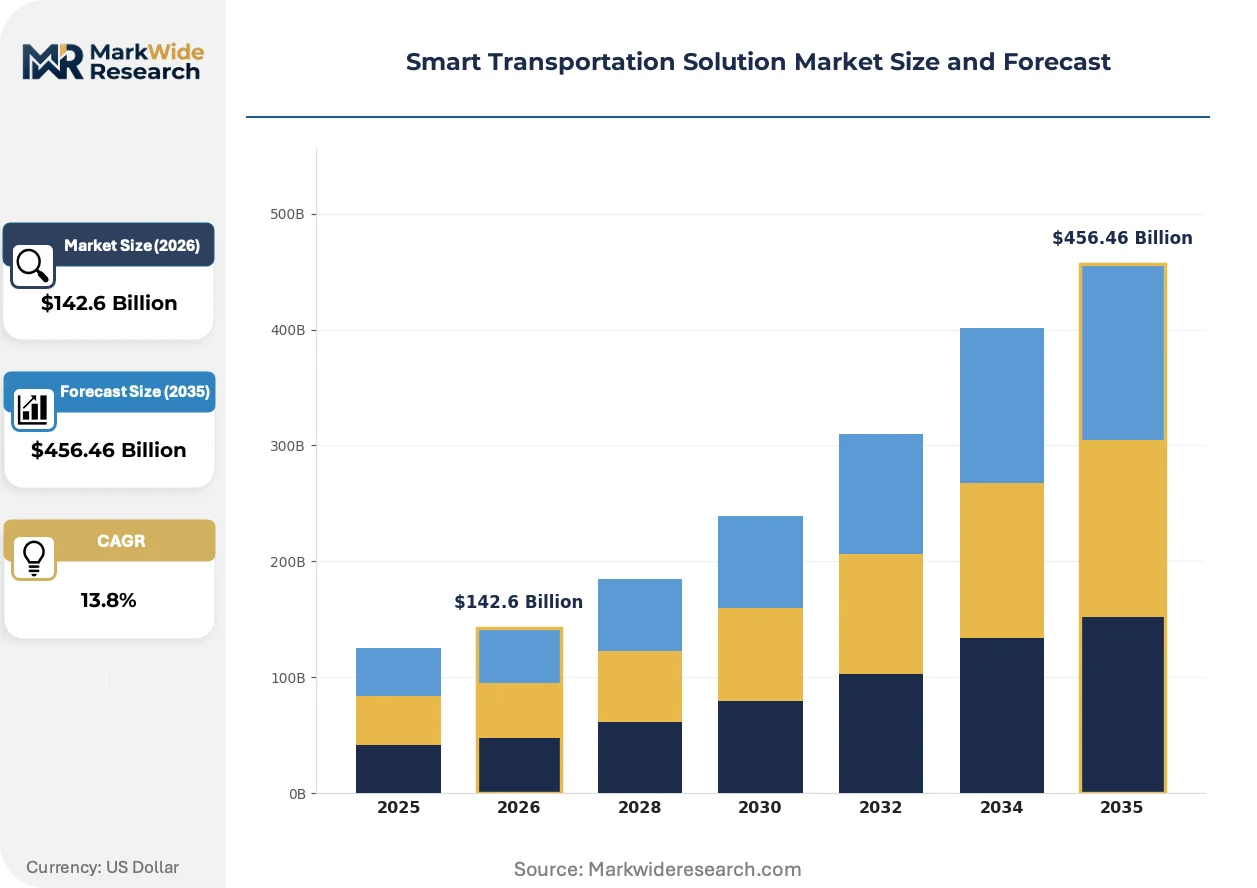
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $456.46 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Management Systems, Fleet Management Solutions, Smart Parking Solutions, V2X Communication Systems Technology: IoT, AI, Big Data Analytics, Cloud Computing End User: Public Transportation Agencies, Logistics Companies, Commercial Fleets, Ride-Sharing Services Application: Traffic Optimization, Route Management, Passenger Information Systems, Fleet Tracking |
| Companies Covered | Siemens AG, Thales Group, Hitachi Ltd., Cisco Systems, Inc., Kapsch TrafficCom AG, Cubic Corporation, IBM Corporation, Huawei Technologies Co., Ltd., Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Transportation Solution Market Trends and Innovations
Digital twin architectures are absorbing investment from static traffic modeling as agencies demand predictive simulation capabilities for corridor optimization.
Digital twin platforms replicate urban mobility networks in real-time, enabling scenario testing before physical deployment. Transit authorities in Dubai and São Paulo are adopting these systems at accelerated procurement cycles. The technology is absorbing engineering resources from conventional simulation vendors, compressing their addressable market in advanced economies.
The EU AI Act imposes mandatory algorithmic transparency on automated traffic decision systems deployed in public safety contexts. Black-box predictive models face deployment restrictions across European transit hubs. Vendors are responding by engineering explainable AI modules that document decision pathways for regulatory audit.
Municipal buyers are consolidating vendor relationships around integrated platform contracts rather than point-solution procurement. Single-source corridor management agreements are displacing fragmented traffic signal, fleet tracking, and payment system purchases. This pattern concentrates most visibly in German and Japanese transit authorities with mature procurement frameworks.
Smart Transportation Solution Market Segmentation
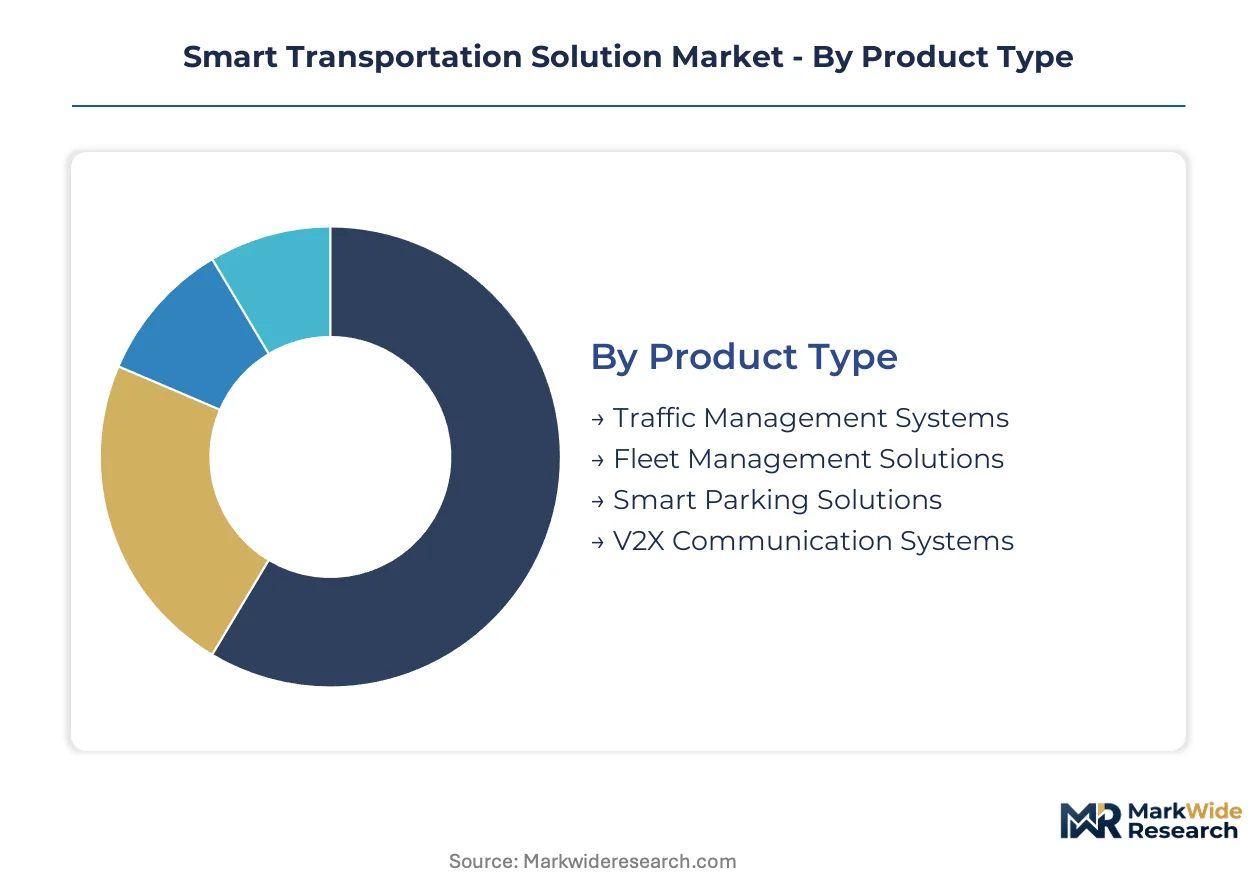
Procurement patterns across smart transportation diverge sharply by buyer technical maturity and capital deployment timelines. Municipal agencies prioritize integrated platforms with decade-long amortization horizons, while logistics operators favor modular deployments with rapid ROI cycles.
Product Type:
Buyer differentiation centers on infrastructure ownership models—cities favor capital-intensive embedded systems, while private fleets demand subscription-based orchestration layers.
- Traffic Management Systems:These platforms integrate sensor fusion, adaptive signal control, and centralized command centers for urban corridor optimization. German transit authorities in Hamburg and Munich anchor procurement volume through integrated corridor contracts spanning rail, tram, and bus priority signaling.
- V2X Communication Systems:Vehicle-to-everything protocols enable sub-second latency coordination between connected vehicles and roadside infrastructure. Deployment concentrates along Singapore's expressway network and Dubai's autonomous vehicle test corridors, driven by mandates from the Land Transport Authority and Dubai's RTA respectively.
- Fleet Management Solutions:Cloud-native orchestration platforms optimize routing, fuel consumption, and maintenance scheduling for commercial vehicle operators. São Paulo's logistics corridor generates concentrated demand from last-mile delivery consolidation.
- Smart Parking Solutions:Sensor-guided space allocation and dynamic pricing modules reduce urban congestion. Japanese municipal deployments in Tokyo and Osaka prioritize integration with existing transit payment ecosystems.
Volume sits with Traffic Management Systems; growth tilts toward V2X Communication Systems.
Technology:
Technology selection tracks data sovereignty requirements—European buyers prioritize edge-localized processing under GDPR constraints, while Asian hubs emphasize centralized cloud architectures.
- IoT:Sensor networks and edge computing nodes form the physical layer for real-time traffic monitoring. Dubai's smart city initiative drives concentrated deployment of environmental and occupancy sensors across metro and road networks.
- Big Data Analytics:Predictive maintenance and demand-forecasting modules command premium positioning from logistics operators seeking to minimize fleet downtime. São Paulo's cargo consolidation hubs represent high-margin demand concentration for freight pattern optimization.
- AI:Algorithmic traffic prediction and autonomous vehicle coordination face deployment friction from EU AI Act transparency mandates. Explainable AI architectures are displacing black-box models in German and French procurement cycles.
- Cloud Computing:Elastic infrastructure supports multi-tenant fleet orchestration platforms with variable load patterns. Singapore's Land Transport Authority mandates sovereign cloud residency for passenger data processing.
Margin pools concentrate in Big Data Analytics; AI faces regulatory headwinds despite technical capabilities.
End User:
End-user segmentation reflects divergent procurement authority structures—public agencies operate under political budget cycles, while commercial operators align technology refresh with depreciation schedules.
- Public Transportation Agencies:Municipal and regional transit authorities deploy integrated corridor management with decade-long capital planning horizons. Japan's Ministry of Land, Infrastructure, Transport and Tourism coordinates standardization across Tokyo, Osaka, and Nagoya metro networks.
- Logistics Companies:Freight operators prioritize route optimization and predictive maintenance to minimize per-mile costs. Brazil's agricultural export corridor through Santos port drives concentrated demand for multimodal cargo tracking.
- Commercial Fleets:Corporate vehicle pools demand telematics integration with existing enterprise resource planning systems. German manufacturing clusters around Stuttgart and Wolfsburg anchor procurement for captive fleet electrification tracking.
- Ride-Sharing Services:Platform operators require dynamic pricing algorithms and driver-rider matching optimization. Dubai's RTA-regulated ride-hailing ecosystem mandates API interoperability with public transit payment systems.
Procurement volume aggregates with Public Transportation Agencies; Logistics Companies demonstrate steepest expansion trajectory for predictive analytics modules.
Application:
Application prioritization varies by urban density—megacities emphasize passenger information integration, while logistics corridors prioritize freight velocity.
- Traffic Optimization:Real-time signal adaptation and congestion pricing algorithms reduce urban travel times. Singapore's Electronic Road Pricing system represents mature deployment with dynamic rate adjustment capabilities.
- Fleet Tracking:GPS-based location monitoring and geofencing enable cargo security and driver compliance verification. São Paulo's pharmaceutical distribution networks mandate cold-chain tracking integration with traffic optimization platforms.
- Route Management:Dynamic rerouting algorithms respond to incidents and demand fluctuations. German autobahn corridors deploy predictive diversion models integrated with weather and construction data feeds.
- Passenger Information Systems:Real-time arrival displays and multimodal journey planners improve perceived service quality. Tokyo Metro's integrated signage across rail, bus, and micro-mobility modes sets interoperability benchmarks.
Traffic Optimization commands capital deployment priority; Fleet Tracking gains share fastest among logistics operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in German industrial clusters and Chinese manufacturing hubs, while deployment demand aggregates in dense urban corridors across Singapore, Dubai, and São Paulo. Consumption patterns diverge sharply between mature transit authorities with decade-long procurement cycles and emerging cities prioritizing rapid corridor digitization.
United States
The US Department of Transportation coordinates with the NHTSA to mandate connected-vehicle standards that reshape product certification timelines for domestic suppliers. The IRA's clean transit incentives create procurement tailwinds for integrated corridor contracts spanning multiple transit modes. California's transit authorities anchor demand concentration through electrified infrastructure mandates in Los Angeles and San Francisco Bay Area metro networks.
Germany
Hamburg and Munich transit authorities anchor procurement volume through integrated corridor contracts spanning rail, tram, and bus priority signaling. The EU Green Deal's binding emissions targets compel municipal authorities to accelerate deployment of traffic management systems with embedded carbon monitoring. Bavaria's manufacturing clusters around Stuttgart and Wolfsburg drive captive fleet electrification tracking demand from automotive producers.
Singapore
The Land Transport Authority mandates sovereign cloud residency for passenger data processing and drives concentrated V2X deployment along the expressway network. Dense urban networks generate concentrated demand for multimodal orchestration platforms unifying rail, bus, and micro-mobility flows. The metro corridor digitization program absorbs capital from legacy signal systems as the city prioritizes real-time vehicle-to-infrastructure coordination.
China
The MIIT enforces GB standards for V2X protocol interoperability that condition market access for foreign equipment vendors. Edge-computing chip fabrication concentrates in East Asian foundries, exposing system integrators to geographic supply risk. Yangtze River Delta manufacturing hubs produce sensor fusion hardware serving domestic metro expansion in Shanghai and Hangzhou.
Brazil
São Paulo's logistics corridor generates concentrated demand from last-mile delivery consolidation and pharmaceutical distribution networks requiring cold-chain tracking integration. The agricultural export corridor through Santos port drives demand for multimodal cargo tracking and freight pattern optimization. Latin America's largest urban corridor presents underpenetrated demand for cloud-native fleet orchestration architectures.
Smart Transportation Solution Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with embedded rail-automation heritage. Siemens AG and Thales Group anchor the premium tier through integrated corridor contracts, while networking specialists occupy the infrastructure layer. Three archetypes dominate: heritage rail-automation providers, telecommunications infrastructure vendors, and cloud-native fleet orchestration platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players bridge hardware fabrication with software service layers.
Among heritage European industrial groups, Siemens AG and Thales Group exemplify the rail-automation-to-multimodal convergence archetype. Cisco Systems, Inc. represents the networking infrastructure specialist position. Huawei Technologies Co., Ltd. occupies a scale-driven manufacturing position within the equipment supply tier. These three anchors illustrate how competitive positioning fragments across automation heritage, edge-networking specialization, and integrated platform delivery.
| Leading Market Players |
|---|
| Siemens AG |
| Thales Group |
| Hitachi Ltd. |
| Cisco Systems, Inc. |
| Kapsch TrafficCom AG |
| Cubic Corporation |
| IBM Corporation |
| Huawei Technologies Co., Ltd. |
| Robert Bosch GmbH |
| Others |
Pricing and Supply Chain Analysis
Municipal procurement consolidation around integrated corridor contracts is compressing vendor margins as buyers demand decade-long service bundling with upfront hardware deployment. This specification shift forces suppliers to absorb financing costs and inventory risk, reshaping how pricing power distributes across equipment tiers.
Pricing Analysis
Margin tightening in mid-tier traffic management systems reflects buyer consolidation around single-source corridor agreements spanning German and Japanese transit authorities. Three-tier pricing structure across premium, standard, and economy levels separates heritage rail-automation providers from networking specialists and cloud-native entrants. Price differentiation traces to certification grade under EU AI Act transparency mandates and volume scale in multimodal platform deployments. Logistics operators demonstrate highest price sensitivity due to rapid ROI cycle requirements, while public agencies with amortized capital planning tolerate premium positioning for integrated solutions.
Supply Chain Analysis
Edge-computing chip fabrication rests on Taiwanese and South Korean foundry capacity, with sensor fusion hardware production concentrated in Yangtze River Delta manufacturing clusters. Raw material dependencies span silicon wafers, 5G radio components, and automotive-grade sensors for V2X protocol stacks. Single-source vulnerability in semiconductor supply exposes traffic management system integrators to geographic concentration risk. Distribution runs through systems integrators with embedded rail-automation heritage, who bundle hardware fabrication with software service layers for municipal procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform vendors as EU AI Act compliance costs and 5G backhaul capital requirements force point-solution providers toward acquisition or exit.
For Market Incumbents: Hedge against margin compression by deepening in-house production of edge-computing nodes to offset foundry pricing volatility. Anchor integrated corridor contracts through signaling-to-payments convergence that locks in decade-long service revenue and raises switching costs for municipal buyers evaluating modular alternatives. For New Entrants and Emerging Players: Capture underpenetrated demand in São Paulo's cloud-native fleet orchestration architectures, where logistics corridor digitization lags European procurement maturity. Target pharmaceutical distribution networks requiring cold-chain tracking integration as a beachhead for multimodal cargo optimization platforms with faster deployment cycles than legacy traffic management systems. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with explainable AI module capabilities and sovereign cloud residency certifications. Long-term viability hinges on regulatory compliance infrastructure rather than pure technical differentiation. Watch EU AI Act enforcement patterns across German and French transit hubs as the inflection signal for which vendor archetypes secure preferred procurement status.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies traffic signal, fleet tracking, and payment systems under single-source corridor contracts demanded by Hamburg and Munich authorities. |
| Backward Integration | Captures edge-computing node production to reduce exposure to Taiwanese foundry concentration and stabilize component costs. |
| Regulatory Certification Investment | Secures EU AI Act algorithmic transparency compliance that restricts black-box AI deployment in German and French public safety contexts. |
| Strategic Partnership | Enables V2X-to-payments convergence across autonomous and human-driven fleets through signaling heritage integration. |
| Geographic Expansion | Addresses underpenetrated São Paulo logistics corridor demand for cloud-native fleet orchestration with localized deployment capabilities. |
Research Methodology
Document review covered regulatory filings from the US Department of Transportation, EU AI Act implementation guidance, and MIIT GB standards documentation, complemented by interviews with municipal transit authority procurement directors, systems integration engineers at heritage rail-automation providers, and fleet operations managers at São Paulo logistics corridors. Secondary validation drew from NHTSA connected-vehicle standard releases, Land Transport Authority tender databases, and customs records of edge-computing hardware trade flows. Bottom-up demand modeling across urban corridor deployments was cross-referenced with top-down market sizing from integrated platform contract values.
Historical deployment trajectories in Singapore, Dubai, and São Paulo metro networks were cross-referenced against panel input from procurement officers regarding budget cycle timing and specification evolution. Segmentation modeling spanned product type, technology layer, end-user archetype, and application priority across the projection horizon. CAGRs were derived from elasticity-adjusted deployment curves incorporating 5G backhaul rollout pacing and EU Green Deal procurement mandate acceleration. Industry-specific inputs included V2X protocol certification timelines and sovereign cloud residency requirements for passenger data processing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply concentration and regulatory fragmentation across Washington, Brussels, and Beijing. Forecasts reflect documented assumptions regarding municipal budget cycle stability and clean transit incentive continuity. A small set of triggers warrants ongoing watch: MIIT protocol interoperability rulings, EU AI Act enforcement precedent, and IRA tax credit renewal patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Smart Parking Systems Market