
 Transportation Analytics Market | 2026-2036
Transportation Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Analytics Market Intelligence
Cloud infrastructure is pivoting away from legacy on-premises data centers in transportation analytics, slashing total cost of ownership for municipal buyers. IBM Corporation leverages its hybrid cloud architecture to dominate government contracts. Siemens Mobility anchors European intelligent traffic systems through deep hardware-software integration. SAP SE sustains competitive position via ERP-linked fleet analytics modules.
Transportation analytics encompasses the computational processing of geospatial, telematics, and operational data to optimize vehicle routing, traffic flow, and asset utilization across multimodal networks. The discipline integrates real-time sensor feeds, predictive algorithms, and visualization dashboards to reduce congestion, fuel consumption, and incident response latency. Cloud-based deployment leads solution architecture by enabling elastic compute for seasonal traffic spikes and distributed fleet monitoring. Freight logistics application segments capture premium margins through cargo-tracking APIs and predictive delay analytics. Route optimization solutions exhibit the fastest expansion as fuel volatility pressures trucking operators toward algorithmic dispatch.
The Federal Transit Administration and the European Commission's ITS Directive shape demand by mandating open data standards and interoperability protocols for public transit systems. The EU AI Act imposes algorithmic accountability requirements on automated traffic management systems, forcing vendors to document decision logic and bias testing. Stakeholders must monitor evolving cybersecurity frameworks from the U.S. Department of Transportation and the EU Agency for Cybersecurity as connected vehicle data flows multiply attack surfaces.
Market Dynamics
Cloud migration is compressing deployment timelines for municipal traffic management systems, forcing legacy hardware vendors to rearchitect around API-first service delivery or cede procurement cycles to software-native competitors.
Growth Catalysts
- Federal Transit Administration mandates:Open data standards for public transit interoperability compel agencies to upgrade legacy systems, creating replacement demand for integrated analytics platforms.
- Edge computing architectures:Real-time processing at roadside units reduces latency for incident detection, accelerating adoption among highway operators managing high-volume corridors.
- Fuel price volatility:Trucking fleets deploy algorithmic dispatch systems to optimize routing against diesel cost swings, pulling demand for predictive analytics modules.
Market Restraints
- Semiconductor supply concentration:Sensor and edge-processor fabrication concentrates in East Asian foundries, exposing traffic hardware deployments to input bottlenecks and extended lead times.
- EU AI Act compliance costs:Algorithmic documentation and bias-testing requirements for automated traffic management systems inflate vendor R&D expenditure and extend sales cycles.
- Legacy system entrenchment:Municipal procurement inertia favors incumbent providers with entrenched maintenance contracts, delaying competitive displacement even where superior analytics exist.
Strategic Opportunities
- India's smart cities mission:Federal infrastructure spending on urban mobility creates white space for cloud-based traffic platforms in metro areas lacking legacy hardware investments.
- Connected vehicle data monetization:OEM telematics streams enable new revenue models for predictive maintenance and usage-based insurance, converging automotive and analytics value chains.
- Cybersecurity certification tailwinds:U.S. Department of Transportation frameworks for connected vehicle security create compliance-driven demand for encrypted data-pipeline solutions.
Industry Challenges
- Geospatial data science talent scarcity:Shortage of specialists combining machine learning expertise with transportation domain knowledge constrains vendor scaling and implementation velocity.
- Multi-vendor integration complexity:Municipal buyers demand seamless interoperability between competing sensor hardware, cloud platforms, and legacy central systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Analytics Market |
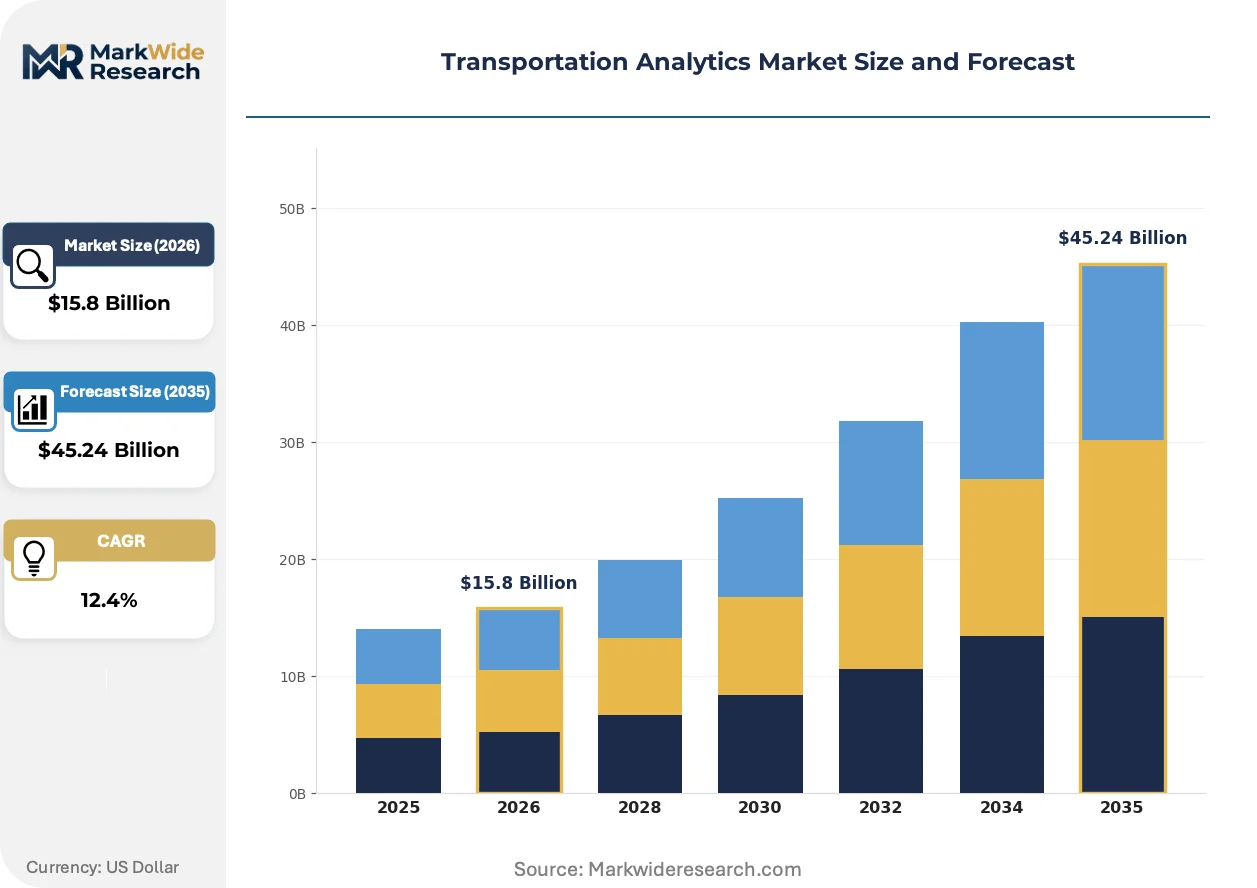
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $45.24 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution: Fleet Management, Traffic Monitoring, Route Optimization, Incident Detection, Cargo Tracking Application: Public Transit, Freight Logistics, Ride Sharing, Aviation Management, Maritime Operations End User: Logistics Providers, Municipal Agencies, Transportation Operators, Supply Chain Managers |
| Companies Covered | IBM Corporation, Siemens Mobility, SAP SE, Oracle Corporation, Trimble Inc., SAS Institute Inc., Cubic Corporation, TomTom NV, INRIX Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Analytics Market Strategic Shifts & Innovations
Algorithmic transparency requirements and edge-to-cloud architectural shifts are redefining competitive advantage, privileging vendors who can document decision logic while processing sensor streams at sub-second latency.
Digital twin technology is integrating physical road network geometry with real-time traffic flow simulation, enabling predictive scenario modeling for congestion management. State departments of transportation in California and Texas deploy these systems for pre-event routing optimization. The technology is compressing planning cycles from months to hours by virtualizing infrastructure interventions before physical deployment.
The EU AI Act imposes mandatory algorithmic impact assessments on automated traffic signal control systems, forcing vendors to maintain auditable decision trails. German municipal authorities now require documentation of training data provenance and bias testing protocols as standard procurement criteria. This regulatory friction favors established providers with compliance infrastructure over emerging competitors lacking legal resources.
Fleet operators are consolidating vendor relationships around integrated platform contracts that bundle telematics, routing optimization, and regulatory reporting. Mid-sized trucking companies in the Midwest United States increasingly reject point-solution purchases in favor of subscription-based analytics suites. This buying-pattern compression pressures specialized software vendors to expand feature breadth or accept margin erosion through partnership arrangements.
Transportation Analytics Market Segmentation
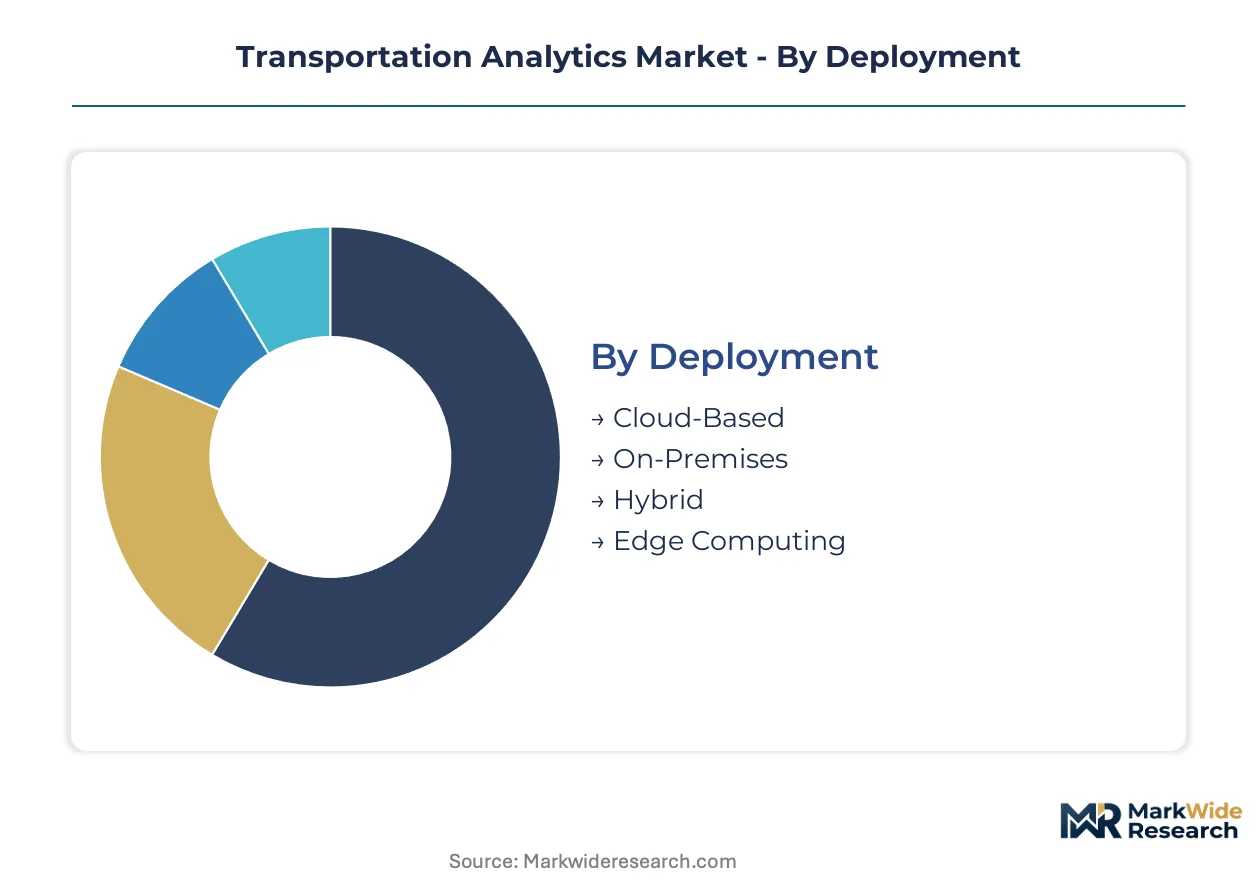
Transportation analytics vendors configure solution architectures around distinct deployment topologies, functional modules, and operational domains. Each segmentation dimension carries specific procurement patterns, margin profiles, and integration requirements that shape competitive positioning.
Deployment:
Standardization dominates at the infrastructure layer while customization intensifies at the edge, creating a deployment spectrum from commodity cloud to bespoke embedded systems.
- Cloud-Based:Elastic compute resources scale dynamically with traffic data volumes. Municipal agencies in Germany and the United States concentrate procurement here, driven by Federal Transit Administration open-data mandates and EU AI Act documentation requirements that favor centralized audit trails.
- On-Premises:Dedicated hardware installations within agency data centers maintain air-gapped security for sensitive transportation networks. Defense and critical infrastructure operators in France and Japan retain this model despite higher total cost of ownership, constrained by national cybersecurity frameworks and data sovereignty regulations.
- Hybrid:Split architectures process sensitive operations locally while pushing analytics workloads to cloud infrastructure. Mid-sized logistics providers across the Midwest United States adopt this pattern to balance latency requirements against capital constraints.
- Edge Computing:Real-time processing at roadside units and vehicle gateways minimizes response latency for collision avoidance and signal optimization. Highway operators managing California's I-405 and Texas's I-35 corridors deploy these systems for sub-second incident detection.
Leading the category by volume: Cloud-Based. Growing fastest: Edge Computing.
Solution:
Application maturity separates established fleet visibility tools from emerging predictive modules, with revenue concentration tracking operational criticality rather than technological sophistication.
- Fleet Management:Unified platforms integrating vehicle telemetry, driver behavior scoring, and maintenance scheduling. Trucking operators in the United States and Germany anchor demand, pressured by fuel price volatility into algorithmic dispatch adoption.
- Traffic Monitoring:Real-time sensor fusion and congestion visualization for urban road networks. Siemens Mobility dominates European deployments through hardware-software integration, while IBM Corporation captures North American government contracts via hybrid cloud architecture.
- Route Optimization:Predictive algorithms minimize fuel consumption and transit time across variable demand patterns. Last-mile delivery providers in India and Brazil expand procurement fastest as e-commerce volumes strain legacy dispatch systems.
- Incident Detection:Automated video analytics and acoustic sensors identify collisions, debris, and erratic driving. Deployment concentrates on high-volume corridors in California, Texas, and Germany's autobahn network where response latency directly impacts throughput.
- Cargo Tracking:API-connected visibility platforms monitor container location, condition, and customs status. Maritime freight forwarders and pharmaceutical shippers pay premium margins for temperature-controlled chain-of-custody documentation.
Revenue concentrates in Fleet Management and Traffic Monitoring. Route Optimization climbs fastest as fuel volatility pressures operational margins.
Application:
Operational complexity and data integration depth vary sharply across mobility modes, with multimodal platforms commanding pricing premiums over single-domain solutions.
- Public Transit:Ridership forecasting, schedule adherence, and fare collection analytics for bus and rail networks. EU ITS Directive interoperability mandates and Federal Transit Administration open-data standards drive replacement cycles in Germany, France, and the United States.
- Freight Logistics:End-to-end shipment visibility, carrier performance scoring, and warehouse synchronization. This application captures the steepest expansion trajectory as supply chain volatility pushes shippers toward predictive delay analytics.
- Ride Sharing:Dynamic pricing, driver supply matching, and demand heat-mapping for mobility-as-a-service platforms. Urban deployments in India and Brazil outpace mature markets as smartphone penetration enables informal fleet participation.
- Aviation Management:Gate utilization, baggage handling optimization, and airside vehicle tracking. Airport authorities in the United States, Germany, and Japan prioritize these systems for capacity-constrained hub operations.
- Maritime Operations:Port congestion prediction, vessel routing, and container yard optimization. Singapore and Rotterdam port authorities anchor adoption, with emissions monitoring requirements from the EU Green Deal accelerating sensor deployment.
Freight Logistics generates highest absolute spending. Ride Sharing expands most quickly in emerging metro corridors lacking legacy infrastructure.
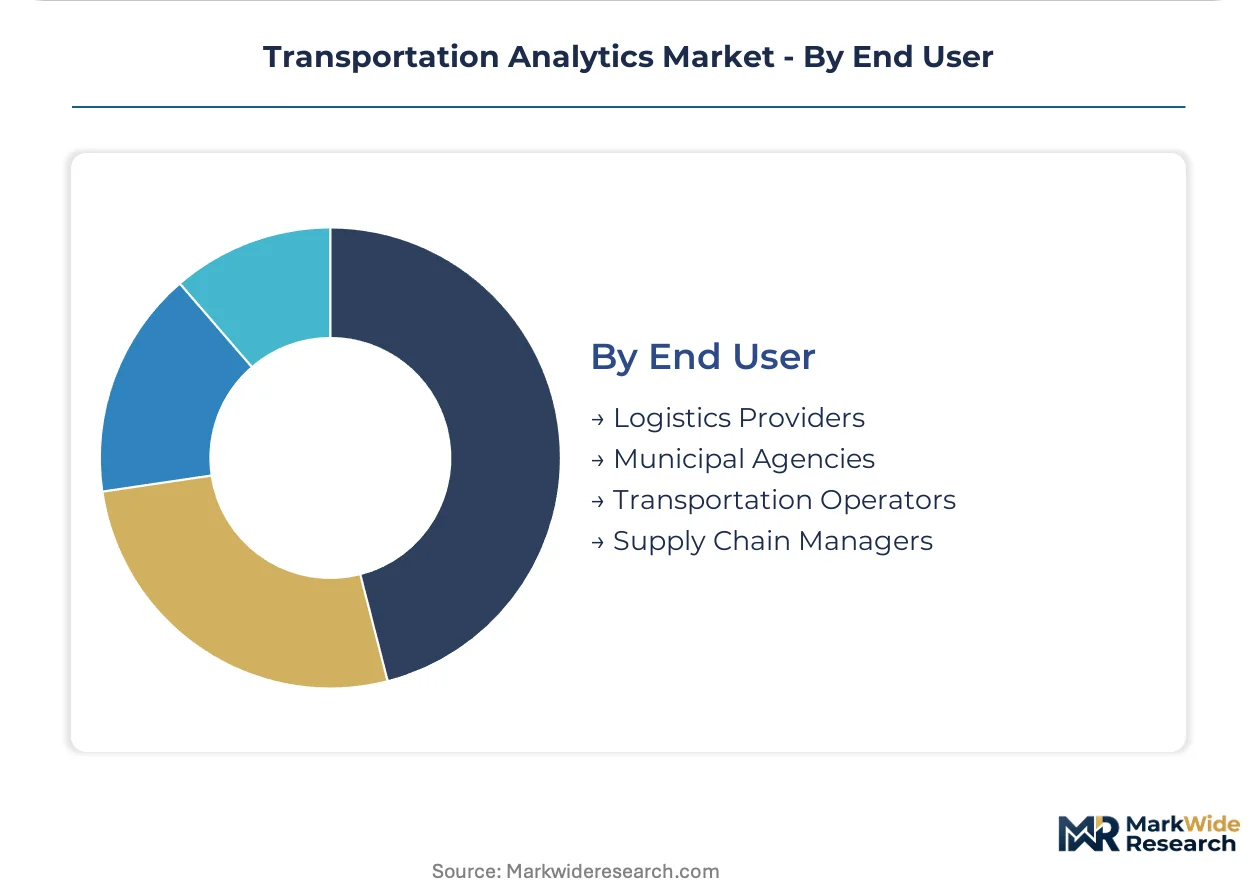
End User:
Procurement sophistication separates enterprise-scale integrators from constrained municipal buyers, with contract structures evolving from perpetual licenses toward outcome-based subscriptions.
- Logistics Providers:Third-party freight operators and courier networks requiring multimodal visibility and customer-facing tracking portals. DHL and FedEx-scale operators consolidate vendor relationships around integrated platform contracts.
- Municipal Agencies:City and regional transportation departments managing traffic signals, public transit, and road maintenance. Procurement inertia favors incumbent providers with entrenched maintenance contracts, delaying competitive displacement.
- Transportation Operators:Rail, bus, and ferry companies optimizing fleet deployment and passenger experience. German municipal authorities now require algorithmic documentation as standard procurement criteria under EU AI Act compliance.
- Supply Chain Managers:Enterprise manufacturers and retailers orchestrating inbound materials and outbound distribution. These buyers demand seamless interoperability between competing sensor hardware, cloud platforms, and legacy central systems.
Municipal Agencies represent the largest addressable base by contract count. Logistics Providers drive fastest platform consolidation as mid-sized operators reject point-solution purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal authorities anchor European procurement intensity for intelligent traffic systems, while United States agencies drive North American cloud migration under Federal Transit Administration mandates.
United States
State departments of transportation in California and Texas deploy digital twin systems for pre-event routing optimization on high-volume corridors. The Federal Transit Administration mandates open data standards for public transit interoperability, compelling agencies to upgrade legacy systems. Midwest trucking operators consolidate vendor relationships around integrated platform contracts that bundle telematics and regulatory reporting.
Germany
Siemens Mobility anchors intelligent transportation infrastructure deployments through deep hardware-software integration across urban networks. The EU AI Act imposes algorithmic accountability requirements on automated traffic management systems, forcing vendors to document decision logic and bias testing. Municipal authorities in Bavaria and North Rhine-Westphalia now require documentation of training data provenance as standard procurement criteria.
India
Federal infrastructure spending on urban mobility creates white space for cloud-based traffic platforms in metro areas lacking legacy hardware investments. The country's smart cities mission channels investment toward multimodal network optimization. Last-mile delivery providers in Mumbai and Bengaluru expand procurement fastest as e-commerce volumes strain legacy dispatch systems.
Japan
Defense and critical infrastructure operators retain on-premises installations within agency data centers, constrained by national cybersecurity frameworks and data sovereignty regulations. METI guidelines shape connected vehicle data governance standards. Industrial clusters in Kanto and Kansai regions prioritize air-gapped security for sensitive transportation networks despite higher total cost of ownership.
Singapore
Port authorities anchor maritime operations adoption for congestion prediction and container yard optimization. EU Green Deal emissions monitoring requirements accelerate sensor deployment across vessel routing systems. The city-state's intelligent transport systems integrate real-time sensor feeds with predictive algorithms for sub-second incident detection on high-density corridors.
Transportation Analytics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with software-native vendors capturing municipal cloud contracts while hardware-integrated incumbents defend entrenched maintenance relationships. The vendor base organizes around three strategic archetypes: hybrid cloud platform providers, hardware-software integrators, and ERP-linked fleet analytics specialists. Dominant competitive moves include API-first service delivery rearchitecture and compliance infrastructure investment under algorithmic transparency mandates.
Among technology conglomerates with transportation verticals, IBM Corporation represents the hybrid cloud platform archetype for government contract capture, while Siemens Mobility exemplifies hardware-software integration dominance in European deployments. SAP SE occupies a position linking ERP systems to fleet analytics modules, sustaining competitive positioning through enterprise software integration.
| Leading Market Players |
|---|
| IBM Corporation |
| Siemens Mobility |
| SAP SE |
| Oracle Corporation |
| Trimble Inc. |
| SAS Institute Inc. |
| Cubic Corporation |
| TomTom NV |
| INRIX Inc. |
| Others |
Cost & Logistics Intelligence
Edge processor fabrication costs in Taiwan and South Korea flow through sensor hardware pricing tiers, compressing margins for municipal traffic management deployments while elevating premiums for air-gapped on-premises installations in defense-sensitive networks.
Pricing Analysis
Volume concentration in cloud-based SaaS subscriptions diverges from premium capture in edge computing hardware bundles. Three-tier pricing structure across enterprise, mid-market, and municipal levels separates API-call volume commitments from customization depth and compliance documentation tiers. Pricing pressure stems from EU AI Act algorithmic audit requirements inflating vendor R&D overhead. Municipal agencies exhibit highest price sensitivity due to procurement inertia, while freight logistics operators absorb premium margins for predictive cargo tracking.
Supply Chain Analysis
Specialized geospatial data science labor shortages in Germany and the United States constrain implementation velocity for traffic analytics vendors. Semiconductor fabrication for roadside sensors concentrates in Taiwan, South Korea, and Japan, with raw material dependencies spanning silicon wafers, LiDAR components, and edge AI accelerators. Single-source vulnerability in advanced node chip production exposes hardware delivery timelines. Distribution runs through systems integrators and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transportation analytics sector sits at a cloud-to-edge architectural inflection point, with real-time roadside processing displacing legacy centralized data center deployments.
For Market Incumbents: Deploy compliance infrastructure as the defensive lever. IBM Corporation and Siemens Mobility should expand algorithmic documentation capabilities to capture EU AI Act-mandated procurement in Germany and France. Edge computing hardware-software integration protects against pure-play SaaS erosion in highway corridor deployments. Certification investment in U.S. Department of Transportation cybersecurity frameworks creates switching costs for municipal renewals. For New Entrants and Emerging Players: Municipal agencies in India's smart cities mission represent the most penetrable buyer segment, lacking entrenched legacy maintenance contracts that delay competitive displacement in North America and Europe. Cloud-native traffic platforms with API-first architectures bypass hardware integration barriers. Partnership with regional systems integrators accelerates deployment velocity where direct sales cycles extend beyond twelve months. For Investors and Strategic Acquirers: Federal Transit Administration open-data mandate enforcement is the leading indicator that replacement demand for integrated analytics platforms will accelerate across U.S. municipal agencies. Long-term viability favors vendors with hybrid cloud-edge architectural flexibility rather than pure-play point solutions. Acquisition targets should demonstrate documented algorithmic transparency protocols and established compliance infrastructure under evolving EU regulatory frameworks. Watch for consolidation signals when mid-sized trucking operators reject point-solution purchases in favor of bundled platform contracts.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Rearchitecture | Municipal cloud procurement in California and Texas favors vendors with elastic compute service delivery. |
| Algorithmic Compliance Certification | EU AI Act documentation requirements in Germany and France create procurement barriers for non-compliant vendors. |
| Edge Computing Hardware Integration | Highway operators on I-405 and I-35 corridors prioritize sub-second latency for collision avoidance systems. |
| Geospatial Talent Acquisition | Machine learning specialists with transportation domain expertise remain scarce in vendor scaling efforts. |
| Freight Logistics Platform Consolidation | Mid-sized Midwest trucking operators increasingly demand bundled telematics and regulatory reporting suites. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this transportation analytics market assessment. Primary interviews with municipal transportation directors, fleet operations managers, ITS systems integrators, and cloud platform procurement officers combined with Federal Transit Administration mandate documentation, EU ITS Directive compliance databases, and semiconductor import records. Bottom-up deployment volume estimates triangulated against top-down vendor revenue aggregation across cloud, edge, and hybrid infrastructure segments.
Data-stream reconciliation across sensor hardware shipment manifests, SaaS subscription billing records, and municipal contract award databases informed the analytical framework. Segmentation dimensions modeled include deployment topology, solution functional module, application operational domain, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted demand curves incorporating fuel price volatility indices and connected vehicle penetration trajectories. Edge processor supply constraints and EU AI Act implementation timelines served as industry-specific forecast modifiers across the projection horizon.
Caveats apply where semiconductor supply bottlenecks, algorithmic regulatory enforcement delays, or municipal procurement cycle extensions could materially shift the outlook. Forecasts reflect documented assumptions regarding cloud migration velocity and edge computing adoption thresholds. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Shared Mobility Market