
 Global Smart Highway Market | 2026-2036
Global Smart Highway Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Highway Market Foresight
Aftermarket service revenue from legacy toll-collection hardware is tilting toward cloud-based traffic management platforms. Siemens AG leverages its European installed base to anchor recurring software subscriptions across German and Austrian expressway networks. Huawei Technologies Co. Ltd. competes on manufacturing scale for roadside unit deployments across Middle Eastern and Southeast Asian markets. Cisco Systems Inc. specializes in edge-computing architectures that process vehicle-to-infrastructure data at sub-100-millisecond latency thresholds.
Smart highways integrate IoT sensors, fiber-optic communication backbones, and centralized AI analytics to monitor traffic density, surface conditions, and environmental parameters in real time, with primary purpose of reducing congestion-related fuel waste and collision incidence on high-volume corridors. IoT Sensors and AI Traffic Management capture the dominant share of current capital expenditure as transportation authorities prioritize real-time data acquisition over adaptive lighting retrofits. Connected Vehicle Systems represents the fastest-expanding technology segment as V2X protocol standardization enables interoperable communication between heterogeneous vehicle fleets and roadside infrastructure across Deployment categories spanning Urban Expressways and Freight Corridors.
The EU AI Act imposes conformity assessment requirements on automated traffic decision systems, while the US DOT Federal Highway Administration administers STIP funding eligibility criteria that favor shovel-ready smart infrastructure proposals with documented safety performance targets. China's MIIT enforces GB/T standards for connected vehicle security architectures that foreign suppliers must satisfy for national highway project participation. Stakeholders must monitor evolving procurement qualification frameworks that increasingly bundle cybersecurity certification with traditional technical compliance documentation.
Market Dynamics
Transportation authorities are accelerating procurement of AI traffic management systems following the EU AI Act's risk-based classification of automated decision-making infrastructure, forcing vendors to bundle cybersecurity certification with traditional technical compliance documentation.
Growth Catalysts
- EU AI Act Conformity Requirements:The risk-based classification of automated traffic decision systems mandates conformity assessments that upgrade legacy procurement frameworks, compelling transportation authorities to modernize infrastructure.
- GB-Standard Connected Vehicle Corridors:China's MIIT mandates national standards along Beijing-Shanghai-Tianjin freight routes, creating concentrated demand for interoperable roadside unit deployments.
- Edge-Computing Latency Thresholds:Sub-100-millisecond vehicle-to-infrastructure data processing enables real-time collision avoidance and congestion management on high-volume urban expressways.
Market Restraints
- Fiber-Optic Backbone Capital Intensity:Smart highway deployments require extensive trenching and cable laying, with material costs and right-of-way negotiations extending project timelines.
- Supplier Concentration in Semiconductor Components:Roadside unit manufacturers depend on concentrated Asian foundry capacity for specialized automotive-grade chips, exposing projects to supply volatility.
- Legacy Toll-Collection Hardware Lock-In:Existing proprietary systems across German and Austrian expressway networks create technical friction for cloud-based platform migration.
Strategic Opportunities
- Middle Eastern Expressway Modernization:Saudi Arabia and UAE transportation authorities are greenfielding smart infrastructure without legacy system burdens, enabling full V2X protocol implementation.
- Freight Corridor Electrification Integration:Smart highways are converging with overhead catenary and dynamic wireless charging for heavy-duty electric trucks along designated routes.
- STIP Funding Eligibility Criteria:The US DOT Federal Highway Administration prioritizes shovel-ready proposals with documented safety performance targets, favoring projects with pre-certified AI traffic management architectures.
Industry Challenges
- Cybersecurity Certification Timeline Compression:The EU AI Act's conformity assessment requirements must integrate with traditional technical compliance documentation, extending vendor qualification periods.
- V2X Protocol Standardization Fragmentation:Heterogeneous communication standards between vehicle fleets and roadside infrastructure create interoperability testing complexity across deployment categories.
- Cross-Functional Talent Scarcity:Transportation authorities lack personnel combining civil engineering, AI systems integration, and data analytics expertise for smart highway operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Highway Market |
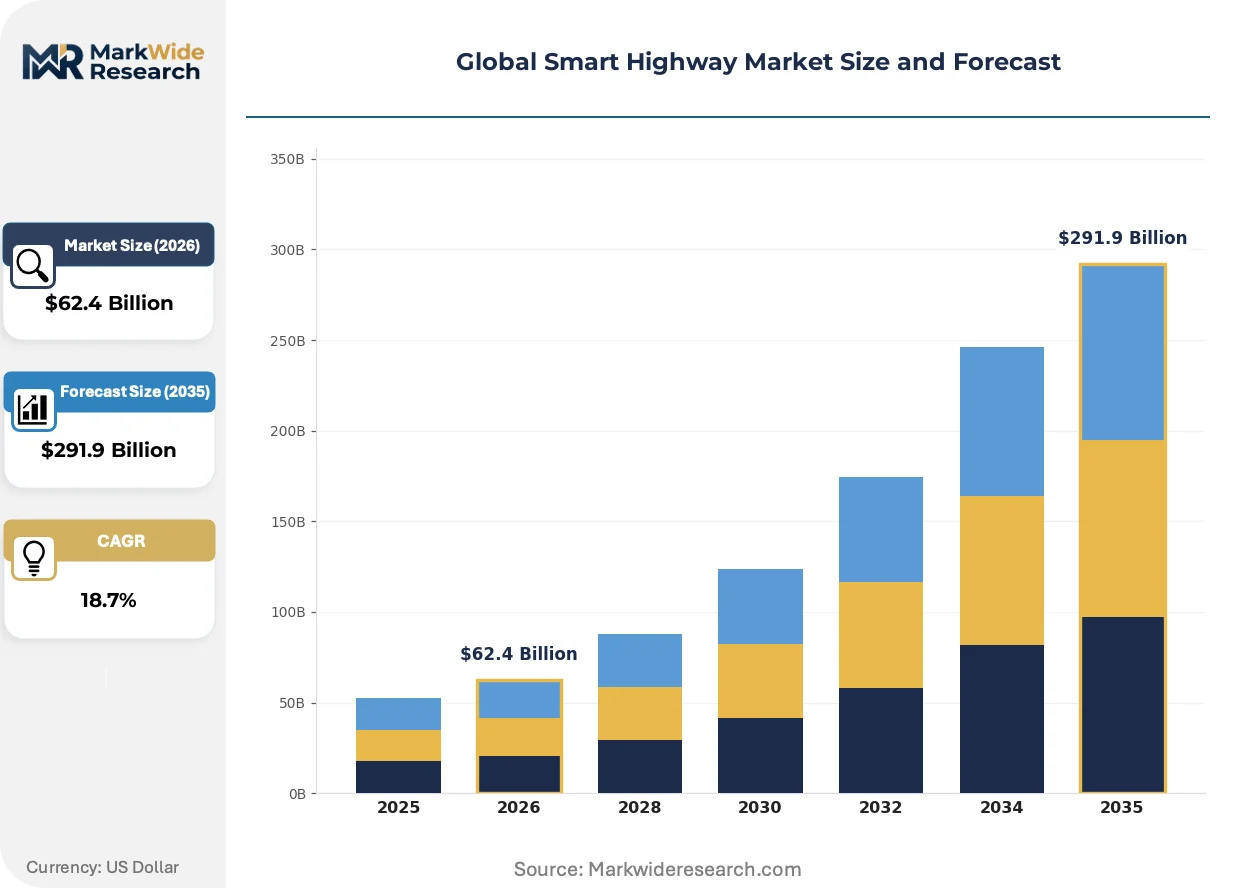
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $291.9 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, AI Traffic Management, Connected Vehicle Systems, Adaptive Lighting, Drone Surveillance Application: Traffic Flow Optimization, Incident Detection, Environmental Monitoring, Toll Collection, Infrastructure Maintenance Deployment: Urban Expressways, Suburban Roadways, Rural Roads, Toll Plazas, Freight Corridors End User: Transportation Authorities, Freight Operators, Emergency Services, Municipalities, Road Asset Managers |
| Companies Covered | Cisco Systems Inc., Huawei Technologies Co. Ltd., IBM Corporation, Kapsch TrafficCom AG, Siemens AG, Indra Sistemas S.A., Yunex Traffic, SWARCO, Conduent Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Highway Market Shifts & Advancements
Smart highway architecture is actively hybridizing edge computing with centralized cloud analytics, compressing the traditional separation between roadside data processing and back-end traffic management platforms.
Edge-computing architectures are processing vehicle-to-infrastructure data at sub-100-millisecond latency thresholds, enabling real-time hazard detection and adaptive signal control. German and Austrian expressway operators are deploying these systems most aggressively, driven by EU AI Act compliance deadlines. The technology is hybridizing traffic management functions that previously required separate roadside and centralized systems.
The EU AI Act imposes conformity assessment requirements on automated traffic decision systems, treating high-risk AI infrastructure as safety-critical equipment. Transportation authorities in Germany must now document algorithmic transparency and human oversight protocols before procurement approval. Vendors serving European markets are restructuring product documentation to satisfy both technical performance and algorithmic accountability standards.
Aftermarket service revenue from legacy toll-collection hardware is tilting toward cloud-based traffic management platforms, unbundling maintenance contracts from equipment ownership. Siemens AG anchors recurring software subscriptions across its European installed base, displacing traditional hardware replacement cycles. This pattern is most visible in Germany and Austria, where transportation authorities prioritize operational expenditure flexibility over capital-intensive infrastructure ownership.
Global Smart Highway Market Segmentation
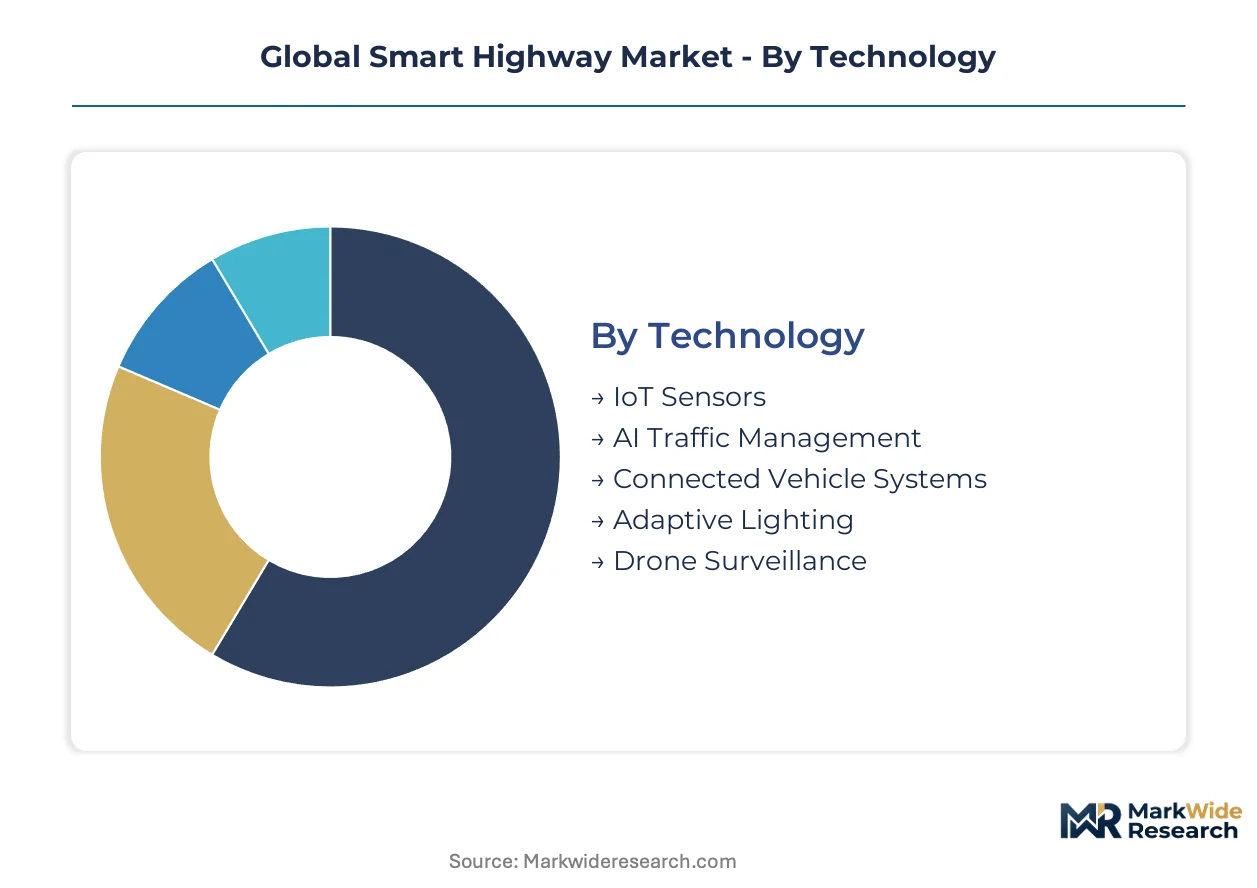
Smart highway procurement patterns diverge sharply across technology tiers and operational contexts. Transportation authorities prioritize segments with demonstrable safety outcomes and regulatory compliance pathways.
Technology:
After-sales service intensity concentrates in software-centric segments requiring continuous algorithm updates and cybersecurity patches.
- IoT Sensors:Fiber-optic and wireless sensor arrays embedded in pavement and roadside infrastructure monitor traffic density, surface conditions, and structural integrity. China's MIIT-mandated GB-standard corridors along Beijing-Shanghai-Tianjin freight routes are driving concentrated demand for ruggedized, automotive-grade sensor deployments.
- AI Traffic Management:Centralized platforms processing real-time data streams for predictive congestion modeling and automated signal optimization. The EU AI Act's conformity assessment requirements are forcing German transportation authorities to upgrade legacy procurement frameworks, accelerating vendor qualification for algorithmic transparency documentation.
- Connected Vehicle Systems:V2X protocol infrastructure enabling interoperable communication between heterogeneous vehicle fleets and roadside units. Saudi Arabia and UAE greenfield expressway projects implement full protocol stacks without legacy system constraints.
- Adaptive Lighting:LED arrays with dimming controls responsive to traffic volume and ambient conditions. Municipal deployments favor retrofit configurations over new-build integration.
- Drone Surveillance:Aerial monitoring systems for incident verification and emergency response coordination. Deployment remains concentrated in Middle Eastern markets with favorable airspace regulations.
IoT Sensors and AI Traffic Management hold the largest share; momentum sits with Connected Vehicle Systems as V2X standardization accelerates.
Application:
Cost tier differentiation separates capital-intensive infrastructure from operational expenditure platforms.
- Traffic Flow Optimization:Real-time signal timing adjustments and dynamic lane management reduce congestion-related fuel waste. Edge-computing architectures achieving sub-100-millisecond latency thresholds enable adaptive control on high-volume German and Austrian expressways.
- Incident Detection:Automated collision identification and emergency service dispatch systems. The US DOT Federal Highway Administration's STIP funding criteria prioritize proposals with documented safety performance targets, favoring pre-certified detection architectures.
- Environmental Monitoring:Air quality and noise level sensors supporting regulatory compliance reporting. European deployments integrate with CSRD disclosure requirements.
- Toll Collection:Legacy hardware maintenance contracts are tilting toward cloud-based platform subscriptions. Siemens AG anchors recurring revenue across its European installed base.
- Infrastructure Maintenance:Predictive analytics for pavement degradation and structural asset lifecycle management. Road asset managers prioritize condition-based maintenance over scheduled replacement.
Traffic Flow Optimization commands the largest deployment base; Incident Detection is climbing the fastest on safety-targeted funding eligibility.
Deployment:
Volume concentration tracks freight corridor electrification and urban congestion management priorities.
- Urban Expressways:High-density corridors requiring integrated sensor networks and real-time analytics platforms. Edge-computing deployments process vehicle-to-infrastructure data for collision avoidance in Germany's compliance-driven upgrade cycle.
- Freight Corridors:Designated routes integrating overhead catenary and dynamic wireless charging for heavy-duty electric trucks. China's eastern coastal provinces concentrate procurement for Beijing-Shanghai-Tianjin connectivity.
- Suburban Roadways:Moderate-density networks prioritizing cost-effective sensor coverage over full V2X implementation.
- Rural Roads:Sparse deployments focused on incident detection and emergency response connectivity.
- Toll Plazas:Transition zones between free-flow and controlled-access infrastructure requiring hybrid collection systems.
Urban Expressways represent the dominant deployment category; Freight Corridors are gaining share fastest on electrification convergence.
End User:
Customer type segmentation reflects divergent procurement authority and operational control structures.
- Transportation Authorities:Government agencies with mandate over arterial highway networks and regulatory compliance. German authorities bundle cybersecurity certification with technical documentation under EU AI Act frameworks.
- Road Asset Managers:Entities with lifecycle responsibility for pavement condition and structural integrity. These operators prioritize predictive maintenance platforms with outcome-based service contracting.
- Freight Operators:Logistics companies investing in corridor-specific V2X infrastructure for fleet optimization.
- Emergency Services:First responder agencies requiring prioritized incident data feeds and automated dispatch triggers.
- Municipalities:Local governments managing suburban and urban street networks with constrained capital budgets.
Transportation Authorities account for the largest procurement volume; Road Asset Managers are expanding most quickly on predictive maintenance platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's eastern coastal provinces show the least price elasticity, absorbing premium V2X infrastructure costs under MIIT-mandated corridor programs. German transportation authorities demonstrate moderate elasticity, balancing EU AI Act compliance premiums against operational savings. Middle Eastern greenfield markets accept high upfront capital for integrated systems without legacy migration burdens.
United States
The US DOT Federal Highway Administration's STIP funding criteria prioritize shovel-ready smart infrastructure proposals with documented safety performance targets. State transportation departments in California, Texas, and New York compete for federal matching funds requiring pre-certified AI traffic management architectures. The Northeast Corridor concentrates deployments where dense urban expressways justify edge-computing latency investments.
Germany
Transportation authorities accelerate AI traffic management procurement under EU AI Act conformity assessment deadlines for automated decision-making infrastructure. The KBA coordinates with federal ministries to bundle cybersecurity certification with traditional technical compliance documentation. Bavaria and Baden-Württemberg anchor the densest expressway upgrade activity, with Siemens AG leveraging installed base relationships for recurring software subscriptions.
China
MIIT mandates GB-standard connected vehicle corridors along Beijing-Shanghai-Tianjin freight routes, creating concentrated demand for ruggedized roadside units. The Yangtze River Delta and Pearl River Delta provinces absorb the highest capital expenditure volumes for IoT sensor and V2X deployments. Huawei Technologies Co. Ltd. competes on manufacturing scale for these domestic installations while exporting to Southeast Asian markets.
Saudi Arabia
The Ministry of Transport greenfields smart highway infrastructure without legacy toll-collection hardware lock-in, enabling full protocol stack implementation. NEOM and Riyadh anchor expressway modernization programs integrating drone surveillance with favorable airspace regulations. State-backed procurement favors integrated system vendors capable of delivering fiber-optic backbones and centralized AI analytics platforms.
United Arab Emirates
Dubai's Roads and Transport Authority deploys adaptive lighting and incident detection systems across urban expressway networks with performance-based maintenance contracting. Abu Dhabi transportation planners prioritize freight corridor electrification integration with dynamic wireless charging pilots. The federation's procurement frameworks emphasize outcome-based service models over capital-intensive infrastructure ownership.
Global Smart Highway Market Competitive Landscape
Capability concentration sits with European system integrators possessing decades of installed base relationships; scale advantage sits with Asian hardware manufacturers commanding semiconductor supply chains. The vendor base stratifies across three tiers: legacy toll-collection operators pivoting to cloud platforms, telecommunications equipment specialists capturing roadside unit deployments, and edge-computing architects optimizing sub-100-millisecond latency thresholds. Dominant competitive moves include strategic partnerships between sensor manufacturers and AI software providers, plus geographic expansion into greenfield Middle Eastern markets without legacy system constraints.
Within the European system integrator tier, Siemens AG and Kapsch TrafficCom AG exemplify vendors leveraging installed base relationships for recurring revenue transition. Cisco Systems Inc. occupies a position among edge-computing specialists, while Huawei Technologies Co. Ltd. represents the scale-driven manufacturing archetype for roadside infrastructure. These three companies collectively illustrate the competitive divergence between software-centric platform strategies and hardware-dominant deployment capabilities.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd. |
| IBM Corporation |
| Kapsch TrafficCom AG |
| Siemens AG |
| Indra Sistemas S.A. |
| Yunex Traffic |
| SWARCO |
| Conduent Incorporated |
| Others |
Supply & Pricing Matrix
Beijing-Shanghai-Tianjin freight corridors absorb premium V2X infrastructure costs under MIIT-mandated GB standards, concentrating procurement power among domestic suppliers while downstream transportation authorities face tiered service pricing based on cybersecurity certification tiers and edge-computing latency performance.
Pricing Analysis
After-sales service revenue from algorithm updates and cybersecurity patches anchors lifetime value capture across European installed bases. SaaS-tiered subscription models stratify across premium, standard, and economy tiers based on EU AI Act conformity assessment completion and sub-100-millisecond latency guarantees. Pricing pressure stems from semiconductor component volatility in Asian foundry markets. German transportation authorities demonstrate moderate price sensitivity balancing compliance premiums against operational savings, while Chinese provincial buyers absorb costs with minimal elasticity under state-mandated corridor programs.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates supply chain risk for automotive-grade chip sourcing. Roadside unit manufacturers draw from concentrated foundry capacity in Taiwan, South Korea, and China for specialized semiconductors. Fiber-optic cable, edge-computing hardware, and ruggedized sensor arrays constitute critical input dependencies. Single-source vulnerability in advanced node production exposes projects to allocation constraints. Distribution runs through systems integrators with established transportation authority relationships rather than direct vendor-to-buyer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart highway infrastructure exhibits defensive moat characteristics rooted in regulatory entrenchment, where EU AI Act conformity assessments and MIIT GB-standard certifications create multi-year qualification barriers that protect incumbent positions from rapid competitive displacement.
For Market Incumbents: Build switching-cost moats by bundling cybersecurity certification maintenance with multi-year software subscription lock-in. Deepen backward integration into edge-computing hardware design to reduce semiconductor supply volatility exposure. Prioritize capacity addition in Saudi Arabia and UAE greenfield markets before competitive saturation. For New Entrants and Emerging Players: Establish a beachhead in drone surveillance systems for Middle Eastern expressway networks with favorable airspace regulations. Target freight corridor electrification integration as the most penetrable segment given convergence with dynamic wireless charging pilots. Pursue outcome-based service contracting as the primary go-to-market angle to bypass capital-intensive infrastructure ownership barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-computing architects with sub-100-millisecond latency capabilities over legacy toll-collection hardware operators. Long-term viability rests on software-centric platform transitions with recurring revenue visibility. Monitor V2X protocol standardization convergence as the critical inflection signal for interoperability-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Bundling | EU AI Act conformity assessments force vendors to integrate algorithmic transparency documentation with technical compliance. |
| Edge-Computing Latency Investment | Sub-100-millisecond processing thresholds enable real-time collision avoidance on German and Austrian expressways. |
| Greenfield Market Expansion | Saudi Arabia and UAE procurement favors integrated system vendors without legacy migration burdens. |
| Freight Corridor Electrification Integration | Dynamic wireless charging pilots along Beijing-Shanghai-Tianjin routes converge smart highway and heavy-duty truck infrastructure. |
| Outcome-Based Service Contracting | UAE transportation authorities prioritize performance-based maintenance over capital-intensive infrastructure ownership models. |
Research Methodology
Desk research of regulatory filings, transportation authority procurement databases, and semiconductor trade flow data preceded structured interviews with smart highway program directors, roadside unit procurement leads, edge-computing platform engineers, and fiber-optic infrastructure contractors. Secondary validation drew from EU AI Act implementation guidance, MIIT GB-standard documentation, US DOT STIP funding criteria, and KBA conformity assessment protocols. Bottom-up segment sizing triangulated against top-down infrastructure spending forecasts from national transportation ministries.
Assumptions around V2X protocol standardization timelines, EU AI Act enforcement intensity, and MIIT corridor deployment schedules remained fixed across baseline scenarios while semiconductor supply volatility and greenfield market entry patterns were stress-tested through sensitivity bands. Segmentation modeling spanned technology tier, deployment category, application function, and end-user procurement authority. CAGRs were derived from infrastructure investment trajectories weighted by regulatory compliance deadlines and safety-targeted funding eligibility.
Sensitivities concentrate around V2X interoperability breakthroughs, EU AI Act conformity assessment timeline compression, and foundry capacity allocation shifts for automotive-grade chips. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Car E-Hailing Market
Smart Transportation Solutions
Asia Pacific Hyperloop Technology Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Car Sharing Market