
 Consumer Telematics Market | 2026-2036
Consumer Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Telematics Market Analysis
Subscription-based fleet leasing and asset-light mobility service models are narrowing the competitive field in consumer telematics. Continental AG leverages its captive semiconductor supply to control hardware cost curves across integrated cockpit platforms. Robert Bosch GmbH anchors its position through manufacturing scale in sensor fusion modules that feed telematics control units. Verizon competes on channel dominance, embedding connectivity plans directly into dealer-finance packages for personal vehicle buyers.
Consumer telematics denotes the two-way data exchange between vehicles and external networks using onboard diagnostics, cellular modems, and satellite positioning to enable real-time location tracking, driver behavior profiling, and predictive maintenance alerts. Systems typically integrate GNSS receivers with CAN bus interfaces sampling at 10 Hz to capture acceleration, braking, and steering telemetry for insurance risk scoring and fleet optimization algorithms. Cellular deployment dominates the technology stack as 5G RedCap modules displace legacy 2G fallback circuits in cost-sensitive installations. Cloud-based deployment is expanding fastest among ride-sharing services requiring elastic compute for dynamic pricing and demand forecasting. Insurance application segments concentrate margin pools where granular driving data enables individualized premium actuarial models.
FCC spectrum allocations shape device certification requirements for cellular telematics hardware sold in the United States. EMA type-approval frameworks and GDPR data-governance rules constrain cross-border data routing architectures for European fleet operators. NHTSA event data recorder mandates and EPA emissions monitoring protocols create dual-compliance obligations for OEM-embedded systems serving North American passenger vehicles. Stakeholders must decide whether to build in-house data analytics layers or partner with specialized actuarial platforms as insurance carriers tighten API specifications for real-time risk scoring.
Market Dynamics
Cellular connectivity mandates embedded in European type-approval frameworks are accelerating hardware refresh cycles across passenger vehicle fleets, compressing replacement timelines for legacy telematics modules and reshaping supplier order books.
Growth Catalysts
- EMA Type-Approval Mandates:European cellular connectivity requirements for new vehicle registrations force OEMs to embed compliant telematics hardware, creating baseline demand across Germany, France, and Italy passenger car production lines.
- Usage-Based Insurance Expansion:Insurance carriers in the United States and United Kingdom are deploying granular driving telemetry for individualized risk scoring, pulling hardware installations through fleet and personal vehicle channels.
- 5G RedCap Module Proliferation:Low-complexity 5G chipsets are replacing legacy 2G fallback circuits in cost-sensitive aftermarket installations, expanding addressable volume in emerging market vehicle parc upgrades.
Market Restraints
- Semiconductor Supply Concentration:Telematics control unit production depends on concentrated advanced node fabrication capacity in Taiwan and South Korea, exposing hardware vendors to allocation volatility during demand spikes.
- GDPR Data Governance Friction:European cross-border fleet operations face constrained data routing architectures under GDPR localization requirements, increasing compliance overhead for multi-national telematics service providers.
- Cellular Module Cost Structure:Integrated GNSS-cellular chipsets carry premium pricing relative to discrete component alternatives, pressuring margin structures in price-sensitive aftermarket installations.
Strategic Opportunities
- India Fleet Digitization Gap:Commercial vehicle telematics penetration remains underdeveloped across India interstate logistics corridors, presenting first-mover positioning for hardware-software bundled offerings.
- Predictive Maintenance Convergence:Integration of CAN bus telemetry with machine learning diagnostics creates service revenue streams for component suppliers targeting commercial fleet uptime optimization.
- Dealer-Finance Channel Embedding:Connectivity plan bundling into vehicle retail finance packages opens direct consumer acquisition paths bypassing traditional aftermarket distribution.
Industry Challenges
- Embedded Systems Integration Complexity:OEM telematics deployments require synchronization with legacy vehicle network architectures, extending validation timelines and engineering resource allocation.
- Actuarial Platform API Standardization:Insurance carriers maintain heterogeneous data format specifications, forcing telematics providers to maintain multiple integration layers for carrier connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Telematics Market |
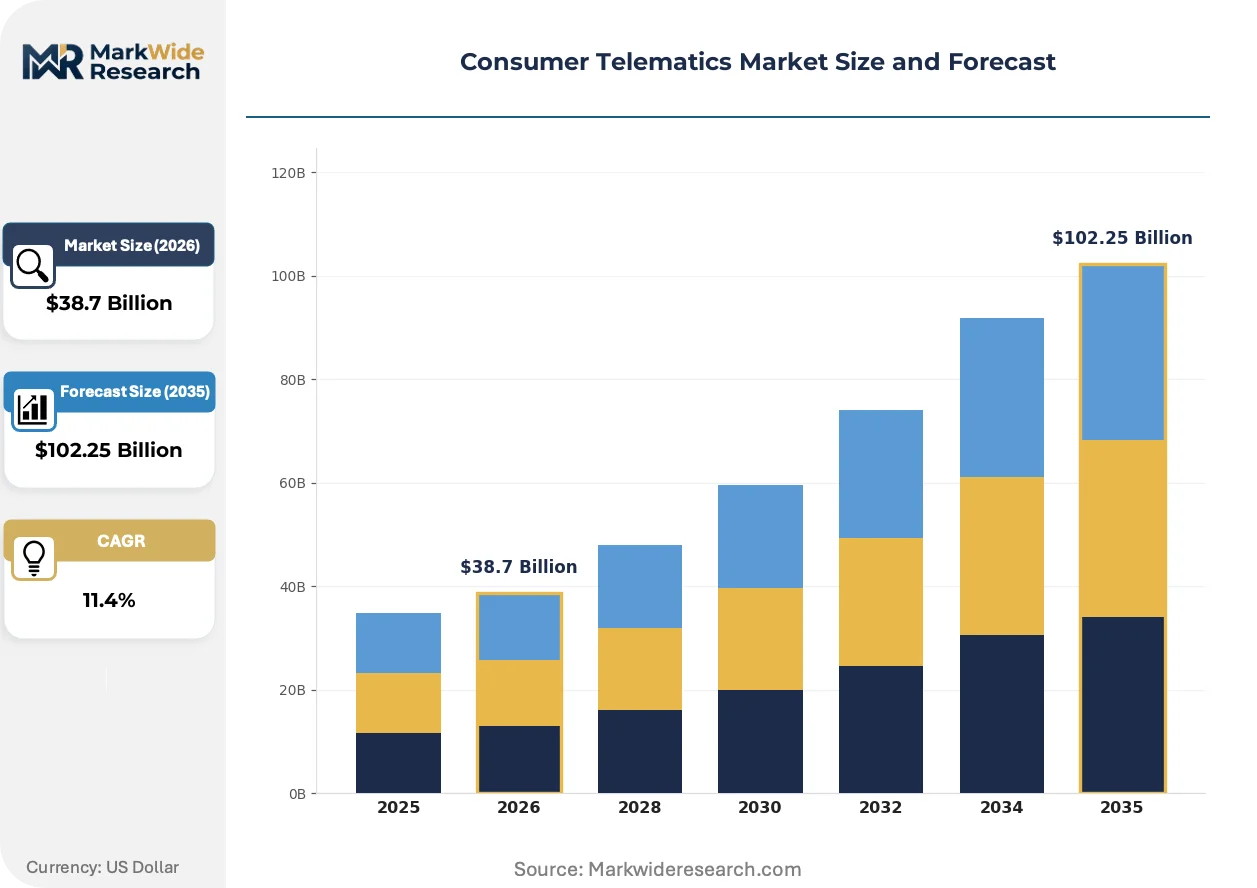
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Bluetooth, Wi-Fi, Cellular Application: Fleet Management, Vehicle Tracking, Road Safety, Insurance End User: Personal Vehicles, Commercial Fleets, Ride-Sharing Services, Logistics Deployment: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | Continental AG, Robert Bosch GmbH, LG Electronics, Harman International, Verizon, TomTom, Denso Corporation, Geotab, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Telematics Market Emerging Trajectories
Real-time data processing architectures and edge-compute deployment models are restructuring how driving telemetry flows from vehicle to cloud, compressing latency requirements and reshaping hardware specification priorities.
5G RedCap modules are collapsing the cost-performance tradeoff that previously separated premium OEM-embedded systems from aftermarket alternatives. Fleet operators in Germany and the United States are adopting RedCap-based retrofit kits at accelerating pace. This technology convergence is collapsing the historical three-tier hardware segmentation into two dominant performance bands.
GDPR data-localization enforcement is tightening cross-border telemetry routing for European fleet operators. The regulation forces architecture decisions that segment data processing across jurisdictional boundaries. Multi-national logistics providers operating between Germany, Poland, and Czechia are deploying region-locked edge nodes to maintain compliance.
Fleet procurement departments are consolidating telematics vendor relationships around integrated platform providers. Discrete hardware sourcing from specialized suppliers is giving way to bundled hardware-software-service contracts with single accountability. This concentration is most visible in United States long-haul trucking and United Kingdom last-mile delivery verticals.
Consumer Telematics Market Segmentation
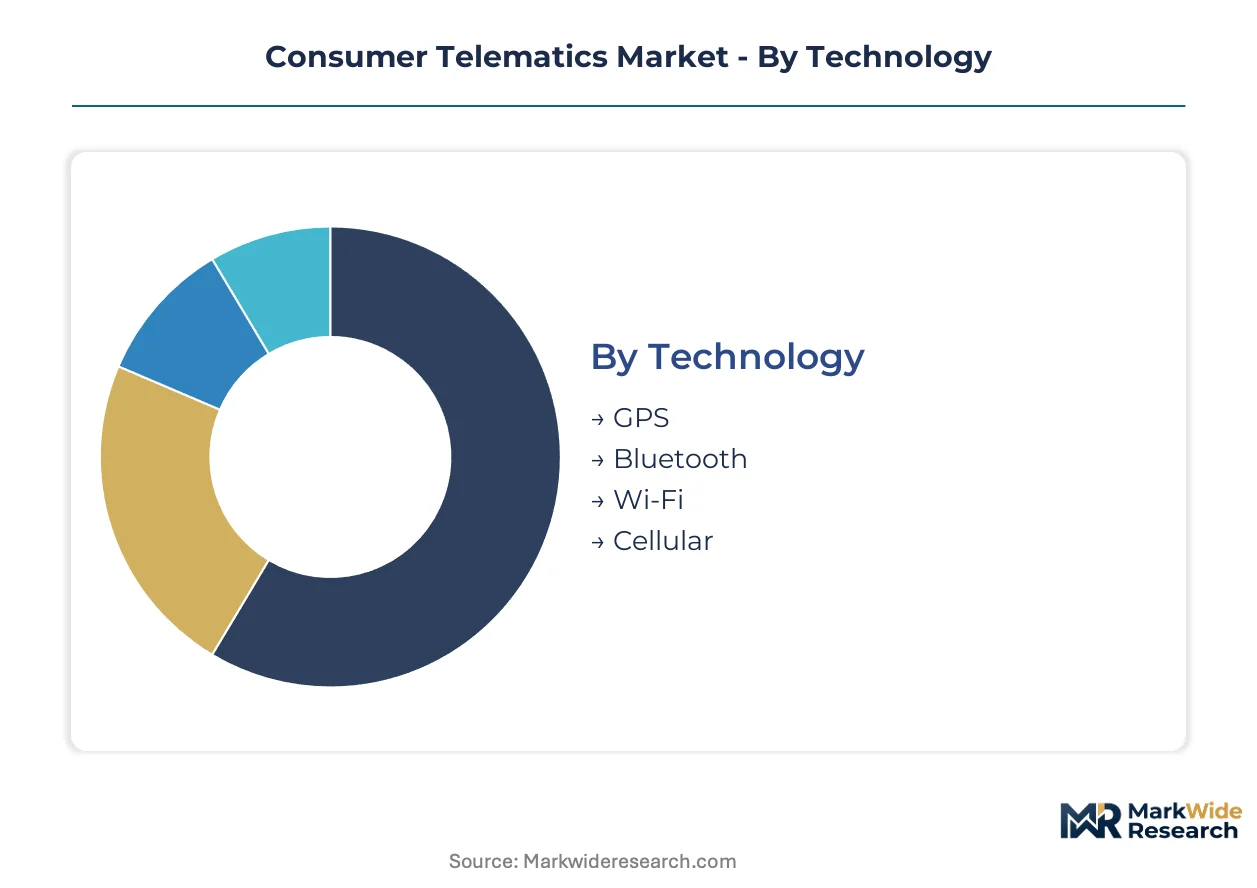
Segmentation in consumer telematics reveals how hardware specifications, connectivity protocols, and deployment architectures align with distinct value capture models across insurance, fleet operations, and mobility services. Understanding these divisions exposes where margin pools concentrate and which technology transitions reshape competitive positioning.
Technology:
GPS, Bluetooth, Wi-Fi, and Cellular solutions span a use-case spectrum from low-cost proximity sensing to high-bandwidth real-time streaming, with each protocol commanding distinct hardware cost structures and data throughput capabilities.
- Cellular:Integrated GNSS-cellular chipsets enable continuous two-way data exchange with external networks, supporting real-time driver behavior profiling and predictive maintenance alerts. Demand concentrates in Germany and United States passenger vehicle OEM installations, pulled by EMA type-approval mandates and usage-based insurance carrier requirements. 5G RedCap modules are displacing legacy 2G fallback circuits in cost-sensitive aftermarket retrofits.
- GPS:Satellite positioning receivers provide foundational location telemetry for asset tracking and geofencing applications, typically sampling at 10 Hz through CAN bus interfaces. Fleet operators in United States long-haul trucking and United Kingdom last-mile delivery verticals anchor volume, driven by route optimization algorithms and fuel consumption monitoring.
- Bluetooth:Short-range wireless protocol enables smartphone-tethered telematics for personal vehicle owners seeking aftermarket driver scoring without embedded cellular subscriptions. Lower hardware costs attract price-sensitive personal vehicle segments in emerging market vehicle parc upgrades.
- Wi-Fi:High-bandwidth local connectivity supports fleet depot data offloading and over-the-air software updates, reducing recurring cellular data charges for commercial operators with predictable return-to-base patterns.
Established volume favors GPS; emerging adoption favors Cellular.
Application:
Application segments track how telematics data transforms into monetizable services across risk transfer, asset management, and safety compliance domains.
- Insurance:Granular driving telemetry enables individualized premium actuarial models through acceleration, braking, and steering pattern analysis. United States and United Kingdom carriers are tightening API specifications for real-time risk scoring, pulling hardware installations through fleet and personal vehicle channels. Cloud-based deployment expands fastest among carriers requiring elastic compute for dynamic pricing models.
- Fleet Management:Integrated platform solutions consolidate vehicle location, driver behavior, and maintenance scheduling for commercial operators. Procurement departments in United States long-haul trucking and United Kingdom last-mile delivery are consolidating vendor relationships around bundled hardware-software-service contracts with single accountability.
- Vehicle Tracking:Core location monitoring for theft recovery and asset visibility, predominantly serving logistics providers and rental fleet operators with compliance-driven deployment requirements.
- Road Safety:Event data recording and emergency response triggering, shaped by NHTSA event data recorder mandates in North American passenger vehicles and equivalent European type-approval frameworks.
Insurance applications command premium margins; fleet management anchors installed base expansion.
End User:
End user categories reflect divergent procurement patterns between individual consumers, enterprise fleet operators, and platform-mediated mobility services.
- Commercial Fleets:Enterprise operators with centralized procurement functions demand integrated platform solutions with predictive maintenance convergence. India interstate logistics corridors present underdeveloped penetration, creating first-mover positioning for hardware-software bundled offerings targeting uptime optimization.
- Personal Vehicles:Individual owners acquire telematics through OEM-embedded systems or aftermarket retrofits, with dealer-finance channel embedding of connectivity plans opening direct consumer acquisition paths bypassing traditional aftermarket distribution.
- Ride-Sharing Services:Platform-mediated mobility services require elastic cloud compute for dynamic pricing and demand forecasting, driving fastest expansion in cloud-based deployment architectures.
- Logistics:Multi-national logistics providers operating between Germany, Poland, and Czechia deploy region-locked edge nodes to maintain GDPR compliance across cross-border telemetry routing.
Commercial fleets dominate current revenue; ride-sharing services are climbing the fastest.
Deployment:
Deployment architectures determine where data processing occurs and how compliance obligations distribute across cloud, edge, and on-premise infrastructure.
- Cloud-Based:Elastic compute resources support dynamic scaling for demand forecasting and real-time pricing algorithms. Ride-sharing services and insurance carriers with variable data volumes favor this model for operational flexibility.
- Hybrid:Split processing between vehicle-edge and cloud enables GDPR-compliant data localization while preserving centralized analytics capabilities. European multi-national fleet operators adopt this architecture to satisfy cross-border data governance requirements.
- On-Premise:Dedicated infrastructure for operators with stringent data sovereignty requirements or predictable, high-volume processing loads that justify capital expenditure over recurring cloud subscriptions.
- Others:Emerging edge-compute deployment models with region-locked processing nodes for jurisdictional compliance in fragmented regulatory environments.
Hybrid deployment gains share fastest among compliance-constrained operators; cloud-based leads absolute volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA type-approval mandates are reshaping hardware deployment timelines across European passenger vehicle production, while FCC spectrum allocations and NHTSA event data recorder requirements create dual-compliance architectures in North American markets. Cellular connectivity obligations embedded in vehicle registration frameworks are compressing replacement cycles for legacy telematics modules.
Germany
OEM-installed telematics penetration in passenger vehicles leads regional adoption curves, with KBA type-approval processes enforcing embedded cellular hardware for new registrations. GDPR data-localization requirements constrain cross-border telemetry routing for fleet operators managing multi-national logistics. The Stuttgart automotive cluster concentrates supplier engineering resources for integrated cockpit platform development.
United States
Usage-based insurance carriers deploy granular driving telemetry for individualized risk scoring, pulling hardware installations through fleet and personal vehicle channels. FCC device certification requirements shape cellular telematics hardware specifications for aftermarket and embedded systems. Michigan and Ohio automotive corridors anchor OEM telematics control unit validation and production.
United Kingdom
Insurance application segments concentrate margin pools where driving data enables premium actuarial individualization. GDPR compliance obligations segment data processing architectures for cross-border fleet operations serving European logistics routes. London and Midlands logistics hubs drive last-mile delivery telematics procurement consolidation.
India
Commercial vehicle telematics penetration remains underdeveloped across interstate logistics corridors, presenting positioning opportunities for hardware-software bundled offerings. TRAI spectrum management frameworks govern cellular module certification for aftermarket installations. Maharashtra and Gujarat manufacturing clusters are emerging as assembly locations for cost-sensitive telematics retrofit kits.
South Korea
Advanced node semiconductor fabrication capacity concentrates telematics control unit component supply, exposing hardware vendors to allocation volatility during demand spikes. MIIT-equivalent standards coordination governs cellular module integration for regional vehicle production. Seoul metropolitan area electronics clusters anchor sensor fusion module and integrated chipset design.
Consumer Telematics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Automotive Tier 1 suppliers leverage captive semiconductor supply and manufacturing scale advantages. Telecommunications carriers embed connectivity plans into dealer-finance packages. Technology specialists concentrate on sensor fusion and location intelligence software. Dominant competitive moves include strategic partnerships between hardware vendors and insurance actuarial platforms, plus portfolio diversification into predictive maintenance service layers.
Among Germany-based automotive suppliers, Continental AG and Robert Bosch GmbH exemplify integrated platform archetypes combining hardware manufacturing with embedded software stacks. Verizon occupies a position representing telecommunications carrier channel control, embedding connectivity subscriptions directly into vehicle retail finance structures. These three anchors illustrate the competitive tension between manufacturing-scale specialists and distribution-controlling service providers reshaping customer acquisition economics.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| LG Electronics |
| Harman International |
| Verizon |
| TomTom |
| Denso Corporation |
| Geotab |
| AT&T |
| Others |
Supply Flow & Price Mechanics
Taiwan and South Korea semiconductor fabrication capacity concentration anchors telematics control unit cost structures, with advanced node allocation volatility feeding directly into hardware vendor margin compression and tiered pricing spreads across OEM-embedded and aftermarket segments.
Pricing Analysis
Certification level (EMA type-approval versus aftermarket self-certification) creates the primary spread between premium and economy hardware tiers. Subscription-based SaaS pricing dominates insurance and fleet management applications, while transactional per-unit hardware sales persist in emerging market retrofit channels. Cost compression in aftermarket cellular modules intensifies as 5G RedCap chipsets commoditize, with price sensitivity highest among India commercial fleet operators and lowest among Germany OEM platform integrators.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Taiwan semiconductor foundries shape working capital requirements for telematics hardware assemblers. Component sourcing draws from South Korea memory modules, Taiwan cellular baseband processors, and China passive component clusters. Single-source vulnerability in advanced node fabrication exposes vendors to allocation rationing during demand spikes. Distribution runs through Tier 1 automotive supplier channels for OEM-embedded systems and electronics distributors for aftermarket retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumer telematics functions as a service-attach opportunity where predictive maintenance and usage-based insurance data layers expand faster than underlying hardware shipments, rewarding platform providers with recurring revenue architectures over discrete device vendors.
For Market Incumbents: Harden embedded software stack differentiation against modular hardware commoditization by deepening sensor fusion algorithm IP and securing exclusive dealer-finance channel embedding partnerships. Priority investment in GDPR-compliant hybrid cloud architectures defends European fleet operator relationships against compliance-focused challengers. For New Entrants and Emerging Players: India interstate logistics corridors offer the most penetrable white space for hardware-software bundled offerings targeting uptime optimization in underdigitized commercial vehicle segments. A dealer-direct go-to-market angle bypasses fragmented aftermarket distribution and captures first-mover positioning before incumbent platform consolidation accelerates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telematics platform specialists holding sticky fleet management contracts but lacking predictive maintenance service layer depth. The inflection signal to watch is insurance carrier API standardization convergence, which will determine whether point-solution hardware vendors or integrated platform providers capture margin pool consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| 5G RedCap Module Integration | RedCap chipsets collapse cost-performance gaps between OEM and aftermarket hardware tiers. |
| Predictive Maintenance Service Layer | CAN bus telemetry convergence with machine learning creates recurring revenue streams beyond device sales. |
| Dealer-Finance Channel Embedding | Connectivity plan bundling into retail finance packages captures consumer acquisition economics. |
| GDPR-Compliant Hybrid Cloud Architecture | Region-locked edge nodes satisfy European cross-border data governance for fleet operators. |
| Insurance Actuarial Platform Partnership | Real-time risk scoring API integration secures carrier-driven hardware pull-through demand. |
Methodological Framework
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, insurance carrier actuarial directors, and fleet operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EMA type-approval filings, FCC device certification databases, vehicle production registration data, and TRAI spectrum allocation records. Bottom-up hardware shipment modeling triangulated against top-down service revenue estimates from cloud platform disclosures.
Scenario-bracketing framed sensitivity analysis across regulatory acceleration, semiconductor supply disruption, and insurance carrier consolidation pathways. Segmentation dimensions spanned connectivity protocol, deployment architecture, application vertical, and end-user procurement archetype across the projection horizon. CAGRs derived from installed base growth, replacement cycle compression, and service attach rate expansion rather than extrapolated trend fitting.
Practitioners should monitor EMA mandate enforcement timing, RedCap module cost curves, and carrier API specification convergence for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market