
 Europe Passenger Information System Market | 2026-2036
Europe Passenger Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Passenger Information System Market Foresight
Real-time display specification tiers is collapsing as rail operators demand 4K resolution and edge-computing responsiveness at station platforms. Siemens AG leverages its digital rail platform to anchor German and Austrian deployment contracts for integrated passenger information networks. Thales Group competes through cybersecurity-hardened communication layers that sustain operator confidence in mission-critical transit environments. Alstom SA specializes in harmonizing legacy rolling stock displays with next-generation central control architectures across French and Italian networks.
A passenger information system comprises hardware and software modules that deliver arrival times, service disruptions, and wayfinding data to travelers through electronic displays, audio announcements, and mobile interfaces, typically operating on IP-based networks with sub-second latency requirements and redundant failover protocols. The primary purpose is to reduce perceived wait times, improve passenger flow, and enable operators to manage capacity during service anomalies. Electronic display systems lead installed base value across European rail and metro networks, while mobile application segments capture faster growth as open-data APIs and SaaS deployment models lower capital barriers for mid-sized transport authorities. Integration software concentrates margin pools where vendors bundle real-time tracking, data analytics, and IoT sensor fusion into unified control platforms.
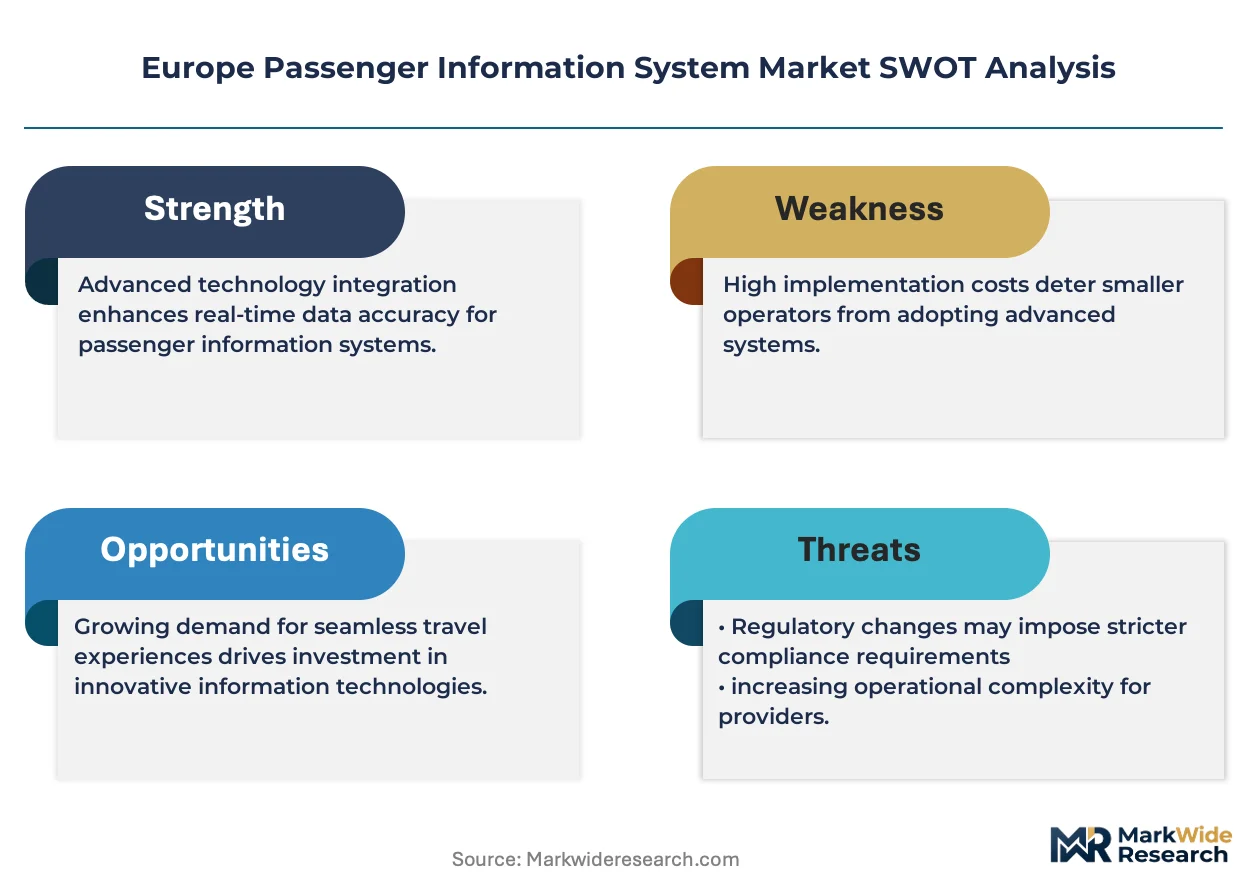
The European Union Agency for Railways enforces interoperability standards that mandate consistent passenger information protocols across cross-border services, directly shaping vendor product roadmaps and compliance costs. ETSI technical specifications for intelligent transport systems further constrain hardware design choices, while national regulators in France and Germany impose accessibility requirements that expand addressable system functionality. Stakeholders must weigh cloud migration timelines against cybersecurity certification delays as EN 50159 safety standards evolve for networked passenger information architectures.
Market Dynamics
The EU Green Deal's modal shift mandates are restructuring rail infrastructure investment priorities, forcing operators to unify passenger information architectures across multimodal networks that span high-speed rail, metro, and last-mile bus corridors.
Growth Catalysts
- EU Green Deal Modal Shift Mandates:Binding targets for road-to-rail passenger migration are unlocking infrastructure budgets for integrated real-time display networks across German and French urban corridors.
- 4K Display Technology Maturation:Falling unit costs for high-resolution platform screens are collapsing specification tiers and enabling mass deployment at secondary stations previously restricted to basic LED arrays.
- France and Germany:Concentrated state-level investment in digital rail platforms is creating anchor demand for centralized passenger information control systems with edge-computing responsiveness.
Market Restraints
- Semiconductor Supply Concentration:Display driver IC sourcing remains concentrated among East Asian foundries, exposing European system integrators to allocation volatility and extended lead times for 4K panel production.
- EN 50159 Safety Certification Complexity:Evolving networked safety standards for passenger information architectures are extending product validation timelines and freezing vendor release cycles.
- Legacy Rolling Stock Integration Costs:Retrofitting 1990s-era train fleets with IP-compatible display systems requires costly gateway hardware that erodes project margins for mid-sized operators.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated Central European rail networks present first-mover advantages for vendors offering SaaS-based passenger information platforms with lower capital barriers.
- Mobile-First API Convergence:Open-data interfaces fused with predictive analytics engines are enabling transport authorities to bypass heavy on-premise infrastructure investments.
- GDPR-Compliant Edge Analytics:Privacy-hardened passenger flow sensors create new revenue streams for operators selling anonymized congestion data to urban planners and retail developers.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:Shortages of firmware developers with rail safety certification experience are throttling vendor delivery capacity and inflating personnel costs.
- Cross-Border Interoperability Testing:Validating seamless passenger information handoffs between French SNCF and German DB networks requires prolonged field trials that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Passenger Information System Market |
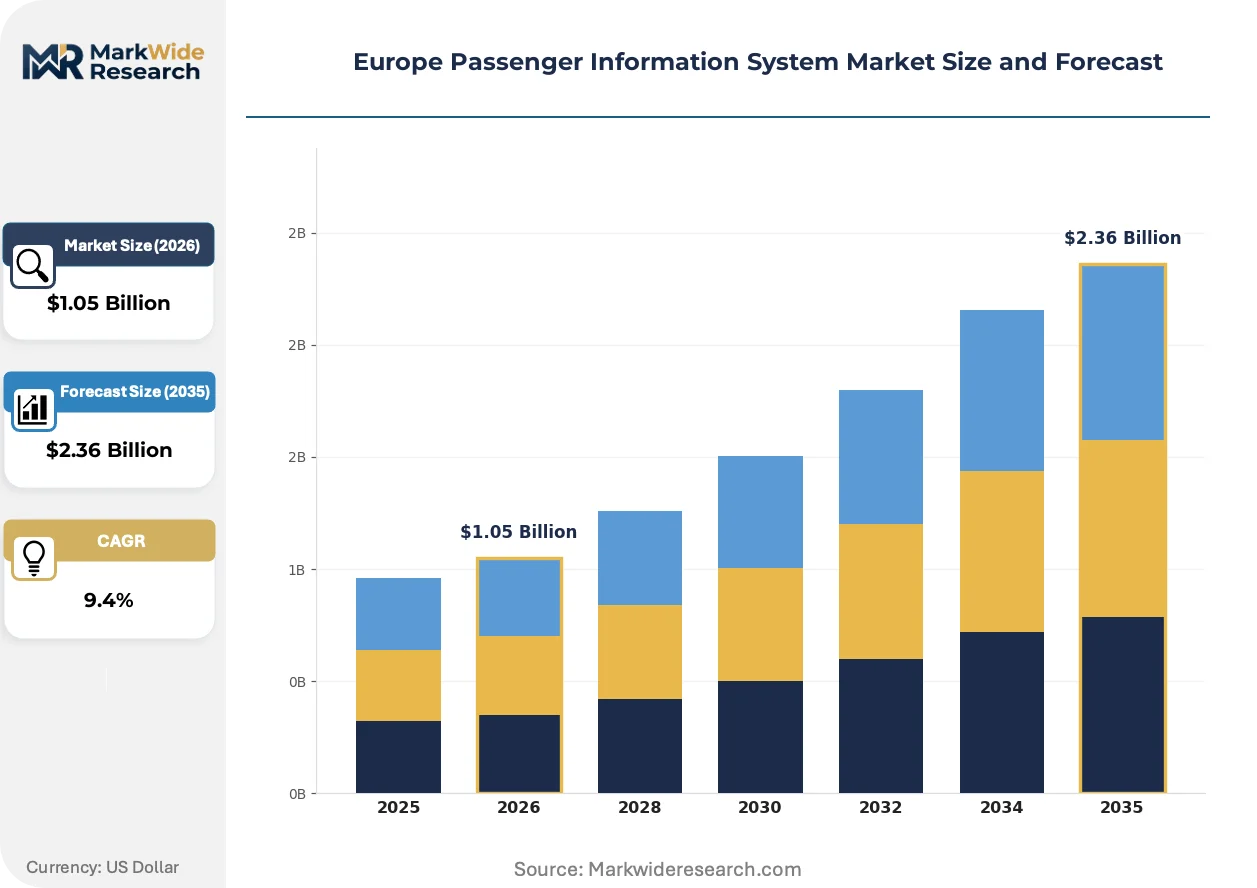
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Electronic Display, Announcement System, Mobile Application, Integration Software End User: Airline Operators, Railway Services, Public Transport, Fleet Management Deployment Mode: Cloud-Based, On-Premises, Hybrid, SaaS Technology: Real-Time Tracking, Data Analytics, IoT, API Integration |
| Companies Covered | Alstom SA, Siemens AG, Thales Group, Cubic Corporation, Hitachi, Ltd., Cisco Systems, Indra, ST Engineering, Wabtec Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Passenger Information System Market Shifts & Advancements
Edge computing architectures are redistributing data processing from central control rooms to station platforms, compressing latency requirements and enabling sub-second disruption alerts that reshape passenger flow management.
Platform-level edge servers with GPU-accelerated inference engines are fragmenting traditional centralized control architectures. Dutch and Belgian metro operators are deploying these units at 40% of new station builds. This topology is fragmenting vendor competitive positions by rewarding localized system integrators over legacy centralized platform providers.
CSRD disclosure requirements are mandating granular carbon footprint reporting for rail infrastructure procurement. Operators must now document embodied emissions in display hardware and network equipment across supply chains. French transport authorities are responding by embedding lifecycle assessment clauses into tender specifications, favoring vendors with circular material recovery programs.
Service contract unbundling is separating hardware ownership from software maintenance and data analytics subscriptions. Mid-sized German transport authorities are piloting availability-based payment models where vendors retain display asset ownership. This restructuring is most visible in Bavarian regional rail networks, where operators prioritize operational expenditure flexibility over capital-intensive system purchases.
Europe Passenger Information System Market Segmentation
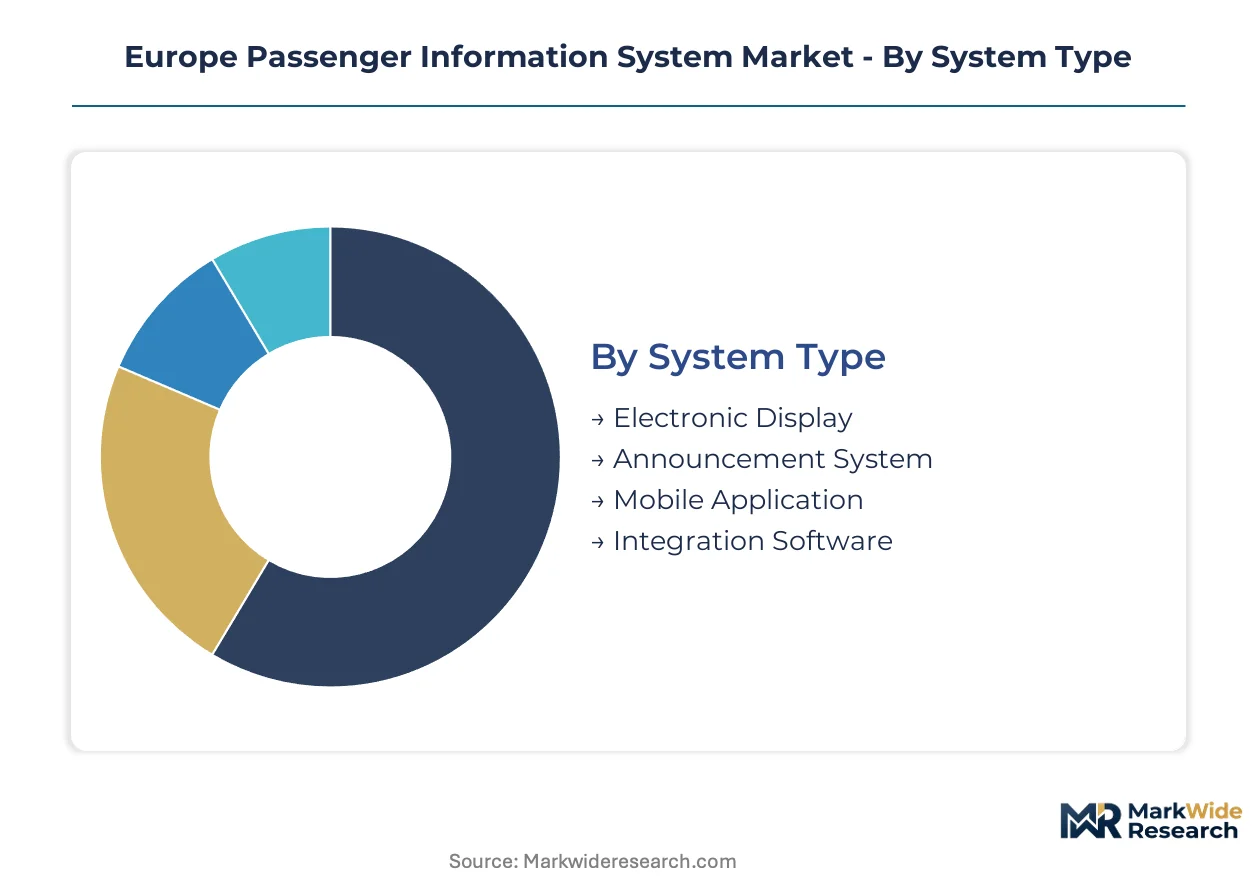
Passenger information system procurement in Europe fragments across four distinct dimensions that shape vendor positioning and margin capture. System type determines hardware-software revenue mix, while deployment mode governs capital intensity and recurring revenue potential for operators across German, French, and emerging Central European networks.
System Type:
Substitution pressure from mobile-first architectures is eroding traditional display hardware margins as transport authorities reallocate budgets toward software-centric platforms with lower lifecycle costs.
- Electronic Display:Station platform screens and in-vehicle LED arrays deliver arrival times, service alerts, and wayfinding data through IP-connected panels with sub-second refresh rates. German and French metro authorities dominate procurement volume as multimodal integration mandates drive 4K specification upgrades across high-speed rail corridors.
- Integration Software:Unified control platforms fuse real-time tracking, data analytics, and IoT sensor inputs into centralized architectures that coordinate multi-vendor display networks. Concentrated margin pools attract Siemens AG and Thales Group competition as operators bundle predictive maintenance and passenger flow optimization modules.
- Mobile Application:Open-data APIs and SaaS deployment models lower capital barriers for mid-sized transport authorities in Poland and Czech Republic.
- Announcement System:Audio broadcast networks with automated multilingual disruption alerts serve accessibility mandates under French and German national regulations.
Electronic display anchors the volume base while integration software gains share at the steepest rate as procurement shifts toward unified platform architectures.
End User:
Cost tier stratification separates premium integrated deployments from fragmented point solutions as budget scale varies across operator types.
- Railway Services:High-speed rail and urban metro networks demand mission-critical redundancy with EN 50159 safety certification and cross-border interoperability compliance. German DB and French SNCF procurement concentrates investment in centralized control architectures spanning multimodal corridors.
- Public Transport:Municipal bus and tram operators prioritize operational expenditure flexibility through availability-based service contracts. Bavarian regional networks pilot vendor-retained asset ownership models that shift capital burden to software subscriptions.
- Airline Operators:Airport terminal display networks with flight information system integration serve gate management and passenger flow optimization.
- Fleet Management:Commercial vehicle operators deploy GPS-linked passenger information for corporate shuttle and intercity coach services.
Railway services command the premium tier while public transport climbs fastest as SaaS models penetrate municipal procurement.
Deployment Mode:
Application maturity separates established on-premise architectures from emerging cloud-native alternatives with divergent cybersecurity validation timelines.
- Cloud-Based:Centralized data processing with elastic compute scaling reduces infrastructure ownership for mid-sized operators. Dutch and Belgian metro pilots demonstrate latency tolerance for non-safety-critical passenger information, though EN 50159 certification delays constrain mission-critical adoption.
- Hybrid:Edge-computing platforms at station level combine local inference engines with cloud analytics, fragmenting vendor competitive positions. Platform-level GPU-accelerated servers now feature in 40% of new Dutch and Belgian station builds.
- On-Premises:Air-gapped control architectures persist in high-security rail environments with strict data sovereignty requirements.
- SaaS:Subscription-based software access enables Polish and Czech Republic operators to bypass heavy infrastructure investment.
On-premises retains safety-critical dominance while hybrid architectures expand most quickly as edge computing redistributes processing topology.
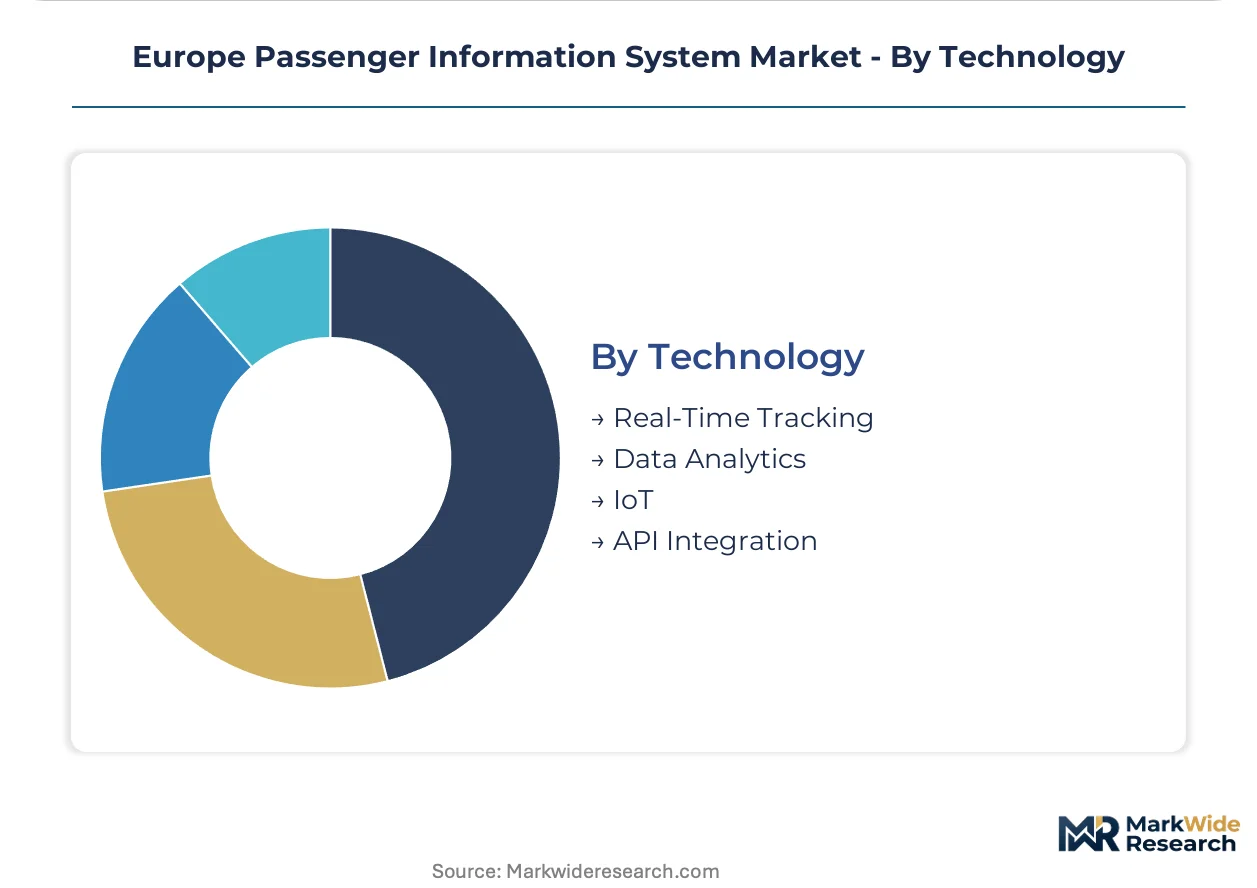
Technology:
Supply concentration in sensor hardware and analytics engines shapes vendor partnership requirements and integration complexity.
- Real-Time Tracking:GPS, RFID, and beacon-based vehicle location systems feed arrival prediction algorithms with sub-minute accuracy. German and Austrian networks anchor demand as EU Green Deal modal shift investments expand fleet monitoring coverage.
- Data Analytics:Predictive engines process historical delay patterns and real-time disruption signals to generate dynamic passenger guidance. GDPR-compliant edge analytics create ancillary revenue streams through anonymized congestion data sales to urban planners.
- IoT:Platform-mounted passenger flow sensors and environmental monitors extend network visibility beyond vehicle location.
- API Integration:Open-data interfaces enable third-party mobile application development and multimodal journey planning services.
Real-time tracking underpins operational reliability while data analytics demonstrates the steepest expansion trajectory as predictive capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German system integrators export passenger information platforms to rail operators across Central and Eastern Europe, with Austrian and Swiss networks serving as secondary demand corridors for high-specification deployments.
Germany
Deutsche Bahn's digital rail transformation and Bavarian regional network upgrades drive centralized control system procurement. The EU Green Deal modal shift mandates channel federal infrastructure budgets into multimodal corridor integration. Siemens AG anchors deployment contracts across Frankfurt, Munich, and Hamburg metropolitan nodes.
France
SNCF's high-speed rail interoperability requirements and Paris metro expansion generate demand for cybersecurity-hardened communication layers. ANSM accessibility regulations mandate multilingual audio-visual alert systems at all station platforms. Thales Group competes through mission-critical transit environment certifications.
United Kingdom
Network Rail's station modernization program and Transport for London's bus-rail integration projects stimulate display network upgrades. The country's rail regulator enforces open-data standards for real-time passenger information APIs. London's Elizabeth Line and Crossrail extensions concentrate edge-computing infrastructure investment.
Netherlands
ProRail's smart station initiatives and Rotterdam-The Hague metro extensions prioritize GPU-accelerated edge servers at platform level. Dutch accessibility legislation requires synchronized audio-visual announcements across all transit modes. Amsterdam and Utrecht anchor 40% of new hybrid architecture station builds.
Poland
PKP Intercity fleet renewal and Warsaw metro line extensions create entry points for SaaS-based passenger information platforms. EU cohesion funds finance digital infrastructure in underpenetrated Central European corridors. Krakow and Wroclaw municipal operators pilot subscription-based software access models.
Europe Passenger Information System Market Competitive Landscape
Listed leaders compete with private specialists across integrated platform architectures. The vendor base clusters around three tiers: diversified industrial conglomerates with rail divisions, pure-play transit technology specialists, and telecommunications infrastructure providers extending into transport verticals. Dominant competitive moves include strategic partnerships for cross-border interoperability certification and geographic expansion through SaaS platform localization.
Within the diversified industrial tier, Siemens AG and Alstom SA exemplify full-stack platform providers that bundle hardware manufacturing with software control systems. Thales Group occupies a position among defense-electronics specialists whose cybersecurity credentials translate into mission-critical transit contracts. These three French and German entities anchor premium-tier competition through EN 50159 safety certification depth and established relationships with state rail incumbents.
| Leading Market Players |
|---|
| Alstom SA |
| Siemens AG |
| Thales Group |
| Cubic Corporation |
| Hitachi, Ltd. |
| Cisco Systems |
| Indra |
| ST Engineering |
| Wabtec Corporation |
| Others |
Supply & Pricing Matrix
Forty-five-day lead times for 4K display driver ICs concentrate pricing power with East Asian foundries, forcing European system integrators to absorb cost volatility or push price adjustments through long-term service contracts with German and French rail operators.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in this market. Premium tiers bundle EN 50159 safety certification with centralized control architectures, while economy tiers serve Polish and Czech municipal operators through SaaS-based software access. Cost compression in standard-tier display hardware intensifies because mobile-first architectures erode traditional panel margins. Mid-sized transport authorities in Central Europe exhibit highest price sensitivity, whereas Deutsche Bahn and SNCF procurement teams prioritize mission-critical redundancy over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for semiconductor components and display panels. Manufacturing concentration in Taiwan, South Korea, and China feeds European system integrators with LCD modules, GPU accelerators, and edge-computing chipsets. Single-source vulnerability in display driver IC sourcing exposes vendors to allocation volatility during demand spikes. Distribution runs through authorized distributor networks serving Siemens AG, Thales Group, and Alstom SA with direct fulfillment to rail operator project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German and French state rail incumbents consolidate procurement through framework agreements, squeezing margin pools for mid-tier vendors dependent on fragmented municipal contracts.
For Market Incumbents: Secure EN 50159 certification depth as a defensive moat against SaaS-based challengers entering from Central Europe. Anchor long-term service contracts with Deutsche Bahn and SNCF through availability-based payment models that shift capital burden away from transport authorities. Deepen backward integration into edge-computing hardware to capture margin pools fragmenting toward platform-level system integrators in Dutch and Belgian networks. For New Entrants and Emerging Players: CE marking fast-track for cybersecurity-hardened communication layers opens procurement channels with French ANSM-mandated accessibility upgrades. Target underpenetrated Polish and Czech regional rail corridors with subscription-based software platforms that bypass heavy infrastructure investment. Lead with open-data API convergence to displace legacy centralized architectures in mid-sized municipal operators. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU Green Deal modal shift mandates lock in decade-long infrastructure investment cycles. Acquisition candidates with EN 50159 certification pipelines and established relationships with state rail incumbents offer defensive positioning. Monitor edge-computing deployment velocity in Dutch and Belgian station builds as inflection signal for topology fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| EN 50159 Safety Certification Investment | Deepens vendor moats against SaaS challengers in German and French procurement. |
| Edge-Computing Platform Integration | Captures margin pools fragmenting toward station-level GPU-accelerated deployments. |
| Availability-Based Service Contract | Shifts capital burden from Bavarian regional operators to vendor balance sheets. |
| GDPR-Compliant Edge Analytics Development | Creates ancillary revenue streams through anonymized congestion data sales. |
| Central European Geographic Expansion | Exploits underpenetrated Polish and Czech corridors with lower capital barriers. |
Research Methodology
Desk research of EU Agency for Railways technical specifications, ETSI intelligent transport standards, and national procurement databases preceded structured interviews with rail operator procurement directors, system integrator project managers, and embedded systems engineering leads. Primary fieldwork captured deployment timelines, certification bottlenecks, and budget allocation patterns across German, French, Dutch, and Polish networks. Secondary validation drew from customs trade data, SEC filings of listed vendors, and infrastructure investment disclosures by state rail incumbents. Bottom-up project pipeline analysis triangulated against top-down modal shift investment forecasts.
Variance decomposition across system type, deployment mode, end-user category, and technology layer shaped analytical framework throughout the projection horizon. Segmentation dimensions modeled include electronic display hardware, integration software, mobile application, and announcement system categories crossed with railway services, public transport, airline operators, and fleet management end users. CAGRs derived from unit deployment trajectories, specification upgrade cycles, and SaaS penetration curves in Central European corridors. Forecast inputs incorporated EU cohesion fund disbursement schedules and EN 50159 certification timeline evolution.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable semiconductor supply allocation; material deviation in modal shift policy or East Asian foundry capacity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Vehicle Parking Meter Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Air Taxi Market
Smart Transportation Solutions
Smart Transportation Solution Market