
 Automated Parking Systems Market | 2026-2036
Automated Parking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Parking Systems Market Intelligence
The customer base for automated parking solutions is expanding from large-scale commercial operators to include a fragmented set of smaller property developers and facility management companies seeking to maximize land use. Westfalia Technologies leverages its deep logistics automation expertise to serve large-scale airport facilities and commercial complexes. Klaus Multiparking Systems specializes in semi-automated puzzle systems tailored for residential and boutique commercial projects. Unitronics Systems positions its solutions for corporate campuses requiring high-throughput capabilities.
Automated parking systems are electromechanical structures that move vehicles from an entry point to a storage bay without a driver. These systems utilize a combination of lifts, pallets, and shuttles to achieve parking densities two to three times greater than conventional garages. While robotic parking systems command the highest value per project, shuttle parking systems represent the fastest-growing product type due to their scalability. Commercial complexes and airport facilities remain the primary applications, driving demand for high-throughput solutions.
System deployment is governed by a patchwork of local building codes in the United States and national safety standards, such as China's GB standards for mechanical equipment. In Europe, components must adhere to strict CE marking requirements, which certify electrical and mechanical safety for public-facing infrastructure. Compliance with these diverse regulations dictates market access and design specifications. Stakeholder focus now turns to standardizing software interfaces for integration with smart building management platforms and electric vehicle charging infrastructure.
Market Dynamics
The central dynamic in the automated parking systems market is the collision of extreme urban land constraints with the demand for integrated, smart building functionality. This forces developers to seek solutions that not only maximize spatial density but also seamlessly connect with electric vehicle charging and building management platforms.
Growth Catalysts
- Urban Planning Mandates:Municipal governments in high-density cities, particularly in Germany and across Japan, are implementing zoning regulations that favor or require high-density parking solutions in new constructions to combat urban sprawl and preserve land.
- EV Infrastructure Integration:The imperative to incorporate electric vehicle charging stations directly into parking structures creates a strong catalyst for automated systems, which can optimize the placement and usage of a limited number of chargers among many vehicles.
- Maximizing Real Estate Value:Property developers of mixed-use and commercial projects utilize automated parking to reduce the land footprint dedicated to parking, thereby maximizing the available square footage for revenue-generating residential or retail space.
Market Restraints
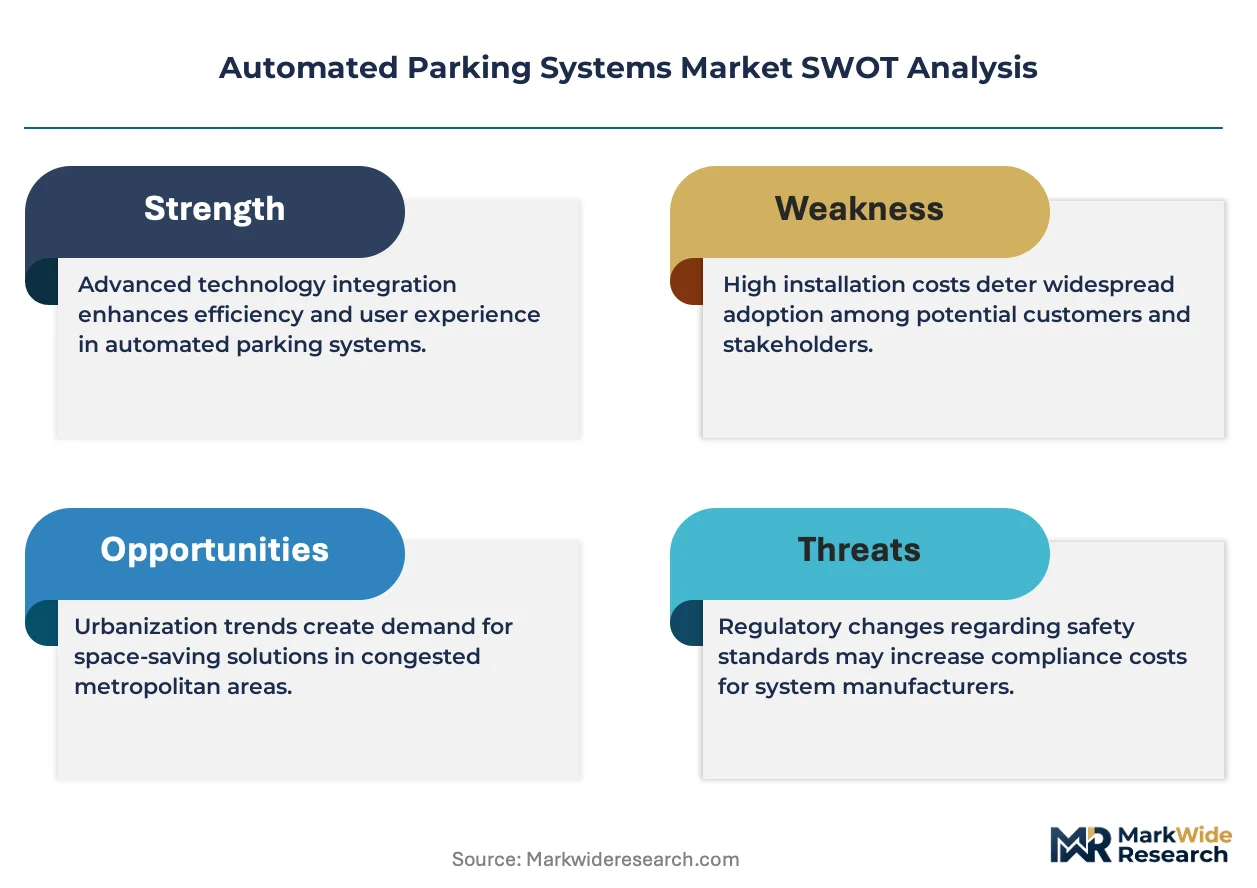
- High Initial Capital Outlay:The substantial upfront investment required for complex electromechanical systems, including lifts, shuttles, and software, presents a significant barrier compared to the lower cost of constructing conventional multi-story concrete garages.
- Fragmented Regulatory Frameworks:A lack of uniform international standards, with deployments governed by a patchwork of local building codes in the United States versus national GB standards in China, complicates system design and slows cross-border market entry.
- Technical Expertise for Maintenance:The operational reliability of these systems depends on a specialized workforce capable of servicing and troubleshooting advanced robotics, control software, and mechanical components, creating a potential service bottleneck.
Strategic Opportunities
- Retrofitting Existing Buildings:A significant opportunity exists in adapting compact, modular automated parking systems for existing residential and commercial buildings in historic urban centers, where constructing new garages is not feasible.
- Software and Data Services:Developing standardized software platforms for integration with building management systems and offering predictive maintenance and usage analytics as a recurring revenue service represents a key value-add.
- Logistics and Last-Mile Delivery Hubs:Applying automated vehicle storage and retrieval technology to create compact, high-density urban hubs for last-mile delivery fleets and car-sharing services is an emerging application.
Industry Challenges
- System Integration Complexity:Ensuring seamless and reliable interoperability between the parking automation software, building access controls, payment gateways, and diverse electric vehicle charging protocols remains a primary operational hurdle for installers.
- Public Perception and User Adoption:Overcoming end-user apprehension regarding system safety, reliability, and vehicle retrieval times is critical for gaining broader public acceptance, especially in residential applications.
- Standardization of Components:The absence of industry-wide standards for key components like vehicle pallets and communication interfaces between subsystems leads to vendor lock-in and complicates long-term maintenance and upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Parking Systems Market |
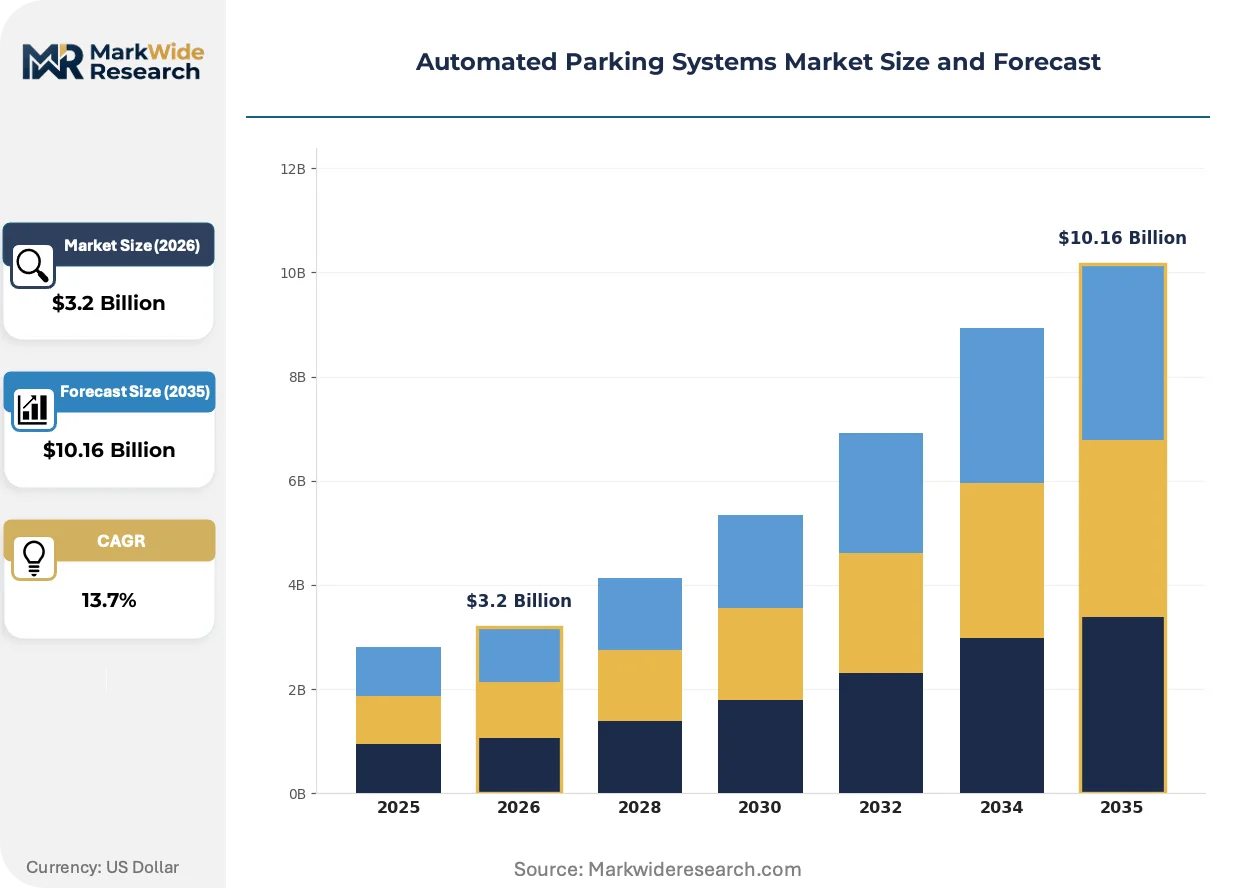
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $10.16 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Parking Systems, Puzzle Parking Systems, Shuttle Parking Systems, Automated Stack Parking, Lift Parking Systems Technology: Magnetic Sensors, Ultrasonic Sensors, Infrared Sensors, RFID Technology, Vision-Based Systems, Laser Scanning Application: Commercial Complexes, Airport Facilities, Entertainment Centers, Corporate Campuses, Mixed-Use Developments End User: Property Developers, Facility Management Companies, Commercial Operators, Hospitality Sector, Automotive Dealerships |
| Companies Covered | Westfalia Technologies, Klaus Multiparking Systems, Wohr Parking System, Robotic Parking Systems, Unitronics Systems, Skyline Parking, Lodige Industries, City Lift Parking, Parkmatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Parking Systems Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from standalone mechanical installations toward software-defined, networked systems. This transition emphasizes scalability, data integration, and adaptability to new vehicle technologies, fundamentally changing how value is created and delivered.
Software-Driven Modularity
Shuttle-based parking systems utilize fleets of autonomous robotic shuttles to transport vehicles on pallets within a storage structure. Commercial and airport developers are adopting these systems for their inherent scalability and high-throughput performance. This technology is modularizing system design, enabling phased deployments and customized throughput capacities that were difficult to achieve with older, monolithic lift-and-rail systems.
CE Marking and Safety Certification
European Union directives for CE marking mandate stringent electrical and mechanical safety verification for components in public-facing infrastructure. This regulation acts as a critical quality and safety gatekeeper for all lifts, shuttles, sensors, and control panels deployed within the EU. Consequently, manufacturers targeting the European market engineer their systems for compliance from the initial design phase, often resulting in higher-spec products that can be readily adapted for other global markets.
Shift in Procurement Models
Property developers are increasingly moving away from accepting single-vendor turnkey proposals and are instead specifying subsystems from different providers. This unbundling of the procurement process disrupts the traditional integrator's role, as developers now contract directly with specialists for control software, lift mechanisms, or EV charging infrastructure. This trend is most visible in large-scale, technologically complex mixed-use developments in North America where bespoke integrations are required.
Automated Parking Systems Market Segmentation
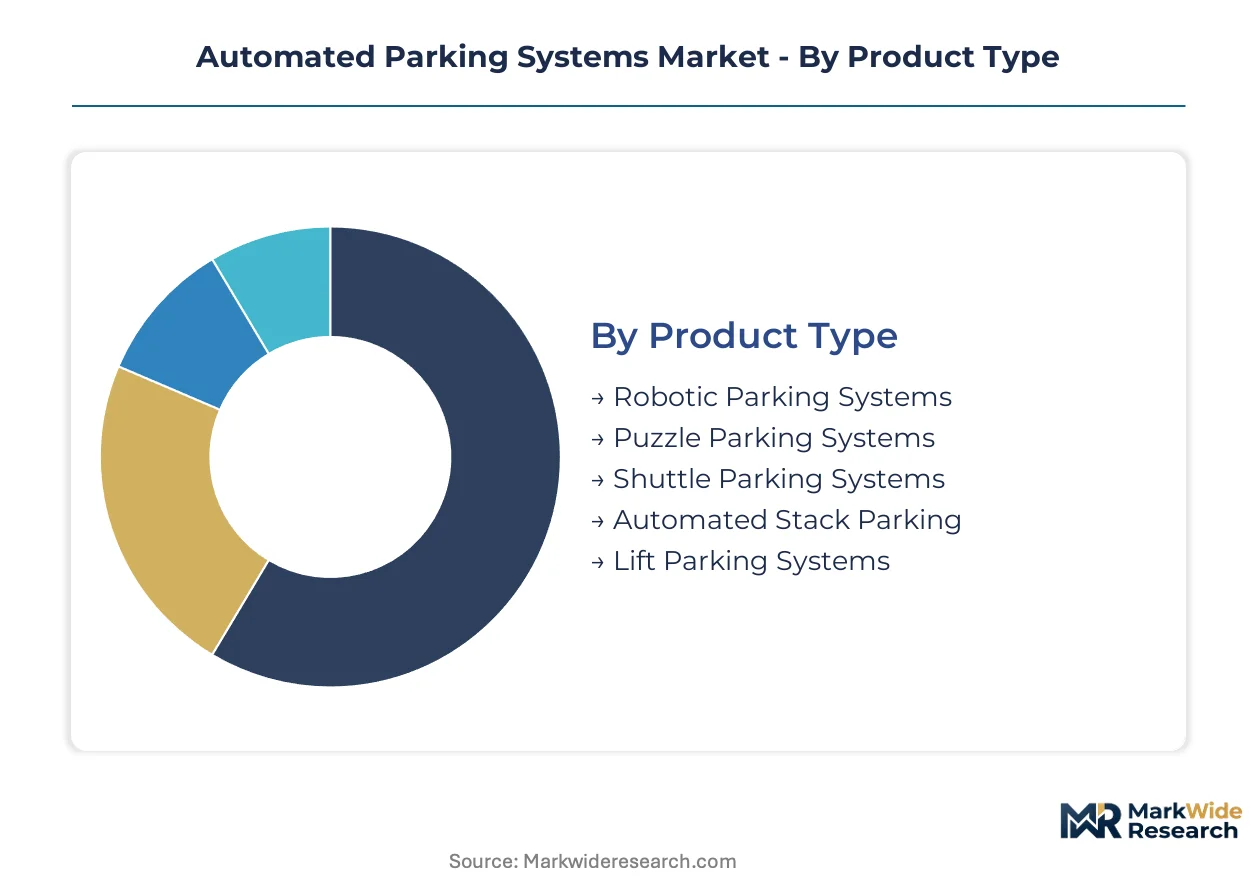
The automated parking systems market segments by the core technologies and use cases that define its operational capabilities and target customer groups. Understanding these distinctions is critical for solution providers to align product development with specific market demands and regulatory environments.
Product Type:
The integration depth of automated parking systems varies significantly by product type, reflecting a spectrum from fully embedded robotic solutions to more standalone mechanical configurations.
- Robotic Parking Systems:These systems employ autonomous robots to move vehicles on pallets within a dedicated storage structure. Robotic systems command the highest value per project due to their complexity, offering high density and throughput in constrained urban centers like Tokyo.
- Shuttle Parking Systems:Fleets of robotic shuttles transport vehicles on pallets, allowing for modular, scalable deployments across multiple levels. Commercial and airport developers increasingly adopt these systems for their inherent scalability and high-throughput performance in major transport hubs.
- Puzzle Parking Systems:Semi-automated systems use hydraulic lifts and horizontal platforms to arrange vehicles like a puzzle, optimizing space in smaller footprints.
- Automated Stack Parking:These systems mechanically stack vehicles vertically using lifts, suitable for maximizing density in compact residential or commercial buildings.
- Lift Parking Systems:Simple mechanical lifts raise and lower vehicles to access different levels, providing basic space efficiency solutions for smaller parking areas.
Robotic Parking Systems lead in value per project today; Shuttle Parking Systems are gaining share fastest.
Technology:
Technology components for automated parking systems span various maturity levels, from established sensor types to advanced vision-based solutions.
- Vision-Based Systems:These advanced systems utilize cameras and image processing algorithms for precise vehicle positioning, identification, and obstacle detection. Developers in Germany deploy these for enhanced reliability and integration with smart building platforms.
- Laser Scanning:Laser scanners provide highly accurate distance measurements and environmental mapping, displacing older sensor types for improved system navigation and safety. Urban developments in Japan increasingly rely on this technology for precise vehicle handling.
- Magnetic Sensors:These sensors detect the presence and position of metallic objects, commonly used for basic vehicle detection at entry and exit points.
- Ultrasonic Sensors:Emitting sound waves to measure distances, ultrasonic sensors assist in parking guidance and obstacle avoidance within the system's operational envelope.
- Infrared Sensors:Infrared technology detects heat signatures or breaks in beams, providing presence detection and safety interlocks within the automated parking structure.
- RFID Technology:Radio-Frequency Identification tags enable automated vehicle identification and access control, streamlining entry and exit processes for registered users.
Vision-Based Systems exhibit the steepest expansion trajectory; Magnetic Sensors maintain a foundational role.
Application:
Automated parking solutions cater to diverse application environments, each with distinct demand characteristics for throughput and space optimization.
- Commercial Complexes:These large-scale facilities require high-throughput systems to manage significant vehicle volumes efficiently for shoppers and office workers. Developers in major metropolitan areas utilize these to maximize revenue-generating space.
- Airport Facilities:Airports demand robust, high-speed automated parking solutions to handle high turnover and provide reliable service for travelers. Major international airports increasingly adopt these systems to optimize land use.
- Mixed-Use Developments:These projects integrate residential, commercial, and retail spaces, requiring flexible parking solutions that can serve varied user needs and peak times.
- Corporate Campuses:Automated parking provides efficient solutions for employee and visitor parking, often integrating with campus access control and smart building management systems.
- Entertainment Centers:Stadiums, theaters, and event venues use automated parking to manage large crowds and rapid vehicle inflow/outflow during peak events.
Commercial Complexes dominate current demand; Mixed-Use Developments show substantial growth potential.
End User:
End-user segments reflect varying investment scales and operational requirements for automated parking infrastructure.
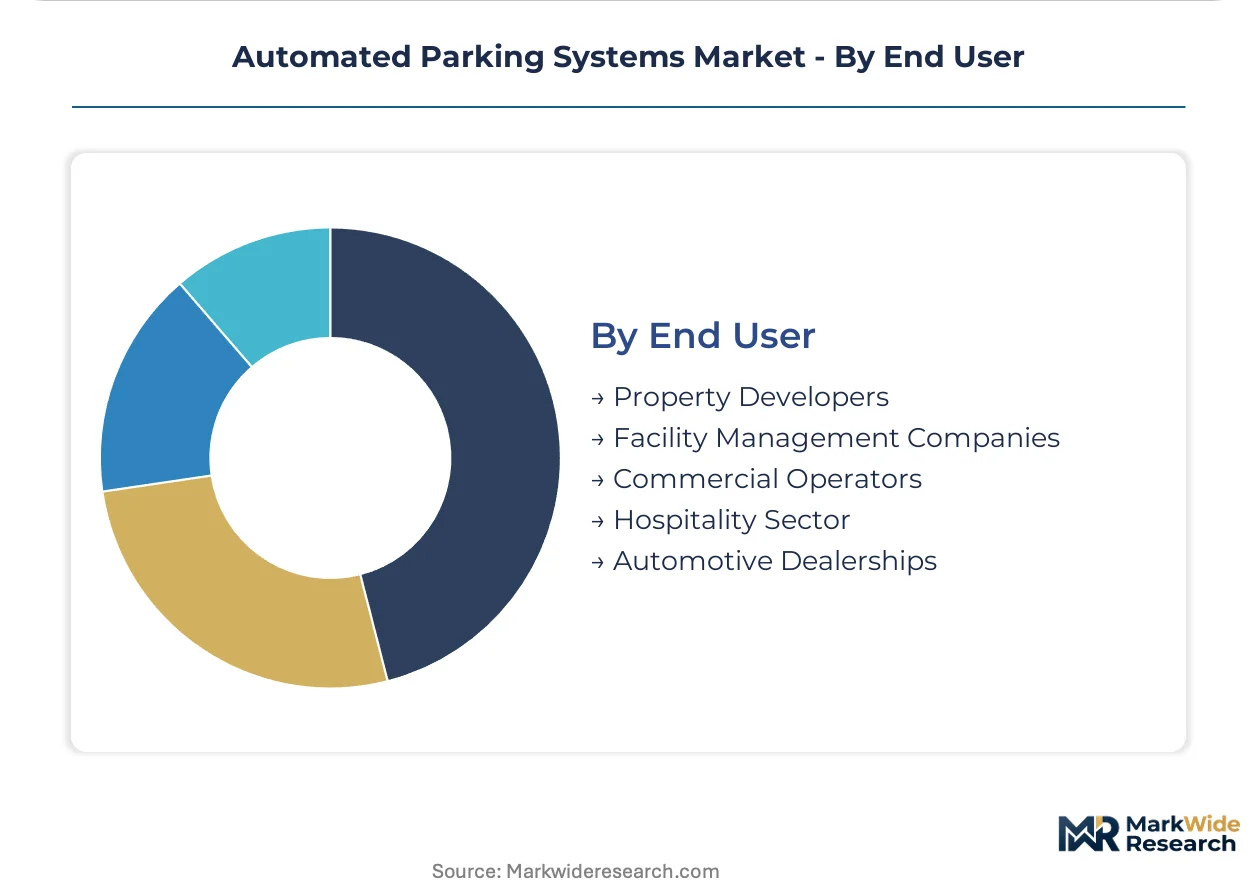
- Property Developers:These entities invest in automated parking to maximize land use, reduce construction costs for parking, and enhance property value in dense urban environments. Developers in high-density centers like Berlin prioritize these solutions.
- Commercial Operators:Large-scale parking facility owners and operators purchase automated systems to improve operational efficiency, increase parking capacity, and offer premium services. Operators of major city center garages focus on high-throughput solutions.
- Facility Management Companies:These firms manage the day-to-day operations and maintenance of various facilities, including parking structures, and seek reliable, low-maintenance automated solutions.
- Hospitality Sector:Hotels and resorts use automated parking to provide convenient guest services, often in space-constrained urban locations, enhancing the luxury experience.
- Automotive Dealerships:Dealerships utilize automated storage for new and used car inventory, improving security, organization, and space utilization on their lots.
Property Developers significantly influence purchasing decisions; Commercial Operators drive operational efficiency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's market for automated parking systems emphasizes high-density solutions driven by stringent urban planning, while Japan focuses on precision engineering for space-constrained urban centers. These distinct regional priorities shape system design and regulatory compliance. The demand for efficient parking solutions spans various global markets, influenced by local infrastructure, population density, and regulatory frameworks.
Germany
Property developers in Germany prioritize automated parking systems to comply with urban planning mandates favoring high-density solutions. CE marking requirements ensure electrical and mechanical safety for all components within the European Union. New project deployments in cities like Berlin concentrate on integrating these systems into smart building management platforms.
Japan
Japan's market for automated parking systems emphasizes advanced laser scanning technology for precise vehicle handling in extremely dense urban environments. The country's JIS standards for mechanical equipment underpin design specifications and operational reliability. Urban developments in Tokyo increasingly adopt these solutions to maximize land use and manage vehicle flow.
United States
The United States sees demand for automated parking solutions from mixed-use developments and corporate campuses seeking to maximize real estate value. A patchwork of local building codes governs system deployment, complicating cross-state market entry. Major metropolitan areas like New York City are experiencing increased adoption, particularly for high-throughput applications.
China
China's market for automated parking systems is driven by large-scale commercial complexes and airport facilities requiring high-throughput capabilities. National GB standards for mechanical equipment dictate design and safety parameters for system manufacturers. Major cities such as Shanghai are seeing significant investment in these advanced parking solutions.
United Kingdom
Developers in the United Kingdom leverage automated parking systems to optimize space in existing residential and commercial buildings within historic urban centers. Adherence to CE marking requirements ensures system safety and reliability for public-facing infrastructure. London's property market, facing severe space constraints, actively seeks modular and compact automated parking solutions.
Automated Parking Systems Market Key Industry Players
European producers anchor one tier of the automated parking systems market, emphasizing precision engineering and regulatory compliance, while Asian specialists hold another, focusing on scale and high-throughput solutions. The market exhibits a fragmented structure with specialized providers catering to distinct application needs. Strategic archetypes include large-scale logistics automation integrators, niche residential solution providers, and corporate campus specialists. Competitive moves frequently involve technology licensing and strategic partnerships to enhance integration capabilities.
Specialists in high-throughput logistics automation include Westfalia Technologies. Klaus Multiparking Systems exemplifies providers of compact, semi-automated solutions tailored for residential and boutique commercial projects. Unitronics Systems occupies a position among developers of robust, high-throughput systems designed for corporate campuses.
| Leading Market Players |
|---|
| Westfalia Technologies |
| Klaus Multiparking Systems |
| Wohr Parking System |
| Robotic Parking Systems |
| Unitronics Systems |
| Skyline Parking |
| Lodige Industries |
| City Lift Parking |
| Parkmatic |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in automated parking systems often prioritize long-term client relationships, influencing supply stability and pricing discipline. Their focus on specialized engineering and bespoke solutions limits aggressive price competition.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-throughput systems, introducing more competitive options. The dominant pricing model remains project-based, reflecting the bespoke nature of each installation. Price differentiation stems from the customization level and adherence to stringent safety certifications like CE marking in Europe. Pricing pressure stems from the substantial initial capital outlay required for complex electromechanical systems. Property developers exhibit the highest price sensitivity, while commercial operators prioritize long-term operational efficiency.
Supply Chain Analysis
Adherence to CE marking requirements and national standards like China's GB standards gates supplier qualification for critical components. The supply chain for automated parking systems draws from precision engineering hubs in Germany and Japan, alongside scale manufacturing in China. Key dependencies include specialized electromechanical lifts, robotic shuttles, and advanced vision-based sensor arrays. Single-source vulnerability for specific control software or highly specialized mechanical parts poses a structural risk. Distribution runs through direct sales teams and certified installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated parking systems market presents a clear margin-expansion story, driven by the increasing demand for premium, space-efficient solutions in dense urban centers. Integration of advanced vision-based systems allows for higher value-per-project.
For Market Incumbents:Cement market leadership by standardizing software interfaces for seamless integration with smart building platforms. Deepen vertical integration into specialized component manufacturing to mitigate supply chain risks and protect intellectual property. This defends against emerging software-only integrators and fragmented regulatory complexities. Investment in CE marking compliance ensures broader European market access and product quality differentiation.
For New Entrants and Emerging Players:Online platform aggregation of modular parking solutions offers a direct-to-developer channel for niche projects. Target white-space opportunities in retrofitting existing buildings within historic urban centers and developing compact logistics hubs for last-mile delivery fleets. Modular systems for existing residential buildings in London represent a highly penetrable segment. Offer outcome-based predictive maintenance as a recurring revenue service.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional specialists with strong local installation networks but limited software capabilities. The long-term viability of this market rests on sustained demand from urban densification and the imperative for EV infrastructure integration. Target acquisition profiles include software and data service providers specializing in smart building integration. The signal to watch is the industry's progress in standardizing software interfaces, indicating broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Standardize Software Interfaces | This initiative is crucial for seamless integration with smart building platforms and diverse EV charging protocols. |
| Develop Modular Shuttle Systems | Modular systems address scalability and phased deployment needs for commercial and airport developers. |
| Invest in Vision-Based Technology | Such investment enhances system reliability and precision for vehicle handling in dense urban environments. |
| Expand Retrofit Solutions | Retrofit solutions unlock new market opportunities in existing residential and commercial buildings within urban centers. |
| Offer Predictive Maintenance Services | This creates recurring revenue streams and improves operational reliability for commercial operators. |
Research Approach
Direct dialogue with property developers, commercial operators, facility management companies, and system engineers provided qualitative insights. This primary research was rigorously combined with secondary validation from industry association reports, national building codes in Germany and China, and company financial filings. A bottom-up and top-down triangulation approach ensured data consistency and robust market sizing.
A bottom-up analytical framework informed volume and value outputs across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and geographic deployment. Compound Annual Growth Rates were derived from historical trends and projected growth drivers. Key industry-specific forecast inputs included urbanization rates in dense urban centers and electric vehicle adoption forecasts.
Shifts in local building codes, global economic downturns, and raw material price volatility are the dominant revision risks for market forecasts. These forecasts reflect assumptions regarding technological adoption and regulatory stability. Deviation in urban planning mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Global Smart Commute Market