
 Global IoT in Transportation Market | 2026-2036
Global IoT in Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Transportation Market Foresight
Software-defined fleet subscriptions is rebalancing vendor economics toward recurring revenue and over-the-air feature unlocks. Cisco Systems leverages its networking stack to anchor edge-computing contracts with port authorities and rail operators. Thales Group specializes in encrypted satellite-to-ground links for defense and commercial aviation tracking. Garmin International dominates consumer and light-commercial telematics through integrated hardware-software bundles.
IoT in transportation denotes networked sensor, communication, and analytics systems embedded across vehicles, infrastructure, and cargo assets to enable real-time visibility, predictive intervention, and automated coordination. These systems typically operate across sub-one-second latency thresholds for collision avoidance and route recalculation, with data pipelines feeding cloud or edge platforms for operational decision-making. Cellular IoT connectivity leads in unit volume among technology layers because carrier-grade coverage and falling module costs suit high-mobility fleets. Fleet management applications capture the largest share of current spend, while predictive maintenance is expanding fastest as OEMs embed vibration and thermal sensors at the factory. Cloud-based deployment holds the margin pool for platform vendors, though hybrid architectures are gaining share among operators with strict data-sovereignty requirements.
The Federal Communications Commission shapes spectrum allocation for connected-vehicle protocols in the United States, while the European Union's GDPR and forthcoming AI Act constrain cross-border data flows and automated decision systems in logistics platforms. Japan's Ministry of Economy, Trade and Industry (METI) coordinates 5G corridor pilots that directly determine which IoT standards gain scale in East Asian freight networks. Stakeholders must weigh regulatory fragmentation against the cost of region-specific compliance stacks when selecting technology partners and deployment architectures.
Market Dynamics
Cellular IoT module costs have collapsed below satellite-equivalent pricing, triggering wholesale architecture swaps across commercial fleets and eroding legacy hardware incumbents' installed-base moats.
Growth Catalysts
- EPA emissions mandates:Fleet operators in the United States face tightening NOx and particulate standards, forcing real-time telemetry adoption for compliance documentation and automated reporting.
- 5G corridor pilots:Japan's Ministry of Economy, Trade and Industry funds dedicated freight lanes with guaranteed low-latency connectivity, validating cellular-V2X for autonomous platooning.
- Predictive maintenance sensors:OEMs now embed vibration and thermal monitoring at the factory, creating captive data streams that lock operators into manufacturer-hosted analytics platforms.
Market Restraints
- Semiconductor supply concentration:Cellular modem silicon depends on TSMC's 7nm and 5nm foundry capacity in Taiwan, exposing module vendors to single-point geopolitical risk.
- GDPR data-sovereignty friction:The European Union's cross-border transfer restrictions force operators to maintain region-specific cloud instances, duplicating infrastructure costs.
- Legacy fleet replacement cycles:Commercial vehicles average twelve-year service lives in Brazil and India, delaying sensor retrofit adoption despite connectivity availability.
Strategic Opportunities
- India's logistics digitization:The country's PLI scheme for automotive components subsidizes domestic telematics manufacturing, creating localized supply alternatives to Chinese modules.
- Rail-to-port intermodal visibility:Container handoffs between freight rail and maritime terminals remain tracking blind spots, opening white space for multi-modal sensor orchestration.
- EU AI Act compliance services:Automated decision systems in route optimization face new transparency requirements, creating demand for explainable-AI middleware in logistics platforms.
Industry Challenges
- Edge-AI talent scarcity:Fleet operators struggle to hire embedded systems engineers capable of optimizing inference workloads on resource-constrained vehicle gateways.
- Multi-protocol integration complexity:Deployments must reconcile legacy J1939 CAN bus signals with modern MQTT and 5G-NR interfaces, extending commissioning timelines.
- ISO 26262 functional safety certification:Collision-avoidance systems require ASIL-D validation, adding eighteen to twenty-four months to product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Transportation Market |
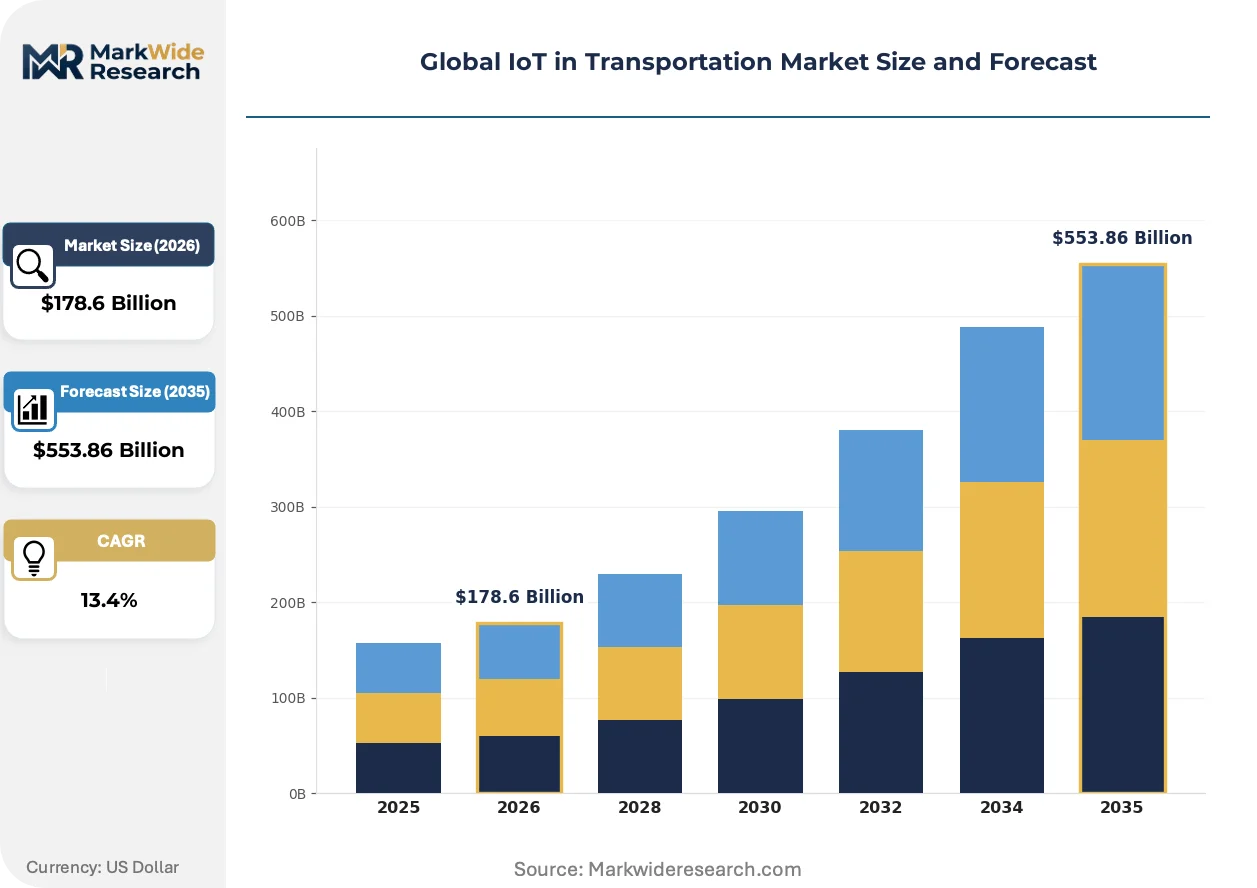
| Market Size in 2026 | $178.6 Billion |
| Market Size in 2035 | $553.86 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Tracking, RFID, Cellular IoT, LPWAN, Bluetooth, Satellite Communication Application: Fleet Management, Cargo Monitoring, Predictive Maintenance, Route Optimization, Traffic Management, Safety Enhancement Deployment: Cloud-Based, Edge Computing, Hybrid, On-Premise End User: Logistics Companies, Public Transport Operators, Freight Forwarders, Last-Mile Delivery Providers, Vehicle Rental Services |
| Companies Covered | IBM Corporation, Cisco Systems, Inc., AT&T Inc., Alcatel-Lucent, Garmin International Inc., Denso Corporation, Thales Group, Verizon Communications Inc., TomTom N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Transportation Market Shifts & Advancements
Transportation IoT architectures are compressing decision latency from cloud round-trips to milliseconds through edge-native processing, rewiring competitive advantage around real-time responsiveness rather than historical analytics.
Digital twin technology is automating fleet simulation and scenario testing before physical deployment. Logistics operators in Germany and the Netherlands deploy virtual replicas of distribution networks to stress-test routing algorithms against weather disruptions and demand spikes. This capability compresses pilot-to-production cycles from quarters to weeks while reducing hardware waste from failed configurations.
The European Union's AI Act imposes risk-classification requirements on automated logistics decision systems, mandating human oversight interfaces for high-risk route optimization. Platform vendors must now embed audit trails and explainability modules into cloud analytics stacks. Freight operators with cross-border EU lanes are prioritizing compliant vendors, creating procurement preference shifts that disadvantage opaque black-box systems.
Subscription-based fleet management contracts are displacing perpetual-license sales across North American and European mid-market operators. Buyers prefer operational expenditure models that bundle hardware, connectivity, and software upgrades into per-vehicle monthly fees. This shift pressures vendor cash flow timing but locks in longer customer relationships and reduces competitive churn in the United States and United Kingdom commercial fleet segments.
Global IoT in Transportation Market Segmentation
Transportation IoT purchasing decisions hinge on upgrade cycles that vary dramatically across fleet age profiles and regulatory compliance deadlines. Vendors must align product roadmaps with these heterogeneous replacement rhythms rather than assuming uniform technology refresh patterns.
Technology:
Fleet operators face diverging replacement economics as satellite-only architectures give way to multi-technology stacks.
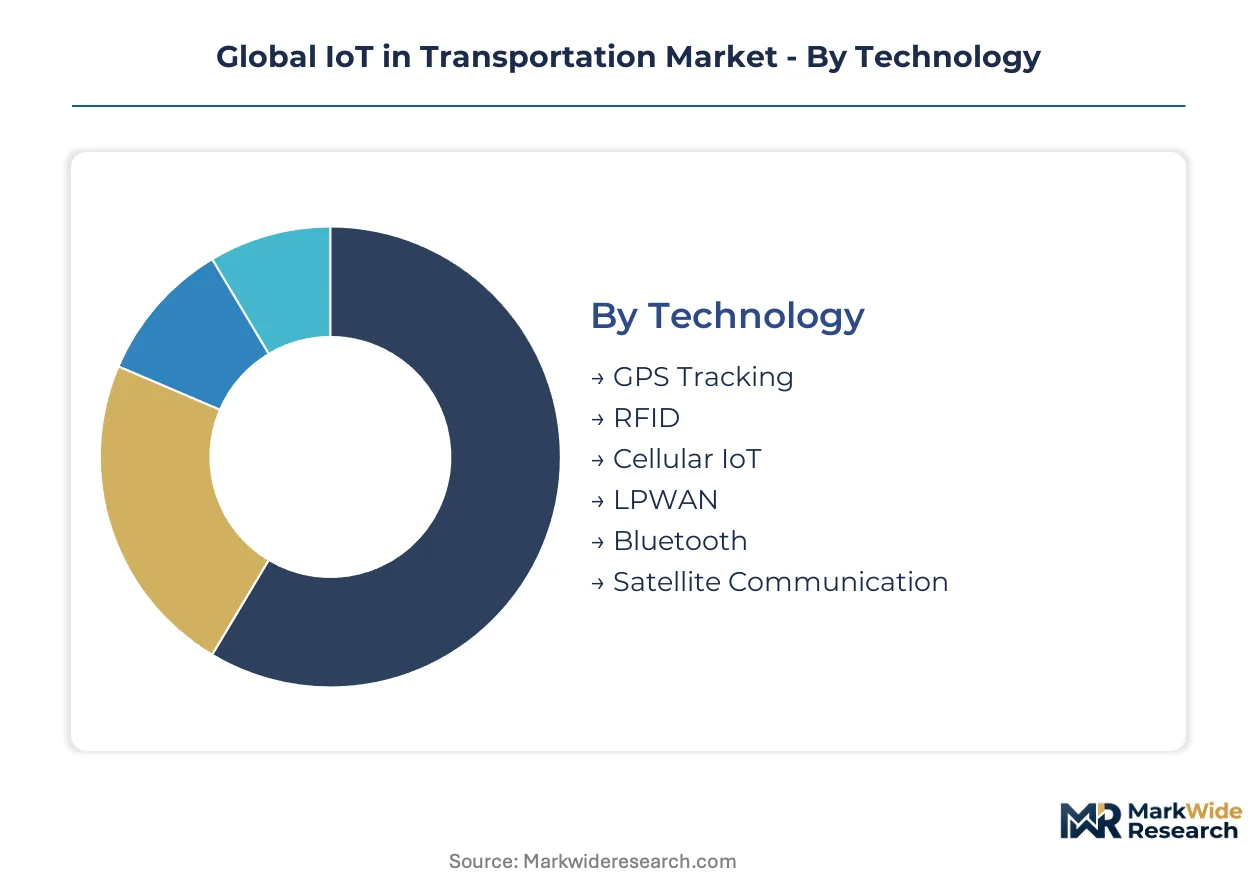
- Cellular IoT:Modules integrate 4G LTE and 5G NR modems with carrier-certified SIM management for seamless handoffs across roaming agreements. Demand concentrates in Germany and Japan where METI-funded 5G corridors validate cellular-V2X for autonomous platooning, though TSMC foundry concentration creates supply vulnerability.
- GPS Tracking:Multi-constellation receivers process L1/L5 signals from GPS, Galileo, and BeiDou with sub-meter accuracy for geofencing enforcement. Logistics operators in Brazil and India prioritize this layer for asset recovery and route verification where cellular backhaul remains intermittent.
- RFID:Passive UHF tags enable gate-level container identification without battery maintenance.
- LPWAN:NB-IoT and LoRa networks serve low-bitrate telemetry for refrigerated trailer temperature monitoring.
- Bluetooth:Short-range beacons facilitate yard management and driver authentication workflows.
- Satellite Communication:L-band and Ku-band terminals retain dominance in maritime and remote mining corridors where cellular coverage vanishes.
Cellular IoT sits at the top of the volume ranking, with GPS Tracking climbing the fastest.
Application:
Procurement patterns split between compliance-mandated deployments and discretionary efficiency investments.
- Fleet Management:Unified platforms combine telematics, driver behavior scoring, and fuel consumption analytics through subscription contracts. North American operators dominate current spend as EPA emissions mandates force real-time NOx monitoring and automated reporting documentation.
- Predictive Maintenance:Vibration and thermal sensors embedded at OEM factories create captive data streams locking operators into manufacturer-hosted analytics. European freight forwarders prioritize this segment to minimize unplanned downtime penalties under JIT delivery contracts.
- Cargo Monitoring:Environmental sensors track shock, humidity, and temperature for pharmaceutical and electronics shipments.
- Route Optimization:Machine learning engines process traffic, weather, and delivery window constraints.
- Traffic Management:Municipal deployments coordinate signal timing and incident response across urban corridors.
- Safety Enhancement:Collision-avoidance systems require ASIL-D functional safety certification extending development cycles.
Fleet Management captures the dominant revenue share, while Predictive Maintenance expands most quickly as factory-embedded sensor penetration deepens.
Deployment:
Margin structures diverge sharply between centralized cloud platforms and distributed edge architectures.
- Cloud-Based:Multi-tenant SaaS platforms aggregate telemetry from millions of vehicles into centralized data lakes for pattern recognition. Platform vendors in the United States and United Kingdom capture recurring revenue through per-vehicle monthly subscriptions that bundle hardware, connectivity, and software upgrades.
- Hybrid:Architectures partition sensitive operational data to on-premise nodes while pushing anonymized analytics to public cloud. German and Dutch logistics operators favor this model to satisfy GDPR data-sovereignty requirements without sacrificing scalability.
- Edge Computing:Vehicle gateways process inference workloads locally for sub-100ms collision avoidance decisions.
- On-Premise:Fully air-gapped installations serve defense and critical infrastructure operators with classified mobility requirements.
Cloud-Based deployment holds the margin pool, with Hybrid architectures gaining share fastest among operators with strict cross-border data constraints.
End User:
Customer concentration varies by fleet scale and contract negotiation leverage.
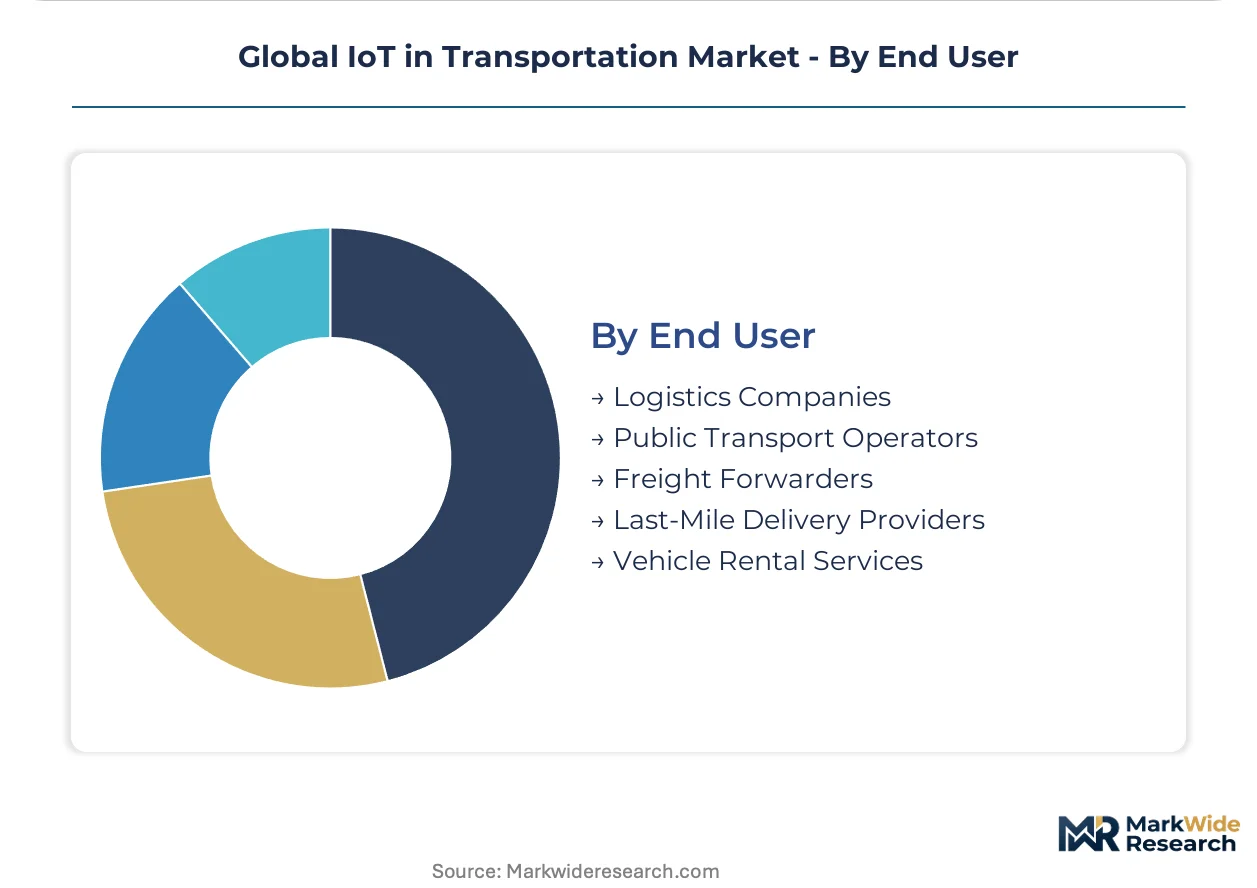
- Logistics Companies:Integrated 3PL and 4PL providers operate heterogeneous vehicle pools spanning owned assets and subcontracted capacity. These buyers in the United States drive standardization toward API-first platforms that aggregate disparate telematics feeds into unified control towers.
- Last-Mile Delivery Providers:E-commerce fulfillment networks optimize dense urban routing with real-time customer communication. Indian operators exploit PLI scheme subsidies for domestic telematics manufacturing to reduce module costs.
- Public Transport Operators:Municipal bus and rail agencies prioritize passenger information systems and fare collection integration.
- Freight Forwarders:International cargo coordinators demand multi-modal visibility across ocean, air, and land legs.
- Vehicle Rental Services:Short-term mobility providers track utilization rates and damage attribution through embedded black boxes.
Logistics Companies represent the deepest customer segment, with Last-Mile Delivery Providers showing the steepest expansion trajectory as e-commerce volumes compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan deploy cellular-V2X corridors at scale while Brazil and India struggle with legacy fleet replacement cycles and intermittent rural coverage.
United States
Fleet operators face EPA emissions mandates requiring real-time NOx and particulate monitoring for compliance documentation. The FCC shapes spectrum allocation for connected-vehicle protocols through 5.9 GHz band rules. California's Central Valley agricultural trucking corridors deploy edge-computing gateways for automated hours-of-service logging.
Germany
Logistics operators demand hybrid cloud architectures to satisfy GDPR data-sovereignty requirements without sacrificing scalability. The EU AI Act imposes transparency requirements on automated route optimization systems. The Rhine-Ruhr freight cluster pilots digital twin simulations for distribution network stress-testing against weather disruptions.
Japan
METI funds dedicated 5G freight corridors with guaranteed low-latency connectivity for autonomous platooning validation. The ministry coordinates standards adoption that determines which IoT architectures gain scale in East Asian freight networks. The Nagoya-Tokyo corridor serves as the primary testbed for cellular-V2X commercial deployment.
Brazil
Commercial vehicles average twelve-year service lives that delay sensor retrofit adoption despite connectivity availability. ANVISA and national transport regulators emphasize cargo security tracking for pharmaceutical and high-value goods. São Paulo's metropolitan freight operators prioritize GPS tracking with multi-constellation receivers for geofencing enforcement where cellular backhaul remains intermittent.
India
The PLI scheme for automotive components subsidizes domestic telematics manufacturing to reduce module costs and create localized supply alternatives. BIS standards shape device certification requirements for fleet deployments. Last-mile delivery providers in Mumbai and Delhi exploit scheme subsidies to expand real-time customer communication systems for e-commerce fulfillment networks.
Global IoT in Transportation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with networking incumbents anchoring enterprise contracts and component suppliers capturing hardware volume. The vendor base concentrates around three strategic archetypes: networking-stack providers leveraging infrastructure relationships, encrypted communications specialists serving defense and aviation, and integrated hardware-software bundlers dominating consumer telematics. Competitive dynamics center on recurring revenue migration through subscription contracts and edge-computing partnerships with port and rail authorities.
Within the networking infrastructure tier, Cisco Systems anchors edge-computing contracts through its established carrier relationships, while Thales Group exemplifies the encrypted communications archetype with satellite-to-ground specialization. Garmin International occupies a position in the integrated bundle segment, representing the hardware-software convergence model for light-commercial applications.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems, Inc. |
| AT&T Inc. |
| Alcatel-Lucent |
| Garmin International Inc. |
| Denso Corporation |
| Thales Group |
| Verizon Communications Inc. |
| TomTom N.V. |
| Others |
Supply & Pricing Matrix
EPA emissions mandates gate qualified supply and premium-tier pricing access for fleet operators seeking compliant telemetry systems, forcing buyers to absorb certification premiums or risk regulatory penalties. Tier-1 module vendors leverage this compliance barrier to sustain pricing power while second-tier suppliers compete on stripped-down configurations for price-sensitive retrofit segments.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for cellular IoT modules as new foundry capacity enters service. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ASIL-D certification status and data-sovereignty bundling. Cost compression in economy-tier cellular modules is intensifying because Chinese vendors are flooding Brazil and India with uncertified alternatives. Small fleet operators in India exhibit the highest price sensitivity, while German logistics companies prioritize GDPR-compliant hybrid architectures with minimal cost elasticity.
Supply Chain Analysis
Dual-sourcing requirements from European automotive OEMs now mandate multi-supplier qualification for cellular modems to mitigate TSMC concentration risk. Manufacturing concentrates in Taiwan, China, and Vietnam, with module assembly drawing from 7nm and 5nm silicon wafers, ceramic antenna substrates, and automotive-grade SIM form factors. Single-source vulnerability in TSMC's foundry capacity exposes vendors to geopolitical disruption. Distribution runs through carrier-certified logistics channels with regional warehousing in Rotterdam, Singapore, and Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EPA and EU AI Act compliance requirements shift procurement toward premium-specification platforms with embedded audit trails and explainability modules.
For Market Incumbents: Lock in long-term connectivity contracts with North American port authorities before 5G corridor pilots expand vendor qualification lists. Cisco Systems and Thales Group should deepen backward integration into edge-computing silicon to defend against modular hardware commoditization. Certification investment in ISO 26262 ASIL-D validation creates eighteen-month moats against unqualified entrants.
For New Entrants and Emerging Players: Edge-AI optimization software for resource-constrained vehicle gateways offers the most penetrable wedge against incumbent hardware bundling. Target India's last-mile delivery segment where PLI scheme subsidies reduce customer acquisition costs and domestic manufacturing requirements favor localized software stacks. A channel partnership with domestic telematics assemblers in Mumbai accelerates regulatory compliance without captive fabrication.
For Investors and Strategic Acquirers: Roll-up economics work for hybrid cloud orchestration specialists because GDPR data-sovereignty requirements fragment customer deployments across region-specific instances. Long-term viability favors vendors with recurring SaaS revenue above sixty percent of total mix. Watch METI's 5G corridor standardization decisions as the inflection indicator for which cellular-V2X architectures achieve East Asian scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Partnership | Port authorities in Los Angeles and Rotterdam demand sub-100ms collision avoidance processing. |
| 5G Corridor Certification | METI-funded pilots in Japan validate cellular-V2X for autonomous platooning commercialization. |
| GDPR-Compliant Hybrid Deployment | German logistics operators require on-premise nodes with cloud analytics partitioning. |
| Predictive Maintenance Platform Integration | OEMs embed vibration sensors at factory, creating captive data lock-in opportunities. |
| PLI Scheme Localization | Indian automotive component subsidies reduce module costs for domestic telematics manufacturing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, cellular module procurement leads, port authority technology officers, and automotive OEM platform engineers with secondary validation. Secondary sources included FCC spectrum allocation filings, METI 5G corridor pilot documentation, EU AI Act regulatory texts, and EPA emissions compliance databases. Bottom-up module shipment tracking and top-down fleet telematics spend estimates were triangulated against carrier-reported IoT connection growth.
Comparable historical periods anchored the projection horizon to prior regulatory compliance cycles and technology substitution waves. Segmentation dimensions modeled include connectivity technology, deployment architecture, application type, fleet scale tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to disclosed connection volumes and vendor revenue mixes. Forecast inputs incorporated foundry capacity expansion schedules and emissions mandate enforcement timelines.
The model holds under stable geopolitical conditions and continued foundry capacity expansion; deviation in TSMC supply disruption or EPA enforcement acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Nordic Bike Sharing Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Scooter Sharing Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
Alternate Transportation Market