
 Iran Vehicles Market | 2026-2036
Iran Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Vehicles Market Foresight
Project finance tied to local content mandates is tilting competitive access toward manufacturers with established Iranian partnerships. Iran Khodro leverages its integrated foundry and stamping operations to control cost structures across passenger car lines. Saipa sustains volume leadership in economy vehicle segments through dense dealership networks in provincial cities. Kerman Motor specializes in commercial vehicle assembly for fleet operators serving mining and construction sectors.
Vehicles in Iran encompass motorized transport equipment designed for passenger carriage, goods movement, or specialized industrial tasks, typically incorporating internal combustion or alternative-fuel powertrains rated to national technical specifications for emissions and safety. These assets serve commercial logistics, personal mobility, and public transit functions across Iran's mountainous terrain and urban corridors. Passenger cars dominate transaction volumes within the market segment dimension, though commercial vehicles command stronger margin pools due to fleet procurement cycles and after-sales service attach rates. CNG fuel type configurations hold structural importance given Iran's abundant natural gas reserves and subsidized pricing regime relative to petrol. Electric vehicles remain nascent but attract policy attention as the country explores reduced import dependency for refined fuels.
The Institute of Standards and Industrial Research of Iran sets mandatory safety and emissions benchmarks that all domestic assemblers must satisfy before market release, while the country's national automotive regulator oversees homologation procedures for imported components and knock-down kits. These frameworks effectively constrain which foreign partners can participate and dictate localization thresholds for continued operational licensing. Stakeholders must monitor how currency volatility interacts with component import rules to assess which assembly models retain economic viability.
Market Dynamics
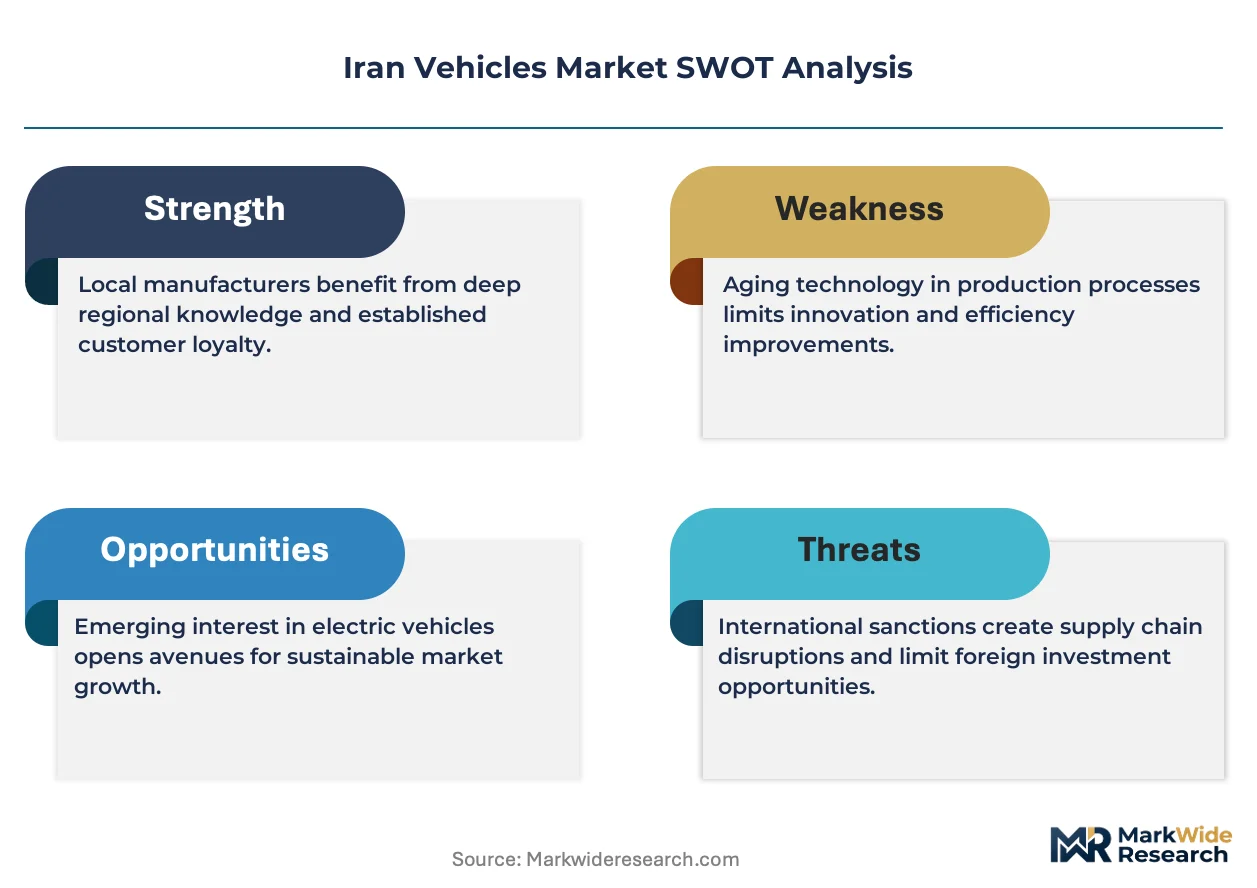
Local content mandates enforced by the Institute of Standards and Industrial Research of Iran are restructuring competitive access, privileging assemblers with captive foundry capacity and long-standing component supplier networks over import-dependent entrants.
Growth Catalysts
- CNG Infrastructure Expansion:Iran's abundant natural gas reserves and subsidized pricing regime create structural cost advantages for fleet operators converting commercial vehicle fleets to compressed natural gas powertrains.
- Logistics Modernization:Mining and construction sectors are accelerating procurement cycles for heavy-duty trucks as haulage networks connecting industrial corridors to port facilities undergo capacity upgrades.
- Domestic Content Thresholds:Mandatory localization benchmarks for knock-down kit assembly protect incumbent manufacturers with established stamping and foundry operations from pure import competition.
Market Restraints
- Currency Volatility:Rial depreciation against component supplier currencies erodes margin predictability for assemblers reliant on imported transmissions and electronic control modules.
- Refined Fuel Import Dependency:Sanctions-constrained access to gasoline and diesel refining technology limits powertrain diversification and locks the market into CNG-dominant configurations.
- Homologation Bottlenecks:Extended certification timelines for foreign-designed safety systems delay platform updates and compress product lifecycle competitiveness.
Strategic Opportunities
- Electric Powertrain Pilots:Policy attention toward reducing refined fuel import dependency is opening experimental regulatory windows for battery-electric bus and light commercial vehicle trials in Tehran's municipal fleet.
- Provincial Dealership Density:Economy passenger segments in secondary cities remain underserved relative to Tehran-centric distribution networks, offering volume expansion paths for regional assembly partnerships.
- After-Sales Service Unbundling:Fleet operators are separating maintenance contracts from initial vehicle procurement, creating standalone service revenue pools for technical training and parts logistics specialists.
Industry Challenges
- Powertrain Calibration Expertise:Shortage of engineers fluent in CNG injection mapping and emissions optimization for Iran's altitude-variable terrain constrains product development velocity.
- Knock-Down Kit Integration:Reconfiguring assembly lines to accommodate variable component specifications from multiple foreign licensors creates tooling redundancy and quality consistency risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Vehicles Market |
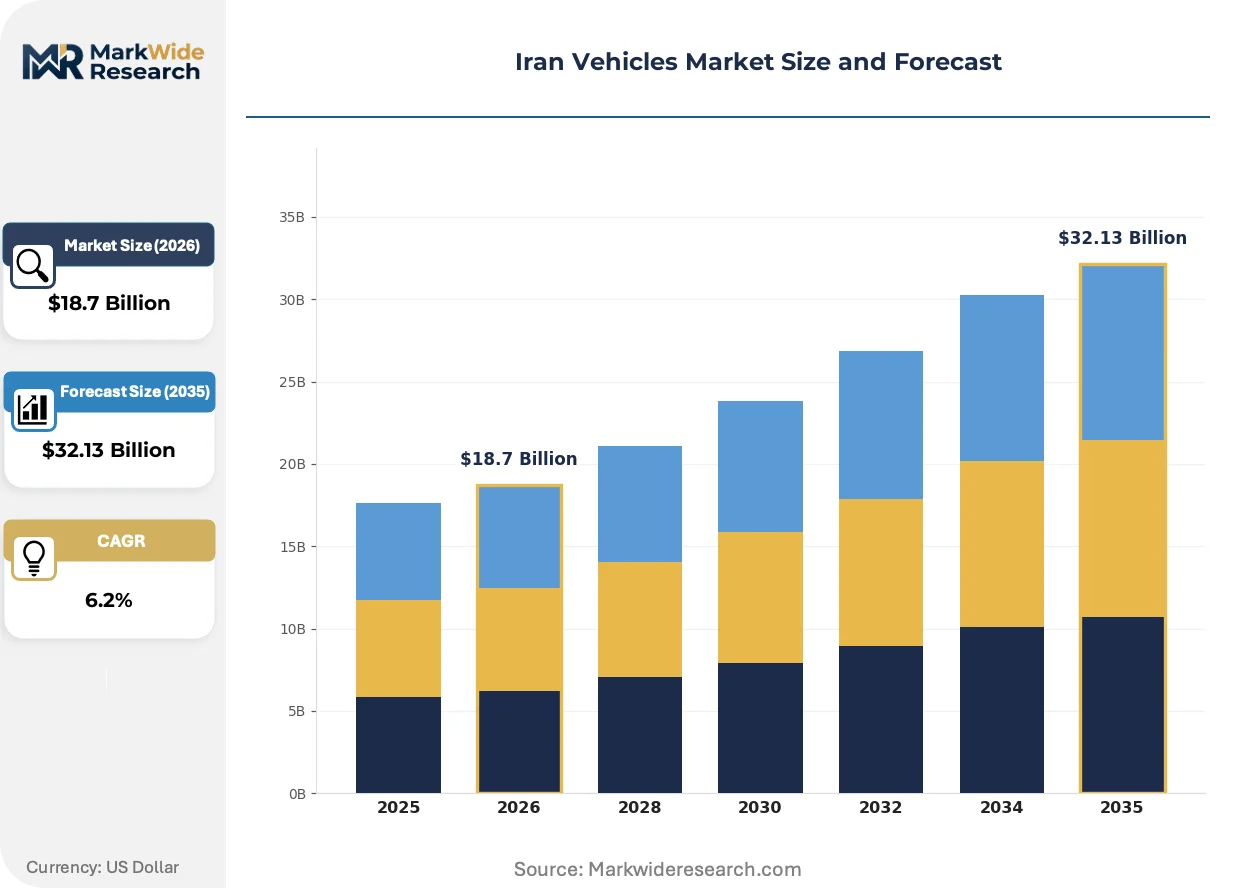
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Vehicles, Buses, Motorcycles Fuel Type: Petrol, Diesel, CNG, Electric End User: Individuals, Fleet Operators, Government Agencies, Manufacturers Market Segment: New Vehicles, Used Vehicles, Luxury Vehicles, Economy Vehicles |
| Companies Covered | Iran Khodro, Saipa, Kerman Motor, Bahman Group, Zamyad, Peugeot, Renault, Hyundai Motor, Kia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Vehicles Market Shifts & Advancements
Technology trajectories in the Iranian market are compressing around fuel system optimization and modular assembly architectures as sanctions pressure and domestic content rules converge on specific technical pathways.
Sequential CNG injection systems are collapsing the performance gap between dedicated natural gas powertrains and conventional gasoline equivalents. Fleet operators in mining haulage and urban bus transit are adopting these systems at accelerated replacement cycles. The technology is collapsing after-sales service complexity by reducing cylinder head wear and extending maintenance intervals relative to earlier mixer-type conversions.
The Institute of Standards and Industrial Research of Iran's phased emissions benchmarks are tightening particulate matter and NOx thresholds for commercial vehicle categories. Domestic assemblers must redesign exhaust after-treatment systems or risk homologation suspension. Heavy-duty truck lines serving the Kerman mining corridor face the steepest compliance redesign costs and shortest implementation timelines.
Leasing structures are displacing outright purchase for commercial vehicle acquisition among mid-sized logistics operators. Tehran-based fleet management providers are bundling maintenance and fuel supply into per-kilometer contracts. This shift concentrates buyer power among a handful of fleet aggregators and compresses manufacturer direct sales relationships in the capital region.
Iran Vehicles Market Segmentation
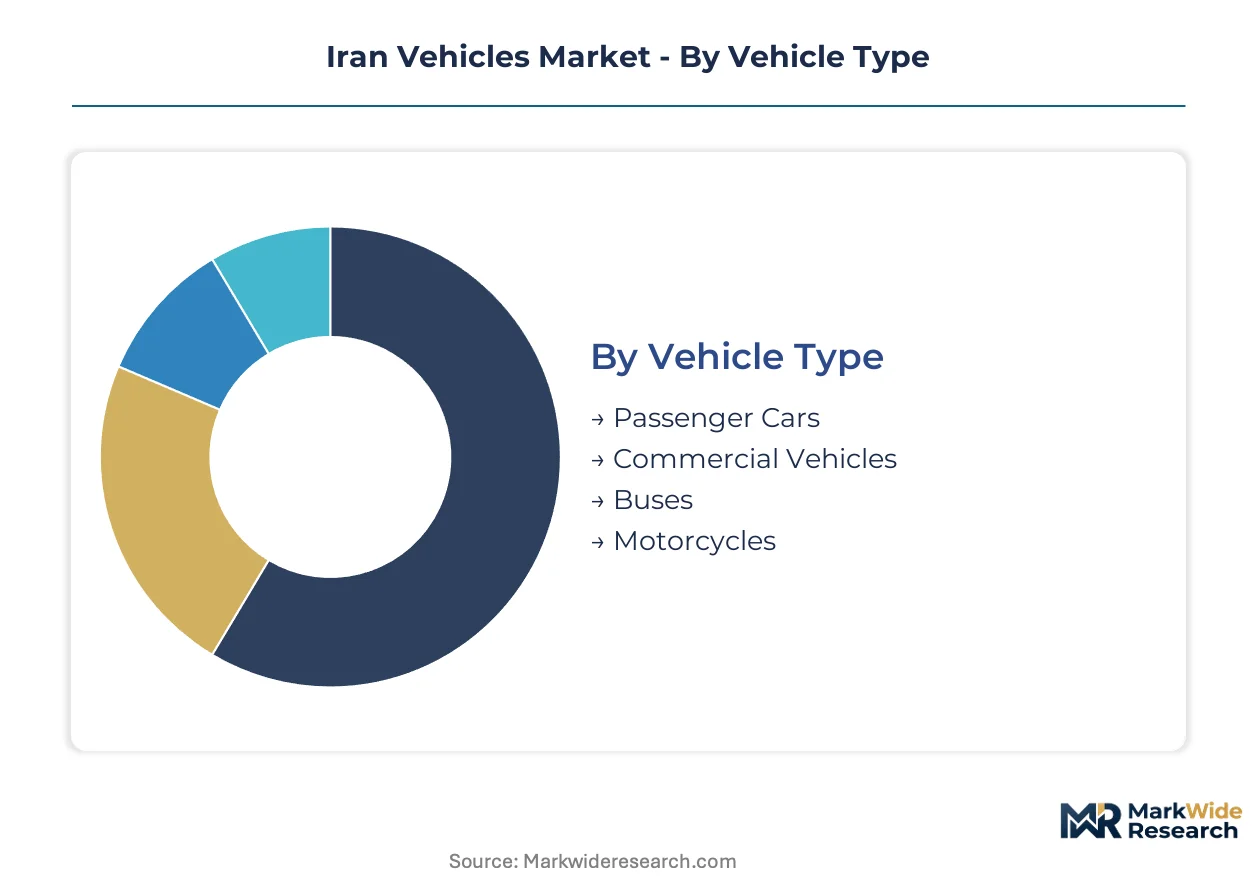
Segmentation in the Iranian market reveals how procurement cycles, fuel subsidies, and localization mandates concentrate margin pools across distinct vehicle categories. Understanding these fault lines helps stakeholders align assembly capacity with the replacement rhythms and regulatory exposure of each segment.
Vehicle Type:
Replacement cycles vary dramatically across this dimension, with motorcycles turning over fastest due to lower price points and harsher operating conditions, while buses operate on decade-long procurement timelines tied to municipal budget cycles.
- Passenger Cars:Four-door sedans and hatchbacks designed for personal mobility dominate transaction volumes across Tehran and provincial centers. Tehran's dense urban corridors and Iran Khodro's integrated foundry operations sustain concentrated demand for compact and mid-size configurations, though currency volatility on imported electronic control modules compresses margin predictability for assemblers.
- Commercial Vehicles:Heavy-duty trucks and light commercial vans engineered for goods movement serve mining haulage and logistics modernization. Fleet operators in the Kerman mining corridor and port-connected industrial zones are accelerating procurement as CNG infrastructure expansion reduces fuel cost exposure on long-haul routes.
- Buses:Municipal transit and intercity coaches accommodate high-capacity passenger movement. Tehran's municipal fleet pilots attract policy attention for electric powertrain trials aimed at reducing refined fuel import dependency.
- Motorcycles:Two-wheel motorized transport for last-mile delivery and personal mobility in congested urban environments. Dense dealership networks in secondary cities sustain volume for economy configurations.
Passenger cars dominate installed base. Commercial vehicles are where expansion concentrates.
Fuel Type:
Cost tier differentiation in this category tracks directly to subsidy levels and infrastructure availability, with CNG holding structural advantage from abundant domestic reserves.
- CNG:Compressed natural gas powertrains configured with sequential injection systems that narrow performance gaps with gasoline equivalents. Fleet operators converting commercial vehicle fleets exploit subsidized pricing regimes that undercut petrol by substantial margins, particularly in mining and construction applications.
- Petrol:Conventional gasoline internal combustion engines subject to sanctions-constrained refining capacity and import dependency. Individual buyers in Tehran and surrounding industrial corridors face periodic supply disruptions that erode powertrain reliability perceptions.
- Diesel:Compression-ignition engines for heavy-duty commercial applications requiring torque density for haulage. The Institute of Standards and Industrial Research of Iran's tightening particulate matter thresholds force exhaust after-treatment redesigns on truck lines serving the Kerman corridor.
- Electric:Battery-electric powertrains in pilot deployment for municipal bus and light commercial trials. Policy windows favor Tehran-based fleet management providers bundling charging infrastructure into per-kilometer contracts.
CNG commands the largest share of new commercial vehicle registrations. Electric configurations are climbing the fastest as regulatory windows open.
End User:
Customer type in this market determines financing structure, after-sales attachment, and sensitivity to currency-driven price volatility.
- Fleet Operators:Mid-sized logistics and mining sector buyers acquiring vehicles through leasing structures that unbundle maintenance from procurement. Tehran-based aggregators concentrate buyer power and compress manufacturer direct sales relationships through per-kilometer contracts bundling fuel supply and service.
- Individuals:Personal mobility purchasers prioritizing upfront affordability and dealership proximity over total cost of ownership. Provincial cities remain underserved relative to Tehran-centric distribution networks.
- Government Agencies:Municipal and national procurement bodies subject to domestic content mandates and extended homologation timelines. Experimental regulatory windows for electric bus pilots originate from this segment's policy priorities.
- Manufacturers:Industrial buyers acquiring specialized vehicles for in-plant material movement and captive logistics. Knock-down kit integration requirements from the Institute of Standards and Industrial Research of Iran constrain supplier selection.
Individual buyers represent the deepest installed base. Fleet operators are gaining share fastest as leasing structures displace outright purchase.
Market Segment:
Maturity and margin structure diverge sharply here, with new vehicle sales tied to localization compliance and used vehicles absorbing demand from currency-constrained buyers.
- Economy Vehicles:Entry-price-point configurations emphasizing basic transportation functionality over feature content. Saipa's dense provincial dealership networks sustain volume leadership in this tier.
- New Vehicles:Factory-fresh units subject to mandatory domestic content thresholds and homologation procedures. Assembly models with captive foundry and stamping operations retain economic viability against currency volatility.
- Used Vehicles:Pre-owned transactions absorbing demand from buyers priced out of new vehicle markets by rial depreciation. Quality consistency risks from variable maintenance histories constrain premium pricing.
- Luxury Vehicles:Premium configurations with elevated feature content and imported component exposure. Sanctions and currency constraints compress volumes to negligible levels.
Economy vehicles dominate transaction volumes. New vehicle sales are where manufacturer investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tehran commands premium pricing power for commercial vehicles while provincial assembly centers absorb volume-driven economy segments. The pricing asymmetry reflects concentrated fleet procurement in the capital region against dispersed individual demand across secondary cities. Currency volatility amplifies this divergence by compressing margins on imported components in Tehran while local content-heavy operations in outlying zones retain cost stability.
Tehran Province
Fleet operators and municipal procurement bodies concentrate demand for CNG-configured heavy trucks and electric bus pilots. The Institute of Standards and Industrial Research of Iran enforces emissions benchmarks that shape homologation timelines for vehicles entering this corridor. Industrial zones west of Tehran host stamping and foundry operations that feed knock-down kit assembly lines serving the capital's logistics modernization.
Kerman Province
Mining sector haulage requirements drive accelerated replacement cycles for heavy-duty diesel and CNG trucks. Domestic content mandates protect local assemblers with established supplier networks from import competition. The Kerman mining corridor functions as the primary demand node for commercial vehicles configured to altitude-variable terrain and extreme duty cycles.
Isfahan Province
Manufacturing clusters and steel production facilities generate captive logistics demand for specialized industrial vehicles. Provincial dealership networks extend economy passenger car distribution beyond Tehran-centric channels. The Isfahan industrial zone anchors assembly partnerships targeting mid-sized fleet operators with localized maintenance capabilities.
Mazandaran Province
Port-connected distribution infrastructure and agricultural processing create mixed demand for light commercial vans and trucks. CNG infrastructure expansion along the Caspian corridor reduces fuel cost exposure for regional haulage operators. The Tonekabon-Chalus industrial strip concentrates vehicle service operations supporting cross-border trade routes.
East Azerbaijan Province
Border trade logistics and provincial manufacturing sustain demand for durable economy vehicles with simplified maintenance requirements. Currency-driven price volatility pushes individual buyers toward used vehicle markets and basic configurations. The Tabriz industrial cluster hosts component fabrication supporting knock-down kit integration for regional assembly.
Iran Vehicles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying foundry and stamping inputs to licensed assemblers. The market structure concentrates around three domestic manufacturers with captive production infrastructure and long-standing regulator relationships. Two strategic archetypes dominate: vertically integrated assemblers controlling cost structures through in-house metalworking, and foreign-licensed operators dependent on knock-down kit imports subject to homologation bottlenecks. Competitive moves center on localization threshold compliance and provincial dealership density expansion.
Within the integrated assembler tier, Iran Khodro and Saipa occupy positions shaped by decades of operational licensing under domestic content regimes. Kerman Motor represents the specialized commercial vehicle archetype, anchoring mining and construction fleet supply through regional assembly partnerships. These three entities exemplify how captive foundry capacity and established component supplier networks privilege incumbents over import-dependent entrants facing currency volatility and extended certification timelines.
| Leading Market Players |
|---|
| Iran Khodro |
| Saipa |
| Kerman Motor |
| Bahman Group |
| Zamyad |
| Peugeot |
| Renault |
| Hyundai Motor |
| Kia |
| Others |
Supply & Pricing Matrix
The Tehran-Kerman haulage corridor's fuel cost dynamics concentrate supply power among CNG-integrated assemblers while forcing three-tier price differentiation across configured-to-order, standard, and economy vehicle tiers. Domestic foundry capacity anchors cost stability for incumbents as currency volatility erodes margins on import-dependent kit assembly.
Pricing Analysis
Configured-to-order pricing for CNG-configured heavy trucks commands substantial premiums over standard assembly-line units due to sequential injection calibration and altitude-variable terrain mapping. Price differentiation hinges on domestic content certification tiers from the Institute of Standards and Industrial Research of Iran and after-sales service bundling density. Cost compression in economy passenger segments intensifies as rial depreciation pushes individual buyers toward basic configurations. Fleet operators exhibit lowest price sensitivity given per-kilometer contract structures that internalize fuel savings.
Supply Chain Analysis
Export-control regimes restricting advanced transmission and electronic control module technology limit component flows from Germany, Japan, and South Korea into Iranian assembly operations. Knock-down kit integration draws from China, Turkey, and domestic stamping facilities for body-in-white and powertrain housings. Single-source vulnerability concentrates in semiconductor-dependent engine management systems. Distribution runs through Tehran-based fleet aggregators and provincial dealership networks anchored by Saipa's secondary-city presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Iranian vehicle market functions as a service-attach opportunity where maintenance contract unbundling and CNG conversion servicing expand faster than hardware transaction volumes.
For Market Incumbents: Pre-empt knock-down kit import dependency by deepening captive foundry capacity for cylinder heads and transmission housings before currency volatility renders foreign-licensed assembly uneconomic. Secure provincial dealership density in Isfahan and Mazandaran against emerging regional assembly partnerships threatening volume leadership. For New Entrants and Emerging Players: Pursue electric powertrain pilot participation in Tehran's municipal bus fleet where regulatory windows favor experimental battery-electric configurations. Target aftermarket service specialization for CNG sequential injection systems given shortage of qualified calibration engineers across the Kerman mining corridor. For Investors and Strategic Acquirers: Carve-out targets emerge from distressed foreign-licensed assemblers with homologation backlog and knock-down kit inventory exposure; these operations trade at structural discounts to replacement cost. Watch for inflection signals in central bank foreign exchange allocation policy toward automotive component imports.| Strategic Initiative | Industry Significance |
|---|---|
| CNG Infrastructure Partnership | Aligns fleet operators with subsidized fuel pricing through dedicated compression station networks. |
| Provincial Dealership Expansion | Captures economy vehicle demand in secondary cities underserved by Tehran-centric distribution. |
| Electric Powertrain Pilot | Positions manufacturers for regulatory preference in municipal procurement cycles. |
| After-Sales Service Unbundling | Creates standalone revenue pools from maintenance contracts separated from initial vehicle sales. |
| Domestic Content Threshold Compliance | Preserves operational licensing under Institute of Standards and Industrial Research of Iran mandates. |
Research Methodology
The analysis maps passenger car, commercial vehicle, bus, and motorcycle segments, each validated through fleet procurement managers, dealership operators, foundry production heads, and regulatory affairs specialists at the Institute of Standards and Industrial Research of Iran. Primary fieldwork combined with customs records, vehicle registration databases, and industrial production indices enables bottom-up assembly volume triangulation against top-down fuel consumption and infrastructure deployment data.
Assumptions held currency volatility within observed rial depreciation bands against component supplier currencies while varying domestic content threshold compliance scenarios across the projection horizon. Segmentation dimensions span vehicle class, propulsion architecture, end-user procurement structure, and regional production cluster. CAGRs derive from replacement cycle modeling calibrated to fleet operator interview data and municipal budget cycle documentation.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by captive foundry operators or sudden liberalization of knock-down kit import rules would shift outcomes. Material shifts in sanctions enforcement intensity or central bank foreign exchange allocation prioritization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
United States Commercial Vehicles Market