
 Smart Rail Suite Solutions Market | 2026-2036
Smart Rail Suite Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Rail Suite Solutions Market Analytics
CE marking under the EU's Rail System Directive is bifurcating the competitive landscape between established European incumbents and challengers seeking market access. Siemens Mobility leverages its in-house signaling heritage to anchor large-scale fleet management deployments across German and Austrian networks. Alstom competes through integrated platform offerings that combine IoT-enabled asset monitoring with predictive maintenance algorithms. Huawei Technologies differentiates by positioning its AI analytics stack as a cost-efficient alternative for cloud-based ticketing architectures in emerging rail markets.
Smart Rail Suite Solutions denote integrated software-hardware ecosystems that orchestrate rail operations through real-time data fusion, encompassing ETCS Level 2/3 signaling protocols, on-board IoT sensors, and centralized traffic management algorithms. These systems enable operators to optimize headways, reduce energy consumption, and deliver predictive passenger information across multimodal journeys. Fleet Management currently occupies the largest value pool as aging rolling stock fleets require condition-based monitoring to extend service life, while AI Analytics represents the fastest-expanding technology segment as operators deploy machine learning for demand forecasting and anomaly detection. Cloud Computing deployments are gaining traction among private operators seeking to avoid capital-intensive on-premise infrastructure.
The European Union Agency for Railways enforces interoperability standards that dictate which subsystems suppliers may integrate into cross-border networks, while the Federal Railroad Administration in the United States mandates Positive Train Control compliance that shapes procurement specifications for domestic operators. China's National Railway Administration issues GB standards for smart rail components that create de facto technical barriers for foreign vendors. Stakeholders must monitor how divergent certification timelines across these jurisdictions affect product development roadmaps and partnership strategies.
Market Dynamics
The Smart Rail Suite Solutions market faces a structural inflection where ETCS Level 3 migration is forcing incumbent signaling vendors to rebuild architectures around moving-block principles rather than fixed-block legacy systems. This shift compresses hardware margins while elevating software and integration service value pools.
Growth Catalysts
- EU Green Deal modal shift mandates:Binding emissions targets for 2030 are redirecting public transport budgets toward rail digitalization, with procurement specifications now weighting energy optimization algorithms equally with safety certification.
- China's high-speed corridor expansion:The National Railway Administration's GB standards for smart components are creating captive demand for integrated signaling-telecom platforms across 40,000 kilometers of operational track.
- Edge computing architectures:On-train processing units are reducing latency for real-time obstacle detection, enabling operators to tighten headways without infrastructure overbuild.
Market Restraints
- Silicon carbide supply concentration:Power electronics for traction systems depend on wafer fabrication concentrated in Taiwan and Japan, exposing rolling stock OEMs to geopolitical supply shocks.
- ETCS certification timelines:European Union Agency for Railways interoperability approvals average 18-24 months, freezing product roadmaps for vendors targeting cross-border deployments.
- Legacy copper signaling infrastructure:Embedded base of relay-based interlocking systems in Eastern European networks creates technical debt that slows digital overlay adoption.
Strategic Opportunities
- India Dedicated Freight Corridor:The 1,500-kilometer eastern and western freight corridors require greenfield signaling systems, bypassing legacy integration constraints that burden brownfield European networks.
- Digital twin convergence:Integration of BIM asset databases with real-time sensor streams is enabling predictive maintenance contracts that capture lifecycle value beyond initial system sales.
- Cloud-based ticketing architectures:Private operators in Southeast Asia are adopting SaaS fare collection to avoid capital-intensive on-premise infrastructure, opening subscription revenue models.
Industry Challenges
- Embedded systems cybersecurity:OT/IT convergence exposes safety-critical networks to ransomware vectors, requiring rail-specific security architects scarce in general IT labor markets.
- Multi-vendor integration complexity:ETCS implementations demand coordination between signaling, telecom, and rolling stock suppliers, with interface disputes delaying commissioning schedules.
- Radio spectrum fragmentation:GSM-R replacement timelines diverge across EU member states, complicating cross-border train authorization system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Rail Suite Solutions Market |
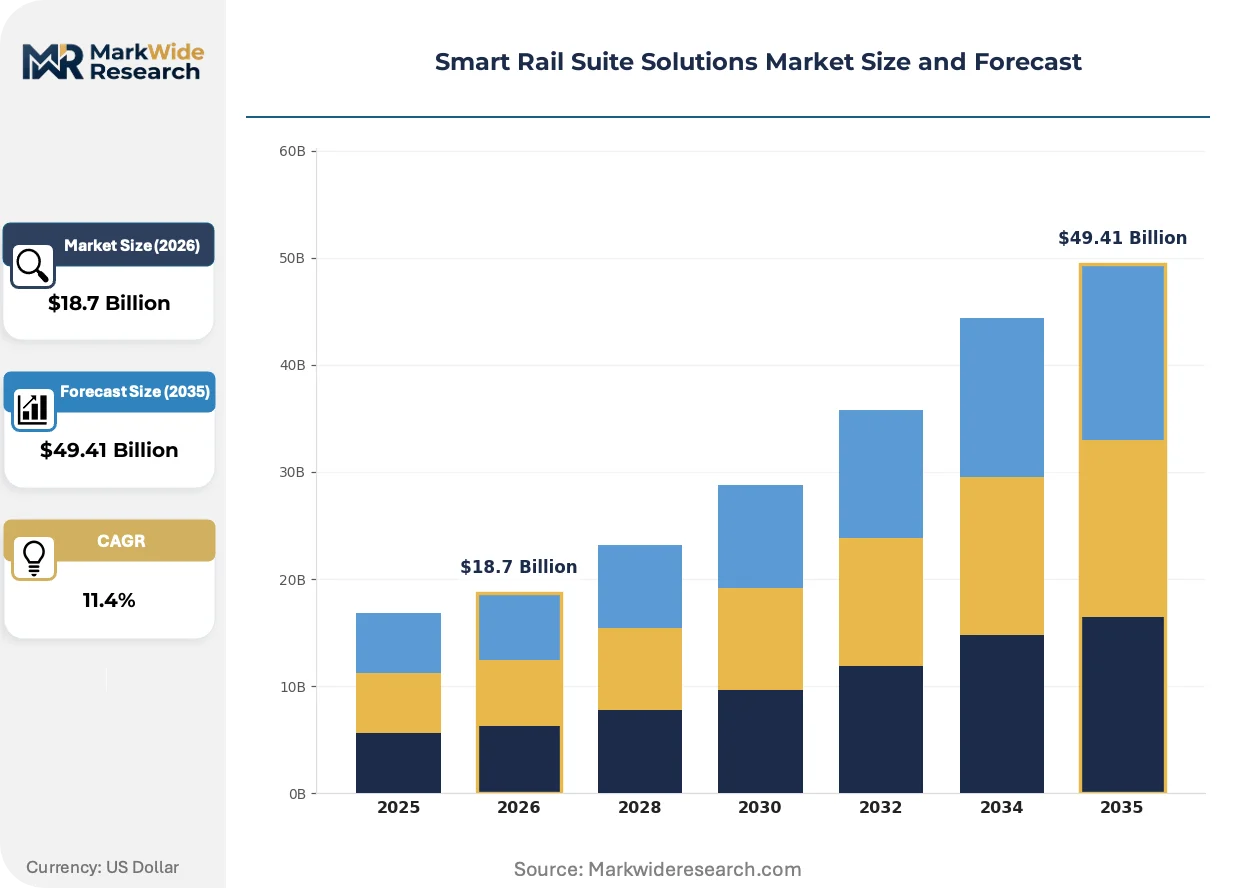
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asset Management, Passenger Information, Fleet Management, Ticketing Solutions End User: Transit Authorities, Railway Operators, Government Agencies, Private Operators Technology: IoT Solutions, AI Analytics, Cloud Computing, GPS Systems Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Siemens Mobility, Alstom, Hitachi Rail, Thales Group, Huawei Technologies, Cisco Systems, ABB Group, Indra Sistemas, Bombardier Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Rail Suite Solutions Market Evolving Landscape
Software-defined signaling is fragmenting traditional hardware-centric value chains, with functionality migrating from trackside cabinets to centralized cloud platforms and edge compute nodes. This architectural shift is compressing equipment supplier margins while elevating systems integrators and data analytics vendors.
Artificial intelligence-based demand forecasting is decomposing fixed-schedule operations into dynamic capacity allocation models. Urban metro operators in Singapore and Dubai are deploying machine learning for passenger flow prediction, enabling 15-20% energy savings through train load balancing. The technology is decomposing traditional timetabling departments into algorithmic operations centers.
The EU AI Act's risk classification framework is imposing conformity assessment obligations on safety-critical rail algorithms. Vendors must now document training data provenance and model drift monitoring for predictive maintenance systems deployed in cross-border networks. German and Austrian operators are requiring algorithmic impact assessments as standard procurement clauses, filtering out challengers lacking compliance infrastructure.
Outcome-based service contracts are displacing capital-heavy system purchases among private concession holders. British and Australian rail franchises now specify availability guarantees and energy consumption targets rather than equipment specifications, transferring operational risk to suppliers. This reconfiguration favors vendors with captive maintenance networks and penalizes pure-play technology licensors.
Smart Rail Suite Solutions Market Segmentation
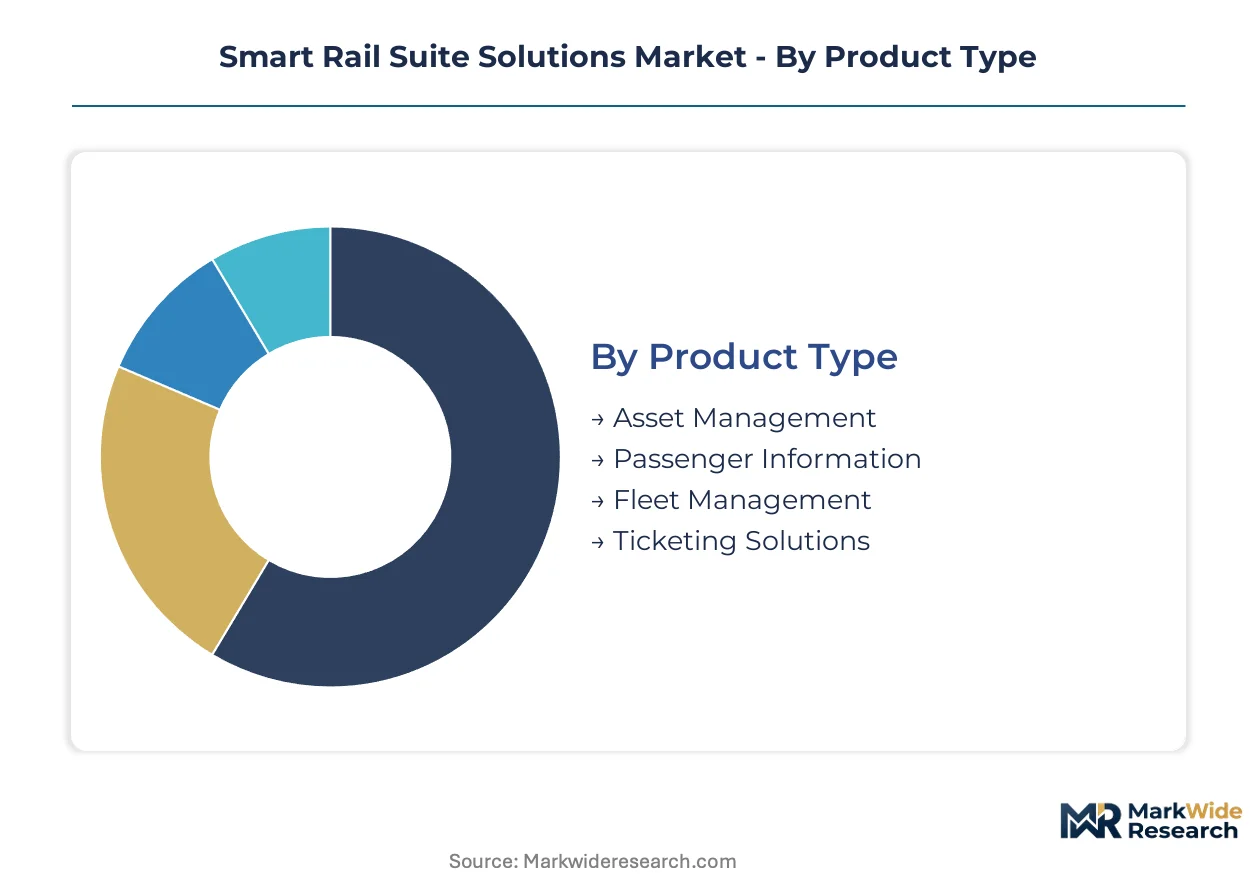
Smart Rail Suite Solutions vendors configure product portfolios around four intersecting dimensions. Procurement patterns differ sharply between public transit authorities seeking integrated platforms and private operators favoring modular cloud deployments.
Product Type:
Margin pools concentrate in systems requiring continuous sensor telemetry and predictive algorithm development rather than one-time hardware installation.
- Fleet Management:Condition-based monitoring systems aggregate vibration, thermal, and electrical signature data from rolling stock components. Indian Dedicated Freight Corridor operators and German intercity networks are consolidating procurement around integrated platforms that combine ETCS signaling with real-time asset health dashboards.
- AI Analytics:Machine learning stacks for demand forecasting and anomaly detection command premium pricing through subscription models. Singapore and Dubai metro authorities are deploying passenger flow prediction algorithms that optimize train loading and reduce energy consumption through dynamic capacity allocation.
- Asset Management:Digital twin platforms integrating BIM databases with sensor streams enable lifecycle maintenance contracts.
- Passenger Information:Multimodal journey planners with real-time disruption rerouting are standardizing across EU networks under interoperability mandates.
- Ticketing Solutions:Account-based fare collection systems are displacing legacy smart card infrastructure in Southeast Asian markets.
Fleet Management holds installed capacity across European and North American networks. AI Analytics is rotating up the share rankings through greenfield deployments in Asia-Pacific and Middle Eastern corridors.
End User:
Customer archetypes separate by procurement flexibility, risk tolerance, and regulatory compliance burden.
- Railway Operators:Incumbent national carriers in Germany, France, and Japan dominate capital deployment with multi-decade fleet replacement cycles. These entities specify integrated signaling-telecom-asset management platforms that lock in vendors through proprietary data architectures and certified maintenance protocols.
- Private Operators:British and Australian rail franchises are shifting toward outcome-based contracts specifying availability guarantees and energy targets rather than equipment specifications. This transfers operational risk to suppliers and favors vendors with captive service networks.
- Transit Authorities:Urban metro operators in China and India are accelerating integrated platform procurement for corridor expansion programs.
- Government Agencies:National railway administrations in China and India set technical standards that shape vendor qualification criteria.
Railway Operators hold installed capacity through legacy fleet embedded base. Private Operators is rotating up the share rankings through concession restructuring and risk-transfer contracting models.
Technology:
Technology stacks are bifurcating between edge-heavy architectures for safety-critical functions and cloud-native platforms for passenger-facing services.
- IoT Solutions:On-train sensor networks and trackside monitoring devices form the physical layer for predictive maintenance. These systems are concentrating procurement in China's high-speed rail expansion where GB standards mandate domestic component certification.
- Cloud Computing:Centralized data lakes and SaaS delivery models are gaining traction among private operators seeking to avoid capital-intensive on-premise infrastructure. Southeast Asian operators are adopting cloud-based ticketing architectures with subscription pricing.
- AI Analytics:Algorithmic operations centers are displacing traditional timetabling departments in Singapore and Dubai.
- GPS Systems:Precise positioning for train authorization is standardizing as GSM-R replacement timelines diverge across EU member states.
IoT Solutions holds installed capacity through embedded trackside and on-train sensor deployments. Cloud Computing is rotating up the share rankings through private operator preference for opex-based delivery models.
Deployment:
Deployment architecture selection tracks operator IT maturity, data sovereignty requirements, and latency sensitivity for safety functions.
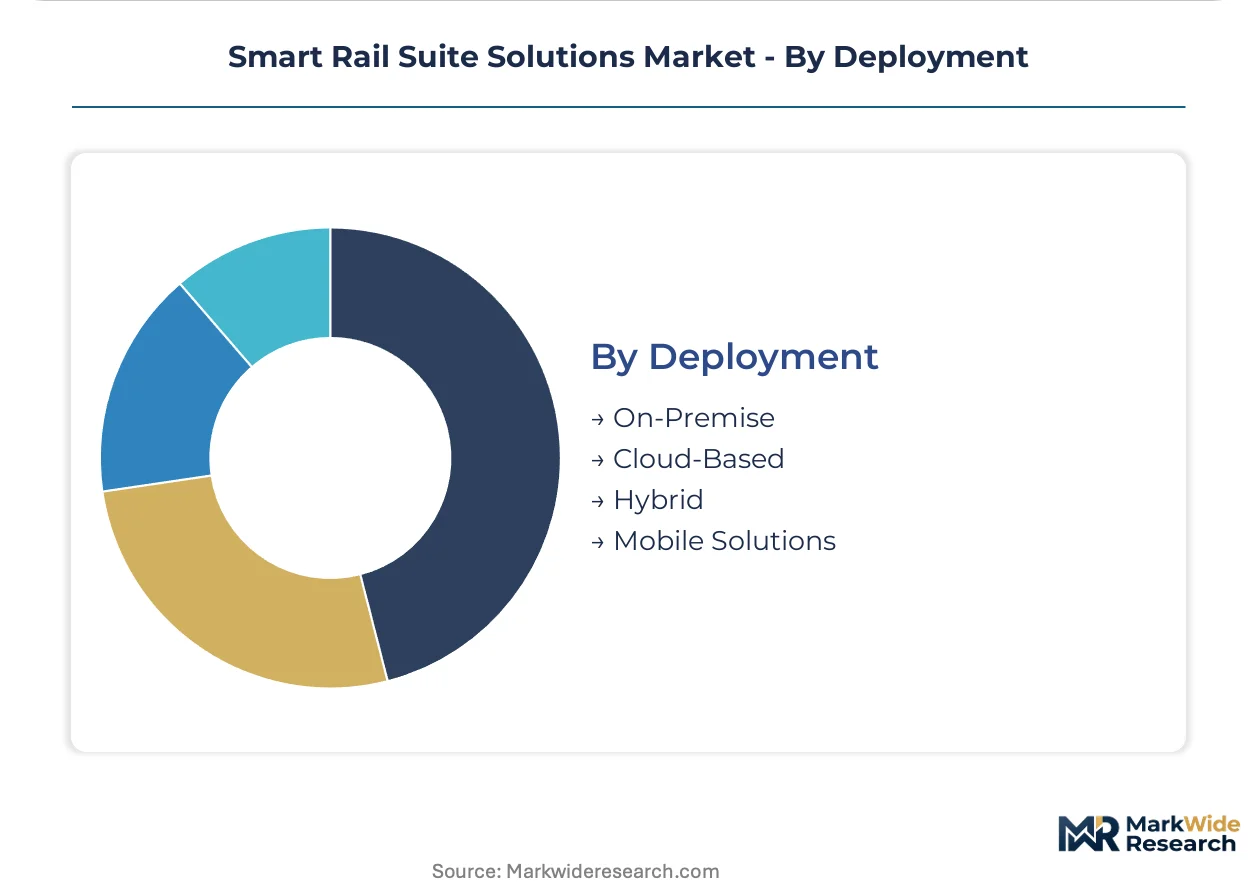
- On-Premise:Air-gapped infrastructure for ETCS signaling and safety-critical networks remains mandatory for cross-border EU deployments under EBA and national rail authority cybersecurity directives. These installations command premium integration services and long-term maintenance lock-in.
- Hybrid:Split architectures processing safety functions at the edge with passenger analytics in cloud environments are emerging as the dominant configuration for urban metro operators. This balances latency requirements with computational scalability.
- Cloud-Based:Pure SaaS deployments are standard for ticketing and passenger information in deregulated markets.
- Mobile Solutions:Driver and maintenance crew applications are proliferating as workforce digitization accelerates.
On-Premise holds installed capacity through safety-certification requirements and legacy infrastructure embedded base. Hybrid is rotating up the share rankings as operators reconcile OT/IT convergence with operational technology security constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates redirect public transport budgets toward rail digitalization, with procurement specifications now weighting energy optimization algorithms equally with safety certification. China's National Railway Administration issues GB standards that create captive demand for integrated signaling-telecom platforms. India's Dedicated Freight Corridor modernization programs accelerate greenfield signaling procurement.
China
The National Railway Administration's GB standards for smart components mandate domestic certification across 40,000 kilometers of operational track. MIIT regulations enforce data localization requirements for cloud-based rail operations. Beijing and Shanghai anchor high-speed corridor expansion programs where integrated platform procurement concentrates.
Germany
Deutsche Bahn's multi-decade fleet replacement cycles drive integrated signaling-telecom-asset management platform specifications. KBA enforces ETCS interoperability approvals that average 18-24 months for cross-border deployments. Berlin and Munich host condition-based monitoring system rollouts combining ETCS signaling with real-time asset health dashboards.
India
The Dedicated Freight Corporation requires greenfield signaling systems across 1,500 kilometers of eastern and western freight corridors. CEA mandates and PLI scheme incentives accelerate domestic component sourcing for smart rail infrastructure. Gujarat and Maharashtra concentrate manufacturing clusters for trackside monitoring device production.
United States
The Federal Railroad Administration mandates Positive Train Control compliance that shapes procurement specifications for domestic operators. FERC regulations intersect with rail electrification programs in select corridors. California and the Northeast Corridor lead passenger rail digitalization with hybrid edge-cloud architectures for urban metro systems.
Singapore
Land Transport Authority procurement prioritizes machine learning stacks for passenger flow prediction and dynamic capacity allocation. The country's national rail regulator enforces cybersecurity standards for OT/IT converged networks. The city-state anchors algorithmic operations center deployments that optimize train loading and reduce energy consumption.
Smart Rail Suite Solutions Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and service network depth. The vendor base stratifies between European incumbents with embedded signaling heritage and technology challengers positioning cost-efficient alternatives. Three archetypes dominate: integrated platform providers, component specialists, and systems integrators. M&A activity concentrates on predictive maintenance algorithm capabilities, while strategic partnerships address multi-vendor ETCS integration complexity.
Within the integrated platform tier, Siemens Mobility and Alstom exemplify European incumbents leveraging in-house signaling heritage. Huawei Technologies occupies a position among technology challengers offering AI analytics stacks for emerging rail markets. These three anchors represent divergent approaches to cloud-based ticketing architectures and edge computing deployments.
| Leading Market Players |
|---|
| Siemens Mobility |
| Alstom |
| Hitachi Rail |
| Thales Group |
| Huawei Technologies |
| Cisco Systems |
| ABB Group |
| Indra Sistemas |
| Bombardier Transportation |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month ETCS certification timelines from the European Union Agency for Railways compress vendor cash conversion cycles while elevating pricing power for certified incumbents. This lead-time band concentrates procurement premiums on interoperability-tested platforms and forces challengers to absorb carrying costs or cede margin.
Pricing Analysis
Certification level creates the primary spread between EU-incumbent premium tiers and challenger economy positioning. Three-tier pricing structure across safety-certified, interoperable-standard, and uncertified-economy levels tracks ETCS Level 2/3 validation status. Pricing pressure stems from cloud-native SaaS entrants undercutting on-premise perpetual licenses in Southeast Asian markets. Private operators exhibit highest price sensitivity through outcome-based contracting, while national carriers absorbing long-term fleet replacement cycles show lowest sensitivity to upfront capital.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for silicon carbide wafers and specialized signaling components. Manufacturing concentrates in Germany, France, and China, with GB-standard certification requirements tethering Chinese domestic production to captive demand. Raw material dependencies span silicon carbide substrates, high-reliability capacitors, and ruggedized edge-compute enclosures. Single-source vulnerability concentrates in Taiwanese wafer fabrication for traction power electronics. Distribution runs through systems integrators holding EBA-certified maintenance protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as ETCS Level 3 migration decomposes integrated platforms into modular software-hardware bundles, creating specialist niches for predictive algorithm developers and edge-compute vendors.
For Market Incumbents: Consolidate predictive maintenance algorithm capabilities through targeted acquisition of machine-learning specialists lacking certification infrastructure. Deepen captive service networks in India and Southeast Asia to capture outcome-based contract premiums. Lock in national carrier relationships through proprietary data architectures that elevate switching costs.
For New Entrants and Emerging Players: Cloud-native ticketing architectures in Southeast Asian private operator markets represent the most penetrable white-space target. Deploy SaaS fare collection with subscription pricing to bypass capital-intensive on-premise infrastructure requirements. Partner with regional systems integrators holding EBA or national rail authority maintenance certifications to bridge compliance gaps.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because interoperability certification creates durable moats around installed vendor bases. Target acquisition profiles center on predictive maintenance algorithm shops with proven rail deployments but lacking CE marking infrastructure. Watch ETCS Level 3 commissioning timelines as the inflection signal—acceleration indicates software-margin expansion, while delays prolong hardware-dependency.
| Strategic Initiative | Industry Significance |
|---|---|
| ETCS Level 3 Platform Migration | Rebuilds architectures around moving-block principles, compressing hardware margins while elevating software value pools. |
| Predictive Maintenance Algorithm Acquisition | Captures lifecycle revenue beyond initial system sales through outcome-based availability contracts. |
| Edge-Compute Deployment Partnership | Reduces latency for real-time obstacle detection, enabling headway tightening without infrastructure overbuild. |
| Cloud-Native Ticketing Launch | Opens subscription revenue models among Southeast Asian private operators avoiding capex-heavy infrastructure. |
| Digital Twin Integration | Combines BIM asset databases with sensor streams to enable predictive maintenance contracts capturing full lifecycle value. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork encompassed rail operator procurement directors, signaling systems integrators, EBA certification consultants, and rolling stock OEM platform engineers. Secondary sources included European Union Agency for Railways interoperability documentation, Federal Railroad Administration PTC compliance records, National Railway Administration GB standards filings, and customs data for silicon carbide wafer trade flows. Bottom-up vendor capacity assessments and top-down modal shift budget allocations were triangulated.
Sensitivity analysis tested forecast outputs against divergent ETCS migration timelines and silicon carbide supply disruption scenarios across the projection horizon. Segmentation dimensions encompassed product type, end-user archetype, technology stack, and deployment architecture, with additional modeling of certification-status tier. CAGRs derived from rolling stock fleet replacement cycles and greenfield corridor expansion budgets. Industry-specific inputs included ETCS Level 2/3 commissioning schedules and cloud-ticketing SaaS adoption curves.
Material uncertainties — geopolitical semiconductor supply shocks, divergent EU member state GSM-R replacement timelines, and ransomware-driven cybersecurity procurement freezes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding modal shift budget continuity and certification timeline stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Automotive V2X Market