
 Smart Vehicle Cabin Market | 2026-2036
Smart Vehicle Cabin Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Vehicle Cabin Market Analytics
Multi-source component procurement is recalibrating as tier-one suppliers balance captive sensor production against external microcontroller sourcing. Robert Bosch GmbH leverages its semiconductor foundry partnerships to secure actuator supply chains. NVIDIA Corporation anchors autonomous cabin computing with its Drive platform architecture. Denso Corporation specializes in climate control integration, sustaining dominance across Japanese OEM programs.
A smart vehicle cabin constitutes the integrated interior environment combining electronic interfaces, environmental management, and occupant monitoring systems operating through CAN bus architectures with sub-50 millisecond latency requirements. Its commercial purpose centers on differentiating vehicle user experience while enabling software-defined revenue streams for manufacturers. Infotainment Systems generate the largest installed base though Connectivity Solutions represent the fastest-expanding margin pool as over-the-air update architectures proliferate. Electric Vehicles application demand outpaces luxury segments, with cabin thermal management becoming critical for battery range optimization.
NHTSA occupant safety standards and the EU AI Act biometric governance framework are tightening certification requirements for driver monitoring cameras and emotion detection algorithms. ISO 26262 functional safety mandates shape microcontroller selection and software validation spend across supplier tiers. Stakeholders must weigh regulatory compliance investment against the pace of software monetization model maturation.
Market Dynamics
The EU AI Act biometric governance framework is compressing certification timelines for driver monitoring systems while forcing architectural redesigns across European OEM supply chains. Tier-one suppliers must validate emotion detection algorithms under stricter data handling protocols before 2026 model year deployments.
Growth Catalysts
- EU AI Act compliance mandates:Biometric data handling requirements for in-cabin monitoring systems are accelerating hardware refresh cycles across German automotive engineering clusters. OEMs must replace legacy camera architectures to meet algorithmic transparency standards.
- Electric vehicle thermal optimization:Cabin climate management directly impacts battery range performance, pulling advanced HVAC electronics into EV platform specifications. Thermal efficiency targets above 25% improvement over ICE equivalents are driving sensor density increases.
- Over-the-air monetization architectures:Software-defined revenue streams are expanding addressable value per vehicle through subscription-enabled feature activation. Connectivity Solutions margins are outpacing hardware sales as update infrastructure matures.
Market Restraints
- ISO 26262 validation costs:Functional safety certification for microcontroller selection adds 18-24 month lead times to new cabin electronics programs. Supplier R&D budgets are absorbing disproportionate software verification spend.
- Semiconductor foundry concentration:Actuator supply chains remain captive to Taiwan and South Korean wafer capacity allocations. Bosch's foundry partnerships provide partial insulation but cannot eliminate allocation risk during automotive demand surges.
- GDPR biometric friction:Cross-border data transfer restrictions are complicating cloud-based occupant analytics for vehicles sold across EU member states. Fleet operators face operational segmentation by jurisdiction.
Strategic Opportunities
- Japanese climate integration specialization:Denso's dominance in OEM programs creates partnership entry points for Western sensor suppliers seeking Asian market access. Joint development agreements on thermal management electronics offer technology transfer pathways.
- CAN bus latency optimization:Sub-50 millisecond response requirements are opening niche markets for deterministic Ethernet alternatives in premium cabin architectures. Real-time occupant safety systems demand deterministic networking beyond legacy bus capabilities.
- NHTSA occupant safety standard harmonization:US-EU regulatory convergence on driver monitoring camera specifications would reduce variant engineering costs. Unified certification pathways would accelerate platform scale economics.
Industry Challenges
- Embedded systems cybersecurity skill scarcity:CAN bus architecture hardening against intrusion requires specialized firmware engineering talent concentrated in German and US defense-adjacent labor pools. Automotive suppliers compete with aerospace for cleared personnel.
- Legacy ICE platform integration friction:Software-defined cabin features demand electrical architecture upgrades incompatible with 2018-2022 vehicle generations. Fleet retrofit economics remain unfavorable for mass-market deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Vehicle Cabin Market |
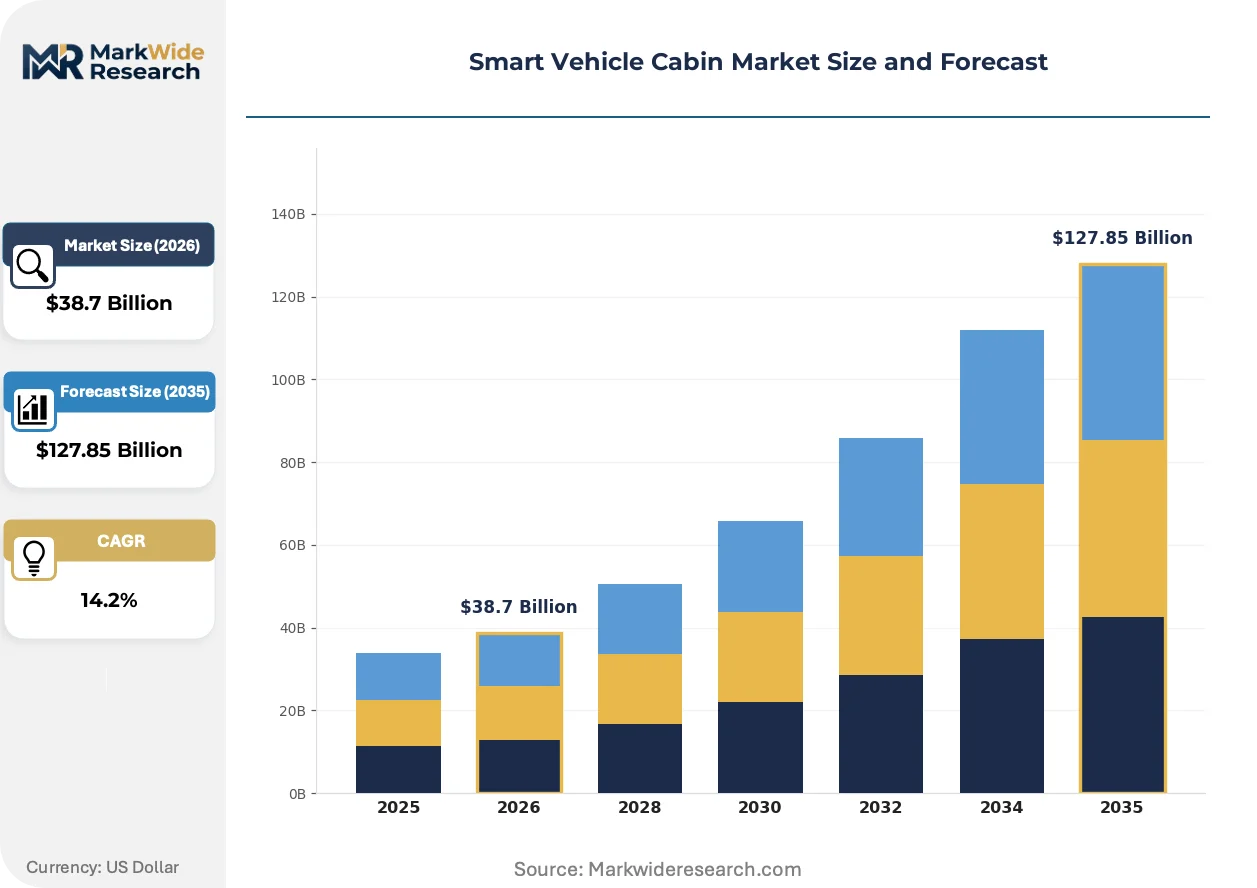
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Infotainment Systems, Climate Control, Advanced Driver Assistance, Connectivity Solutions Component: Displays, Sensors, Actuators, Microcontrollers End User: OEMs, Fleet Operators, Aftermarket Providers, Ride-Hailing Services Application: Luxury Vehicles, Compact Cars, Electric Vehicles, Commercial Trucks |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Panasonic Corporation, NVIDIA Corporation, HYUNDAI MOBIS, Valeo, Continental AG, Harman International, Yanfeng Automotive Interiors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Vehicle Cabin Market Evolving Landscape
Latency-sensitive occupant safety systems are forcing network architecture transitions beyond traditional automotive bus standards. Deterministic computing and edge inference are reshaping cabin electronics packaging and thermal design constraints.
Deterministic Ethernet is electrifying real-time data pathways between camera modules and central cabin controllers. Luxury OEMs are mandating time-sensitive networking for 2026 platform launches to support synchronized multi-sensor fusion. This protocol shift is compressing tier-two supplier margins as semiconductor vendors capture value migration from cabling to silicon.
REACH substance restrictions on flame-retardant cabin materials are accelerating bio-based polymer qualification programs. German suppliers face 2025 compliance deadlines for seat foam and dashboard substrates containing restricted halogen compounds. Interior component sourcing is regionalizing as Asian compounders lag European certification timelines by 18-36 months.
Fleet operators are unbundling after-sales cabin electronics service from traditional dealer maintenance contracts. Direct supplier relationships for over-the-air update management are displacing OEM-mediated service models in commercial vehicle segments. North American logistics operators lead this procurement evolution, negotiating uptime guarantees separate from powertrain service agreements.
Smart Vehicle Cabin Market Segmentation
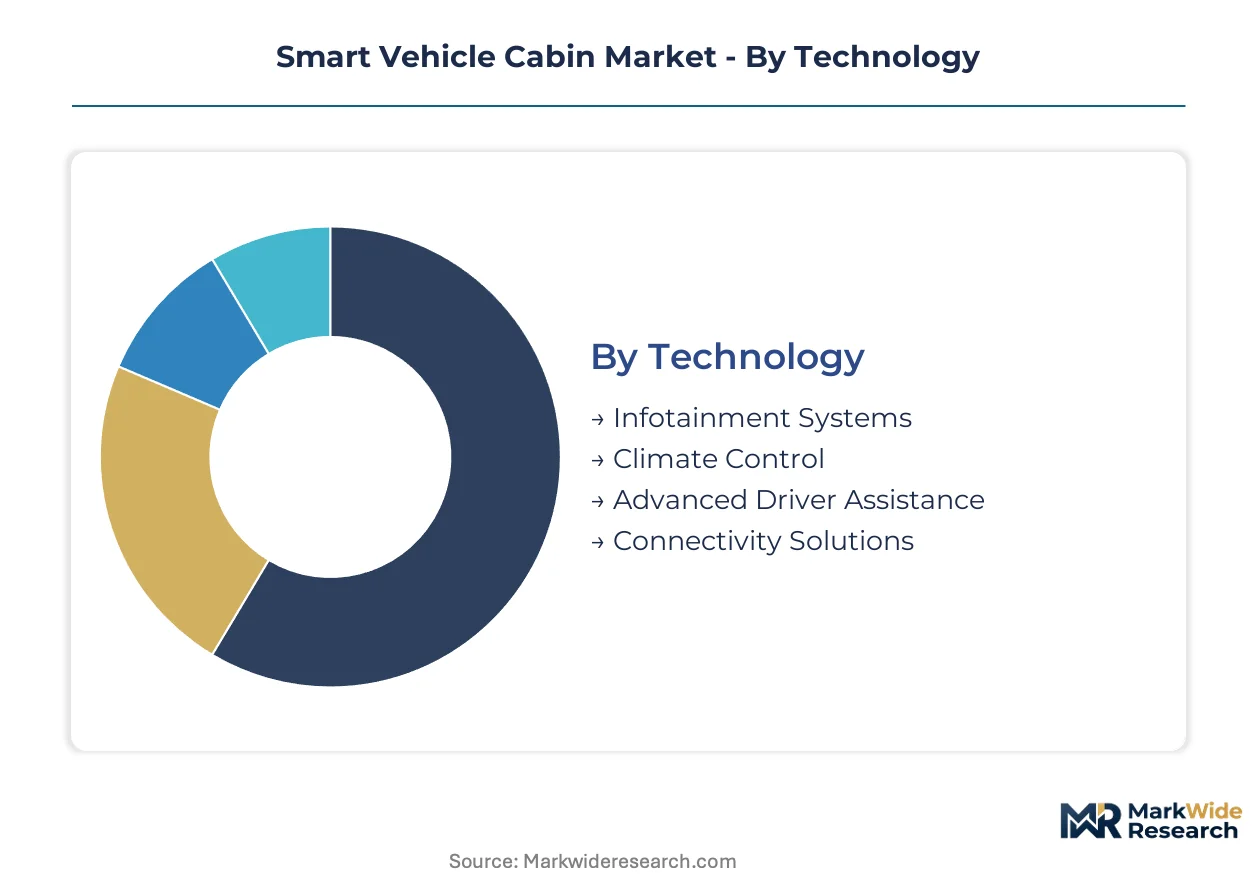
Smart vehicle cabin procurement patterns diverge sharply across technology maturity curves and regulatory exposure zones. Buyers weight thermal performance against biometric compliance costs, while fleet operators prioritize software monetization pathways over hardware specifications.
Technology:
Buyers segment procurement budgets by software monetization potential versus hardware refresh cycles.
- Infotainment Systems:Centralized touchscreen architectures integrating navigation, media, and voice interfaces through Android Automotive or proprietary OS stacks. German luxury OEMs concentrate orders here for brand differentiation, though margin compression intensifies as Qualcomm and NVIDIA consolidate chip supply.
- Connectivity Solutions:Over-the-air update infrastructure, telematics modems, and V2X communication modules enabling subscription revenue streams. Fleet operators in North American logistics corridors are pulling cellular and satellite hybrid architectures fastest as uptime guarantees become contractually binding.
- Climate Control:Multi-zone HVAC electronics with predictive thermal algorithms tied to battery state-of-charge. EV platforms mandate this integration for range preservation.
- Advanced Driver Assistance:In-cabin monitoring cameras and driver attention algorithms subject to EU AI Act biometric validation requirements.
Volume sits with Infotainment Systems; growth tilts toward Connectivity Solutions.
Component:
Supply security now dominates sourcing decisions as foundry allocation constraints persist.
- Sensors:Cabin occupancy detectors, air quality monitors, and biometric imagers converting physical states into CAN bus signals. Tier-one suppliers are qualifying second-source CMOS fabs outside Taiwan to mitigate concentration risk for 2026 programs.
- Microcontrollers:ISO 26262-certified processors executing deterministic control loops for safety-critical functions. Automotive-grade ARM cores from NXP and Renesas face allocation competition from industrial automation sectors.
- Displays:OLED and mini-LED panels for instrument clusters and rear-seat entertainment. Curved glass bonding capacity constrains premium vehicle ramp rates.
- Actuators:Precision motors for seat adjustment, HVAC vent positioning, and haptic feedback mechanisms. Bosch's foundry partnerships provide partial insulation against wafer shortages.
Procurement volume clusters in Sensors; Microcontrollers are expanding most quickly as functional safety mandates proliferate.
End User:
Contract structures separate one-time hardware sales from recurring software service agreements.
- OEMs:Vehicle manufacturers specifying integrated cabin architectures across model lines. German engineering clusters anchor premium development, while volume OEMs in Japan optimize for platform reuse.
- Fleet Operators:Commercial vehicle buyers unbundling cabin electronics service from powertrain maintenance. North American logistics operators negotiate direct supplier relationships for over-the-air update management.
- Aftermarket Providers:Retrofit specialists targeting 2018-2022 vehicle generations with compatibility constraints. ICE platform electrical architecture limitations suppress addressable volume.
- Ride-Hailing Services:Mobility platforms demanding standardized cabin configurations across mixed-vehicle fleets. San Francisco and Singapore operators prioritize occupancy detection for driver-rider safety protocols.
Revenue concentration favors OEMs; Fleet Operators are gaining share fastest as service unbundling accelerates.
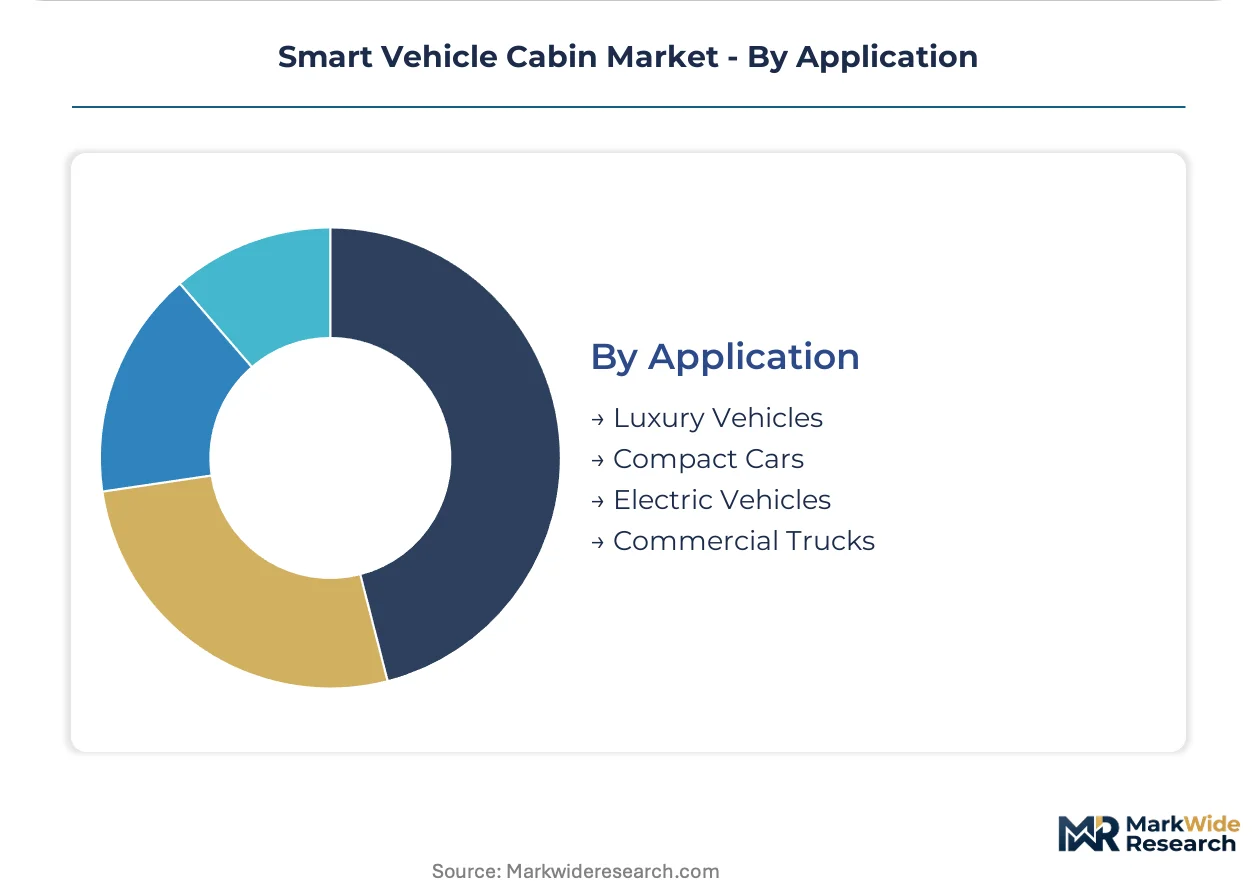
Application:
Thermal management requirements are reordering segment priority as electrification advances.
- Electric Vehicles:Battery-electric platforms where cabin HVAC load directly impacts range. Advanced heat pump architectures and predictive preconditioning algorithms are mandatory specifications for European and Chinese OEMs.
- Luxury Vehicles:Premium segments justifying multi-sensor fusion and deterministic Ethernet networking. German marques mandate time-sensitive networking for synchronized occupant safety systems.
- Commercial Trucks:Long-haul cabins requiring sleeper berth climate management and driver fatigue monitoring. US fleet operators are specifying integrated rest-cycle optimization under FMCSA hours-of-service pressure.
- Compact Cars:Cost-constrained segments where feature content battles semiconductor bill-of-materials limits. Shared microcontroller architectures across body electronics stretch cabin functionality at minimal incremental cost.
Unit volume concentrates in Compact Cars; Electric Vehicles command the steepest expansion trajectory as thermal efficiency targets tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer foundry capacity in Taiwan and South Korea underpins supply security for cabin electronics manufacturers across major automotive engineering clusters worldwide.
Germany
Luxury OEM procurement concentrates in Stuttgart and Munich engineering corridors, with tier-one suppliers qualifying second-source sensor fabs outside Taiwan. The EU AI Act biometric governance framework forces algorithmic transparency retrofits for 2026 model year driver monitoring systems. Bavarian clusters anchor premium cabin development for Mercedes-Benz and BMW electrification programs.
United States
Fleet operators in Michigan and Ohio logistics corridors unbundle cabin electronics service from powertrain maintenance contracts. NHTSA occupant safety standards tighten certification requirements for driver attention cameras and emotion detection hardware. Detroit-area engineering centers coordinate with Austin semiconductor design hubs on deterministic Ethernet networking for commercial truck sleeper berth systems.
China
Domestic EV platforms from BYD and NIO mandate advanced heat pump architectures for cabin thermal management. MIIT cybersecurity standards for connected vehicles reshape data handling protocols for occupant analytics. Yangtze River Delta manufacturing bases in Shanghai and Suzhou concentrate display panel bonding capacity for curved OLED instrument clusters.
Japan
Denso Corporation sustains climate control dominance across Toyota and Honda OEM programs. METI carbon neutrality roadmaps accelerate bio-based polymer qualification for REACH-compliant cabin materials. Nagoya-area engineering clusters specialize in multi-zone HVAC electronics integration with battery state-of-charge prediction algorithms.
South Korea
HYUNDAI MOBIS anchors domestic supply chains for integrated cabin architectures across Kia and Genesis electrification platforms. MFDS-equivalent automotive cybersecurity guidelines influence firmware validation spend for CAN bus hardening. Seoul Capital Area foundry partnerships secure microcontroller allocation priority during automotive demand surges.
Smart Vehicle Cabin Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-one suppliers balance captive semiconductor production against external foundry sourcing. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with in-house sensor capabilities, specialized climate control integrators, and autonomous computing platform architects. M&A activity concentrates on deterministic networking startups and edge inference chip designers. Strategic partnerships between German automotive suppliers and Taiwanese wafer allocators reshape supply security calculations.
Within the diversified industrial tier, Robert Bosch GmbH and Denso Corporation exemplify contrasting geographic anchoring strategies. Bosch leverages semiconductor foundry partnerships to secure actuator supply chains against Taiwan capacity constraints. Denso occupies a specialist position in climate control integration, sustaining program dominance across Japanese OEM electrification roadmaps. NVIDIA Corporation represents the autonomous computing archetype, anchoring cabin intelligence architectures through its Drive platform without direct manufacturing exposure to automotive tier-one procurement cycles.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Panasonic Corporation |
| NVIDIA Corporation |
| HYUNDAI MOBIS |
| Valeo |
| Continental AG |
| Harman International |
| Yanfeng Automotive Interiors |
| Others |
Value Network & Pricing Analysis
German luxury OEM procurement concentration anchors contract-based long-term offtake agreements for cabin electronics, with subscription-enabled feature activation now unbundling hardware from software monetization streams. Fleet operators in North American logistics corridors are accelerating this unbundling, negotiating direct service relationships that separate over-the-air update management from traditional vehicle purchase economics.
Pricing Analysis
Warranty and after-sales service bundling separates premium cabin electronics from standard-tier offerings, with German marques including predictive maintenance algorithms in multi-year contracts while volume OEMs strip service commitments to hit price points. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and deterministic Ethernet capability. Cost compression in microcontroller sourcing is intensifying because automotive-grade ARM cores face allocation competition from industrial automation sectors. Fleet operators exhibit highest price sensitivity as uptime guarantee negotiations drive hardware commoditization, while luxury OEMs remain least sensitive to unit costs when software recurring revenue potential exceeds hardware margins.
Supply Chain Analysis
Specialized firmware engineering talent shortages in German and US defense-adjacent labor pools constrain CAN bus hardening capacity for tier-one suppliers competing with aerospace for cleared personnel. Semiconductor foundry concentration in Taiwan and South Korea, plus precision motor manufacturing in Japan, anchors component supply. Raw material dependencies span silicon wafers, rare earth magnets for seat actuators, and bio-based polymers for REACH-compliant interior substrates. Single-source vulnerability around Taiwan wafer allocation during automotive demand surges represents the dominant structural risk. Distribution runs through OEM-mediated tier-one supplier networks, though fleet operators are increasingly negotiating direct relationships for over-the-air service management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart vehicle cabin market sits in a protocol-transition phase, with deterministic Ethernet architectures displacing legacy CAN bus standards for latency-sensitive occupant safety systems. This infrastructure replacement creates asymmetric opportunity across incumbent defenders and specialized entrants.
For Market Incumbents: Lock in foundry allocation priority through multi-year wafer agreements with Taiwanese partners before 2026 model year ramps absorb remaining automotive-grade capacity. Secure emotion detection algorithm validation pathways under EU AI Act biometric governance frameworks to compress certification timelines against emerging competitors lacking German regulatory relationships. Capacity addition in South Korean microcontroller packaging provides partial insulation against Taiwan concentration risk.
For New Entrants and Emerging Players: Aftermarket retrofit specialists targeting 2018-2022 ICE vehicle generations face electrical architecture incompatibility barriers that suppress addressable volume, creating white-space opportunity for software-defined feature overlays compatible with legacy bus standards. Commercial truck sleeper berth climate management offers the most penetrable application segment, with FMCSA hours-of-service pressure driving fleet procurement of integrated rest-cycle optimization. Go-to-market through direct fleet operator relationships bypasses OEM-mediated channel control.
For Investors and Strategic Acquirers: The window for entry favors deterministic networking startups with time-sensitive networking IP applicable to 2026 luxury platform launches. Long-term viability over the next decade rests on edge inference chip designers capable of occupant safety processing without cloud dependency. Watch for NHTSA-EU regulatory convergence on driver monitoring camera specifications as the inflection signal that would collapse variant engineering costs and accelerate platform scale economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Foundry Partnership | Secures wafer allocation priority from TSMC and Samsung for automotive-grade microcontroller supply. |
| EU AI Act Compliance Investment | Accelerates biometric algorithm validation timelines for 2026 Mercedes-Benz and BMW platform deployments. |
| Deterministic Ethernet Integration | Enables sub-50 millisecond occupant safety response for synchronized multi-sensor fusion architectures. |
| Direct Fleet Service Relationship | Displaces OEM-mediated aftermarket models for North American logistics operator uptime guarantees. |
| Bio-Based Polymer Qualification | Meets REACH substance restrictions ahead of 2025 German compliance deadlines for interior components. |
Research Methodology
Independent corroboration across Tier 1 supplier procurement directors, OEM platform engineers, and fleet operator maintenance executives underwrites the qualitative findings, validated against semiconductor foundry allocation disclosures, NHTSA regulatory filings, and EU AI Act implementation guidance. Bottom-up triangulation combines primary interviews with secondary analysis of customs data for cabin electronics trade flows, SEC filings from automotive semiconductor vendors, and IHS Markit vehicle production databases. Top-down modeling cross-checks segment-level assumptions against aggregate market sizing from registration data and OEM electrification program announcements.
Comparable-period anchoring to historical EV platform ramp rates and luxury vehicle content-per-vehicle trends shapes the forecast framework across the analysis window. Segmentation dimensions span propulsion architecture, vehicle class, content tier, and regional production cluster. CAGRs derive from modeled unit shipments against average selling price trajectories, incorporating battery thermal management integration intensity and software monetization attach rates as automotive-specific inputs.
Revisions become necessary when foundry allocation disruptions, regulatory timeline accelerations, or cybersecurity standard harmonizations materialize outside baseline assumptions. Forecasts reflect documented judgments about biometric governance enforcement intensity and EV adoption curve steepness. A small set of triggers—Taiwan capacity allocation shocks, NHTSA rulemaking pace, and fleet operator unbundling velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Nordic Bike Sharing Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Global Integrated Traffic System Market