
 Smart Door Lock Market | 2026-2036
Smart Door Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Door Lock Market Intelligence
The EU Cyber Resilience Act is expanding baseline cybersecurity requirements for connected home devices across member states, compelling manufacturers to redesign firmware architectures and certification pipelines. ASSA ABLOY anchors European commercial demand through its specification-grade portfolio and direct relationships with facility management conglomerates. Samsung Group leverages semiconductor captive supply to integrate proprietary biometric sensors at cost structures competitors struggle to match. Xiaomi Corporation dominates mass-market e-commerce channels in Asia through aggressive ecosystem bundling with existing smart home gateways.
A smart door lock is an electromechanical locking device incorporating wireless communication modules, biometric sensors, or cryptographic keypads to authenticate users and grant or deny physical access without traditional mechanical keys; units typically operate on battery voltages between four and eight volts and communicate via encrypted protocols over distances up to thirty meters. Deadbolt configurations sustain premium positioning in North American single-family retrofits where consumers prioritize visible security hardware and straightforward installation. Wi-Fi-enabled locks represent the fastest-growing technology segment as cloud-native property management platforms require always-online status monitoring and remote override capabilities for vacation rental portfolios.
The FCC in the United States certifies radio frequency emissions for all wireless smart locks, while the EU AI Act imposes transparency obligations on facial recognition variants marketed in Europe; China's SAMR enforces national cryptographic standards for biometric data storage on domestic devices. Stakeholders must monitor divergence between regional encryption mandates and biometric data governance frameworks when configuring product roadmaps for multi-territory launches.
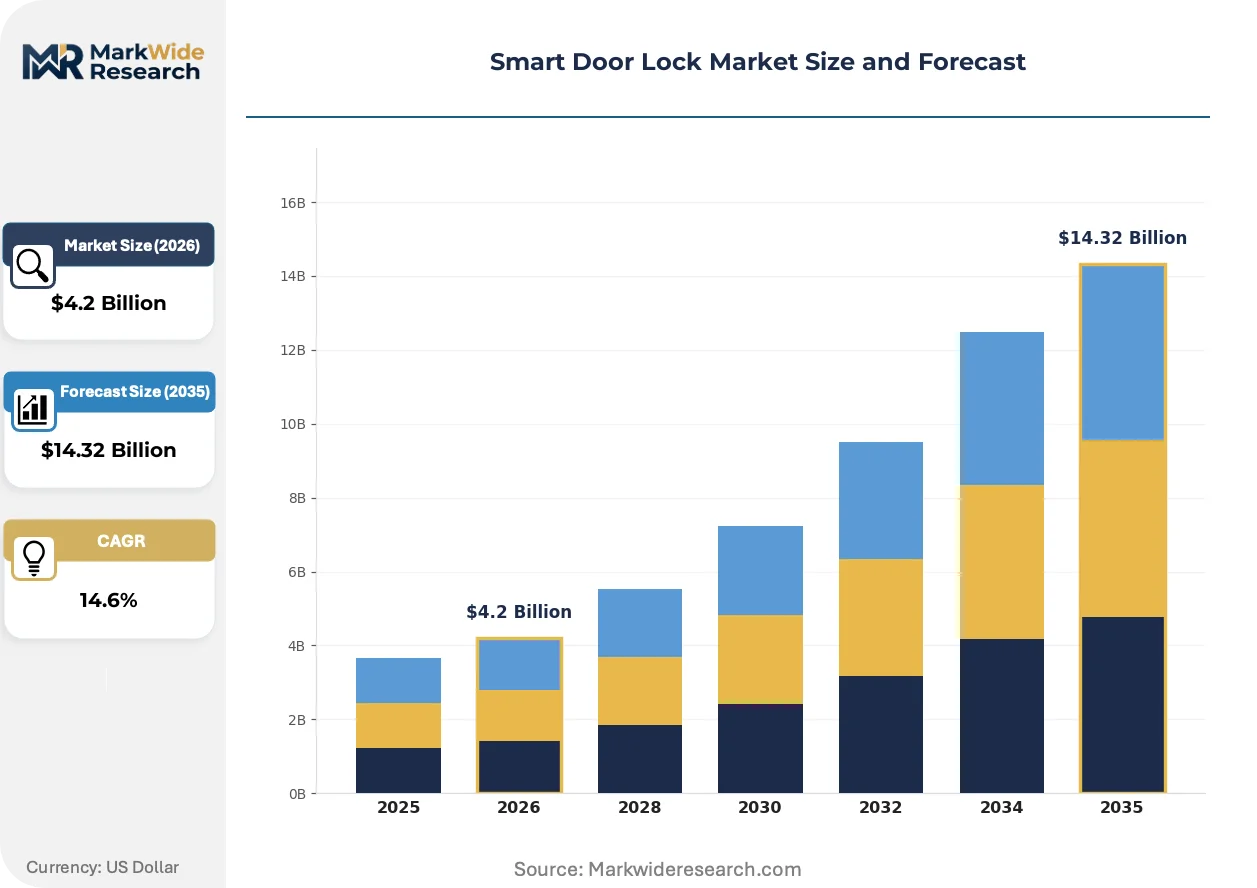
Market Dynamics
The smart door lock market is compressing around cloud-native property management platforms that mandate always-online connectivity and remote override capabilities, forcing hardware manufacturers to redesign firmware architectures around continuous telemetry rather than intermittent local authentication.
Growth Catalysts
- EU Cyber Resilience Act:Mandates baseline encryption for connected entry devices across member states, compelling manufacturers to upgrade certification pipelines and creating replacement demand for non-compliant legacy installations.
- Multi-family residential developers:Now specify biometric-capable locks as standard amenity packages in new construction, embedding smart access into base building specifications rather than optional upgrades.
- China's smart city infrastructure:Concentrates procurement through municipal rollouts in Shenzhen, Hangzhou, and Chengdu, aggregating fragmented demand into volume tenders that accelerate manufacturing scale.
Market Restraints
- Lithium battery supply concentration:Cell production clusters in East Asia create input vulnerability for battery-operated locks, with voltage specifications between four and eight volts limiting alternative chemistry substitution.
- Wi-Fi radio module shortages:FCC certification timelines for wireless emissions extend lead times for North American product launches, constraining responsiveness to seasonal demand spikes.
- Mechanical key override requirements:Fire safety codes in multiple jurisdictions mandate physical bypass capability, adding component cost and design complexity to fully electronic units.
Strategic Opportunities
- Vacation rental property management platforms:Require API-integrated locks with automated guest credential provisioning, opening a channel distinct from traditional locksmith distribution.
- EU AI Act transparency obligations:Create compliance service revenue streams for facial recognition variants, as biometric data governance frameworks impose documentation burdens that vendors can productize.
- India's residential construction pipeline:Remains underpenetrated by smart access relative to smartphone penetration rates, suggesting latent demand as gateway ecosystem bundling reaches mass-market price points.
Industry Challenges
- Firmware security engineering talent:Scarcity in embedded cryptography and secure boot architecture slows product development cycles for manufacturers outside semiconductor captive supply structures.
- Multi-territory certification complexity:Divergence between FCC radio emissions standards, EU AI Act biometric transparency requirements, and China's SAMR cryptographic storage mandates fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Door Lock Market |
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $14.32 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolt, Lever Handle, Mortise, Keypad, Lever Lock Technology: Bluetooth, Wi-Fi, Z-Wave, NFC, Zigbee Application: Residential Homes, Vacation Rentals, Corporate Offices, Government Buildings End User: Property Managers, Facility Supervisors, Real Estate Developers, Security Consultants |
| Companies Covered | DESSMANN, YALE, ASSA ABLOY, Aqara, Xiaomi Corporation, Samsung Group, Panasonic Corporation, Kaadas, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Door Lock Market Strategic Shifts & Innovations
Cloud-native access control platforms are unifying previously separate hardware, software, and service layers into single-vendor stacks, compressing the value chain and displacing traditional integration intermediaries. This convergence is reshaping procurement criteria and technical specification processes across commercial and residential segments.
Matter protocol implementation is unifying fragmented smart home communication standards, enabling cross-platform interoperability between locks, gateways, and voice assistants. Deadbolt manufacturers adopting Matter certification gain placement in multi-brand retail environments previously closed to proprietary ecosystems. This unification is compressing consumer switching costs and accelerating replacement cycles for first-generation Wi-Fi locks with isolated protocols.
The EU AI Act imposes transparency obligations on facial recognition variants marketed in Europe, requiring documented algorithmic decision pathways and human oversight interfaces. Commercial landlords deploying biometric entry systems must now maintain audit trails and consent management infrastructure. Facility management conglomerates are responding by centralizing vendor selection around suppliers with pre-certified compliance documentation, privileging established European specification-grade portfolios.
Property managers are consolidating vendor relationships around vertically integrated platform providers that bundle hardware, installation, and ongoing credential management. Independent locksmiths and security integrators are losing specification influence as procurement authority shifts to centralized technology procurement functions within real estate investment trusts. This concentration is most visible in North American multi-family housing, where institutional owners standardize across portfolios exceeding ten thousand units.
Smart Door Lock Market Segmentation
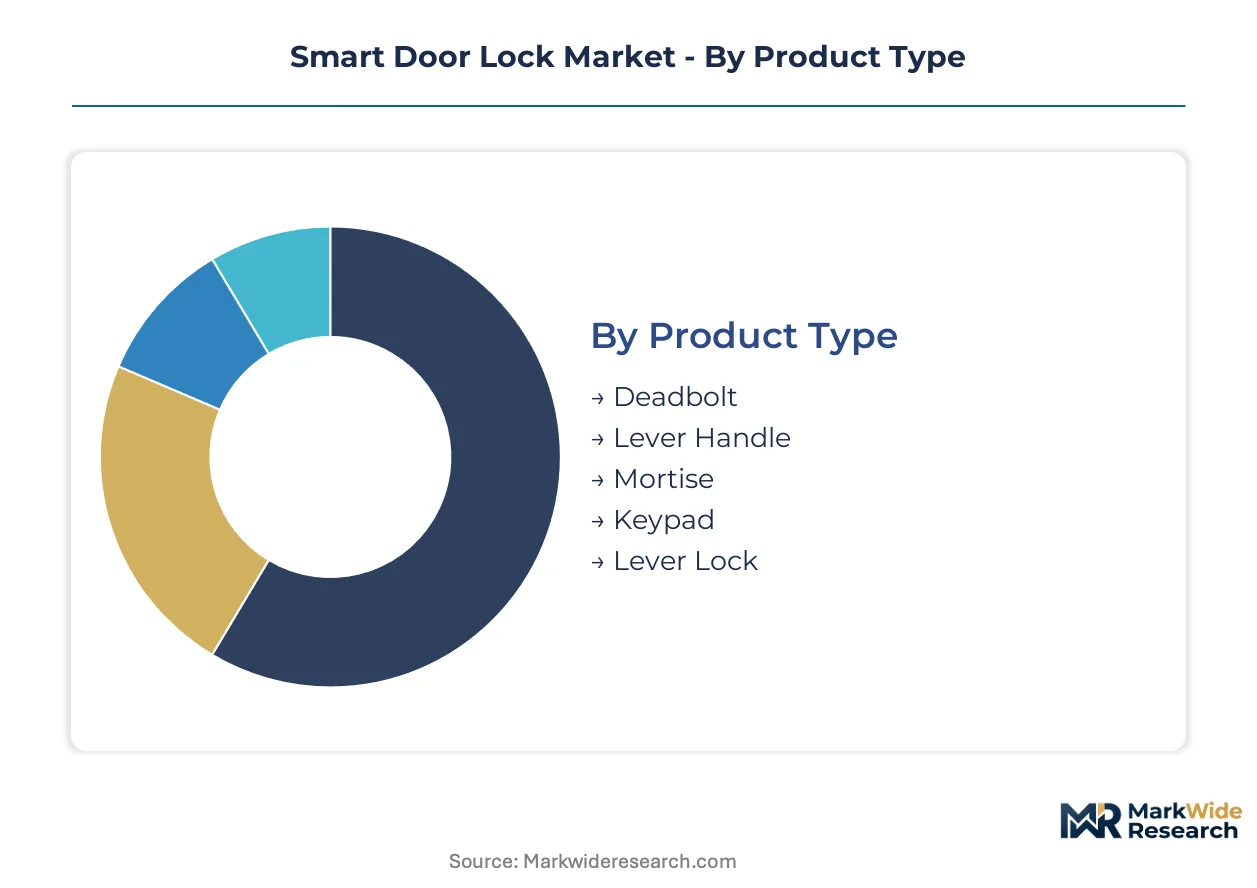
Smart door lock segmentation reveals how hardware specifications, communication protocols, and procurement authority patterns fragment addressable demand across distinct commercial channels. Understanding these axes helps vendors align firmware architectures, certification investments, and distribution partnerships with buyer decision-making structures.
Product Type:
Mechanical configuration determines installation complexity, visible security signaling, and retrofit compatibility against existing door preparations.
- Deadbolt:Single-cylinder or double-cylinder mechanisms extend a solid metal bolt into the door frame. North American single-family retrofits concentrate demand here, driven by consumer preference for visible security hardware and straightforward battery replacement access.
- Lever Handle:Integrated latch and handle mechanisms suit commercial environments requiring ADA-compliant accessibility standards. Corporate office retrofits specify these for high-traffic corridors where hands-free operation reduces contact transmission.
- Mortise:Recessed lock bodies requiring precise door preparation deliver superior forced-entry resistance. Government building specifications favor these for perimeter access points despite higher installation labor costs.
- Keypad:Numeric entry interfaces eliminate smartphone dependency for credential management. Vacation rental operators deploy these for guest turnover scenarios where temporary code provisioning outperforms app-based distribution.
- Lever Lock:Cylindrical locksets with integrated electronic modules fit standard door bores without modification. Mass-market residential channels in Asia-Pacific prefer these for minimal installation skill requirements.
Mature deployment sits with Deadbolt configurations in North American retrofits. Newer deployment is concentrated in Lever Handle formats across commercial accessibility upgrades.
Technology:
Wireless protocol selection governs power consumption, range, cloud connectivity requirements, and interoperability with existing smart home infrastructure.
- Bluetooth:Low-energy protocols enable smartphone proximity unlocking without continuous internet connectivity. Battery-operated residential units in Europe leverage this for GDPR-minimal data transmission profiles.
- Wi-Fi:Always-online modules support remote override and real-time status telemetry. Cloud-native property management platforms mandate this for vacation rental portfolios requiring automated guest credential provisioning.
- Z-Wave:Mesh networking protocols optimize for whole-home automation integration. Professional security integrators in the United States specify these for multi-device scenarios demanding protocol consistency.
- NFC:Near-field communication enables tap-to-unlock with wearables and keycards. Corporate campus deployments in Japan utilize these for employee badge integration with existing access control systems.
- Zigbee:Low-power mesh standards support battery longevity in multi-device ecosystems. Xiaomi ecosystem bundling in China concentrates volume through gateway-integrated starter kits.
Bluetooth dominates residential retrofit penetration. Wi-Fi is expanding most quickly through property management platform mandates.
Application:
End-use environment shapes durability requirements, credential management complexity, and regulatory compliance obligations.
- Residential Homes:Single-family and multi-family dwellings prioritize user-friendly installation and aesthetic integration with entry hardware. China's smart city rollouts in Shenzhen and Hangzhou embed these into municipal housing specifications.
- Vacation Rentals:Short-term hospitality properties demand automated check-in workflows and remote access revocation. API-integrated locks are displacing traditional locksmith channels in this application.
- Corporate Offices:Commercial workplaces require audit trails and integration with identity management systems. EU AI Act transparency obligations for biometric variants reshape vendor selection criteria here.
- Government Buildings:Public sector facilities impose stringent cybersecurity and physical security certifications. SAMR cryptographic storage mandates in China and FCC emissions requirements in the United States fragment product roadmaps for this segment.
Residential Homes anchor current volume concentration. Vacation Rentals are gaining share fastest through platform-driven standardization.
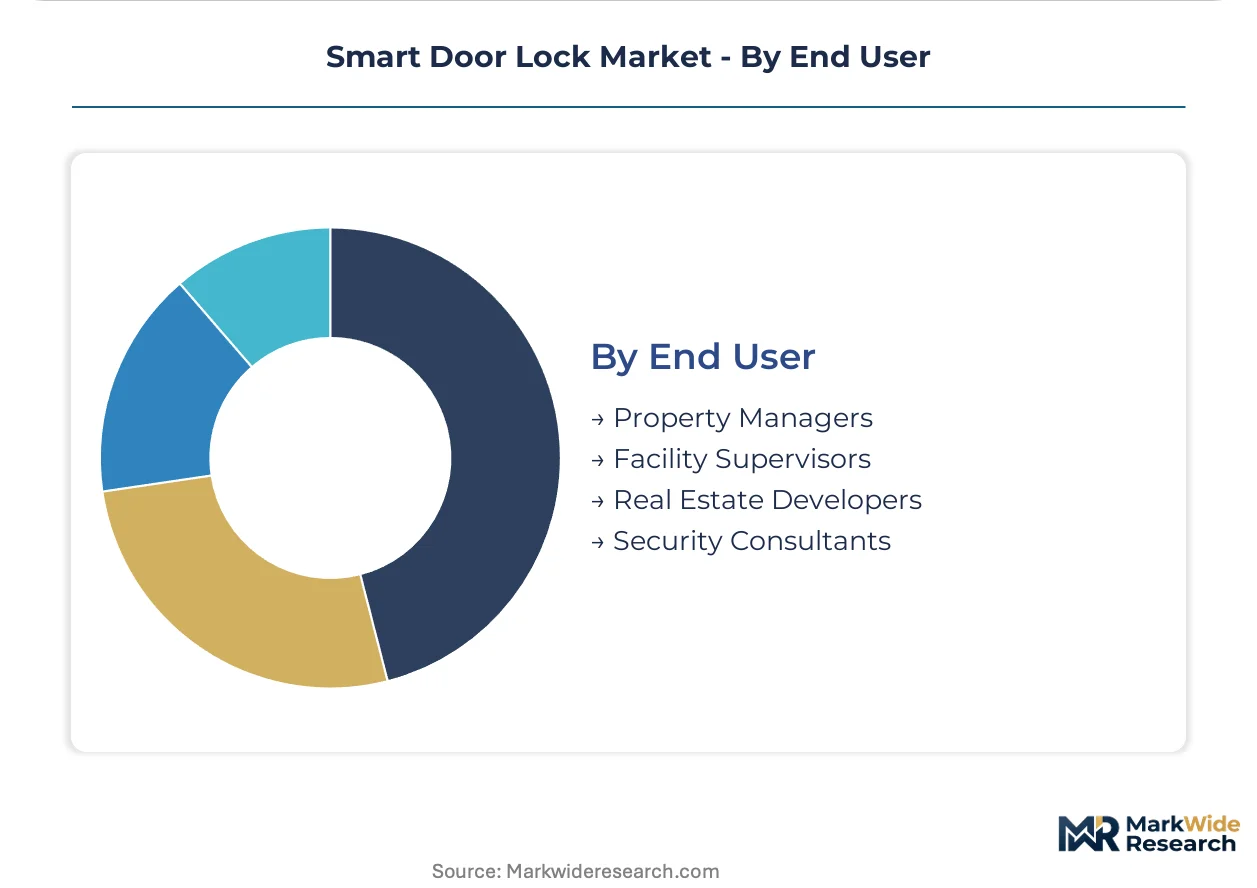
End User:
Procurement authority determines specification influence, price sensitivity, and ongoing service relationship structures.
- Property Managers:Portfolio-level operators standardize across multi-unit residential assets. Institutional owners exceeding ten thousand units centralize technology procurement functions, displacing independent locksmith influence.
- Facility Supervisors:On-site operations staff prioritize reliability and vendor responsiveness for maintenance issues. ASSA ABLOY's direct relationships with facility management conglomerates capture this decision-maker category.
- Real Estate Developers:New construction specifications embed smart access into base building amenities. Multi-family residential developers now mandate biometric-capable locks as standard packages rather than optional upgrades.
- Security Consultants:Independent advisory roles influence high-security and government applications. Compliance documentation burdens under EU AI Act biometric transparency requirements privilege established specification-grade portfolios.
Facility Supervisors represent entrenched procurement relationships. Property Managers are consolidating fastest around vertically integrated platform providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor concentrates smart lock module production, with component suppliers clustering within fifty kilometers of final assembly facilities serving both domestic and export markets.
United States
Vacation rental property management platforms drive Wi-Fi lock adoption across Florida, Arizona, and coastal California markets. FCC certification timelines for radio emissions extend product launch cycles, constraining responsiveness to seasonal demand spikes. The Southeast construction corridor from Atlanta to Dallas anchors multi-family residential specifications.
China
Municipal smart city rollouts in Hangzhou and Chengdu aggregate fragmented demand into volume tenders. SAMR enforces national cryptographic standards for biometric data storage on domestic devices. Yangtze River Delta manufacturers supply gateway-integrated starter kits through Xiaomi ecosystem bundling.
Germany
Facility management conglomerates standardize procurement around specification-grade portfolios for corporate office retrofits. EU Cyber Resilience Act mandates baseline encryption for connected entry devices across member states. Baden-Württemberg industrial clusters produce lever handle mechanisms for ADA-compliant accessibility standards.
Japan
Corporate campus deployments utilize NFC-enabled locks for employee badge integration with existing access control systems. METI guidelines shape IoT security expectations for residential connected devices. Kansai region manufacturers supply mortise lock bodies for government building perimeter specifications.
India
Residential construction pipelines in Maharashtra and Karnataka remain underpenetrated by smart access relative to smartphone penetration rates. BIS certification requirements for electronic safety products create compliance barriers for imported units. Delhi-NCR developers trial biometric-capable locks as standard amenity packages in premium multi-family projects.
Smart Door Lock Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification grade and firmware architecture sophistication. The vendor base organizes into three tiers: specification-grade incumbents with direct facility management relationships, semiconductor-captive electronics conglomerates, and mass-market ecosystem bundlers. Strategic differentiation concentrates on M&A for vertical capability acquisition and API integration partnerships with property management platforms.
Within the specification-grade tier, ASSA ABLOY anchors European commercial demand through direct relationships with facility management conglomerates. Samsung Group exemplifies semiconductor-captive supply structures that integrate proprietary biometric sensors at cost structures competitors struggle to match. Xiaomi Corporation occupies the mass-market ecosystem position, dominating Asia-Pacific e-commerce channels through aggressive gateway bundling.
| Leading Market Players |
|---|
| DESSMANN |
| YALE |
| ASSA ABLOY |
| Aqara |
| Xiaomi Corporation |
| Samsung Group |
| Panasonic Corporation |
| Kaadas |
| Honeywell International |
| Others |
Cost & Logistics Intelligence
Lithium-ion cell costs cascade through three pricing tiers as cylindrical battery packs move from Yangtze River Delta assembly lines through certification-grade deadbolt configurations to mass-market lever lock bundles. Voltage specifications between four and eight volts limit chemistry substitution, tethering margin structures to East Asian cell pricing volatility.
Pricing Analysis
Value-based pricing anchors on remote access uptime guarantees for vacation rental property management platforms. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified Wi-Fi modules with API integration from Bluetooth-only residential units and unconnected keypad entry systems. Cost compression in the mass-market tier intensifies because Xiaomi ecosystem bundling subsidizes hardware through gateway attachment rates. Property managers demonstrate lowest price sensitivity due to portfolio-scale standardization mandates, while independent residential retrofits exhibit highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Dongguan electronics corridors limit firmware engineering capacity for secure boot architecture. Semiconductor fabrication draws from Taiwan and South Korea for biometric sensor ASICs, while lithium cell production rests on China and Japan. Single-source vulnerability concentrates in FCC-certified Wi-Fi radio modules, where certification timelines extend lead times. Distribution runs through facility management conglomerates in Europe, e-commerce platforms in Asia-Pacific, and locksmith wholesale channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware security engineering talent scarcity props pricing power for specification-grade incumbents, constraining volume expansion for commodity-tier competitors.
For Market Incumbents: Cement specification-grade positioning through EU Cyber Resilience Act pre-certification investments, insulating against emerging cloud-native platform providers. Deepen backward integration into biometric sensor supply through semiconductor captive structures, mirroring Samsung Group's cost architecture. Channel control through direct facility management conglomerate relationships defends margin position against API-integrated vacation rental platform entrants. For New Entrants and Emerging Players: EU AI Act transparency obligations in Europe open a window for compliance-documentation service bundling with facial recognition variants. India's underpenetrated residential construction pipeline offers the most penetrable geography, with Maharashtra and Karnataka developers trialing biometric-capable locks as standard amenity packages. Go-to-market through gateway ecosystem partnerships bypasses entrenched locksmith distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor specification-grade incumbents with pre-certified EU encryption compliance and direct facility management relationships in Germany. Long-term viability centers on vertical capability consolidation across hardware, firmware, and cloud platform layers. Watch API integration depth with property management platforms as the inflection indicator for valuation compression in pure-hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Enables cross-platform interoperability for retail placement previously closed to proprietary ecosystems. |
| Biometric Sensor Backward Integration | Reduces unit cost structures through captive semiconductor supply mirroring Samsung Group's model. |
| API Integration Partnership | Locks in vacation rental property management platform procurement through automated credential provisioning. |
| EU Cyber Resilience Act Pre-Certification | Creates replacement demand for non-compliant legacy installations across member states. |
| Smart City Municipal Tender Participation | Aggregates fragmented demand into volume contracts in Shenzhen, Hangzhou, and Chengdu. |
Research Approach
SEC filings, customs trade databases, and FCC equipment authorization records formed the secondary backbone, cross-referenced against primary interviews with smart lock product managers, facility management procurement directors, vacation rental platform technology officers, and biometric sensor semiconductor specialists. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across residential, commercial, and government verticals.
Bottom-up modeling segmented volume across deadbolt, lever handle, mortise, keypad, and lever lock configurations, further split by Bluetooth, Wi-Fi, Z-Wave, NFC, and Zigbee technology protocols. CAGRs derived from elasticity-adjusted replacement cycle assumptions and smart city infrastructure rollout schedules. Firmware security engineering talent availability and lithium cell supply concentration served as industry-specific constraint variables throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for Matter protocol migration would alter the outlook for proprietary ecosystem vendors. Forecasts reflect assumptions about EU AI Act implementation timelines and China SAMR enforcement intensity. Material deviation in municipal smart city procurement cadence or FCC certification backlog duration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
US Access Control Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Canada Access Control Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
South Korea Access Control Market
Access Control Systems
Pre-Departure Clearance System Market