
 Biometric Authentication Solution Market | 2026-2036
Biometric Authentication Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Authentication Solution Market Analytics
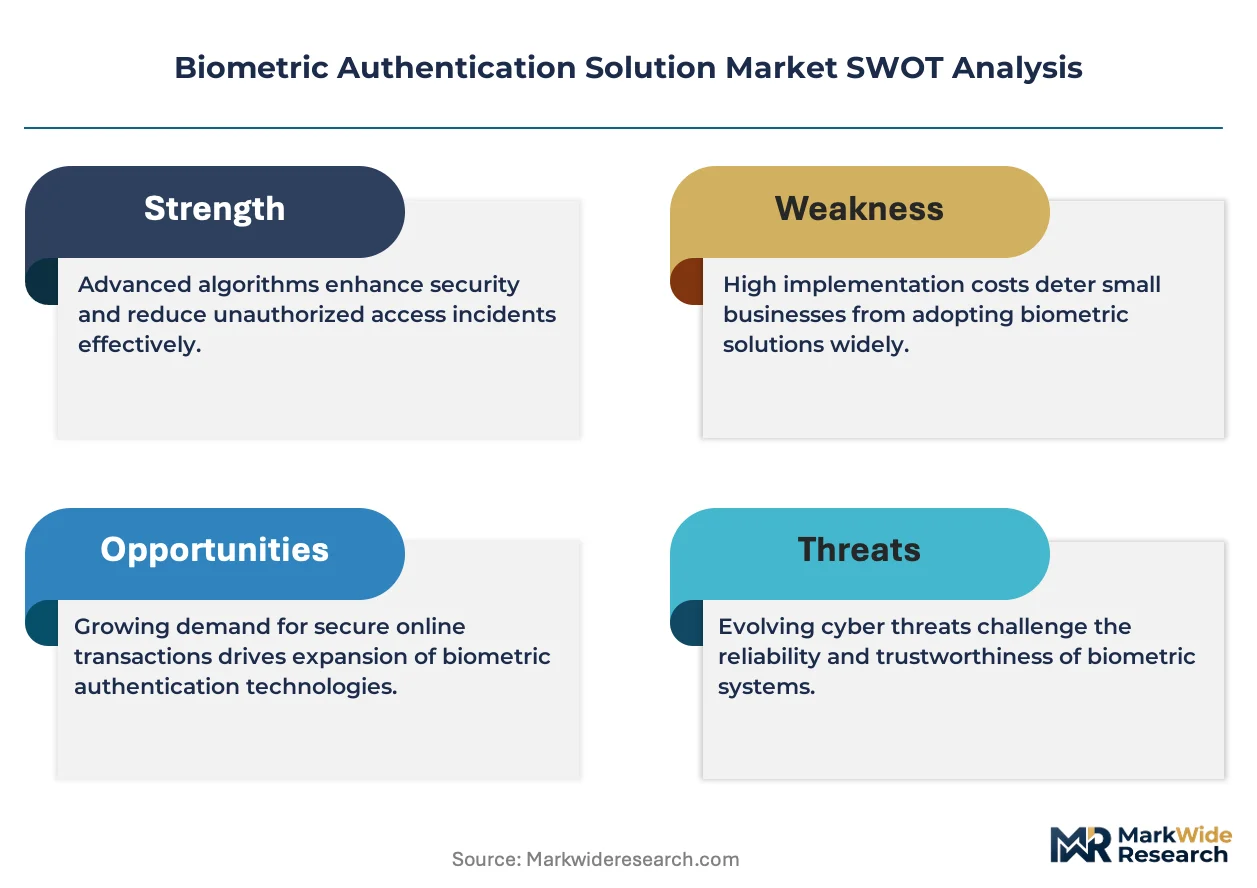
Enterprise distribution channels for biometric hardware and software is reconfiguring around cloud-native delivery and subscription licensing. NEC Corporation leverages its longstanding government relationships to sustain large-scale national ID projects across multiple continents. IDEMIA anchors its position through integrated civil identity and biometric document portfolios. Suprema competes aggressively in physical access control with specialized fingerprint and facial recognition terminals.
Biometric authentication solutions encompass hardware sensors, matching algorithms, and identity management platforms that capture and verify unique biological characteristics including minutiae patterns, iris textures, vocal signatures, and facial geometry against enrolled templates. These systems operate through capture devices with resolution thresholds, liveness detection protocols, and template extraction pipelines to deliver one-to-one or one-to-many identity verification for security-critical transactions. Fingerprint recognition occupies the most mature position with established manufacturing scale and commodity sensor costs, while facial recognition captures the fastest expansion as smartphone integration and contactless access protocols displace legacy card systems. Government applications concentrate the largest project values, though financial services delivers superior margins through recurring software licensing and compliance-driven upgrade cycles.
FDA guidance on biometric device cybersecurity, EU AI Act risk classification for remote identification systems, and GDPR Article 9 special category data protections collectively reshape product architecture and market access requirements across major jurisdictions. The EU AI Act specifically prohibits real-time remote biometric identification in publicly accessible spaces for law enforcement except under judicial authorization, forcing vendors to redesign deployment architectures for European government clients. Stakeholders must monitor evolving national biometric registries, cross-border data transfer restrictions, and algorithmic auditing mandates to align R&D roadmaps with compliance timelines.
Market Dynamics
Cloud-native delivery architectures are compressing deployment timelines for biometric authentication platforms while simultaneously fragmenting vendor revenue models away from perpetual licenses toward recurring subscription streams. This structural shift demands fundamental reconfiguration of R&D investment cycles and customer success operations across the competitive landscape.
Growth Catalysts
- EU AI Act risk classification:Mandatory algorithmic auditing for remote biometric identification systems is forcing financial institutions toward certified vendors, consolidating procurement around compliant platforms.
- Fingerprint sensor commoditization:Manufacturing scale in capacitive and ultrasonic modules has collapsed hardware acquisition costs, enabling mass deployment across mid-market enterprise access control.
- India's national identity modernization:The country's biometric document and civil registry expansion is generating sustained demand for integrated enrollment and verification infrastructure.
Market Restraints
- GDPR Article 9 special category data protections:Stringent consent and purpose limitation requirements impose architectural constraints on cross-border template storage and matching operations.
- Silicon supply concentration:Advanced image sensor fabrication for iris and facial recognition systems depends on a concentrated East Asian foundry base, creating input cost volatility exposure.
- Liveness detection technical limitations:Presentation attack resistance for 2D facial recognition remains vulnerable to sophisticated deepfake injection, limiting high-assurance deployment scope.
Strategic Opportunities
- Behavioral biometrics convergence:Integration of keystroke dynamics, gait analysis, and touchscreen interaction patterns with physiological modalities is opening continuous authentication applications in financial services.
- Saudi Arabia's smart city mandates:Giga-project developments are specifying contactless biometric access for residential, commercial, and transit environments at scale.
- ISO/IEC 30107-3 certification tailwind:Standardized liveness testing frameworks are enabling vendor differentiation and procurement simplification for government and enterprise buyers.
Industry Challenges
- Algorithmic bias audit expertise scarcity:Demonstrating demographic parity across facial recognition systems requires specialized statistical and ethical review capabilities that outstrip current workforce supply.
- Legacy physical access system integration friction:Card reader infrastructure and Wiegand protocol dependencies complicate biometric terminal retrofit projects in established commercial real estate.
- Cross-jurisdictional template interoperability:Divergent national standards for minutiae extraction and template formats obstruct multi-country identity federation initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Authentication Solution Market |
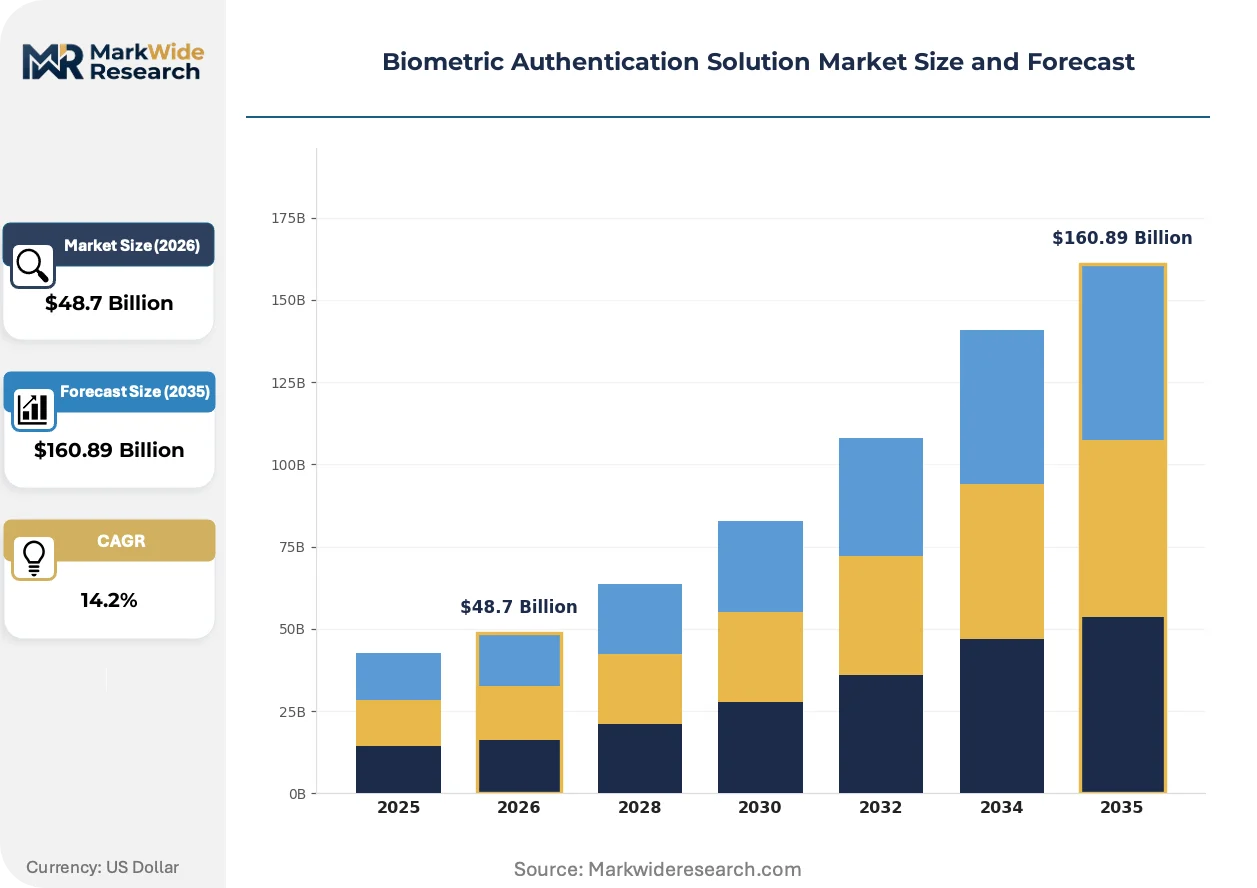
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Mobile Devices, Financial Services, Healthcare, Government End User: Consumers, Enterprises, Government Agencies, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Others |
| Companies Covered | HID Global, NEC Corporation, IDEMIA, Suprema, FUJITSU, Thales, Aware, Nuance Communications, M2SYS Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Authentication Solution Market Evolving Landscape
Edge computing architectures are redistributing biometric processing loads from centralized data centers toward capture devices themselves, altering latency profiles and data governance boundaries simultaneously. This migration is compressing infrastructure requirements while expanding deployment flexibility across distributed environments.
Multispectral imaging for fingerprint capture is migrating from high-security government enrollment stations toward mainstream physical access terminals. Financial services institutions in the United States are piloting these sensors for branch staff authentication. The technology is migrating from specialized forensics applications toward commoditized enterprise hardware, collapsing the traditional performance tier segmentation.
The EU AI Act prohibition on real-time remote biometric identification in publicly accessible spaces is forcing European government vendors toward offline or on-device processing architectures. Law enforcement agencies must now obtain judicial authorization for deployment, extending procurement cycles. National ID projects across Germany, France, and Italy are reconfiguring system designs to accommodate these constraints while maintaining operational utility.
Subscription-based software licensing is displacing perpetual ownership models across enterprise biometric deployments. Chief information security officers favor operational expenditure treatment and bundled update entitlements over capital-intensive refresh cycles. This preference shift is most pronounced in United States healthcare and financial services verticals, where HIPAA and SEC cybersecurity guidance mandate timely patch application.
Biometric Authentication Solution Market Segmentation
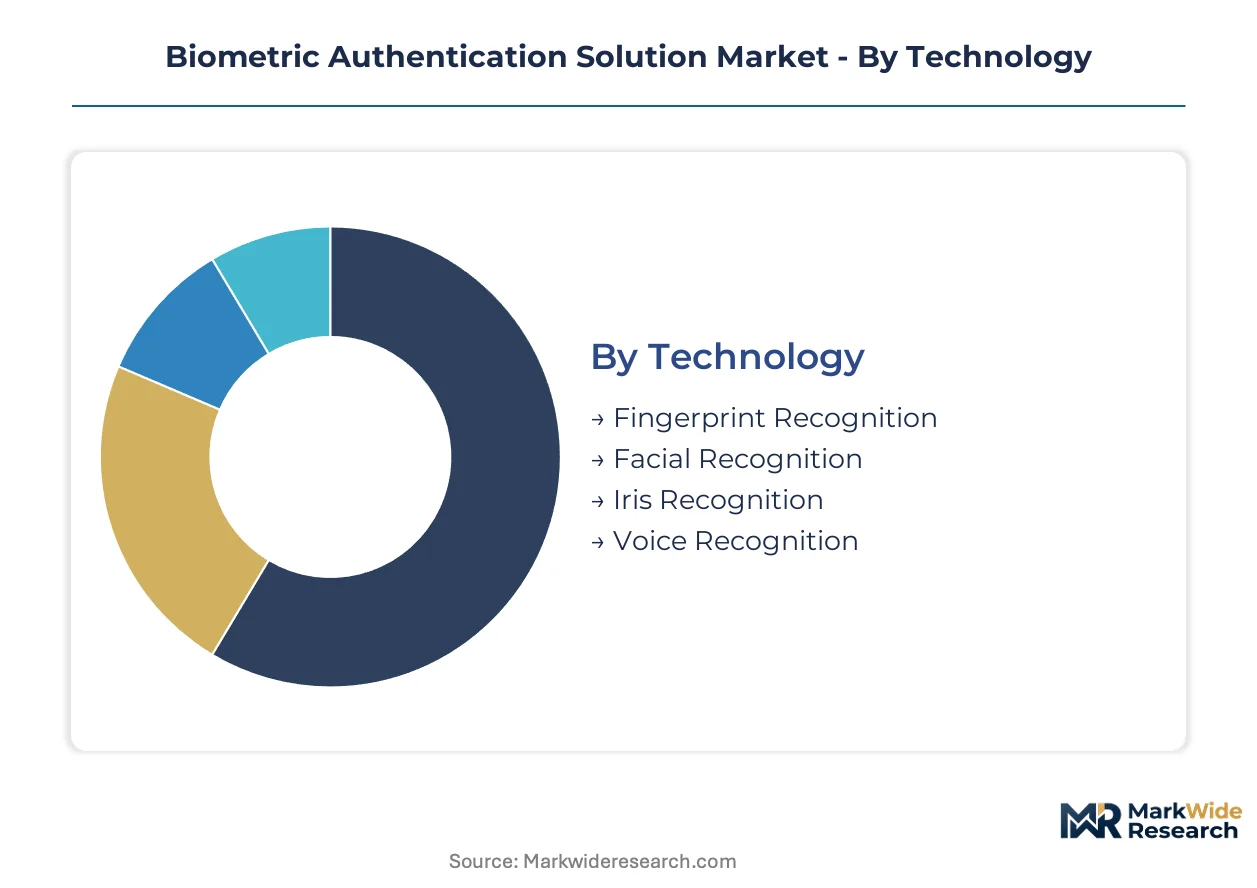
Biometric authentication solutions fragment across technology modalities, deployment architectures, and institutional buyer types. Each segmentation dimension carries distinct margin profiles, compliance burdens, and vendor competitive dynamics that shape procurement patterns.
Technology:
Use-case spectrum spans high-frequency consumer convenience to forensic-grade identity assurance, with modality selection driven by threat model, cost sensitivity, and environmental constraints.
- Fingerprint Recognition:Capacitive and ultrasonic sensors capture minutiae patterns with established manufacturing scale at commodity price points. Financial services branch authentication and mid-market enterprise access control in the United States concentrate procurement here, constrained by residual hygiene concerns post-pandemic.
- Facial Recognition:Neural network-based facial geometry matching enables contactless verification across smartphone unlock, airport e-gates, and retail payment. Smartphone OEM integration and Saudi Arabia smart city mandates are accelerating deployment fastest, though EU AI Act restrictions on real-time remote identification in public spaces limit European law enforcement applications.
- Iris Recognition:Near-infrared imaging of unique trabecular mesh patterns delivers false-match rates below one in a million. Border control and high-security data center applications in the United Arab Emirates and Singapore drive specialized demand.
- Voice Recognition:Vocal tract resonance and prosodic pattern analysis enables hands-free authentication for call center banking and smart speaker ecosystems. Telecommunications fraud prevention in India represents the primary growth vector.
The dominant share belongs to Fingerprint Recognition, while Facial Recognition is closing the gap fastest.
Application:
Cost tier segmentation separates mass-market consumer deployments from compliance-driven institutional systems with dedicated security operations centers.
- Mobile Devices:OEM-integrated fingerprint and facial unlock systems ship at billion-unit annual scale. Apple and Samsung design specifications cascade through component supply chains, with liveness detection now mandatory for payment-grade authentication under ISO/IEC 30107-3.
- Financial Services:Banks and payment networks deploy multi-factor biometric stacks for transaction authorization and branch staff authentication. Recurring software licensing and SEC cybersecurity guidance mandating timely patch application sustain superior margins here.
- Healthcare:HIPAA-covered entities implement biometric patient identification to reduce medical record duplication and insurance fraud. United States hospital systems pilot palm-vein and facial matching for emergency department check-in.
- Government:National ID registries, voter authentication, and law enforcement identification systems concentrate project value. India's Aadhaar-scale enrollment infrastructure and Germany's EU AI Act-compliant border control redesigns exemplify procurement complexity.
Mobile Devices capture volume leadership, though Financial Services commands margin premiums through subscription architectures.
End User:
Customer type determines procurement sophistication, with enterprises and government agencies demanding algorithmic audit trails that consumer markets ignore.
- Consumers:Smartphone and laptop OEM pre-installations normalize biometric convenience at negligible marginal cost. Privacy-preserving on-device template storage under iOS and Android security architectures addresses GDPR Article 9 concerns for European users.
- Enterprises:Chief information security officers evaluate biometric platforms against zero-trust architecture requirements. Physical access control retrofit projects in United States commercial real estate struggle with Wiegand protocol legacy infrastructure.
- Government Agencies:National security and civil registry applications mandate certified liveness detection and demographic parity documentation. EU AI Act risk classification for remote identification systems extends European procurement cycles.
- Educational Institutions:Campus access and examination proctoring deployments prioritize cost containment over assurance. United States university systems pilot facial recognition for dormitory entry with significant student privacy pushback.
Enterprises generate the steepest expansion trajectory as zero-trust mandates displace password-centric security models.
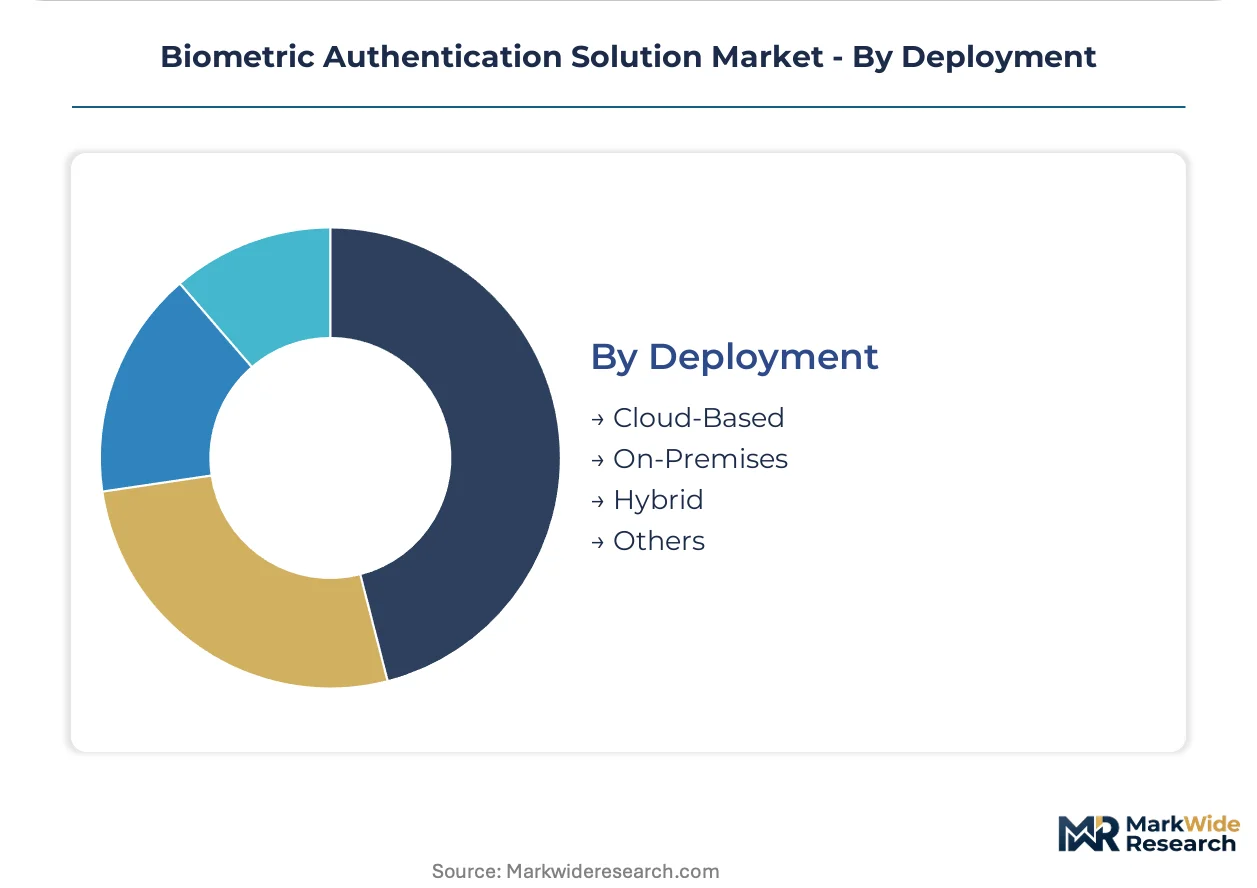
Deployment:
Supply concentration in cloud infrastructure reshapes vendor revenue recognition and customer data governance responsibilities.
- Cloud-Based:Multi-tenant SaaS platforms deliver biometric matching as API-accessible services with elastic scaling. United States healthcare and financial services verticals favor operational expenditure treatment and bundled update entitlements.
- On-Premises:Air-gapped installations satisfy data sovereignty requirements for defense and intelligence community clients. Template storage and matching execute within customer-controlled facilities, eliminating third-party access risks.
- Hybrid:Edge-device capture with cloud-based enrollment and template management balances latency and centralization. European government projects increasingly specify this architecture to satisfy EU AI Act constraints while maintaining operational utility.
- Others:Embedded firmware deployments in IoT and industrial control systems represent emerging demand with fragmented standards.
Cloud-Based deployments hold current preference share, though Hybrid architectures are gaining ground fastest under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States federal procurement while European vendors absorb compliance premiums under the EU AI Act. This asymmetry reshapes vendor investment allocation across development roadmaps.
United States
Federal identity modernization programs and enterprise security upgrades drive procurement concentration. The SEC cybersecurity guidance mandates timely patch application for financial services biometric deployments. Washington DC corridor vendors supply zero-trust authentication stacks to defense and intelligence community clients requiring air-gapped installations.
Germany
Border control infrastructure redesigns and national ID registry modernization sustain project demand. The EU AI Act risk classification for remote identification systems extends procurement cycles through mandatory judicial authorization. Berlin-Brandenburg government technology clusters reconfigure system architectures toward offline processing to satisfy regulatory constraints.
India
Aadhaar-scale enrollment infrastructure and biometric document expansion generate sustained demand for integrated verification systems. The RBI mandates multi-factor authentication for high-value transactions, accelerating bank procurement. Karnataka technology corridors host enrollment station manufacturing and algorithm development operations serving domestic and export markets.
Saudi Arabia
NEOM and giga-project smart city mandates specify contactless biometric access at residential, commercial, and transit scale. The SFDA and national data governance authority impose template storage localization requirements. Riyadh-based system integrators deploy facial recognition terminals across government and private developments.
Singapore
High-security data center and border control applications drive specialized iris recognition demand. The country's national data protection authority enforces strict cross-border template transfer protocols. One-North technology district hosts biometric algorithm R&D operations serving Asia-Pacific financial services clients.
Biometric Authentication Solution Market Competitive Landscape
Government-contracting specialists and enterprise platform vendors split the market along procurement sophistication lines. Consolidation pressure intensifies as cloud-native delivery mandates subscription revenue models incompatible with legacy perpetual licensing operations. Three archetypes dominate: diversified technology conglomerates with civil identity portfolios, specialized biometric hardware fabricators, and cloud-native software platforms. Competitive moves concentrate on strategic partnerships for algorithm certification and geographic expansion into Gulf Cooperation Council smart city projects.
Within the government-contracting tier, NEC Corporation and IDEMIA occupy positions anchored by longstanding national ID relationships across multiple continents. Suprema represents specialized hardware fabrication with concentrated physical access control terminal production. These three exemplify divergent strategic postures: conglomerate diversification, integrated civil identity systems, and focused sensor manufacturing respectively.
| Leading Market Players |
|---|
| HID Global |
| NEC Corporation |
| IDEMIA |
| Suprema |
| FUJITSU |
| Thales |
| Aware |
| Nuance Communications |
| M2SYS Technology |
| Others |
Value Network & Pricing Analysis
Taiwan's advanced foundry clusters in Hsinchu Science Park anchor global capacity for near-infrared image sensors and neural processing units, translating wafer allocation tightness into tiered pricing power for biometric hardware vendors serving government and financial services clients.
Pricing Analysis
The customization-premium spread separates ISO/IEC 30107-3 certified liveness detection systems from commodity fingerprint modules. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in mid-market enterprise access control is intensifying because capacitive sensor manufacturing scale has collapsed hardware acquisition costs. Financial services institutions exhibit the lowest price sensitivity due to SEC cybersecurity guidance mandating timely patch application, while educational institutions prioritize cost containment over assurance.
Supply Chain Analysis
Contract-manufacturing concentration rests with Foxconn and Pegatron for terminal assembly, plus TSMC and Samsung Foundry for advanced image sensor fabrication. Geographic supply concentration centers on Taiwan, South Korea, and China for semiconductor inputs. Raw material dependencies include silicon wafers, near-infrared optics, and specialized biometric algorithm IP. Single-source vulnerability in East Asian foundry capacity creates input cost volatility exposure. Distribution runs through direct enterprise sales teams for government contracts and value-added resellers for mid-market physical access deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biometric authentication market rewards vendors possessing algorithmic bias audit capabilities and certified liveness detection expertise, assets that currently outstrip available workforce supply and create sustainable differentiation moats.
For Market Incumbents: Insulate recurring revenue streams by deepening backward integration into edge-device firmware and securing EU AI Act certification ahead of compliance deadlines. Cloud-native delivery mandates threaten legacy perpetual licensing operations. Capacity addition in Riyadh and Singapore government technology corridors reinforces geographic diversification against European procurement cycle extension. For New Entrants and Emerging Players: Establish a beachhead in behavioral biometrics convergence for continuous authentication in United States financial services. The most penetrable segment combines keystroke dynamics with smartphone OEM integration. A channel partnership with existing physical access control distributors accelerates enterprise footprint without Wiegand protocol retrofit friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native software platforms with API-accessible biometric matching services over hardware-centric fabricators. Long-term viability hinges on subscription revenue model maturity and bundled update entitlements. The acquisition target archetype combines ISO/IEC 30107-3 certification with zero-trust architecture integration. Watch judicial authorization volume for EU AI Act remote identification deployments as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 30107-3 Certification Investment | Enables vendor differentiation and procurement simplification for government buyers under standardized liveness testing frameworks. |
| Cloud-Native Platform Migration | Aligns revenue recognition with SEC cybersecurity guidance mandating timely patch application in financial services. |
| Behavioral Biometrics R&D Partnership | Opens continuous authentication applications through keystroke dynamics and gait analysis integration with physiological modalities. |
| EU AI Act Compliance Architecture | Forces system redesign toward offline processing to satisfy prohibition on real-time remote biometric identification in public spaces. |
| GCC Smart City System Integration | Captures NEOM and giga-project mandates specifying contactless biometric access at residential, commercial, and transit scale. |
Research Methodology
Operator-level perspectives from chief information security officers, biometric algorithm engineers, government procurement officers, and physical access control integrators anchored the qualitative base. These interviews combined with secondary validation from SEC cybersecurity guidance filings, EU AI Act regulatory texts, ISO/IEC 30107-3 certification databases, and hyperscaler biometric API documentation. Bottom-up enrollment station shipment tallies and top-down identity modernization budget allocations provided triangulation across the analysis window.
Scenario-bracketing framed projections across conservative, baseline, and aggressive technology adoption paths. The analytical framework modeled segmentation dimensions including technology modality, deployment architecture, end-user type, and regional regulatory cluster throughout the forecast period. CAGRs derived from algorithmic improvement curves and compliance-driven upgrade cycle frequency. Industry-specific inputs included liveness detection certification penetration rates and zero-trust architecture mandate implementation timelines.
Sensitivities concentrate around EU AI Act enforcement intensity, East Asian foundry capacity allocation shifts, and deepfake presentation attack sophistication. Forecasts reflect assumptions regarding regulatory timeline adherence and semiconductor supply normalization. Quarterly review of judicial authorization volumes for European law enforcement biometric deployments and ISO/IEC 30107-3 certification issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Biometrics Software Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Global Human Identification Market