
 Global Smart Lock Market | 2026-2036
Global Smart Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Lock Market Outlook
Biometric authentication grade is redrawing competitive boundaries across the Global Smart Lock Market. ASSA ABLOY leverages its manufacturing scale to dominate high-security commercial installations across Europe and Asia. Allegion plc anchors its position through deep channel control in North American residential distribution networks. dormakaba Group specializes in hospitality-specific platforms that integrate with property management systems.
A smart lock is an electromechanical locking device that authenticates users through electronic credentials including PIN codes, biometric templates, or encrypted wireless signals transmitted via Bluetooth Low Energy, Wi-Fi, or Z-Wave protocols, with motorized deadbolt actuation typically rated for cycles exceeding one hundred thousand operations. The technology serves to eliminate physical key management while enabling remote access logging and real-time revocation for residential, commercial, and institutional facilities. Deadbolt configurations currently occupy the largest product category due to retrofit compatibility with standard door preparations. Wi-Fi connectivity is displacing Bluetooth-only architectures as primary residence buyers prioritize remote monitoring capabilities. The hospitality end-user segment represents the fastest-growing demand pool as hotel chains mandate mobile-key compatibility across property portfolios.
FCC certification governs wireless transmission parameters for devices sold in the United States, while the EU AI Act imposes risk-classification requirements on biometric-enabled locks processing personal data in European markets. China's SAMR enforces GB standard compliance for electromagnetic compatibility and cybersecurity labeling of networked home devices. Stakeholders must monitor divergence between regional encryption mandates and wireless protocol certifications when configuring product variants for multi-country deployment.
Market Dynamics
Networked electronic access platforms are systematically displacing mechanical master-key systems across hospitality and commercial real estate portfolios, with hardware encryption standards tightening under biometric data processing mandates in major jurisdictions.
Growth Catalysts
- Hospitality Mobile-Key Mandates:Hotel chains across Germany, the United States, and South Korea now require smartphone-compatible entry systems across property portfolios, eliminating front desk key distribution friction.
- EU AI Act Risk Classification:Biometric-enabled locks processing personal data face mandatory conformity assessments, accelerating demand for certified hardware encryption modules in European markets.
- Retrofit-Compatible Deadbolt Designs:Standard door preparation compatibility allows property managers to upgrade existing infrastructure without carpentry modifications, lowering installation barriers in aging building stock.
Market Restraints
- Semiconductor Supply Concentration:Wi-Fi and Bluetooth Low Energy chipsets depend on concentrated foundry capacity in East Asia, exposing lead time volatility for networked lock manufacturers.
- FCC Certification Timeline:United States market entry requires 8-16 week wireless transmission parameter validation, delaying product launches relative to unlicensed spectrum jurisdictions.
- Mechanical Key Persistence:Battery-dependent electronic systems face substitution risk in critical infrastructure applications requiring fail-physical override guarantees.
Strategic Opportunities
- India Smart Building Retrofits:BIS certification pathways for electromagnetic compatibility create first-mover positioning in commercial real estate modernization across Mumbai and Bangalore.
- Property Management System Convergence:Integration APIs connecting door access with housekeeping scheduling and energy management unlock operational efficiency gains for hospitality operators.
- Japan METI Cybersecurity Labeling:Voluntary IoT security certification programs create premium positioning for encryption-compliant devices in residential new construction.
Industry Challenges
- Embedded Firmware Talent Scarcity:Secure bootloader development and over-the-air update architecture require specialized expertise concentrated among semiconductor vendors and automotive suppliers.
- Multi-Protocol Certification Stacking:Simultaneous FCC, CE marking, and GB standard compliance for global product variants extends engineering validation cycles and testing expenditure.
- Legacy PMS Integration Complexity:Proprietary communication protocols in installed hotel property management systems demand custom middleware development for seamless mobile-key deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Lock Market |
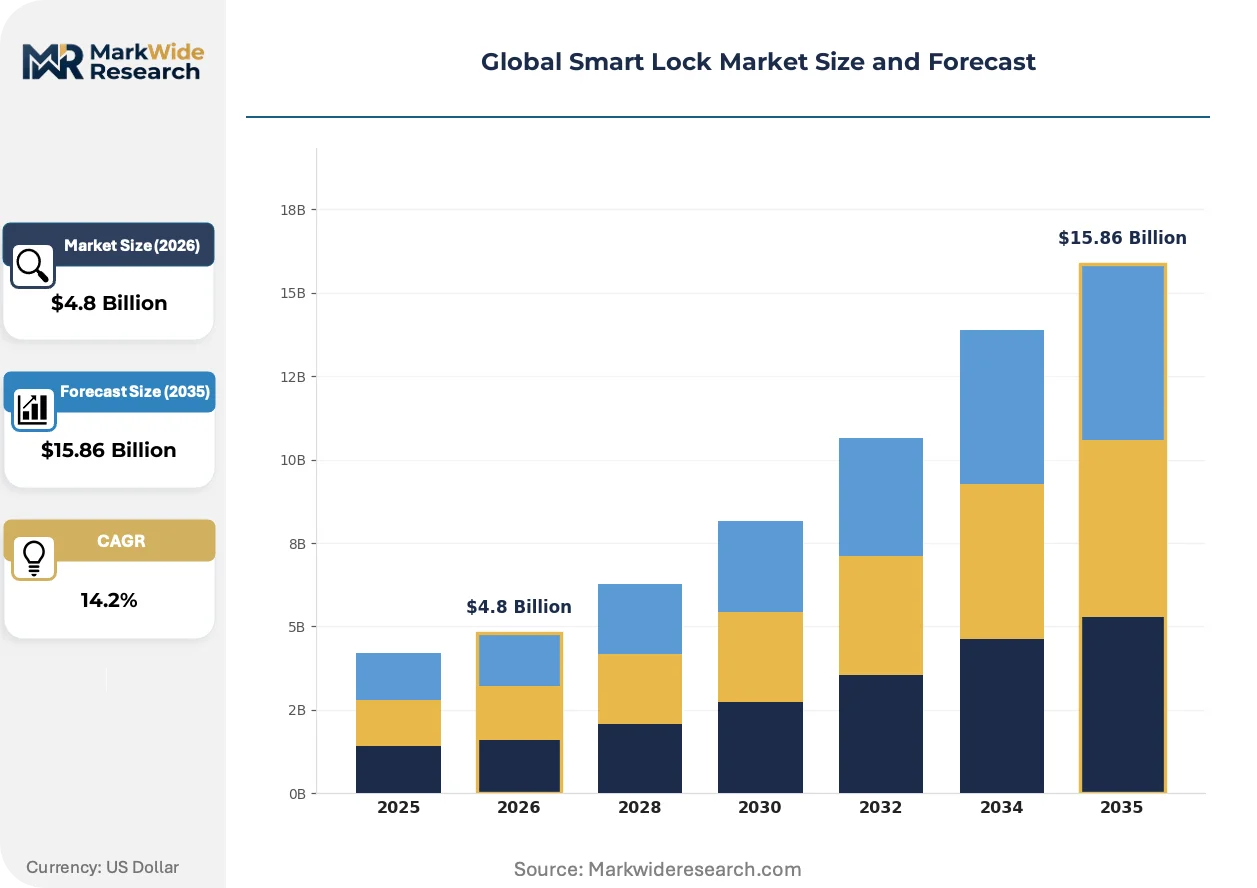
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolt, Lever Handle, Padlock, Smart Mortise Connectivity: Bluetooth, Wi-Fi, Z-Wave, Zigbee End User: Residential, Commercial, Industrial, Hospitality Security Level: High-Security, Standard, Biometric, Keyless |
| Companies Covered | ASSA ABLOY, Allegion plc, dormakaba Group, SALTO Systems, Spectrum Brands, Honeywell International, Samsung Electronics, August Home, Schlage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Lock Market Strategic Shifts
Authentication modality diversification and wireless protocol evolution are compressing hardware replacement cycles while expanding addressable use cases beyond traditional door applications.
Matter protocol adoption is fragmenting connectivity architecture decisions across the residential installer channel. The interoperability standard unifies Zigbee, Thread, and Wi-Fi stacks under single certification, reducing SKU proliferation for distributors serving multi-brand smart home ecosystems. Homebuilder specifiers in the United States now prioritize Matter-compliant devices to future-proof new construction installations against protocol obsolescence.
The EU AI Act's risk-based classification for biometric identification systems is forcing hardware redesigns in European markets. High-risk categorization triggers mandatory third-party conformity assessment, human oversight requirements, and registration in an EU database for locks processing facial or fingerprint templates. German security integrators report 6-9 month delays for biometric product launches as manufacturers reconfigure processing architectures to enable local template storage without cloud transmission.
Short-term rental operators are unbundling access management from traditional hospitality procurement channels. Airbnb hosts and corporate housing platforms now source direct-to-consumer smart locks through e-commerce marketplaces, bypassing security distributor networks that historically served commercial accounts. This channel compression is most visible in coastal United States markets where vacation rental density supports dedicated installation service networks.
Global Smart Lock Market Segmentation
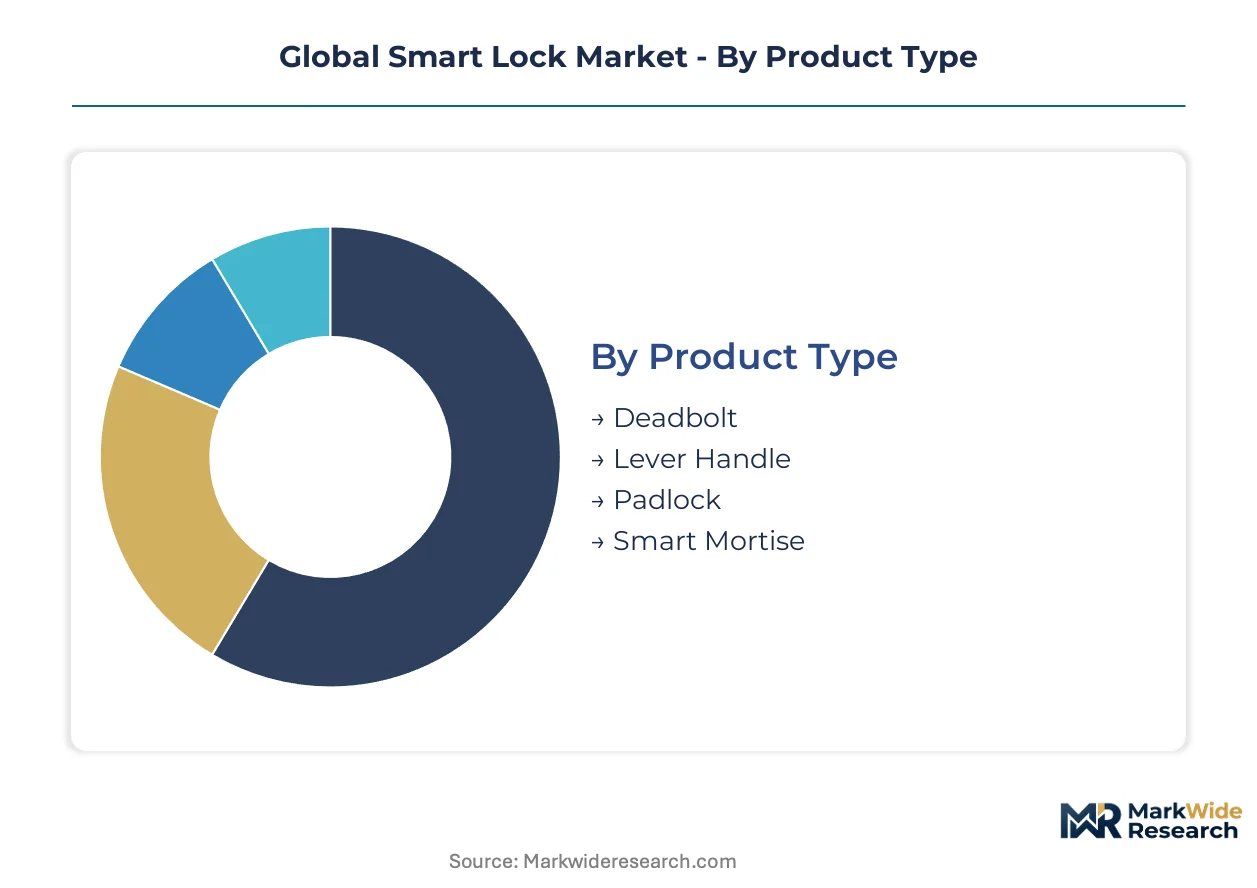
Smart lock procurement channels diverge sharply across product architectures, with retrofit-compatible hardware flowing through security distributors while connected platforms increasingly route through property management system integrators and direct-to-consumer marketplaces. Understanding these channel dynamics illuminates where margin pools concentrate and which segments command pricing power.
Product Type:
Channel mix varies by installation complexity, with deadbolt replacements dominating retail and e-commerce while mortise configurations flow through commercial security integrators requiring certified technician deployment.
- Deadbolt:Motorized single-point locking mechanisms interface with standard ANSI/BHMA door preparations without carpentry modification. Hospitality operators in Germany and the United States specify deadbolt platforms for rapid property-wide retrofits, though battery life constraints limit high-traffic deployment.
- Lever Handle:Integrated clutch mechanisms combine latch retraction with credential authentication in a single trim assembly. Commercial office landlords in South Korea favor lever-handle platforms for ADA-compliant accessibility combined with audit-trail capabilities.
- Padlock:Battery-powered shackle locks with Bluetooth or NFC credential reception target construction sites and shared storage facilities.
- Smart Mortise:Multi-point locking hardware requiring door preparation modification routes exclusively through certified locksmith channels.
Deadbolt dominates installed base. Smart Mortise is where expansion concentrates.
Connectivity:
Protocol selection dictates recurring revenue potential and cybersecurity liability exposure, with cloud-dependent architectures commanding subscription attach rates that pure local-access solutions cannot replicate.
- Bluetooth:Low-energy credential transmission operates without internet dependency, reducing attack surface for offline residential installations. United States single-family homebuilders specify Bluetooth-native locks to avoid Wi-Fi infrastructure dependencies in rural construction.
- Wi-Fi:Direct IP connectivity enables real-time access logging and remote credential revocation from any location. Hotel chains across Germany mandate Wi-Fi architectures to synchronize mobile-key issuance with property management system check-in events.
- Z-Wave:Mesh-network protocol optimized for whole-home automation integration through dedicated hubs.
- Zigbee:Low-power IEEE 802.15.4 standard increasingly subsumed under Matter interoperability certification.
Bluetooth retains volume leadership in unit shipments. Wi-Fi is climbing the fastest as remote management becomes non-negotiable for commercial procurement.
End User:
Customer-type segmentation reveals diverging procurement sophistication, with residential buyers prioritizing installation simplicity while hospitality and industrial accounts demand API-level integration with existing infrastructure.
- Residential:Single-family and multifamily owner-occupants purchase through retail, e-commerce, and homebuilder specification channels. South Korea's apartment-dense urban centers drive concentrated demand for fingerprint-enabled deadbolts with local template storage.
- Commercial:Office landlords and facility managers require audit-trail compliance and integration with visitor management systems. Germany's Mittelstand manufacturing campuses specify commercial-grade platforms with GB standard electromagnetic compatibility for export-oriented operations.
- Industrial:Critical infrastructure operators demand fail-physical override guarantees and extended temperature-range operation.
- Hospitality:Hotel chains and short-term rental operators prioritize mobile-key compatibility and housekeeping schedule integration.
Residential accounts for the largest unit volume. Hospitality is gaining share fastest as mobile-key mandates proliferate across property portfolios.
Security Level:
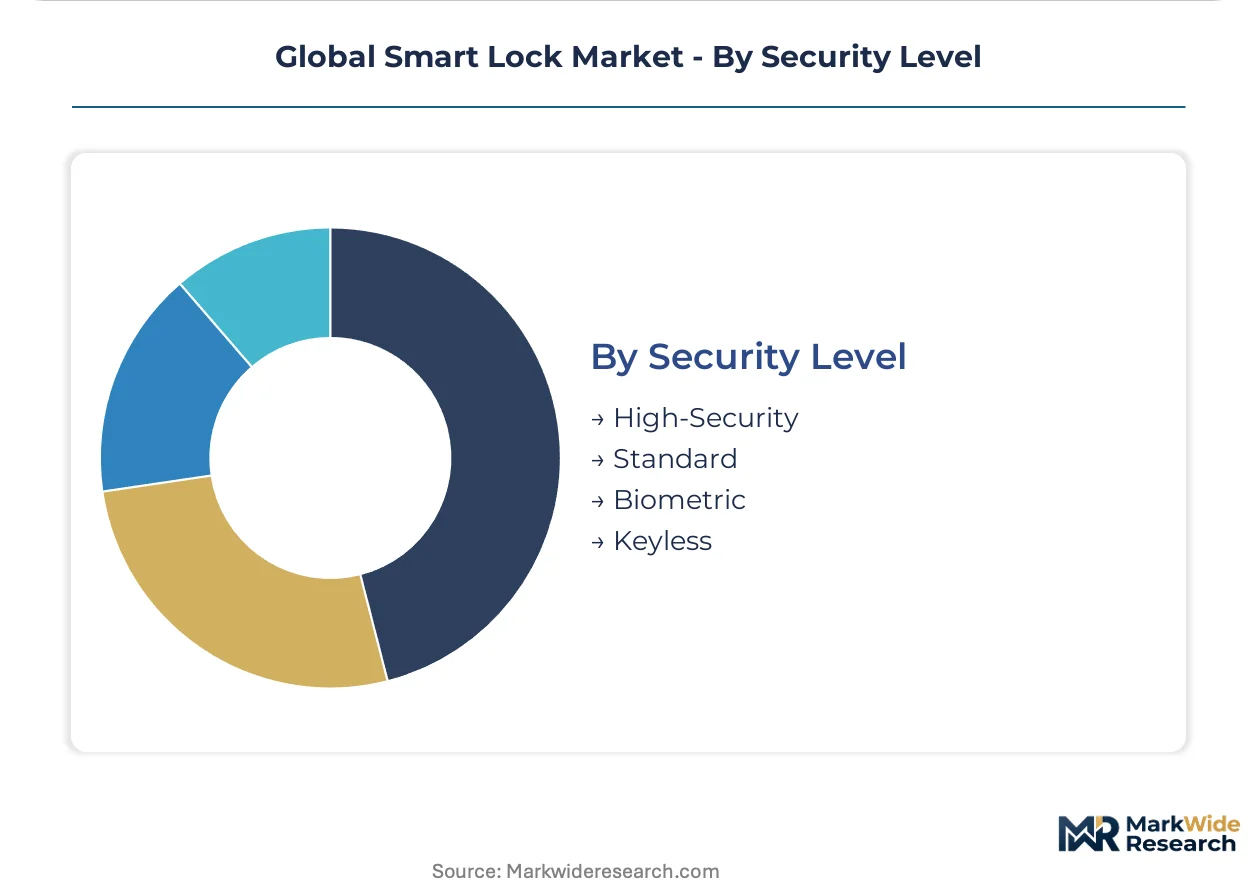
Certification grade determines pricing tier and regulatory exposure, with biometric platforms facing escalating conformity burdens under EU AI Act risk classification while keyless architectures compete on convenience rather than theft resistance.
- Biometric:Fingerprint, facial, or iris template processing requires specialized encryption modules and local storage architectures to satisfy GDPR and EU AI Act mandates. German security integrators report extended validation timelines as manufacturers reconfigure processing to enable template storage without cloud transmission.
- High-Security:UL 437 and EN 1303 certified cylinders resist pick, drill, and bump attacks for financial and government applications. United States federal facilities specify high-security platforms with FIPS 140-2 validated cryptographic modules.
- Standard:Consumer-grade credential protection without certified attack resistance targets price-sensitive residential replacement.
- Keyless:PIN or credential-based entry without mechanical override eliminates key management entirely.
Standard security dominates residential retrofit volume. Biometric is where steepest expansion trajectory concentrates despite regulatory friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports networked electronic access platforms to hospitality operators across Germany and the United States, establishing a critical trade corridor in retrofit-compatible smart lock hardware.
United States
Hotel chains mandate mobile-key compatibility across property portfolios, eliminating front desk friction. FCC certification governs wireless transmission parameters with 8-16 week validation timelines. Installers in coastal vacation rental markets source direct-to-consumer platforms through e-commerce channels, bypassing traditional security distributors.
Germany
Mittelstand manufacturing campuses specify commercial-grade platforms with audit-trail compliance for export-oriented operations. The EU AI Act imposes risk-classification requirements on biometric-enabled locks processing personal data. Security integrators in Berlin report extended validation timelines as manufacturers reconfigure processing architectures for local template storage.
South Korea
Apartment-dense urban centers drive concentrated demand for fingerprint-enabled deadbolts with local template storage. The country's national cybersecurity regulator enforces electromagnetic compatibility standards for networked home devices. Daegu-Gyeongbuk industrial clusters host foundry capacity for Wi-Fi and Bluetooth Low Energy chipsets.
Japan
Residential new construction specifiers prioritize METI cybersecurity labeling for IoT devices to differentiate premium positioning. Voluntary certification programs create segmentation between encryption-compliant and standard-tier hardware. Tokyo-based homebuilders specify Matter-compliant devices to future-proof installations against protocol obsolescence.
India
Commercial real estate modernization in Mumbai and Bangalore creates first-mover positioning for BIS-certified electromagnetic compatibility pathways. The Bureau of Indian Standards mandates labeling for networked home devices entering the market. Facility managers in Delhi-NCR specify retrofit-compatible deadbolt designs to upgrade aging building stock without carpentry modification.
Global Smart Lock Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and channel control dimensions. ASSA ABLOY leverages public market capital access to dominate high-security commercial installations across Europe and Asia. Allegion plc anchors its position through deep channel control in North American residential distribution networks. Three archetypes define competitive positioning: scale-driven manufacturers, channel-integrated distributors, and hospitality-focused platform specialists. Dominant competitive moves include M&A for technology access and strategic partnerships with property management system integrators.
Within the scale-driven tier, ASSA ABLOY and Allegion plc occupy positions as publicly traded entities with manufacturing footprints spanning multiple continents. dormakaba Group represents the specialization archetype, focusing on hospitality-specific platforms. Samsung Electronics exemplifies the technology convergence pattern, leveraging consumer electronics distribution for residential smart home penetration. These anchors illustrate how competitive advantage flows from channel architecture rather than product differentiation alone.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion plc |
| dormakaba Group |
| SALTO Systems |
| Spectrum Brands |
| Honeywell International |
| Samsung Electronics |
| August Home |
| Schlage |
| Others |
Value Chain & Pricing Dynamics
Wi-Fi chipset substitution for Bluetooth-only architectures is redrawing supply geography toward East Asian foundry clusters while compressing pricing premiums for remote-monitoring capabilities. This input transition simultaneously elevates bill-of-materials exposure to semiconductor supply concentration and erodes the pricing power that Bluetooth-native vendors previously commanded in residential retrofit channels.
Pricing Analysis
Three-generation pricing stratification separates Wi-Fi-enabled platforms from Bluetooth-native hardware and legacy mechanical-electronic hybrids. Three-tier pricing structure across premium biometric, standard connected, and economy keypad tiers reflects certification grade differentiation under FCC and EU AI Act mandates. Cost compression in standard Wi-Fi deadbolts is intensifying because hospitality procurement consolidation extracts volume discounts. Short-term rental operators exhibit highest price sensitivity due to direct-to-consumer procurement, while federal facility buyers show lowest sensitivity given FIPS 140-2 compliance requirements.
Supply Chain Analysis
Just-in-time inventory preferences dominate among hospitality procurement teams synchronizing lock deployment with property renovation schedules, though semiconductor lead time volatility is forcing strategic stockpiling of Wi-Fi and Bluetooth Low Energy chipsets. Foundry capacity concentrates in South Korea, Taiwan, and China for wireless connectivity components. Battery cell supply rests on cylindrical lithium primary cell production anchored in Japan and China. Single-source vulnerability in BLE SoC fabrication exposes manufacturers to allocation rationing during foundry capacity constraints. Distribution runs through security distributor networks for commercial accounts and direct-to-consumer marketplaces for residential and short-term rental segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware development expertise for secure bootloaders and over-the-air update architectures represents the critical capability gap constraining product launch velocity. Manufacturers lacking in-house secure software engineering face 6-9 month delays versus integrated competitors.
For Market Incumbents: Compound channel control advantages by embedding mobile-key APIs directly into property management system integration layers, neutralizing the threat from direct-to-consumer entrants bypassing security distributors. Prioritize backward integration into hardware encryption module design to accelerate EU AI Act conformity assessment timelines and defend margin position against certification-driven cost escalation. For New Entrants and Emerging Players: Differentiate on hospitality-specific middleware development for legacy PMS protocol translation, targeting the white-space between installed hotel systems and mobile-key mandates. India's BIS certification pathway for commercial real estate retrofits in Mumbai and Bangalore offers the most penetrable geography. Pursue channel partnerships with vacation rental installation service networks rather than competing for security distributor shelf space. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform specialists with proven PMS integration capabilities over pure hardware manufacturers. Long-term viability hinges on recurring revenue attach rates from cloud-dependent Wi-Fi architectures rather than transactional hardware margins. Acquisition target archetype: hospitality-focused software-hardware integrators with deployed API libraries. Watch Matter protocol adoption velocity among United States homebuilders as inflection indicator for residential channel restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Property Management System API Integration | Enables mobile-key synchronization with housekeeping scheduling across Marriott and Hilton property portfolios. |
| EU AI Act Conformity Assessment Investment | Accelerates biometric product launches in Germany by enabling local template storage architectures. |
| Matter Protocol Certification | Future-proofs residential installations against Zigbee and Thread protocol fragmentation in Japan. |
| Direct-to-Consumer Channel Expansion | Captures short-term rental procurement bypassing traditional security distributor networks in coastal United States. |
| Hardware Encryption Module Backward Integration | Reduces third-party dependency for GDPR-compliant biometric processing in European markets. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with smart lock product managers, hospitality technology procurement directors, commercial security integrators, and semiconductor supply chain specialists; and secondary validation against FCC certification databases, EU AI Act implementation guidance, SEC 10-K filings from publicly traded access control manufacturers, and hospitality property management system integration documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product architecture, connectivity protocol, end-user segment, and security certification tier. CAGRs derived from fitted growth curves applied to segment-specific adoption rates. Forecast inputs incorporated hospitality mobile-key mandate rollout schedules, foundry capacity expansion announcements, and regional electromagnetic compatibility certification pathway timelines.
Material uncertainties — semiconductor allocation disruptions, EU AI Act enforcement intensity variations, and Matter protocol adoption velocity — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained hospitality capital expenditure and stable wireless chipset supply. Revision becomes warranted when foundry utilization rates for BLE and Wi-Fi SoCs cross thresholds triggering allocation rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Car Security System Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Asia-Pacific Card-Based Access Control Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Italy Access Control Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Smart Entry System Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Global Automated Border Control Market