
 United States Smart Lock Market | 2026-2036
United States Smart Lock Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smart Lock Market Analytics
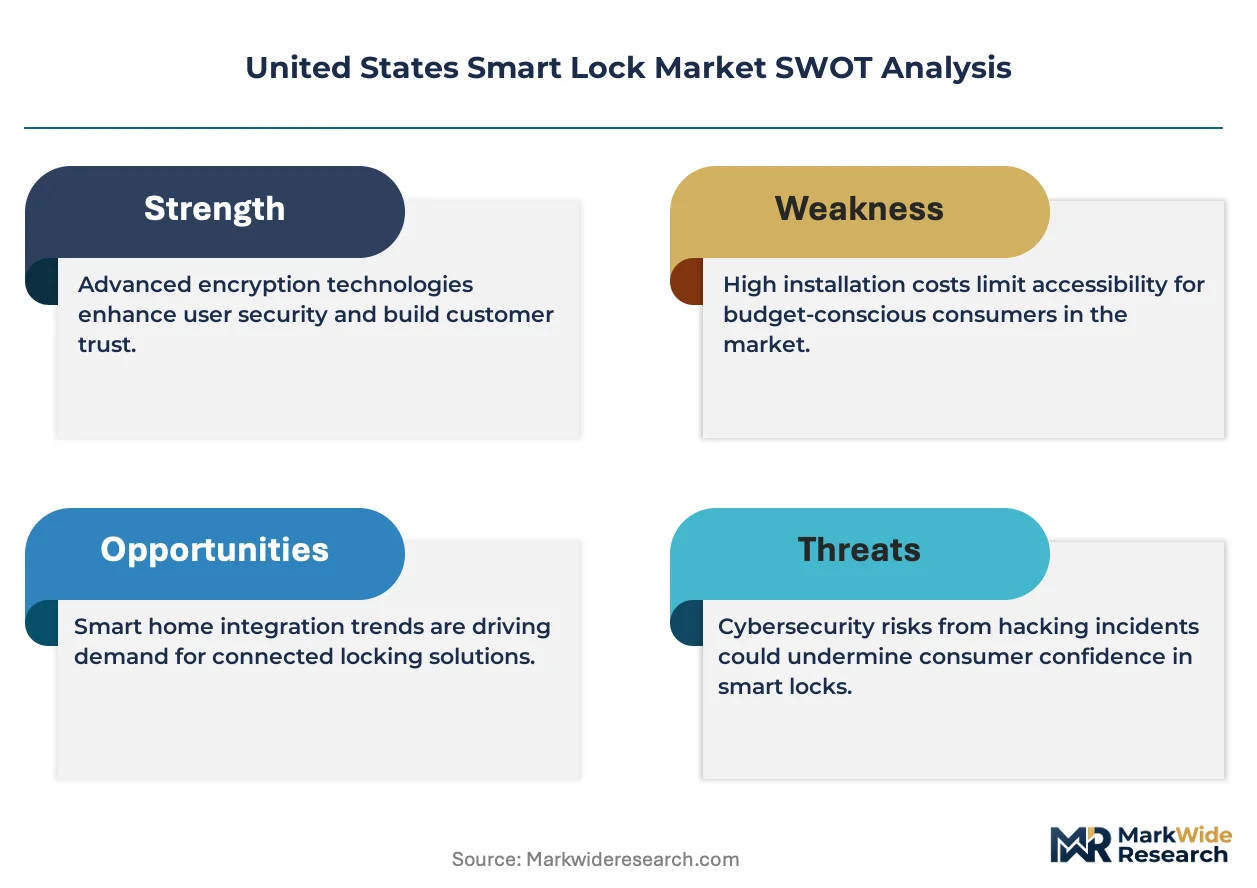
The capital-intensity divergence between integrated hardware-software platforms and traditional lock OEMs is redrawing competitive boundaries in the United States Smart Lock Market. ASSA ABLOY leverages its captive semiconductor sourcing and foundry relationships to control bill-of-material costs across Bluetooth and Z-Wave product lines. Allegion sustains R&D intensity through dedicated cybersecurity labs that harden firmware against wireless protocol exploits. Yale Home anchors brand recognition among institutional buyers through long-standing specification relationships with national facility management firms.
A smart lock is an electromechanical locking device that authenticates users through biometric sensors, keypad codes, mobile applications, or proximity credentials, typically operating on battery power with wireless communication protocols at 2.4 GHz frequency bands. The device serves commercial and residential entry control by logging access events, enabling remote authorization, and integrating with building management systems. Deadbolt configurations command the largest installed base due to retrofit compatibility with standard door preparations, while Wi-Fi-enabled models represent the fastest-growing technology segment as cloud-native property management platforms expand. The commercial end-user category captures disproportionate margin pools through enterprise-grade encryption requirements and recurring software subscription attach rates.
The FCC enforces Part 15 emissions standards that govern wireless smart lock certification, while the NIST Cybersecurity Framework informs enterprise buyer due diligence on IoT device hardening. State-level data privacy statutes, notably the California Consumer Privacy Act, compel manufacturers to disclose biometric data handling practices and retention policies. Stakeholders must monitor evolving insurance underwriting criteria for cyber-physical breaches as carriers tighten loss expectations for networked access control deployments.
Market Dynamics
The United States Smart Lock Market is being restructured by the migration from standalone Bluetooth devices to Wi-Fi-native cloud platforms that enable real-time property management integration. This shift compresses hardware margins while expanding recurring software revenue pools for ecosystem providers.
Growth Catalysts
- FCC Part 15 Certification Streamlining:The commission's modular approval pathways for pre-certified radio modules reduce time-to-market for manufacturers launching Z-Wave and Thread-enabled products. Developers in Texas and Florida now specify smart locks as standard multifamily amenities.
- Biometric Sensor Cost Curves:Fingerprint module prices have fallen below threshold levels for mid-tier residential SKUs. Property managers in Arizona and Nevada are upgrading from keypad-only to biometric-capable hardware.
- California Consumer Privacy Act Compliance:Biometric data handling disclosures mandated by CCPA have paradoxically accelerated enterprise buyer confidence. Facility management firms now demand documented retention policies as a procurement filter.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cylindrical cell production clusters in East Asia create input vulnerability for battery-powered lock OEMs. Tariff exposure on Chinese-sourced cells compresses gross margins on entry-level Wi-Fi models.
- Enterprise Encryption Overhead:AES-256 hardware acceleration requirements add silicon cost that price-sensitive residential buyers resist. This technical floor prevents full feature parity across premium and economy tiers.
- Legacy Mortise Compatibility Limits:Non-standard door preparations in pre-1990 commercial buildings block retrofit penetration. Installation complexity forces deferred replacement cycles in the Northeast's aged building stock.
Strategic Opportunities
- Underpenetrated Secondary Sun Belt Markets:Alabama and South Carolina multifamily construction is accelerating without commensurate smart lock saturation. First-mover specification relationships with regional developers offer lock-in advantages.
- Matter Protocol Convergence:Thread-over-Matter interoperability is collapsing ecosystem fragmentation between Amazon, Apple, and Google smart home stacks. Hardware vendors supporting multi-admin commissioning capture cross-platform demand.
- Insurance Underwriting Incentives:Cyber-physical breach riders on commercial property policies are tightening loss expectations. Carriers in Florida are beginning to discount premiums for encrypted access control deployments.
Industry Challenges
- Firmware Security Talent Scarcity:Embedded systems engineers with wireless protocol exploit mitigation skills command premium compensation. Smaller OEMs struggle to staff dedicated cybersecurity labs comparable to Allegion's capabilities.
- Cloud Platform Integration Complexity:Property management software APIs lack standardization across RealPage, Yardi, and Entrata systems. Lock vendors must maintain multiple integration teams to serve enterprise accounts.
- NIST Cybersecurity Framework Alignment:Enterprise buyers now mandate third-party attestation of IoT device hardening. Certification timelines stretch 8-14 months for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smart Lock Market |
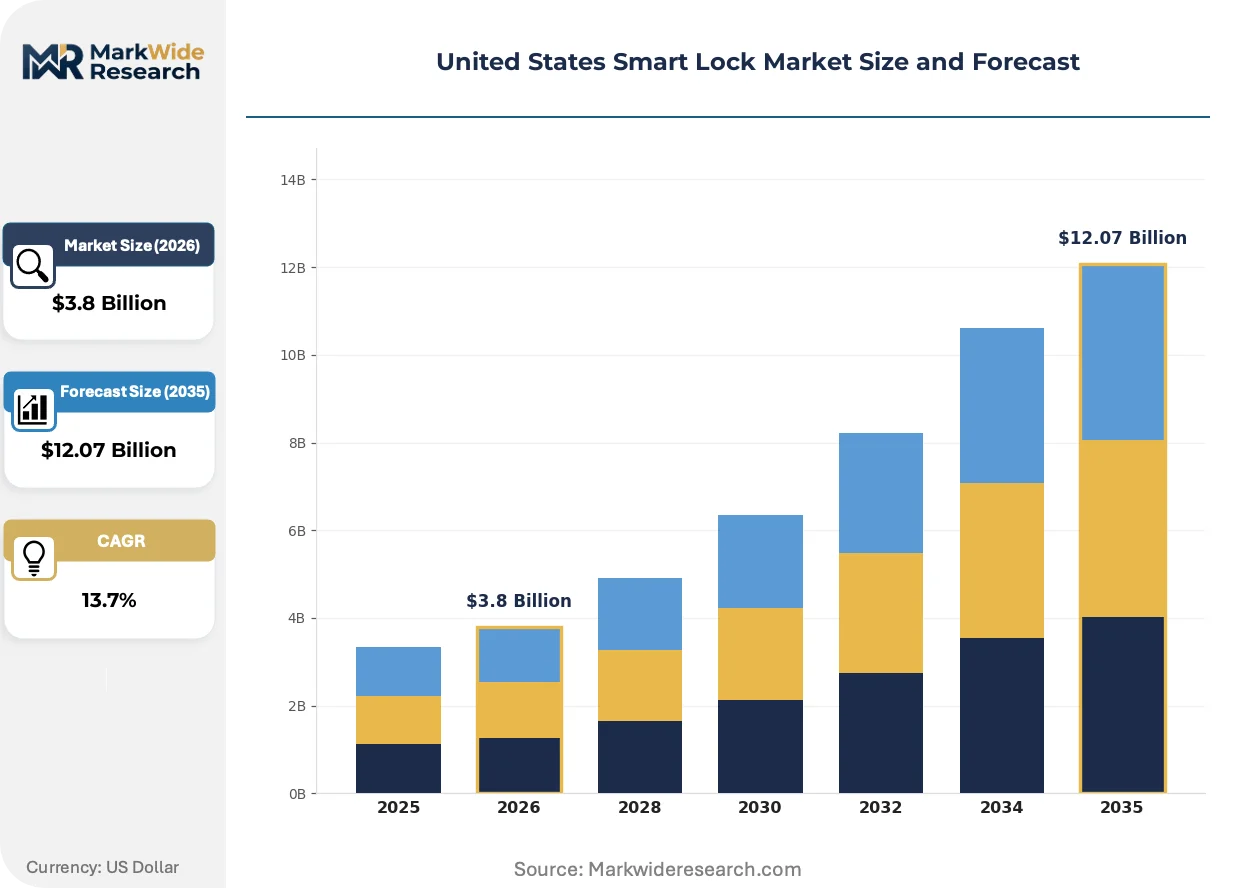
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolt, Lever, Padlock, Mortise Technology: Bluetooth, Wi-Fi, Z-Wave, Zigbee End User: Residential, Commercial, Industrial, Government Installation Type: DIY, Professional, Integrated, Retrofit |
| Companies Covered | ASSA ABLOY, Allegion, August Home, Schlage, Yale Home, Kwikset, Level Home, Lockly, SimpliSafe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smart Lock Market Evolving Landscape
Wi-Fi-enabled smart locks are displacing Bluetooth-only architectures as the default specification in new construction. This transition is compressing the addressable market for standalone keypad devices while expanding cloud-native platform competition.
Thread mesh networking is supplanting Z-Wave as the preferred low-power protocol for whole-home automation integration. Multi-family developers in Dallas and Miami are specifying Thread-native hardware to reduce hub dependency and improve failover reliability. The protocol shift is enabling battery life extension from 12 to 24 months, compressing replacement part revenue for legacy Z-Wave suppliers.
The FCC's enforcement of modular transmitter certification is tightening documentation requirements for software-defined radio implementations. Manufacturers must now submit anticipated firmware update pathways as part of initial equipment authorization. Enterprise-grade SKUs with over-the-air update capabilities face extended review timelines compared to locked-firmware residential models.
Property managers are consolidating vendor relationships around integrated hardware-software platforms rather than sourcing locks and access software separately. National facility management firms now issue RFPs bundling installation, monitoring, and tenant credential provisioning. This procurement compression is most visible in Phoenix and Atlanta, where REITs have standardized on single-ecosystem deployments across entire portfolios.
United States Smart Lock Market Segmentation
Smart lock purchasing patterns diverge sharply across installation contexts, with retrofit compatibility and wireless protocol selection determining vendor shortlists. Understanding segment-level substitution pressures helps manufacturers allocate R&D resources between incremental hardware improvements and platform-level software investments.
Product Type:
Deadbolt configurations face intensifying substitution pressure from lever-style alternatives in multifamily new construction, where reduced installation labor tilts specification decisions.
- Deadbolt:Cylindrical single-bore preparation matches the predominant door specification in single-family residential stock. Demand concentrates in Texas and Florida retrofit markets where homeowners prioritize compatibility with existing strike plates.
- Lever:ADA-compliant handle configurations reduce liability exposure for commercial property managers. Arizona and Nevada multifamily developers specify lever locks to streamline contractor installation schedules and minimize punch-list delays.
- Padlock:Portable electromechanical units serve construction site security and storage facility applications with shackle diameter ratings from 8mm to 11mm.
- Mortise:Box-lock preparations for pre-1990 commercial buildings require specialized door modification, limiting addressable retrofit volume in Northeast urban cores.
Deadbolt retains volume leadership; lever holds the steepest expansion curve.
Technology:
Protocol selection increasingly stratifies by customer technical sophistication, with Wi-Fi-native architectures commanding premium positioning against legacy Bluetooth-only alternatives.
- Bluetooth:Low-energy 2.4 GHz implementations dominate entry-level residential SKUs with 12-month battery life. Sun Belt DIY installers favor Bluetooth for hub-free operation in vacation rental properties.
- Wi-Fi:Direct cloud connectivity enables real-time access logging without intermediary bridges. Phoenix and Atlanta property management firms specify Wi-Fi locks to consolidate vendor relationships around single-platform dashboards.
- Z-Wave:Sub-GHz mesh networking persists in legacy smart home installations with 700-series chip backward compatibility requirements.
- Zigbee:IEEE 802.15.4 protocol adoption concentrates in utility demand-response programs seeking coordinated load management through connected thermostats and entry devices.
Bluetooth retains installed base dominance; Wi-Fi captures the fastest share gains in new construction specifications.
End User:
Customer-type segmentation reflects diverging procurement sophistication, with enterprise buyers demanding cybersecurity attestation that residential channels ignore.
- Residential:Single-family and multifamily households prioritize mobile app convenience over encryption certification. Florida rental property investors drive volume through bulk purchasing of keypad-entry units.
- Commercial:Office and retail facility managers require AES-256 hardware acceleration and documented firmware update pathways. National facility management firms now mandate NIST Cybersecurity Framework alignment in RFP evaluations.
- Industrial:Manufacturing and warehouse applications demand IP65 environmental sealing and tamper-evident housing designs for perimeter access control.
- Government:Federal and municipal installations require FIPS 140-2 validated cryptographic modules with restricted supply chain provenance documentation.
Residential commands absolute unit volume; commercial generates disproportionate margin contribution through software subscription attach.
Installation Type:
Channel structure is bifurcating between self-install retail and integrated professional deployment, with retrofit complexity determining route-to-market economics.
- DIY:Consumer-direct sales through home improvement retailers emphasize 15-minute installation claims and compatibility verification tools. Online configurators reduce return rates by matching deadbolt backset measurements.
- Professional:Locksmith and security dealer channels provide staging, programming, and tenant credential provisioning for multifamily portfolios. Dallas and Miami developers specify professional installation to warranty coverage requirements.
- Integrated:New construction pre-installation by electrical contractors captures smart home bundling opportunities with lighting and climate control systems.
- Retrofit:Replacement of legacy mechanical locks in existing door preparations requires adaptive strike plate kits and bore diameter standardization.
DIY sustains volume leadership in unit terms; integrated installation climbs fastest as new construction smart home pre-wiring becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sun Belt commands pricing power through new construction pre-installation premiums, while the Northeast absorbs margin compression from retrofit complexity and aged building stock limitations.
Texas
Multi-family developers in Dallas and Houston specify smart locks as standard amenities to accelerate lease-up velocity. The Texas Department of Licensing and Regulation enforces contractor licensing for security system installations. Austin's technology corridor attracts smart home platform engineering talent from legacy hardware OEMs.
Florida
Rental property investors in Miami and Tampa drive bulk purchasing of keypad-entry units for vacation rental portfolios. The Florida Building Code mandates hurricane-rated door hardware in coastal counties. Orlando's hospitality sector experiments with mobile-key integration for resort property management.
California
Enterprise facility managers in Los Angeles and San Francisco demand CCPA-compliant biometric data handling documentation. The California Consumer Privacy Act compels retention policy disclosures for fingerprint-enabled hardware. Silicon Valley smart home startups pilot Matter-over-Thread interoperability in corporate housing developments.
Arizona
Property managers in Phoenix and Scottsdale upgrade from keypad-only to biometric-capable hardware as sensor costs decline. The Arizona Registrar of Contractors regulates smart lock installation warranty coverage. Tucson's senior living developers specify lever-style ADA-compliant configurations for liability reduction.
Nevada
Las Vegas hospitality REITs consolidate vendor relationships around single-ecosystem deployments across entire portfolios. The Nevada State Contractors Board licenses residential and commercial security equipment installers. Reno's logistics corridor adopts padlock configurations for construction site perimeter access control.
United States Smart Lock Market Competitive Landscape
Concentration sits with integrated hardware-software platforms that capture recurring subscription revenue alongside device margins. The vendor base stratifies across three tiers: captive semiconductor sourcing specialists, cybersecurity-forward firmware developers, and cloud-native platform integrators. Dominant competitive moves include specification relationship lock-in with national facility management firms and backward integration into radio module certification pathways.
Within the integrated platform tier, ASSA ABLOY and Allegion occupy positions defined by supply chain control and security lab infrastructure respectively. Yale Home exemplifies brand recognition leverage through long-standing institutional procurement channels. August Home sits within the cloud-native segment, representing the shift from standalone Bluetooth architectures to Wi-Fi-enabled property management integration. These three anchors demonstrate how competitive positioning diverges between silicon cost discipline, firmware hardening capabilities, and software ecosystem breadth.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion |
| August Home |
| Schlage |
| Yale Home |
| Kwikset |
| Level Home |
| Lockly |
| SimpliSafe |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with radio module foundries lock in both semiconductor supply access and 18-24 month price visibility for smart lock OEMs navigating FCC certification timelines. These arrangements concentrate procurement leverage among tier-one manufacturers while exposing smaller vendors to spot-market volatility in Bluetooth and Thread chipsets.
Pricing Analysis
The customization-premium spread between configured-to-order enterprise SKUs and standard residential units spans 40-60 percent in the United States Smart Lock Market. Three-tier pricing structure across premium, standard, and economy levels reflects encryption certification grade and after-sales software bundling rather than hardware differentiation alone. Cost compression in entry-level Wi-Fi models stems from lithium-ion cell tariff exposure, forcing margin sacrifices among non-integrated OEMs. Residential DIY buyers exhibit highest price sensitivity, while commercial facility managers prioritize AES-256 attestation over unit cost.
Supply Chain Analysis
China and South Korea anchor cylindrical lithium-ion cell production, while Taiwan concentrates radio frequency chip fabrication for 2.4 GHz and sub-GHz protocols. Smart lock assembly draws from Chinese metal casting for housings, Malaysian PCB fabrication, and domestic firmware development. Single-source vulnerability in East Asian battery supply creates tariff amplification risk that distribution runs through national security dealer networks and direct-to-builder channels must absorb. Professional installation segments mitigate this exposure through warranty-backed service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as protocol convergence collapses ecosystem boundaries, creating niche openings for specialized vendors serving underpenetrated Sun Belt construction verticals and legacy retrofit corridors.
For Market Incumbents: Consolidate specification relationships with national facility management firms before Matter protocol standardization commoditizes hardware differentiation. Backward integration into captive semiconductor sourcing buffers margin pressure from East Asian cell tariffs. Prioritize firmware security lab investment to maintain NIST Cybersecurity Framework alignment as enterprise procurement filter tightens.
For New Entrants and Emerging Players: Lead with Thread-native Wi-Fi architectures targeting Alabama and South Carolina multifamily developers lacking incumbent lock-in. Alabama's accelerating construction pipeline offers first-mover specification advantages absent in saturated Texas and Florida markets. Partner with regional electrical contractors for integrated pre-installation rather than competing through retail DIY channels.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platform integrators with recurring software revenue attach and demonstrated API standardization across property management systems. Long-term viability favors vendors bridging hardware margin compression with subscription monetization. Watch for carrier premium discounting signals in Florida as cyber-physical breach underwriting criteria harden.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Thread-over-Matter interoperability collapses ecosystem fragmentation between Amazon, Apple, and Google smart home stacks. |
| Biometric Sensor Integration | Fingerprint module cost curves below threshold levels enable mid-tier residential SKU upgrades in Arizona and Nevada. |
| Enterprise Encryption Hardening | AES-256 hardware acceleration and documented firmware pathways satisfy NIST Cybersecurity Framework procurement filters. |
| Sun Belt Developer Specification | First-mover relationships with Dallas and Miami multifamily builders capture pre-installation bundling opportunities. |
| Insurance Underwriter Alignment | Florida carrier premium discounts for encrypted access control deployments validate cybersecurity investment ROI. |
Research Methodology
Operator-level perspectives from smart home platform engineers, multifamily property managers, security system contractors, and FCC certification consultants anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed hardware OEMs, FCC equipment authorization databases, and National Multifamily Housing Council construction pipeline reports. Bottom-up unit demand modeling triangulated against top-down addressable housing stock estimates across the analysis window.
Sensitivity analysis tested forecast robustness across protocol adoption scenarios, tariff rate assumptions, and new construction smart home penetration curves. Segmentation dimensions modeled include product configuration, wireless technology, end-user category, installation channel, and regional construction intensity. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns and builder specification survey data. Matter protocol adoption velocity and biometric sensor cost trajectories served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside FCC modular approval timeline stability, Sun Belt construction permit continuity, or lithium-ion supply chain configuration would require recalibration. Forecasts reflect documented assumptions on technology substitution rates and regulatory enforcement intensity. Recalibration cycles align with material shifts in protocol standardization, carrier underwriting criteria, or state-level data privacy statute expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Smart Locks Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
Asia-Pacific Card-Based Access Control Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Digital Security Control Market