
 Mode Locking Device Market | 2026-2036
Mode Locking Device Market Size, Share, and Industry Trends Forecast 2026-2036
Mode Locking Device Market Insights
Industrial laser processing is broadening its share of mode locking device consumption, while legacy telecom test equipment demand contracts. Coherent, Inc. leverages its vertically integrated crystal manufacturing to dominate ultrafast oscillator supply. IPG Photonics anchors high-power fiber laser integration with in-house mode locking modules. Trumpf sustains German precision engineering dominance through captive R&D in disk laser pulse generation.
A mode locking device generates ultra-short optical pulses through phase synchronization of multiple longitudinal cavity modes, typically achieving pulse durations from femtoseconds to picoseconds via active electro-optic modulation or passive saturable absorber techniques. These devices enable precision material ablation, biomedical imaging, and spectroscopic analysis where temporal resolution determines system performance. Electronic lock configurations command premium positioning due to semiconductor fabrication complexity, while smart lock architectures with embedded Bluetooth connectivity represent the fastest-expanding demand pool as IoT-enabled access control penetrates commercial buildings. Mechanical lock variants retain cost-sensitive industrial maintenance applications where electromagnetic interference precludes electronic solutions.
FDA laser product performance standards govern medical and surgical device applications in the United States, mandating specific output stability documentation that shapes manufacturer design priorities. CE marking under the EU Machinery Directive and RoHS substance restrictions constrain material selection and electromagnetic compatibility testing for European market entry. China's MIIT national laser safety standards and GB certification requirements create additional compliance layers for imported equipment. Stakeholders must monitor evolving cybersecurity mandates for wireless-connected smart locks as regulatory frameworks for IoT physical security devices mature across major economies.
Market Dynamics
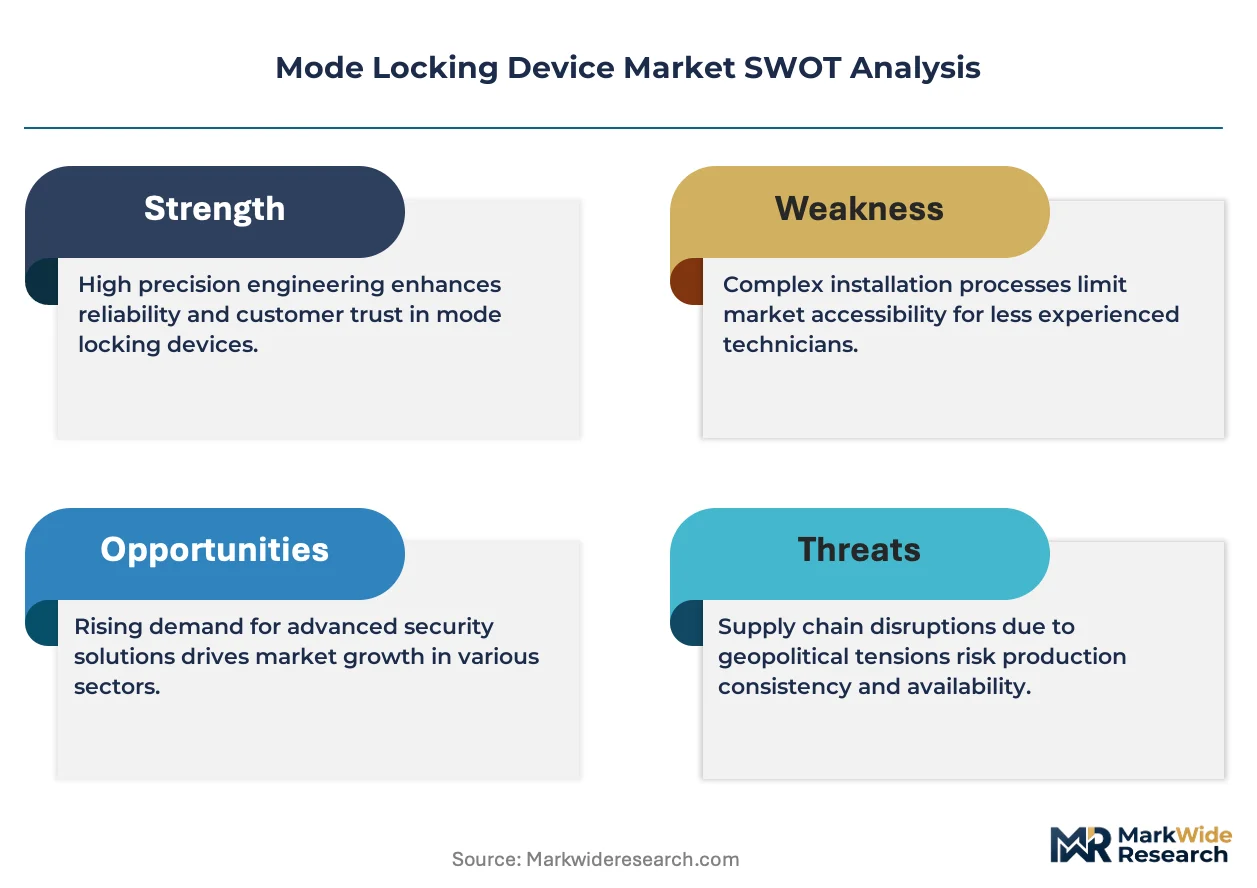
Precision manufacturing is pulling mode locking device demand toward femtosecond-class pulse stability as semiconductor lithography and medical device fabrication tighten tolerance requirements. This structural shift compresses supplier qualification timelines and elevates certification documentation burdens across the value chain.
Growth Catalysts
- Semiconductor node shrinkage:Sub-7nm lithography systems require stabilized ultrafast lasers for mask inspection and wafer metrology, expanding oscillator deployment in foundry capital equipment.
- China's MIIT laser safety standards:Mandatory GB certification for imported industrial laser systems is forcing foreign suppliers to establish local testing partnerships, accelerating domestic supply chain maturation.
- Biomedical imaging proliferation:Multiphoton microscopy adoption in neuroscience research centers is saturating university procurement budgets with mode-locked Ti:sapphire systems.
Market Restraints
- Optical crystal supply concentration:Synthetic sapphire and YAG substrate fabrication concentrates in Ukrainian and Russian facilities, exposing oscillator manufacturers to geopolitical input disruption.
- RoHS substance restrictions:Lead-free solder mandates in EU-bound equipment complicate thermal management in high-power electro-optic modulator assemblies.
- Discrete vs. integrated substitution:Semiconductor saturable absorber mirrors (SESAMs) are displacing bulk crystal mode lockers in cost-sensitive industrial maintenance applications.
Strategic Opportunities
- India's PLI scheme for photonics:Production-linked incentives for laser component manufacturing are attracting module assembly investments near Bengaluru's electronics corridor.
- Quantum sensing convergence:Mode-locked frequency combs interfacing with atomic interferometers are opening defense and geodesy applications outside traditional industrial laser markets.
- Direct-to-researcher distribution:Specialized distributors bypassing traditional systems integrators are capturing margin in academic and government laboratory procurement channels.
Industry Challenges
- Few-optics engineering talent scarcity:Ultrafast pulse characterization and dispersion compensation design skills concentrate in German and Swiss technical universities, constraining Asian supplier R&D scaling.
- FDA 510(k) documentation burden:Medical device laser submissions require extensive pulse stability validation protocols that extend product launch timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mode Locking Device Market |
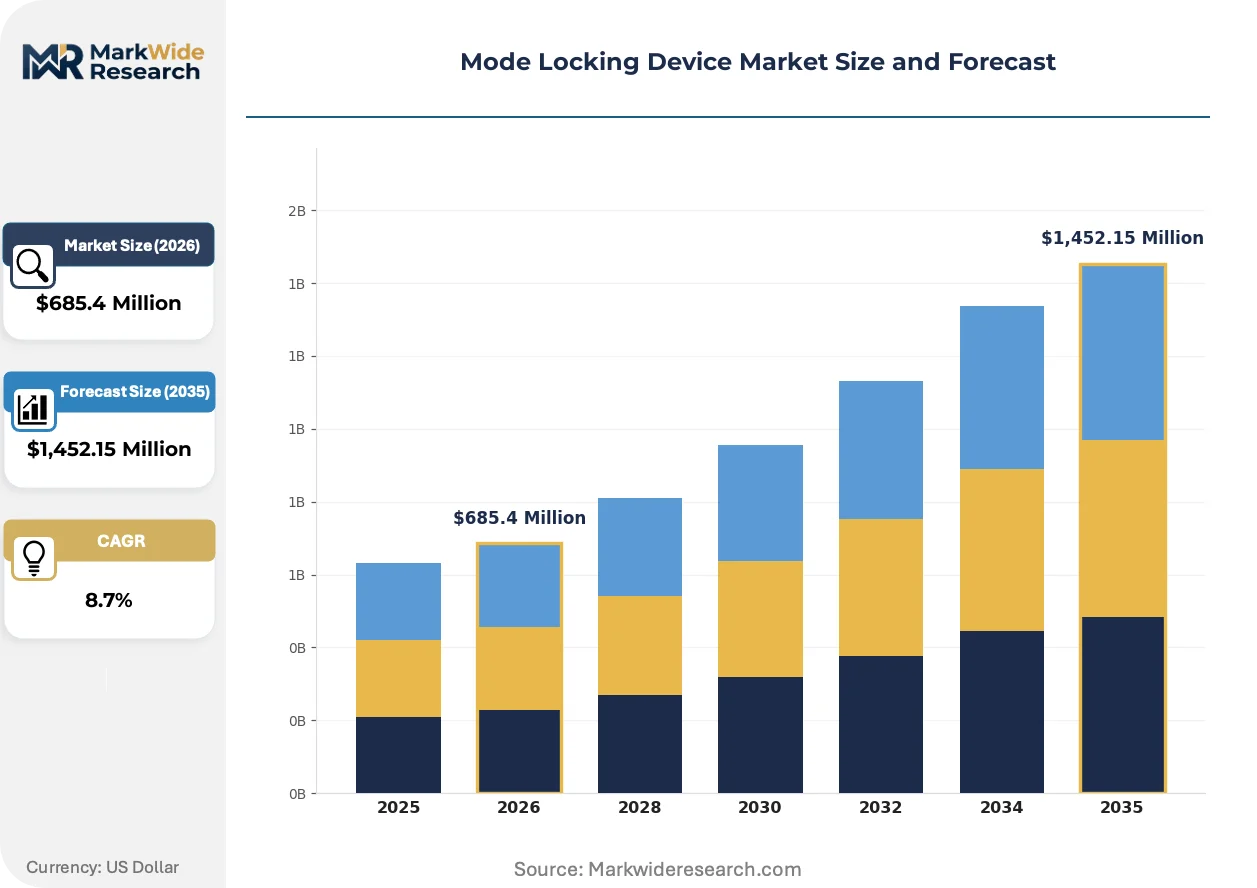
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Lock, Electronic Lock, Smart Lock, Biometric Lock Application: Residential, Commercial, Industrial, Government Connectivity: Wired, Wireless, Bluetooth, Wi-Fi End User: Homeowners, Businesses, Contractors, Security Firms |
| Companies Covered | Coherent, Inc., IPG Photonics, Spectra-Physics, TOPTICA Photonics, Menlo Systems, Amplitude Laser, Trumpf, Ekspla, Light Conversion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mode Locking Device Market Trends and Innovations
Ultrafast laser architecture is fragmenting as application-specific pulse formats displace general-purpose oscillator platforms. This diversification is compressing product development cycles and forcing suppliers to prioritize modular subassembly strategies over integrated system dominance.
Carbon nanotube saturable absorbers are decentralizing mode locking device manufacturing by enabling polymer-composite fabrication outside traditional crystal growth facilities. Medical device OEMs in Germany and Japan are qualifying these lower-cost alternatives for ophthalmic imaging systems. The technology is decentralizing supply chain control from established crystal manufacturers to specialty chemical processors.
China's MIIT national laser safety standards are tightening electromagnetic compatibility testing requirements for wireless-connected smart lock architectures. European exporters must now submit to dual GB certification and CCC marking procedures before hospital and research facility deployment. Medical laser integrators are responding by pre-qualifying modules to both FDA 21 CFR 1040 and MIIT standards during initial design phases.
Buying committees at semiconductor capital equipment firms are unbundling oscillator specification from full laser system procurement, creating direct component sourcing relationships with mode locker specialists. Systems integrators in Japan and South Korea are resisting this disintermediation by embedding proprietary control interfaces. The behavior is most visible in EUV lithography supply chains where ASML-qualified subcomponent lists constrain buyer autonomy.
Mode Locking Device Market Segmentation
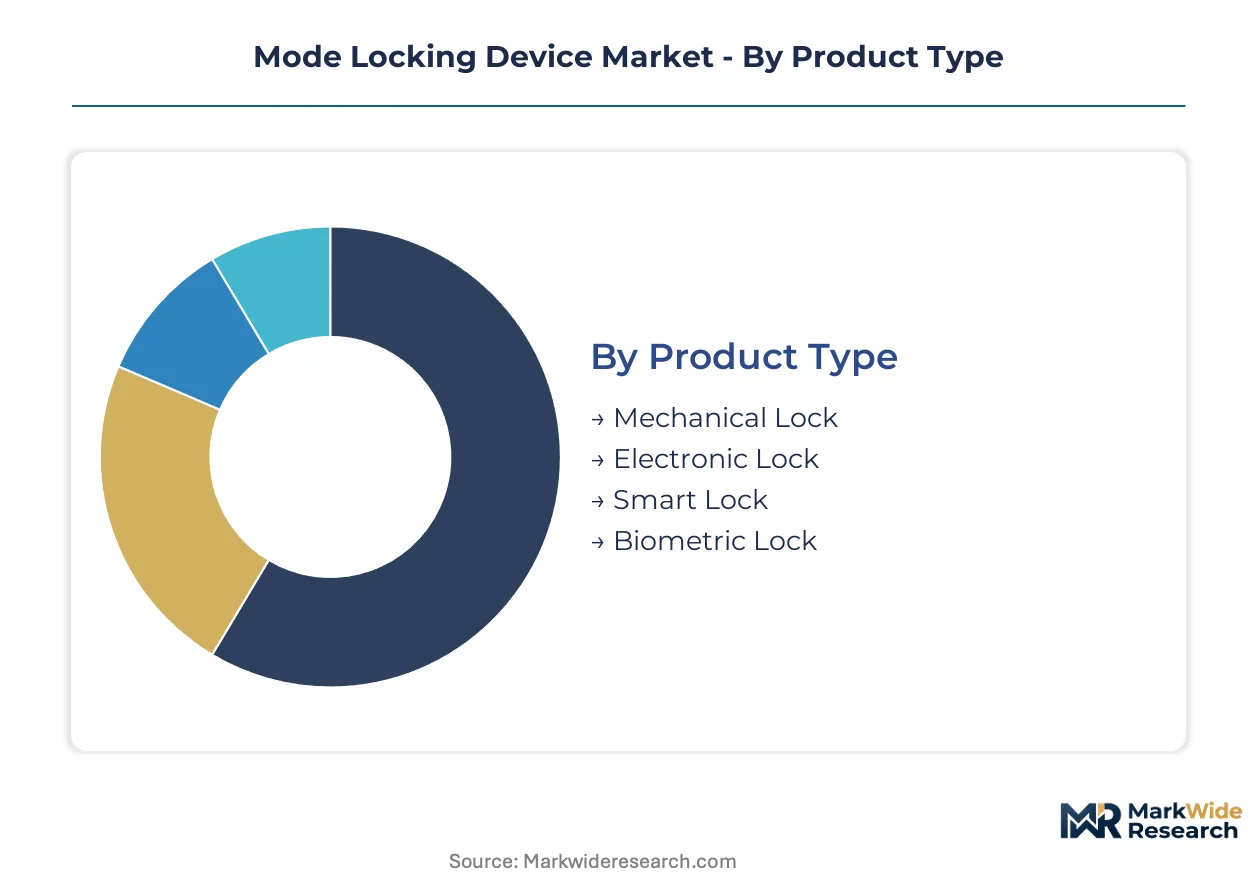
Mode locking device procurement patterns diverge sharply across product architectures and deployment environments. Supplier positioning and certification requirements vary by segment, forcing manufacturers to prioritize specific technical competencies over broad portfolio coverage.
Product Type:
Supply concentration in electro-optic crystal fabrication shapes competitive positioning across lock architectures, with semiconductor manufacturing complexity determining margin structures.
- Electronic Lock:These devices integrate active electro-optic modulators requiring precision-cut lithium niobate or KD*P crystals. Demand concentrates in German photonics manufacturing clusters around Munich, where FDA 510(k) documentation capabilities anchor medical laser system supply. Semiconductor fabrication complexity commands premium positioning against passive alternatives.
- Smart Lock:Embedded Bluetooth connectivity and IoT-enabled access control architectures represent the segment expanding most quickly. China's MIIT electromagnetic compatibility testing requirements are tightening certification timelines for European exporters targeting hospital and research facility deployment.
- Mechanical Lock:Bulk crystal saturable absorber configurations retain cost-sensitive industrial maintenance applications where electromagnetic interference precludes electronic solutions.
- Biometric Lock:Fingerprint and iris recognition integration with ultrafast laser systems remains nascent, concentrated in high-security government laboratory installations.
Today's leader: Electronic Lock. Tomorrow's challenger: Smart Lock.
Application:
Cost tier differentiation separates precision manufacturing requirements from maintenance-grade deployments, with certification documentation burdens scaling directly with application criticality.
- Industrial:Femtosecond-class pulse stability requirements dominate semiconductor lithography and medical device fabrication, compressing supplier qualification timelines. Sub-7nm mask inspection systems in Taiwan and South Korea foundries drive oscillator deployment in capital equipment.
- Commercial:IoT-enabled access control penetration in office buildings and retail facilities is pulling demand toward wireless-connected architectures. Building automation integrators in Japan prioritize electromagnetic compatibility pre-certification.
- Government:Defense and geodesy applications through quantum sensing convergence with atomic interferometers operate outside traditional industrial laser procurement channels.
- Residential:Cost constraints limit deployment to hobbyist and educational laser kit markets, with minimal mode locking device integration.
Industrial applications command current revenue concentration. Commercial deployment shows steepest expansion trajectory.
Connectivity:
Volume distribution across wired and wireless architectures reflects end-user technical sophistication and electromagnetic environment constraints.
- Bluetooth:Low-energy protocols dominate smart lock architectures in commercial building access control, with China's MIIT standards mandating additional GB certification layers for imported equipment.
- Wireless:Proprietary RF and cellular backhaul configurations serve remote industrial monitoring applications where fiber infrastructure is absent.
- Wired:Fiber-coupled electro-optic modulator assemblies retain dominance in high-power laser systems where signal integrity cannot tolerate interference.
- Wi-Fi:IP-connected architectures face cybersecurity scrutiny as regulatory frameworks for IoT physical security devices mature across major economies.
Wired connectivity maintains technical performance leadership. Bluetooth architectures gain share fastest in commercial deployment.
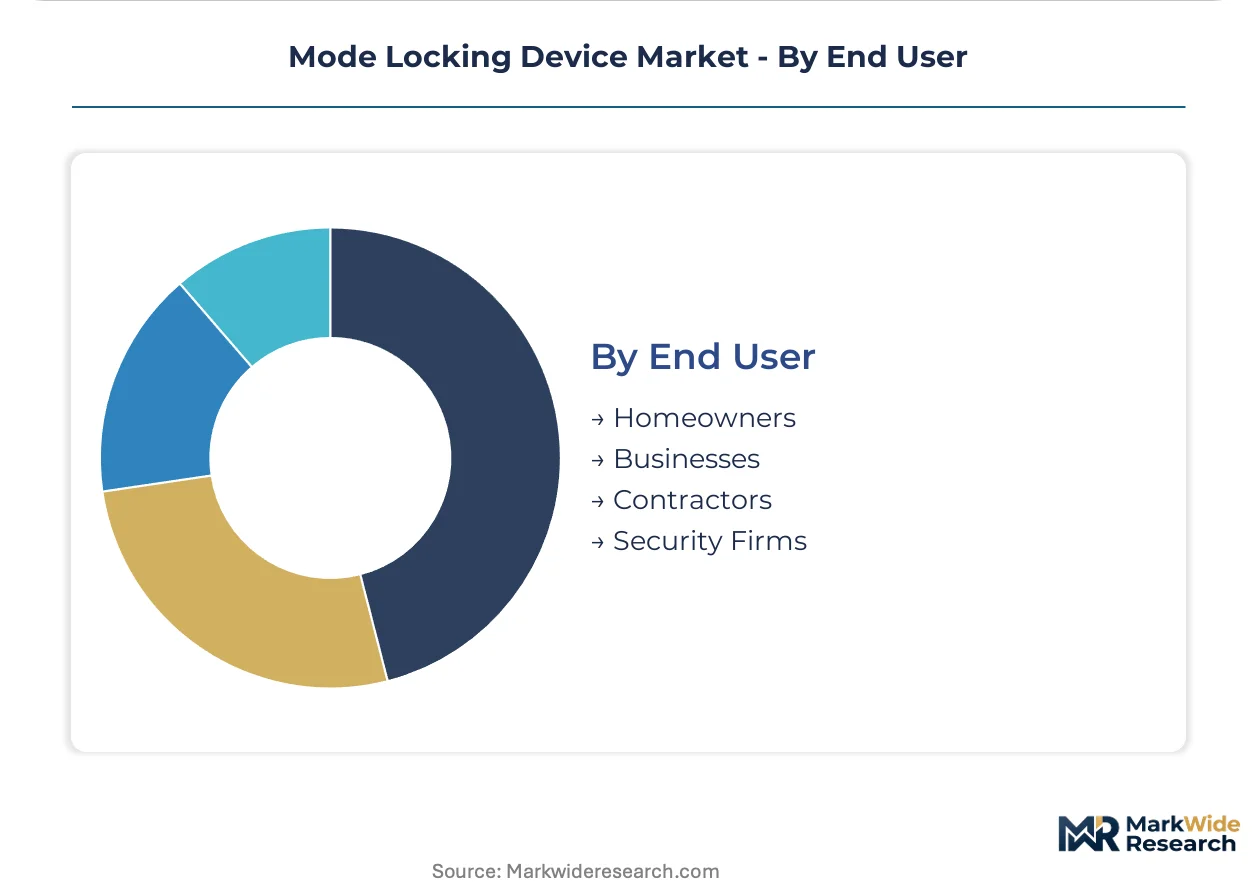
End User:
Customer type determines procurement channel structure, with direct manufacturer relationships displacing traditional systems integrator intermediation in specialized applications.
- Businesses:Semiconductor capital equipment firms are unbundling oscillator specification from full laser system procurement, creating direct component sourcing relationships. Japanese and South Korean systems integrators resist this disintermediation through proprietary control interfaces.
- Security Firms:Commercial building access control contractors prioritize pre-certified modules reducing field commissioning complexity.
- Contractors:Industrial maintenance providers favor mechanical lock variants for electromagnetic interference-prone environments.
- Homeowners:Minimal direct procurement; occasional participation in university and maker space collective purchasing.
Businesses drive specification autonomy trends. Security firms represent emerging consolidated demand channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting mode locking device assembly toward jurisdictions with streamlined certification pathways. China's MIIT standards and India's PLI incentives now attract foreign capital that previously concentrated in German precision engineering clusters.
United States
Semiconductor lithography capital equipment drives oscillator demand from foundries in Arizona and Texas. FDA 21 CFR 1040 laser product standards mandate exhaustive pulse stability documentation that extends supplier qualification timelines. Boston's photonics research corridor anchors biomedical imaging system development for multiphoton microscopy.
Germany
Precision disk laser pulse generation sustains captive R&D investment from industrial laser OEMs. CE marking under the EU Machinery Directive and RoHS substance restrictions constrain material selection for electro-optic modulator assemblies. Munich and Jena photonics manufacturing clusters concentrate ultrafast oscillator fabrication expertise.
China
Domestic foundry buildout for sub-7nm lithography systems expands local oscillator procurement. MIIT national laser safety standards and mandatory GB certification force foreign suppliers into local testing partnerships. Yangtze River Delta electronics corridors mature domestic supply chains for laser component assembly.
Japan
Systems integrators resist component disintermediation through proprietary control interfaces in EUV lithography supply chains. METI industrial standards govern high-power fiber laser integration requirements. Tokyo-Osaka manufacturing belts concentrate medical laser OEM qualification activity.
India
Production-linked incentive schemes for photonics manufacturing attract module assembly investments near Bengaluru's electronics corridor. Central government semiconductor mission programs accelerate domestic laser component ecosystem development. Tamil Nadu and Karnataka states compete for fab-adjacent photonics supplier anchoring.
Mode Locking Device Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system integrators defending proprietary interfaces against component unbundling trends. The vendor base concentrates around three strategic archetypes: vertically integrated laser OEMs with captive pulse generation units, independent oscillator specialists supplying across multiple system platforms, and emerging polymer-composite absorber fabricators decentralizing traditional crystal supply chains. Competitive moves center on backward integration into electro-optic crystal growth and geographic certification pre-qualification to accelerate hospital and research facility deployment.
Among German precision engineering fabricators, Trumpf exemplifies the vertically integrated OEM archetype through disk laser pulse generation capabilities. Coherent, Inc. and IPG Photonics occupy positions spanning independent oscillator supply and high-power fiber laser integration respectively. These three anchors represent divergent strategic postures on the spectrum between full-system control and component specialization.
| Leading Market Players |
|---|
| Coherent, Inc. |
| IPG Photonics |
| Spectra-Physics |
| TOPTICA Photonics |
| Menlo Systems |
| Amplitude Laser |
| Trumpf |
| Ekspla |
| Light Conversion |
| Others |
Pricing and Supply Chain Analysis
Carbon nanotube saturable absorber fabrication is decentralizing mode locking device production from traditional crystal growth facilities to polymer-composite processors, simultaneously compressing unit economics and fragmenting supplier concentration across specialty chemical manufacturers in Asia and North America.
Pricing Analysis
Distributor margins on electro-optic modulator assemblies range from 15-25% for standard industrial grades to 35-45% for medical-certified variants requiring FDA 510(k) documentation support. Three-tier pricing structure across premium, standard, and economy levels separates femtosecond-stability medical laser modules from maintenance-grade mechanical locks and cost-sensitive industrial replacements. Pricing pressure stems from SESAM displacement of bulk crystal mode lockers in high-volume fiber laser maintenance contracts. Semiconductor capital equipment buyers exhibit lowest price sensitivity due to unbundled oscillator procurement and qualification timeline penalties, while industrial maintenance contractors prioritize economy-tier mechanical alternatives.
Supply Chain Analysis
China's MIIT mandatory GB certification and India's PLI scheme for photonics manufacturing are reshaping sourcing patterns by incentivizing local assembly partnerships and domestic component qualification. Synthetic sapphire and YAG substrate fabrication concentrates in Ukrainian and Russian facilities, with electro-optic crystal growth anchored in German and Swiss technical centers. Raw material dependencies span rare-earth dopants for fiber laser integration, precision-cut lithium niobate for active modulators, and semiconductor saturable absorber mirror wafers. Single-source vulnerability in Ukrainian crystal supply exposes oscillator manufacturers to geopolitical disruption. Distribution runs through specialized photonics distributors serving academic and government laboratory channels, bypassing traditional systems integrators in direct-to-researcher procurement trends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mode locking device market functions as a regulatory compounder where China's MIIT laser safety standards and FDA 510(k) documentation requirements continuously elevate certification barriers that consolidate share among pre-qualified suppliers.
For Market Incumbents: Lock in electro-optic crystal supply through backward integration or long-term offtake agreements with Ukrainian and Russian substrate fabricators before geopolitical disruption accelerates. Capture certification investment returns by pre-qualifying modules to both FDA 21 CFR 1040 and MIIT GB standards during initial design phases, blocking European and Asian challengers from hospital and research facility deployment timelines.
For New Entrants and Emerging Players: Specialized distributors bypassing traditional systems integrators represent the most penetrable channel for carbon nanotube saturable absorber alternatives, particularly in German and Japanese ophthalmic imaging system qualification. Target India's PLI scheme for photonics manufacturing near Bengaluru's electronics corridor, where production-linked incentives offset capital equipment costs for module assembly investments. Lead with direct-to-researcher distribution partnerships capturing margin in academic procurement channels outside established OEM relationships.
For Investors and Strategic Acquirers: Roll-up economics work for independent oscillator specialists with FDA 510(k) documentation capabilities because medical laser system supply chains reward consolidated certification expertise over fragmented component sourcing. Five-to-ten year viability hinges on quantum sensing convergence with atomic interferometers opening defense and geodesy applications beyond traditional industrial markets. Watch carbon nanotube saturable absorber qualification timelines in German medical device OEMs as inflection indicator for polymer-composite supply chain decentralization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electro-Optic Crystal Growth | Captive lithium niobate supply secures margin against Ukrainian substrate disruption and German competitor consolidation. |
| Dual Certification Pre-Qualification (FDA/MIIT) | Simultaneous FDA 510(k) and GB certification accelerates hospital deployment in US and China markets. |
| Carbon Nanotube Absorber Platform Launch | Polymer-composite fabrication decentralizes supply from traditional crystal manufacturers to chemical processors. |
| Direct-to-Researcher Distribution Partnership | Bypassing Japanese and South Korean systems integrators captures margin in academic multiphoton microscopy procurement. |
| India PLI Scheme Module Assembly Investment | Bengaluru electronics corridor positioning leverages production-linked incentives for photonics manufacturing scale. |
Research Methodology
Multiple input streams — primary interviews with ultrafast laser system engineers, biomedical imaging procurement managers, and semiconductor capital equipment buyers; secondary validation through FDA 510(k) submission databases, MIIT GB certification registries, and photonics trade association shipment data; plus customs records for electro-optic crystal imports — were reconciled through bottom-up and top-down triangulation across the analysis window.
Data-stream reconciliation anchored volume and value outputs to modeled segmentation across product architecture (electronic, smart, mechanical, biometric lock types), application criticality (industrial, commercial, government, residential), and connectivity protocol (Bluetooth, wireless, wired, Wi-Fi). CAGRs were derived from fitted growth curves incorporating foundry capital equipment procurement cycles, university research budget allocation patterns, and IoT building automation penetration trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Ukrainian crystal supply disruption, MIIT standard evolution, and carbon nanotube absorber qualification velocity in medical device OEMs. A small set of named triggers — geopolitical input disruption, regulatory framework maturation for IoT physical security devices, and quantum sensing application commercialization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
US Access Control Market