
 Europe Access Control Software Market | 2026-2036
Europe Access Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Access Control Software Market Insights
The pricing and capability gap between premium biometric platforms and commodity card-based systems is shifting as enterprise buyers demand cloud-native architectures with GDPR-compliant audit trails. Bosch Security and Safety Systems leverages its hardware-software integration to anchor large commercial deployments across German industrial parks. Johnson Controls competes through building-automation convergence, while Genetec Inc. specializes in unified security platforms that merge access control with video analytics.
Europe access control software encompasses credential management, identity verification, and permission orchestration systems that govern physical entry points through biometric templates, encrypted mobile tokens, or PIN matrices, typically operating via IP-connected controllers with millisecond response thresholds. The primary commercial purpose is to enforce least-privilege access while generating tamper-evident audit streams for regulatory compliance. Cloud-based solutions now lead technology adoption as facilities managers prioritize remote provisioning and subscription economics over capital-intensive on-premises servers. Mobile access solutions represent the fastest-growing product type, displacing legacy card credentials in premium commercial buildings where smartphone ubiquity reduces replacement costs.
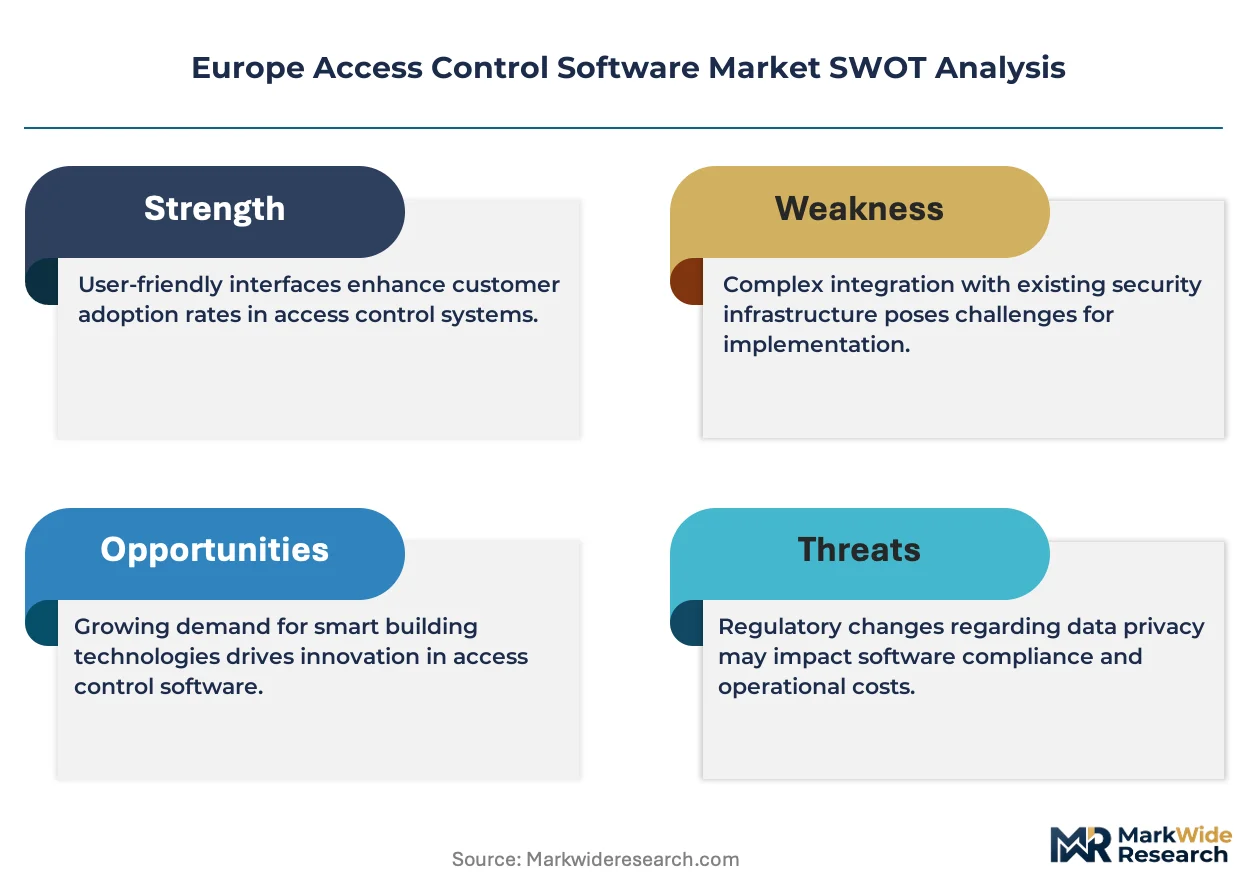
GDPR, the EU AI Act, and CE marking under the Radio Equipment Directive shape product development timelines and data-handling architectures for vendors serving European buyers. EMA guidelines on data integrity and national data-protection authorities in France and Germany enforce strict localization requirements for biometric storage. Stakeholders must monitor evolving harmonized standards under the Cyber Resilience Act as firmware update mandates and vulnerability disclosure rules redefine software lifecycle obligations.
Market Dynamics
GDPR and the EU AI Act are compressing product development timelines while forcing vendors to re-architect data-handling pipelines for biometric storage localization, creating a compliance moat that favors established players with dedicated European legal infrastructure.
Growth Catalysts
- Smart building retrofit mandates:France's RE2020 environmental regulation and Germany's Building Energy Act are accelerating IP-connected controller deployments in commercial real estate portfolios.
- Mobile credential standardization:Bluetooth Low Energy and NFC protocols embedded in smartphones are eliminating physical card replacement logistics for facility managers.
- EMA data integrity guidelines:Pharmaceutical manufacturing sites across the Netherlands and Ireland are upgrading access audit trails to meet serialized tamper-evident logging requirements.
Market Restraints
- Semiconductor controller shortages:IP-connected door controllers rely on specialized microcontrollers concentrated in Taiwanese fabrication capacity, creating 16-24 week lead time volatility.
- Biometric template storage costs:GDPR Article 9 sensitive data classification requires encrypted edge storage or sovereign cloud instances, adding 30-40% infrastructure overhead versus card-based systems.
- Legacy Wiegand protocol entrenchment:Decades of installed card readers using unencrypted two-wire communication create technical debt that slows encrypted OSDP migration.
Strategic Opportunities
- Eastern European greenfield deployment:Poland and Romania commercial construction pipelines lack legacy system burden, enabling cloud-native architecture from inception.
- Healthcare vertical convergence:Hospital identity verification systems are merging physical access with medical device authentication under single credential platforms.
- Cyber Resilience Act preparation:Vendors that pre-position automated firmware update capabilities and SBOM documentation will capture procurement preference as 2027 enforcement deadlines approach.
Industry Challenges
- Embedded systems security engineering scarcity:Firmware developers with hardware-software co-design expertise for secure element integration command premium compensation and extended recruitment cycles.
- Multi-jurisdiction certification stacking:CE marking under RED, GDPR DPIA requirements, and national data protection authority pre-consultations in Germany and France create sequential approval bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Access Control Software Market |
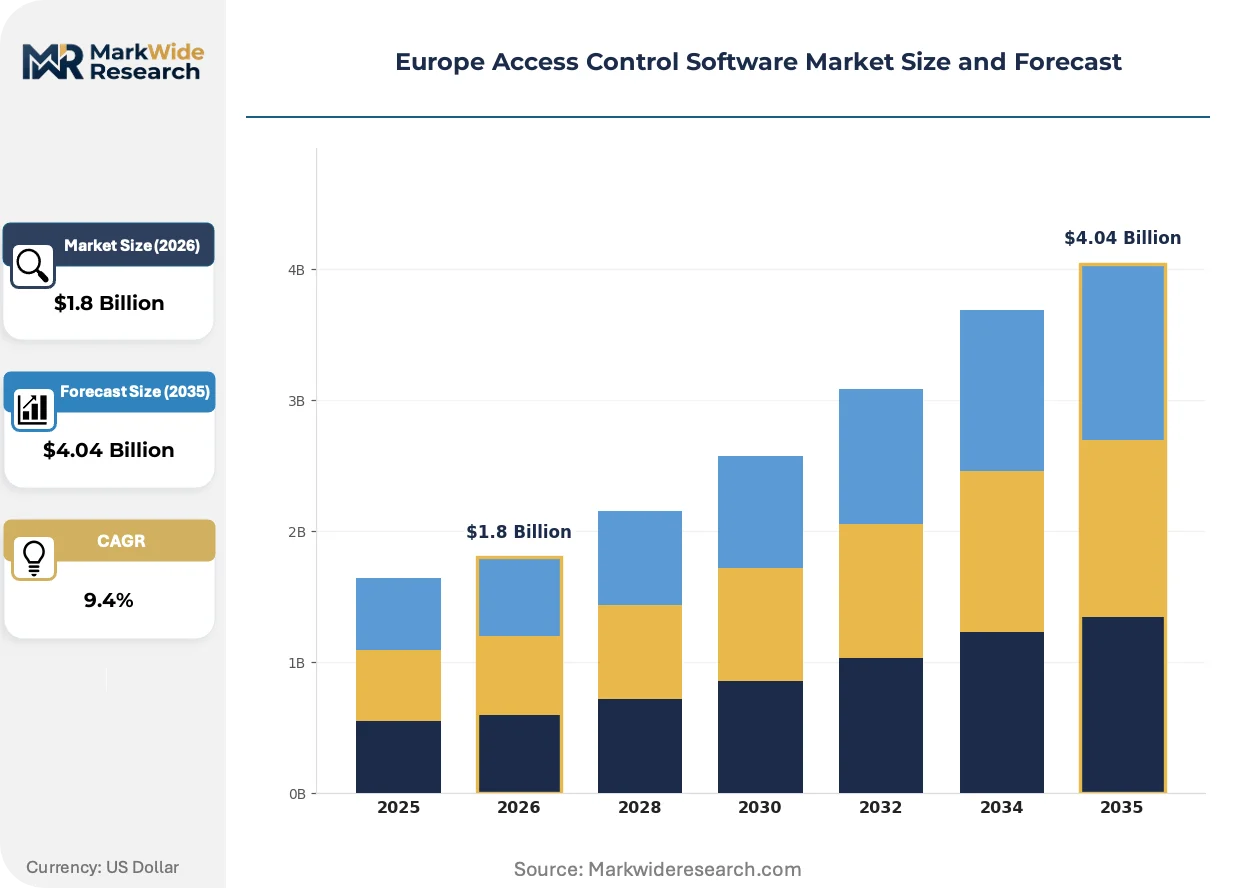
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Card-Based Systems, Keypad Systems, Mobile Access Solutions End User: Commercial Buildings, Residential Properties, Government Institutions, Educational Facilities Technology: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Mobile Authentication Deployment: Remote Access, Centralized Access, Decentralized Access, Wireless Access |
| Companies Covered | Bosch Security and Safety Systems, Johnson Controls, Genetec Inc., Nedap N.V., Honeywell International Inc., Axis Communications AB, Thales Group, IDEMIA, Fujitsu, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Access Control Software Market Trends and Innovations
Cloud-native access control architectures are compressing the traditional on-premises server replacement cycle while enabling subscription revenue models that reshape vendor-customer relationships across European facilities management.
Facial recognition templates with liveness detection are expanding into high-throughput commercial lobbies where frictionless entry replaces card-tap bottlenecks. Premium office developments in London and Amsterdam are deploying these systems for 500+ person morning ingress peaks. The technology is expanding into visitor management workflows that previously required staffed reception desks.
The EU AI Act's risk classification framework is forcing biometric vendors to re-engineer algorithmic transparency features and human-in-the-loop override mechanisms. High-risk system designations for real-time remote biometric identification in publicly accessible spaces are redirecting R&D investment toward privacy-preserving edge processing. French CNIL and German data protection authorities are interpreting these provisions with particular stringency for public sector deployments.
Facilities managers are consolidating security vendor relationships around unified platforms that merge access control with video management and intrusion detection. German industrial park operators and Dutch logistics hubs are prioritizing single-pane-of-glass procurement to reduce integration complexity and training overhead. This preference shift disadvantages point-solution specialists and rewards platform vendors with native API ecosystems.
Europe Access Control Software Market Segmentation
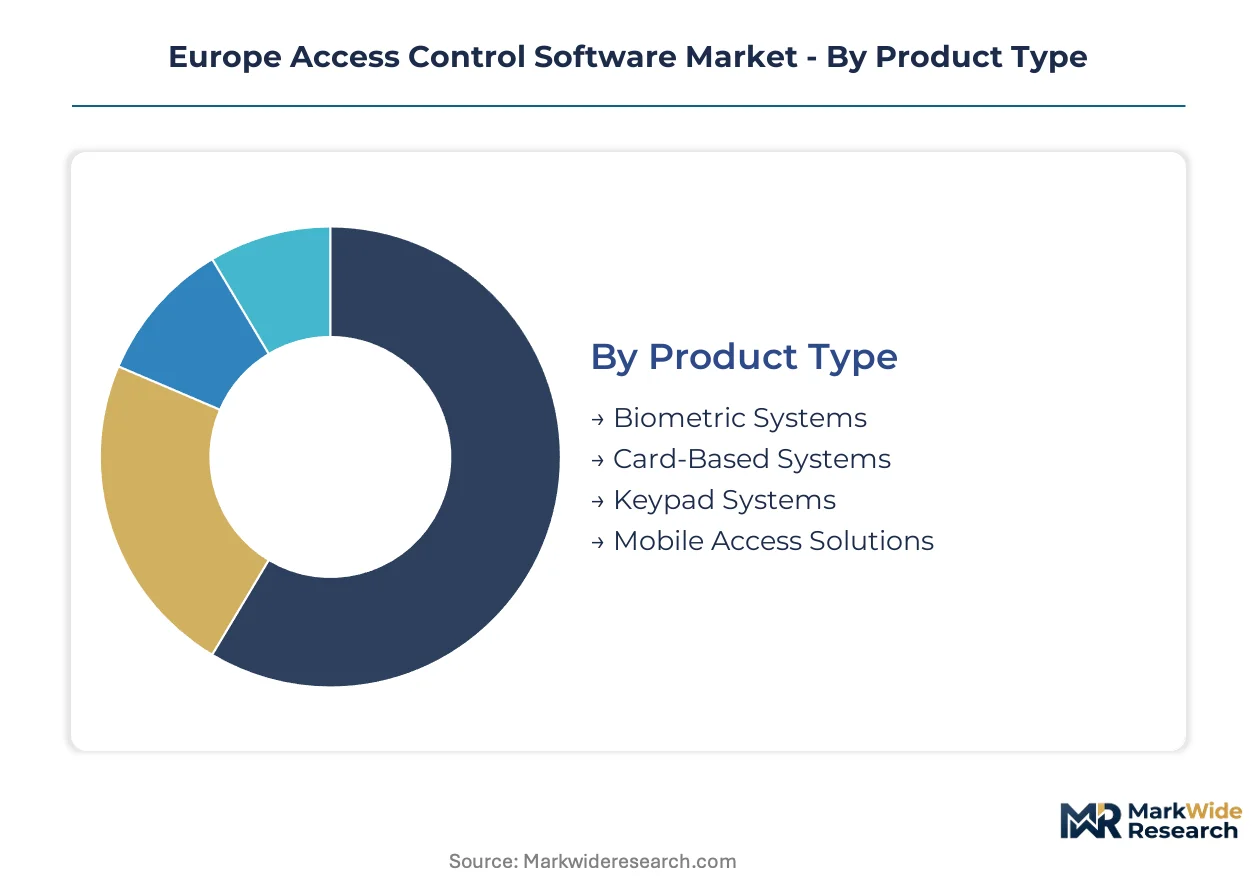
Segmentation in Europe access control software reveals how compliance architecture and procurement patterns fragment across credential technologies, end-use verticals, and deployment topologies. Understanding these divisions exposes where GDPR localization requirements and cloud migration timelines create divergent growth trajectories.
Product Type:
Supply concentration in facial recognition algorithms and secure element manufacturing tilts competitive advantage toward vendors with captive biometric R&D or hardware-software integration capabilities.
- Biometric Systems:Facial recognition, fingerprint, and iris templates with liveness detection operate at millisecond response thresholds for high-throughput commercial lobbies. German industrial parks and Dutch logistics hubs are concentrating demand here, driven by frictionless entry requirements for 500+ person morning ingress peaks and GDPR Article 9 compliance overhead that favors established vendors with dedicated European legal infrastructure.
- Mobile Access Solutions:Bluetooth Low Energy and NFC protocols embedded in smartphones eliminate physical card replacement logistics through encrypted digital credentials. Premium office developments in London and Amsterdam are displacing legacy card systems fastest here, as smartphone ubiquity reduces replacement costs and facilities managers prioritize remote provisioning capabilities.
- Card-Based Systems:Legacy 125kHz proximity and 13.56MHz smart card credentials dominate installed base across French and British commercial real estate.
- Keypad Systems:PIN matrices persist in cost-sensitive residential and small commercial deployments where credential management overhead outweighs security requirements.
Today's leader: Biometric Systems. Tomorrow's challenger: Mobile Access Solutions.
End User:
Cost tier stratification separates premium compliance-driven buyers from price-sensitive segments, with regulatory intensity determining margin architecture across verticals.
- Commercial Buildings:Smart building retrofit mandates under France's RE2020 and Germany's Building Energy Act are accelerating IP-connected controller deployments. Corporate headquarters and financial services clusters in Frankfurt, Paris, and Amsterdam are concentrating demand for unified platforms that merge access control with video analytics and building automation systems.
- Government Institutions:High-security facilities require tamper-evident audit trails and sovereign cloud storage for biometric templates under national data protection authority oversight. German federal and state procurement is particularly stringent on CNIL-equivalent pre-consultation requirements for public sector biometric deployment.
- Educational Facilities:Campus-wide credential platforms serve mixed-use environments across universities in the Netherlands and United Kingdom.
- Residential Properties:Multi-tenant housing and gated communities prioritize cost-efficient mobile credential adoption over biometric infrastructure.
Commercial Buildings capture current revenue concentration. Government Institutions face the steepest compliance-driven expansion trajectory.
Technology:
Volume distribution across deployment models reflects facilities managers' risk tolerance for subscription economics versus capital retention and data sovereignty concerns.
- Cloud-Based Solutions:Remote provisioning, automated firmware updates, and subscription revenue models compress traditional on-premises server replacement cycles. Facilities managers across European commercial real estate portfolios are prioritizing these architectures for multi-site credential orchestration and reduced IT infrastructure overhead.
- Hybrid Solutions:Edge processing with cloud analytics balances GDPR data localization requirements against centralized management needs. Pharmaceutical manufacturing sites in Ireland and the Netherlands are deploying these architectures to meet EMA data integrity guidelines on serialized tamper-evident logging.
- On-Premises Solutions:Air-gapped deployments persist in defense and critical infrastructure where network connectivity risks outweigh operational convenience.
- Mobile Authentication:Smartphone-native credential verification represents the fastest-climbing adoption curve as Bluetooth and NFC standardization eliminates proprietary hardware dependencies.
Cloud-Based Solutions dominate new procurement. Hybrid Solutions are gaining share fastest among regulated verticals.
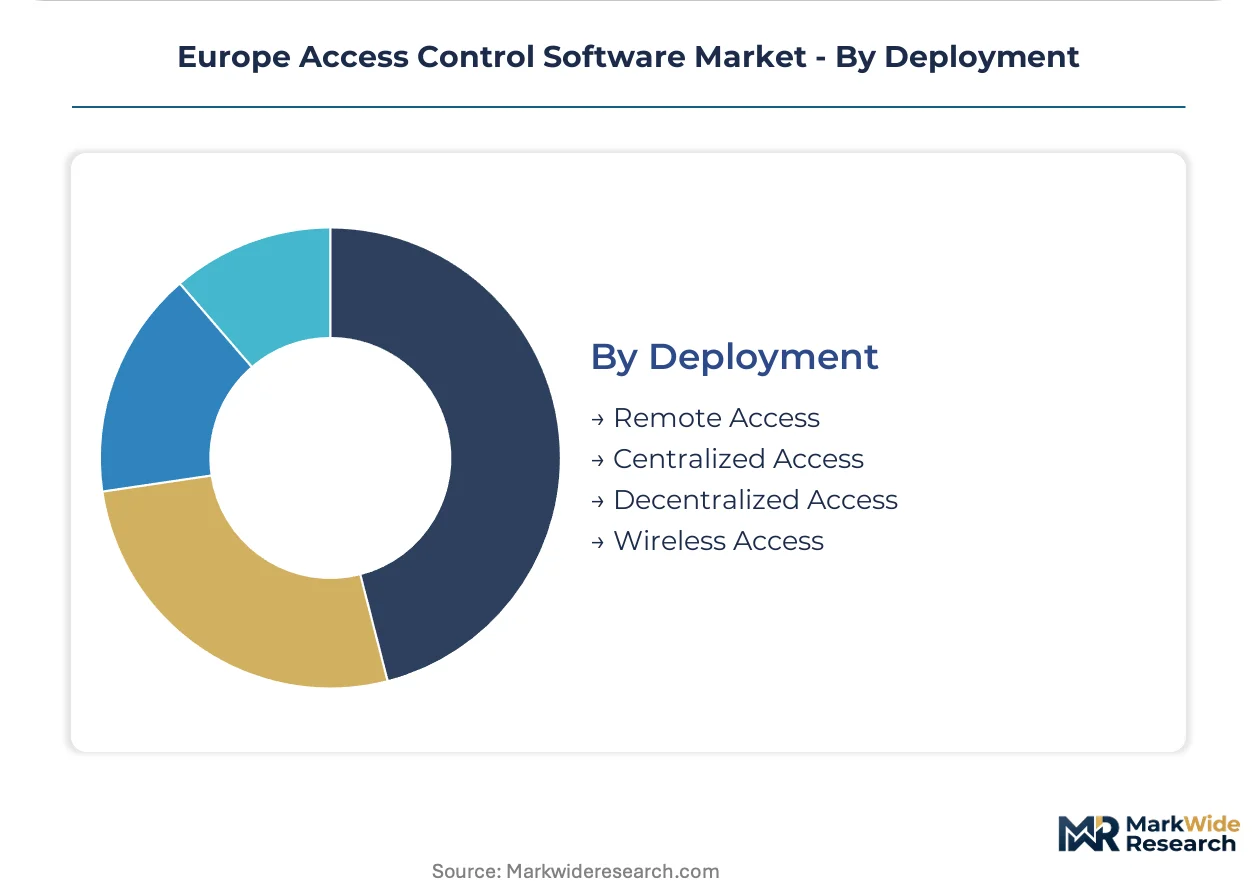
Deployment:
Customer type differentiation separates enterprise multi-site operators seeking centralized governance from distributed facilities requiring local autonomy.
- Centralized Access:Single-pane-of-glass management across geographically dispersed facilities reduces integration complexity and training overhead. German industrial park operators and pan-European logistics chains are consolidating vendor relationships around these architectures to enforce consistent credential policies.
- Decentralized Access:Autonomous site-level controllers with intermittent cloud synchronization serve locations with unreliable connectivity or strict data residency requirements. Eastern European greenfield deployments in Poland and Romania are adopting these architectures to avoid legacy system burden.
- Remote Access:VPN-secured credential provisioning and audit retrieval supports distributed workforces and managed service provider delivery models.
- Wireless Access:Battery-powered controllers and WiFi-enabled locks reduce installation costs in retrofit environments where cabling infrastructure is prohibitive.
Centralized Access anchors enterprise procurement. Decentralized Access is expanding most quickly in greenfield European construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in biometric deployment velocity, while the United Kingdom accelerates cloud-native procurement faster than either continental neighbor. Dutch logistics hubs and Irish pharmaceutical clusters are emerging as distinct demand poles with specialized compliance requirements.
Germany
Industrial park operators and automotive manufacturing clusters drive demand for unified access-video platforms. The Federal Data Protection Act and BSI technical guidelines enforce strict biometric template localization for federal procurement. Frankfurt's financial district and Stuttgart's manufacturing belt are concentrating high-throughput facial recognition deployments for 500+ employee morning ingress.
United Kingdom
London's premium office developments and Cambridge technology parks prioritize mobile credential solutions over legacy card systems. The Information Commissioner's Office biometric guidance and post-Brexit data adequacy arrangements shape vendor selection criteria. Manchester and Birmingham commercial real estate portfolios are consolidating around subscription-based cloud architectures for multi-site management.
France
Smart building retrofits under RE2020 environmental regulations accelerate IP-connected controller installations across Paris and Lyon commercial districts. CNIL pre-consultation requirements for public sector biometric deployment create sequential approval bottlenecks. The Île-de-France region concentrates demand for visitor management systems that replace staffed reception desks in premium developments.
Netherlands
Rotterdam and Amsterdam logistics hubs drive demand for centralized access management across geographically dispersed facilities. EMA data integrity guidelines enforce serialized tamper-evident logging for pharmaceutical manufacturing sites in Oss and Leiden. The Randstad urban corridor is adopting frictionless entry systems for high-throughput distribution centers.
Ireland
Pharmaceutical manufacturing clusters in Cork and Dublin prioritize hybrid cloud-edge architectures for GDPR-compliant audit trails. The Data Protection Commission's enforcement posture on biometric sensitive data classification adds infrastructure overhead that favors established vendors. Greenfield data center developments are deploying air-gapped on-premises solutions where network connectivity risks outweigh operational convenience.
Europe Access Control Software Market Competitive Landscape
Top-tier vendors anchor enterprise and government procurement, while mid-tier specialists occupy vertical niches and regional service markets. The vendor base stratifies across three tiers: integrated security conglomerates with captive hardware-software stacks, unified platform specialists converging access control with video analytics, and point-solution providers serving cost-sensitive retrofit segments. Dominant competitive moves include M&A activity to capture cloud-native capabilities and strategic partnerships with smart building automation vendors.
Within the integrated conglomerate tier, Bosch Security and Safety Systems and Johnson Controls exemplify hardware-software integration strategies that anchor large commercial deployments. Genetec Inc. occupies a distinct position among unified platform specialists, representing the convergence archetype that merges access control with video management and intrusion detection through native API ecosystems.
| Leading Market Players |
|---|
| Bosch Security and Safety Systems |
| Johnson Controls |
| Genetec Inc. |
| Nedap N.V. |
| Honeywell International Inc. |
| Axis Communications AB |
| Thales Group |
| IDEMIA |
| Fujitsu |
| Others |
Pricing and Supply Chain Analysis
Microcontroller unit pricing indices from Taiwanese foundries cascade through three-tier pricing structures across premium biometric, standard mobile-credential, and economy card-based access control tiers, compressing margins for European systems integrators while amplifying procurement power for cloud-native platform buyers.
Pricing Analysis
Capacity additions in Southeast Asian secure element manufacturing are reshaping price floors for biometric template storage modules, forcing GDPR-compliant edge processing premiums upward. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance intensity, with pharmaceutical and government verticals absorbing certification-grade premiums while retail and residential segments drive cost compression. Pricing pressure stems from semiconductor controller scarcity, with facilities managers in German industrial parks and Dutch logistics hubs negotiating longer-term subscription contracts to lock in SaaS-tiered rates against hardware volatility.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from pan-European logistics chains and German automotive clusters, while value-added distributors serve mid-market retrofit installations across French and British commercial real estate. Manufacturing concentration rests on Taiwanese microcontroller fabrication, Chinese secure element production, and German IP-connected controller assembly. Raw material dependencies include silicon wafers, Bluetooth Low Energy chipsets, and cryptographic hardware security modules. Single-source vulnerability around Taiwanese foundry capacity creates procurement risk that vendors mitigate through dual-sourcing arrangements and inventory pre-positioning for GDPR-mandated biometric storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe access control software market functions as a regulatory compounder, where the EU AI Act's 2027 enforcement deadline for high-risk biometric systems generates procurement urgency that outpaces organic replacement cycles.
For Market Incumbents: Acquire cloud-native firmware update capabilities to pre-position against Cyber Resilience Act mandates. Consolidate around unified platform architectures that merge access control with video analytics, neutralizing point-solution specialists. Deepen backward integration into secure element manufacturing to reduce exposure to Taiwanese foundry bottlenecks and capture margin from GDPR-compliant biometric storage premiums.
For New Entrants and Emerging Players: Smart building automation vendors represent the most accessible channel partnership vector for cloud-native access control modules. Target Eastern European greenfield deployments in Poland and Romania where legacy Wiegand protocol entrenchment is minimal. Penetrate healthcare vertical convergence opportunities by positioning smartphone-native credentials for merged physical access and medical device authentication workflows.
For Investors and Strategic Acquirers: Asymmetric upside sits with unified platform specialists possessing native API ecosystems and video management convergence capabilities. Five-to-ten-year viability favors vendors with pre-established GDPR legal infrastructure and CNIL-equivalent regulatory relationships. Monitor EMA data integrity guideline enforcement intensity across Dutch and Irish pharmaceutical clusters as a demand inflection signal for hybrid cloud-edge architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription revenue models compress capital-intensive on-premises server replacement cycles for facilities managers. |
| Biometric Edge Processing Investment | GDPR Article 9 compliance overhead favors vendors with sovereign cloud instances and encrypted local storage. |
| Smart Building Automation Partnership | Johnson Controls and Bosch leverage building-automation convergence to anchor German industrial park deployments. |
| Mobile Credential Standardization | Bluetooth Low Energy and NFC protocols eliminate proprietary hardware dependencies in London and Amsterdam premium developments. |
| Cyber Resilience Act Preparation | Automated firmware update capabilities and SBOM documentation capture procurement preference ahead of enforcement deadlines. |
Research Methodology
Bottom-up facilities management modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with security systems integrators, facilities management directors, IT procurement officers, and smart building automation engineers combined with secondary validation against EMA data integrity guidelines, CNIL biometric deployment advisories, and BSI technical standards. Customs records for IP-connected controller imports, SEC filings from listed security conglomerates, and RE2020 environmental regulation compliance databases provided supply-side triangulation points.
Input-output matrices mapped credential technology adoption against deployment topology preferences and vertical compliance intensity across the projection horizon. Segmentation dimensions modeled include product type, end-use vertical, technology deployment model, and customer scale tier. CAGRs were derived from elasticity-adjusted replacement cycle analysis and regulatory mandate acceleration effects. Forecast inputs incorporated smart building retrofit permit data from French and German regulatory filings and pharmaceutical manufacturing site audit trail upgrade announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act interpretation variance across national data protection authorities and Taiwanese foundry capacity allocation shifts. Forecasts reflect documented assumptions regarding GDPR enforcement consistency and mobile credential standardization velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Border Security System Market
Access Control Systems
Access Control Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Car Security System Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Keyless Entry System Market