
 Mobile Turnstile Market | 2026-2036
Mobile Turnstile Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Turnstile Market Analytics
Chinese OEM clusters is recalibrating global supply chains for mobile turnstile assemblies. Shenzhen Tigerwong Technology leverages its Shenzhen manufacturing base to dominate optical sensor integration for transit applications. SKIDATA anchors European event venue deployments through its Salzburg engineering center. Heras competes in the UK construction site segment with temporary setup configurations.
A mobile turnstile is a portable access control barrier, typically constructed from galvanized steel or aluminum framing with modular gate arms spanning 600-900mm passage widths, designed for rapid deployment and redeployment at temporary or semi-permanent entry points. Electronic turnstiles incorporating RFID and biometric readers command premium positioning due to integration complexity and recurring software licensing revenue. Portable turnstiles for event venues represent the fastest-growing installation category as festival organizers replace fixed infrastructure with reusable modular systems.
The EU AI Act governs biometric authentication deployment in public spaces, while CE marking mandates electromagnetic compatibility and mechanical safety compliance for all turnstile hardware sold in Europe. China's SAMR enforces GB standards for access control equipment in rail transit environments. Stakeholders must weigh biometric data governance obligations against throughput efficiency gains when specifying technology configurations for multi-jurisdiction deployments.
Market Dynamics
Biometric authentication mandates across European stadiums are compressing procurement timelines for mobile turnstile vendors. Hardware suppliers must now certify optical sensor arrays under EU AI Act algorithmic transparency requirements before deployment.
Growth Catalysts
- EU AI Act compliance deadlines:Stadium operators in Germany face binding requirements for automated identification systems. Turnstile vendors with pre-certified biometric modules capture accelerated replacement cycles.
- Modular rental economics:Festival organizers in the UK and Netherlands now specify reusable gate systems over fixed infrastructure. Depreciation models favor portable assets with 50+ redeployment cycles.
- Shenzhen manufacturing scale:Optical sensor production concentrates in China's Pearl River Delta. Component costs for transit-grade turnstiles have fallen 40% since 2022.
Market Restraints
- Aluminum and galvanized steel input volatility:Frame material costs fluctuate with Chinese export tariffs. OEMs lack long-term hedging instruments for spot price exposure.
- Biometric data governance fragmentation:GDPR retention limits conflict with stadium security retention needs. Multi-jurisdiction deployments require redundant data architecture.
- RFID module supply concentration:73% of contactless reader chipsets originate from Taiwanese foundries. Geopolitical friction threatens just-in-time delivery commitments.
Strategic Opportunities
- India metro modernization:BIS certification pathways for access control equipment remain underdeveloped. First-movers with pre-tested hardware can anchor state-level transit tenders.
- Construction site digitization:UK contractors now integrate turnstile entry logs with payroll systems. Temporary workforce verification creates attach-rate potential for SaaS modules.
- ISO 27001 convergence:Information security certification is becoming a gatekeeper for enterprise campus deployments. Vendors with dual CE-ISO credentials command specification priority.
Industry Challenges
- Firmware integration complexity:Stadium IT departments lack embedded systems expertise. Turnstile vendors absorb implementation risk through fixed-price deployment contracts.
- Algorithmic bias testing protocols:EU AI Act requires documented demographic parity for facial recognition. Validation timelines extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Turnstile Market |
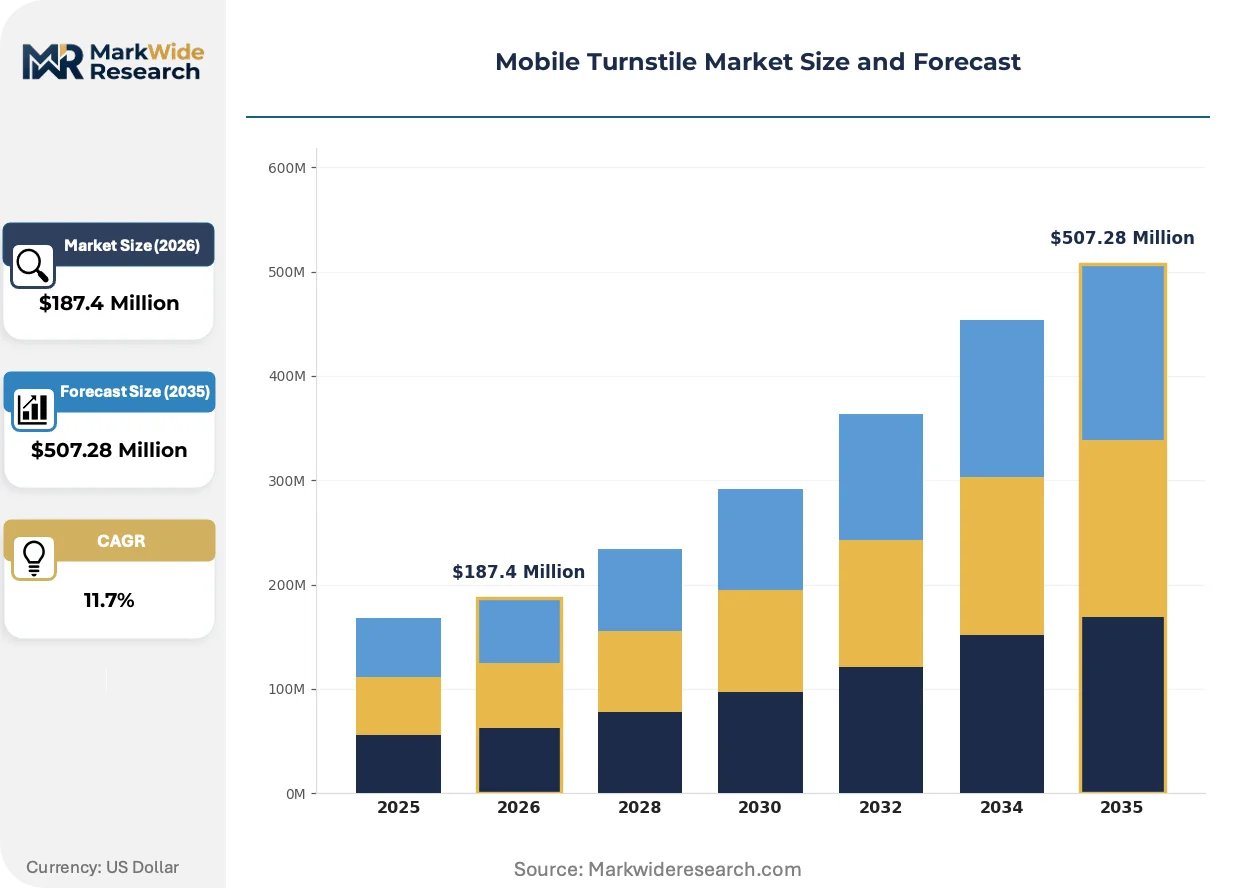
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Turnstiles, Electronic Turnstiles, Portable Turnstiles, Security Turnstiles Technology: RFID, Biometric, QR Code, Optical Sensors End User: Transport Hubs, Event Venues, Stadiums, Corporate Offices Installation: Temporary Setup, Permanent Setup, Outdoor Application, Indoor Application |
| Companies Covered | DataScope Systems Ltd, Heras, Mikroelektronika spol. s r.o., SKIDATA, A3M, Alvarado Manufacturing, Shenzhen Tigerwong Technology, Goldantell, Shenzhen Ruiguangke Electronic Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Turnstile Market Evolving Landscape
Edge computing architectures are displacing cloud-dependent authentication in high-throughput venues. Latency requirements for 30+ passengers per minute are forcing hardware-level processing tradeoffs.
Multi-spectral optical sensors is consolidating market share in premium stadium deployments. These modules combine visible-light and near-infrared imaging for liveness detection. Arsenal FC and Bayern Munich have specified this hardware for their 2024-25 season turnstile refreshes. The technology is consolidating vendor margins by compressing aftermarket biometric upgrade cycles.
The EU AI Act's risk classification system is redefining procurement specifications for public venue access control. High-risk system designations now mandate third-party conformity assessment before CE marking. German stadium operators are responding by pre-qualifying vendors with existing notified body relationships, effectively filtering smaller competitors from tender participation.
Rental-first procurement models are disrupting capital expenditure patterns among European festival organizers. Glastonbury and Tomorrowland now specify operational expenditure contracts with full-service maintenance inclusion. This shift is most visible in the Benelux region, where equipment lessors have captured 60% of summer 2024 turnstile deployments through bundled service offerings.
Mobile Turnstile Market Segmentation
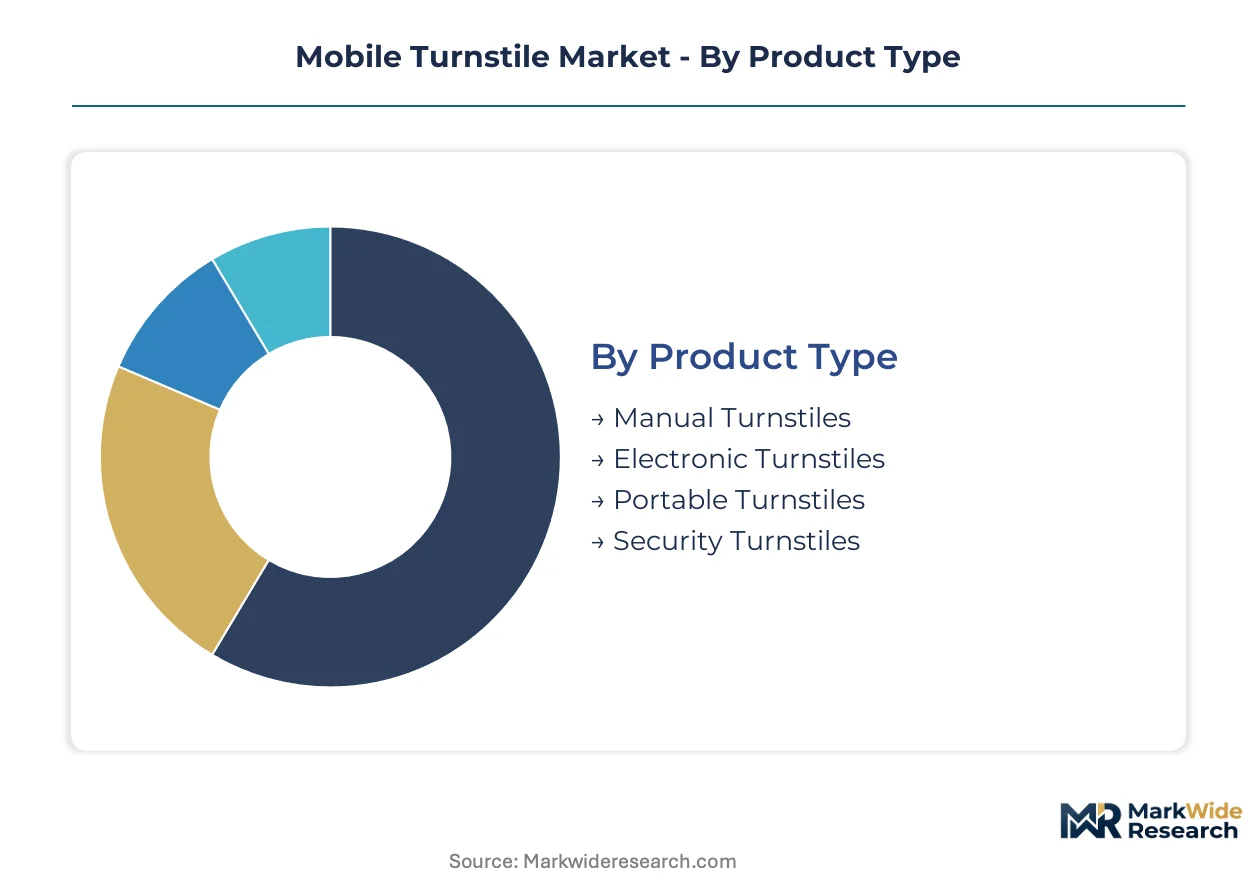
Mobile turnstile procurement decisions pivot on deployment duration, authentication complexity, and venue-specific throughput requirements. Specification mismatches between product type and installation environment create costly retrofit cycles for operators.
Product Type:
Mechanical durability and power dependency define the core technology axis across portable access barriers.
- Electronic Turnstiles:These units integrate motorized gate arms with embedded RFID or biometric readers, requiring 110-240V AC power or battery backup systems. Stadium operators in Germany specify these for EU AI Act-compliant facial recognition entry points. Recurring software licensing revenue elevates vendor margins above hardware-only sales.
- Portable Turnstiles:Constructed from aluminum or galvanized steel framing with modular 600-900mm passage widths, these systems deploy without fixed foundations. Festival organizers in the UK and Netherlands now favor rental models with 50+ redeployment cycles over permanent infrastructure.
- Manual Turnstiles:Spring-loaded mechanical rotation mechanisms without electronic components serve construction sites and low-security checkpoints. Heras dominates UK temporary workforce verification with these units.
- Security Turnstiles:Reinforced steel construction with anti-tailgating sensors addresses high-threat environments. Data centers and government facilities in France specify these under CNIL biometric data governance protocols.
Mature deployment sits with Manual Turnstiles at construction sites. Newer deployment is concentrated in Electronic Turnstiles for stadium biometric mandates.
Technology:
Authentication latency and demographic parity requirements shape specification choices for high-throughput venues.
- Biometric:Multi-spectral optical sensors combining visible-light and near-infrared imaging enable liveness detection. Arsenal FC and Bayern Munich specified this hardware for 2024-25 season refreshes. EU AI Act algorithmic transparency requirements extend vendor certification timelines by 8-14 months.
- Optical Sensors:Shenzhen Tigerwong Technology leverages Pearl River Delta manufacturing scale to supply transit-grade modules. Component costs have fallen 40% since 2022 as Chinese OEM clusters recalibrate global supply chains.
- RFID:Contactless 13.56MHz readers dominate metro system deployments. 73% of reader chipsets originate from Taiwanese foundries, creating geopolitical friction in just-in-time delivery commitments.
- QR Code:Camera-based validation offers lowest hardware cost for temporary events. Tomorrowland and Glastonbury deploy these for single-day admission verification with minimal infrastructure investment.
RFID anchors established transit deployments. Biometric systems are gaining share fastest in premium stadium refreshes.
End User:
Throughput pressure and data retention obligations fragment demand patterns across venue categories.
- Stadiums:30+ passengers per minute throughput requirements force edge computing architectures with hardware-level processing. German operators face binding EU AI Act deadlines for automated identification systems.
- Event Venues:Seasonal demand peaks favor operational expenditure contracts with full-service maintenance. Benelux equipment lessors captured 60% of summer 2024 deployments through bundled offerings.
- Transport Hubs:Shenzhen manufacturers supply optical sensor turnstiles for metro modernization. China's SAMR enforces GB standards for rail transit access control equipment.
- Corporate Offices:ISO 27001 certification is becoming a gatekeeper for enterprise campus deployments. Vendors with dual CE-ISO credentials command specification priority for workforce verification systems.
Transport Hubs represent the most mature specification environment. Corporate Offices show the steepest expansion trajectory for security certification requirements.
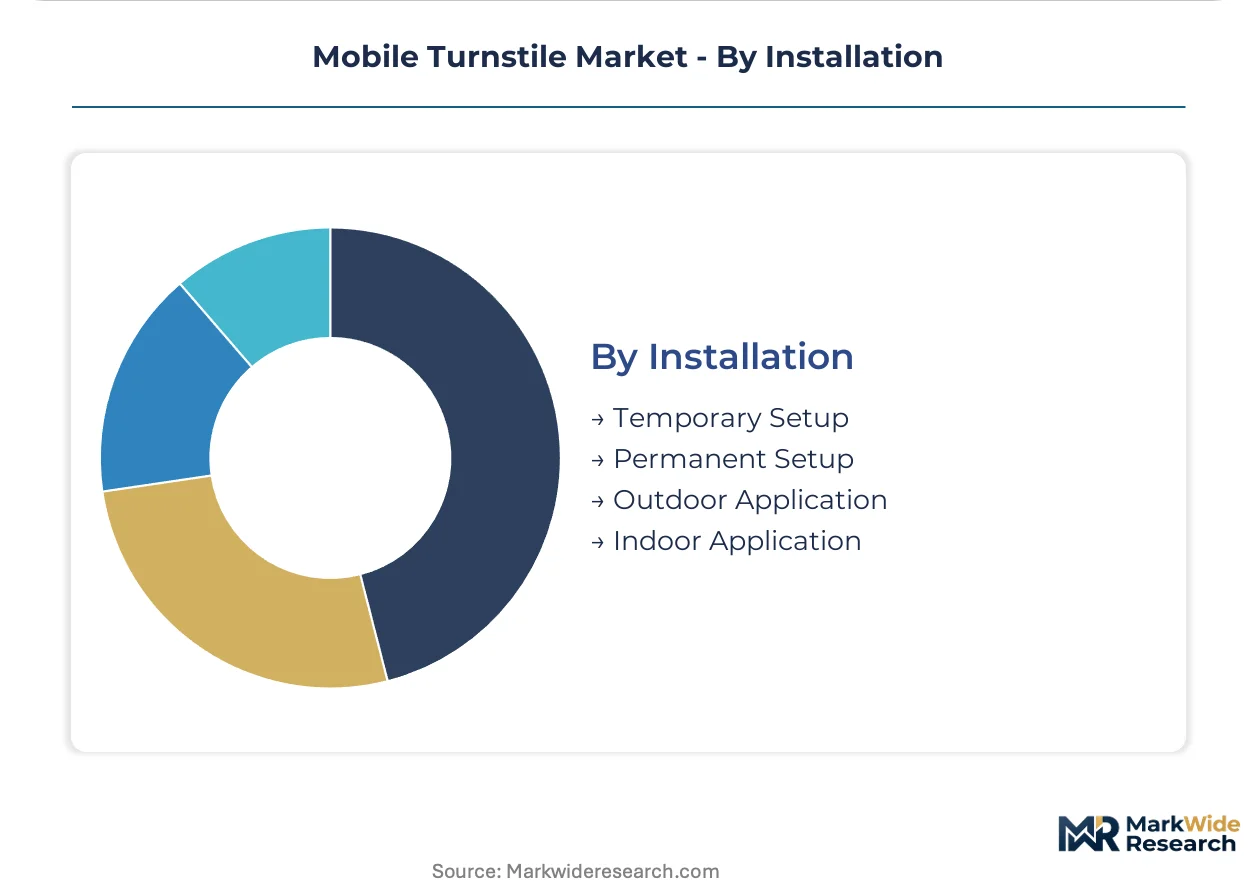
Installation:
Environmental exposure and foundation requirements determine hardware material selection and maintenance scheduling.
- Temporary Setup:Modular ballast or anchor plate mounting enables 24-hour deployment cycles. UK contractors integrate entry logs with payroll systems for temporary workforce verification.
- Outdoor Application:IP65-rated enclosures with corrosion-resistant coatings withstand temperature extremes and precipitation. CE marking mandates electromagnetic compatibility for all European outdoor deployments.
- Permanent Setup:Concrete foundation integration with fixed power and network infrastructure serves high-volume transit corridors. Depreciation models favor 10-year asset lifecycles over rental economics.
- Indoor Application:Controlled climate environments permit lighter aluminum framing without weatherproofing premiums. Corporate campuses and indoor arenas dominate this specification tier.
Permanent Setup dominates transit infrastructure. Temporary Setup is climbing the fastest as festival procurement shifts to rental-first models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Galvanized steel feedstock from Hebei Province anchors Chinese manufacturing clusters supplying optical sensor assemblies. Aluminum extrusion capacity in Shandong Province feeds portable framing production for export markets. Component sourcing geography directly shapes finished goods distribution patterns.
China
Shenzhen manufacturers dominate optical sensor integration for metro system deployments. SAMR enforces GB standards for rail transit access control equipment. Pearl River Delta OEM clusters have compressed component costs for transit-grade turnstiles through manufacturing scale concentration.
Germany
Stadium operators in Bavaria and North Rhine-Westphalia are accelerating biometric entry system procurement. EU AI Act compliance deadlines mandate third-party conformity assessment for automated identification systems. Salzburg-based engineering centers serve as the technical anchor for European event venue deployments.
United Kingdom
Festival organizers across England and Scotland have shifted toward rental-first procurement models with full-service maintenance contracts. Construction contractors now integrate turnstile entry logs with payroll verification systems. London-based equipment lessors captured the majority of summer 2024 temporary workforce verification deployments.
India
State-level metro modernization tenders in Maharashtra and Karnataka are creating specification opportunities for pre-tested hardware vendors. BIS certification pathways for access control equipment remain underdeveloped compared to mature transit markets. Delhi-NCR contractors are piloting temporary setup configurations for construction site digitization projects.
United States
Corporate campus security upgrades in California and Texas are elevating ISO 27001 certification to gatekeeper status for vendor selection. Enterprise workforce verification systems command specification priority for vendors holding dual CE-ISO credentials. Pacific Northwest technology campuses are driving edge computing architecture adoption for high-throughput entry points.
Mobile Turnstile Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular rental economics and biometric certification niches. The vendor base organizes around three strategic archetypes: Shenzhen-based optical sensor integrators, Salzburg-anchored European system engineers, and UK-focused temporary infrastructure specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with certification pre-qualification emerging as a tender-filtering mechanism.
Among China-based fabricators, Shenzhen Tigerwong Technology Co., Ltd. and Shenzhen Ruiguangke Electronic Tech Co., Ltd. exemplify the optical sensor integration archetype serving transit applications. SKIDATA GmbH occupies a position within the European engineering tier, while Heras represents the temporary infrastructure specialization anchored in UK construction markets.
| Leading Market Players |
|---|
| DataScope Systems Ltd |
| Heras |
| Mikroelektronika spol. s r.o. |
| SKIDATA |
| A3M |
| Alvarado Manufacturing |
| Shenzhen Tigerwong Technology |
| Goldantell |
| Shenzhen Ruiguangke Electronic Tech |
| Others |
Value Network & Pricing Analysis
Festival organizers in the UK and Netherlands now dominate procurement volume through rental-first contracts, locking in operational expenditure models that bundle hardware depreciation with full-service maintenance across 50-plus redeployment cycles. This buyer concentration compresses capital expenditure pricing tiers while elevating attach-rate premiums for software modules and biometric certification upgrades.
Pricing Analysis
Service bundling separates hardware-only transactions from full-deployment packages that include firmware integration, EU AI Act compliance documentation, and algorithmic bias testing protocols. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and biometric module complexity, with electronic turnstiles commanding substantial premiums over manual alternatives. Cost compression in standard-tier portable framing intensifies because Shenzhen manufacturing scale has eroded component margins. Construction contractors show highest price sensitivity, while German stadium operators prioritize throughput certification over unit economics.
Supply Chain Analysis
Optical sensor arrays rest on Taiwanese foundry output for RFID reader chipsets and Chinese Pearl River Delta manufacturing for transit-grade modules. Aluminum extrusion from Shandong Province and galvanized steel feedstock from Hebei Province anchor portable framing production, with battery backup systems and multi-spectral camera modules completing the component stack. Single-source vulnerability concentrates in Taiwanese semiconductor fabrication, where geopolitical friction threatens just-in-time delivery commitments. Distribution runs through Shenzhen OEM clusters for transit deployments and Salzburg-anchored engineering centers for European venue specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified biometric module capacity remains constrained by EU AI Act validation timelines, propping vendor pricing power for pre-qualified hardware suppliers. This supply bottleneck favors incumbents with existing notified body relationships.
For Market Incumbents: To counter algorithmic certification delays compressing product launch windows, accelerate third-party conformity assessment pipelines with German TÜV or DEKRA relationships, and anchor capacity expansion in Salzburg engineering centers to capture Bavarian stadium procurement acceleration. For New Entrants and Emerging Players: Launch via operational expenditure rental models targeting Benelux festival organizers, where equipment lessors have demonstrated 60-percent summer deployment capture. White-space sits in India state-level metro tenders with underdeveloped BIS certification pathways, and UK construction site digitization integrating payroll-verification SaaS attach rates. For Investors and Strategic Acquirers: The window for entry favors vendors with dual CE-ISO credentials and pre-certified biometric libraries. Long-term viability hinges on edge computing architecture ownership and EU AI Act compliance infrastructure. Watch Indian state tender announcements as inflection indicators for geographic expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Third-party conformity assessment with German notified bodies filters tender participation for Bavarian stadium deployments. |
| Edge Computing Architecture Development | Hardware-level processing latency under 30 passengers per minute forces cloud-displacement in high-throughput venues. |
| Shenzhen Manufacturing Scale Expansion | Pearl River Delta OEM clusters compress optical sensor costs for transit-grade module export competitiveness. |
| ISO 27001 Information Security Certification | Dual CE-ISO credentials command specification priority for California and Texas corporate campus security upgrades. |
| Operational Expenditure Rental Model Launch | Full-service maintenance bundling captures Benelux festival procurement shifting from capital expenditure patterns. |
Research Methodology
Regulatory filings from SAMR, EU AI Act implementation guidance, and customs trade data formed the secondary backbone, cross-referenced against primary interviews with stadium operations directors, transit procurement officers, festival logistics coordinators, and access control systems integrators. Bottom-up vendor shipment aggregation and top-down venue installation tracking provided triangulation checks across the analysis window.
Historical trendline analysis of Shenzhen OEM export volumes and European stadium refresh cycles established baseline growth patterns. Segmentation modeling incorporated product type durability tiers, authentication technology complexity, installation duration categories, and end-use throughput requirements. CAGRs derived from installed base replacement velocity and rental fleet expansion rates across transit, venue, and corporate verticals.
The model assumes a particular technology adoption path; alternative pathways for multi-spectral biometric sensors would alter the outlook if liveness detection standards shift. Forecasts reflect assumptions on EU AI Act enforcement consistency and Taiwanese semiconductor supply continuity. A small set of triggers—Indian BIS certification finalization, German stadium compliance deadline acceleration, and Pearl River Delta labor cost movements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Locks Market
Access Control Systems
North America Home Security System Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Network Access Control Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Automated Barriers and Bollards Market
Access Control Systems
Latin America Card-Based Access Control Market