
 North America Safety Systems Market | 2026-2036
North America Safety Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Safety Systems Market Analytics
ASIL-D functional safety certification is unwinding legacy product lines across the North America Safety Systems Market. Honeywell International Inc leverages its distributed control architecture to anchor process safety contracts in downstream oil and gas. Schneider Electric Inc sustains competitive positioning through deep integration of EcoStruxure platforms into building safety infrastructure. ABB Ltd differentiates via its Ability SafetyInsight portfolio targeting electrification hazards in heavy manufacturing.
North America safety systems encompass engineered assemblies of sensors, programmable logic controllers, emergency shutdown devices, and communication networks designed to detect hazardous conditions and initiate protective responses within milliseconds. These systems integrate IEC 61508-certified hardware with redundant architectures to prevent catastrophic failures in high-consequence environments. Fire safety systems command the largest installed base across industrial facilities, while AI-driven solutions capture the fastest expansion as predictive algorithms reduce false alarm rates and enable condition-based maintenance. Sensor technology forms the densest margin pool where specialized gas detection and flame sensing modules carry premium pricing.
OSHA process safety management standards and NFPA fire codes shape minimum compliance thresholds for system design and inspection intervals across US facilities. EPA risk management program requirements and Canadian Centre for Occupational Health and Safety guidelines extend regulatory coverage to chemical release scenarios and cross-border facility operations. Stakeholders must monitor evolving NHTSA autonomous vehicle safety mandates and FAA drone integration rules as these create adjacent demand for collision avoidance and geofencing systems.
Market Dynamics
AI-driven sensor fusion is compressing response times from seconds to milliseconds across hazardous facility operations, forcing legacy relay-based architectures into obsolescence and redrawing competitive boundaries around real-time data processing capabilities.
Growth Catalysts
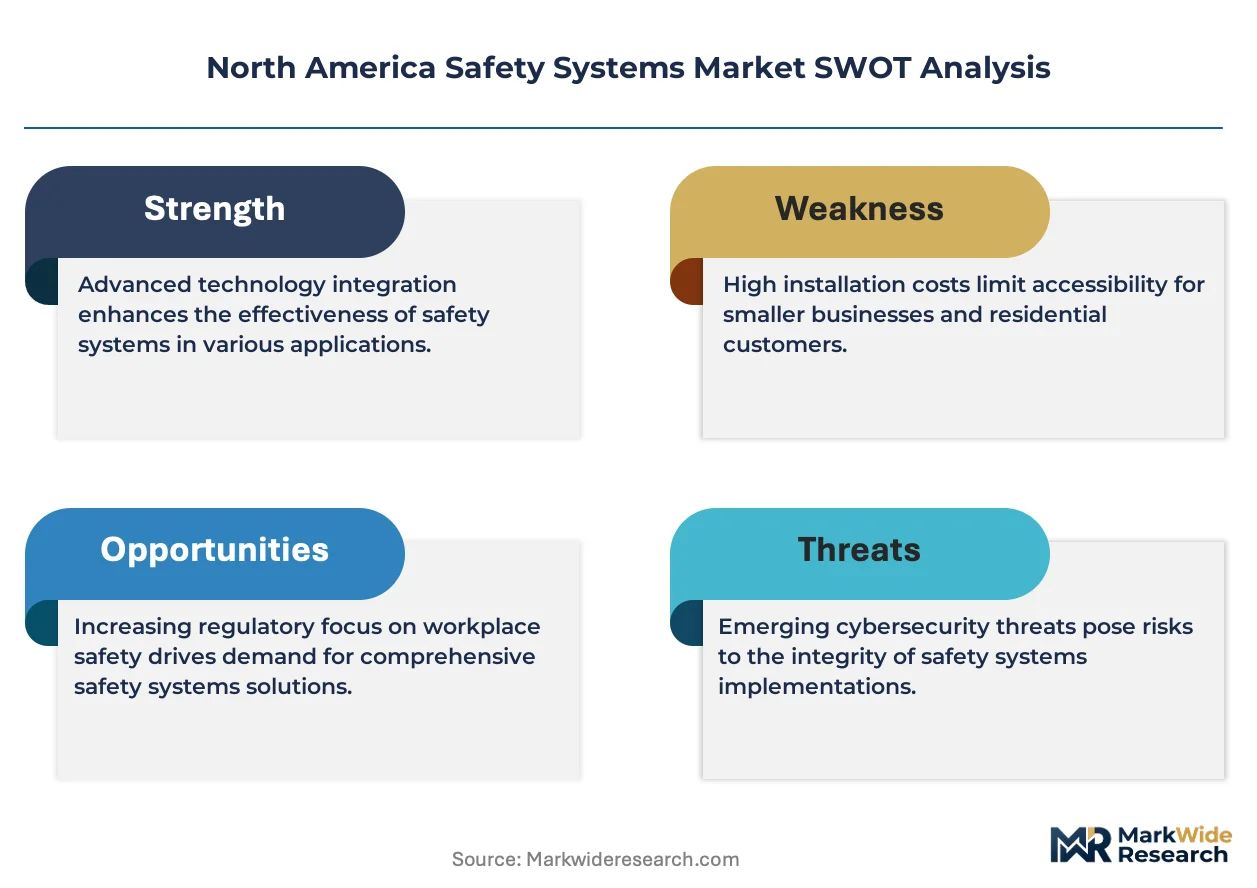
- OSHA Process Safety Management:Mandatory mechanical integrity programs for high-hazard chemicals are triggering systematic replacement of aging safety instrumented systems in Texas and Louisiana refineries.
- Edge computing architectures:On-premise AI inference engines enable predictive maintenance without cloud latency, accelerating adoption in upstream oil and gas remote facilities.
- US Gulf Coast petrochemical corridor:Facility modernization programs are prioritizing integrated hazard detection across ethylene crackers and polyethylene units.
Market Restraints
- Semiconductor supply concentration:Specialized analog chips for flame and gas detection face extended lead times from concentrated Asian foundry capacity.
- ASIL-D certification timelines:Functional safety validation for automotive-qualified components creates 18-24 month product development cycles.
- Copper and rare earth magnet volatility:Electromechanical safety devices face input cost pressure from commodity price swings affecting solenoid valves and servo actuators.
Strategic Opportunities
- Canadian oil sands automation:SAGD facility operators are retrofitting unmanned well pads with wireless safety shutdown systems to reduce personnel exposure.
- NHTSA autonomous vehicle mandates:Collision avoidance system requirements are creating adjacent demand for lidar-based proximity sensors in industrial mobile equipment.
- Digital twin convergence:Integration of safety system simulation with predictive maintenance platforms enables virtual commissioning of emergency shutdown sequences.
Industry Challenges
- IEC 61508 SIL certification backlog:Third-party validation laboratories face capacity constraints extending product launch timelines.
- Cyber-physical security integration:Safety networks require hardened architectures against ransomware while maintaining deterministic response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Safety Systems Market |
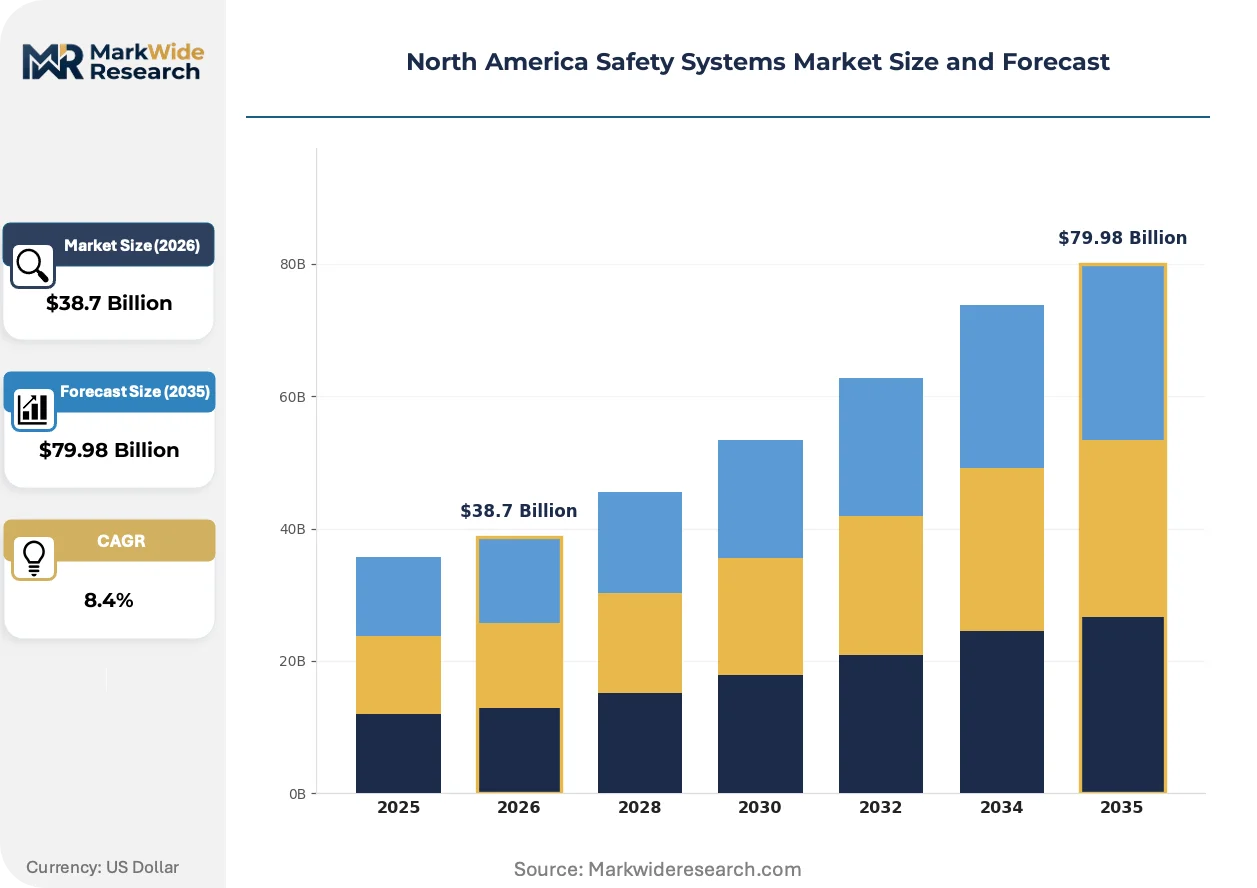
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, RFID, Sensor Technology, AI-driven Solutions End User: Manufacturing, Transportation, Construction, Healthcare Product Type: Fire Safety Systems, Intrusion Detection, Surveillance Equipment, Access Control Application: Industrial Safety, Building Security, Personal Protection, Hazardous Area Safety |
| Companies Covered | Schneider Electric SE, Honeywell International Inc, ABB Ltd, Rockwell Automation Inc, Siemens AG, Yokogawa Electric Corporation, Emerson Electric Co, Mitsubishi Electric Corporation, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Safety Systems Market Evolving Landscape
Real-time hazard detection is migrating from centralized control rooms to distributed edge nodes, compressing system architectures and enabling autonomous protective responses without human intervention loops.
Optical gas imaging technology is decomposing traditional point-detector networks by enabling visualization of fugitive emissions across entire facility perimeters. Midstream pipeline operators are deploying these thermal cameras for continuous methane monitoring. The technology is decomposing the installed base of catalytic bead sensors in natural gas processing plants.
EPA Risk Management Program amendments are tightening worst-case release scenario modeling requirements for chemical facilities. Owners must now quantify passive mitigation effectiveness in quantitative risk assessments. Ammonia refrigeration and chlorine water treatment plants in the US Midwest are responding with enhanced gas detection density and automated isolation valve arrays.
Service unbundling is fragmenting long-term maintenance contracts into discrete performance-based engagements. End-users in the US pharmaceutical sector are purchasing safety system health monitoring separately from hardware procurement. This shift is most pronounced in New Jersey and Pennsylvania biologics manufacturing clusters where facility engineers demand predictive analytics subscriptions independent of original equipment vendor relationships.
North America Safety Systems Market Segmentation
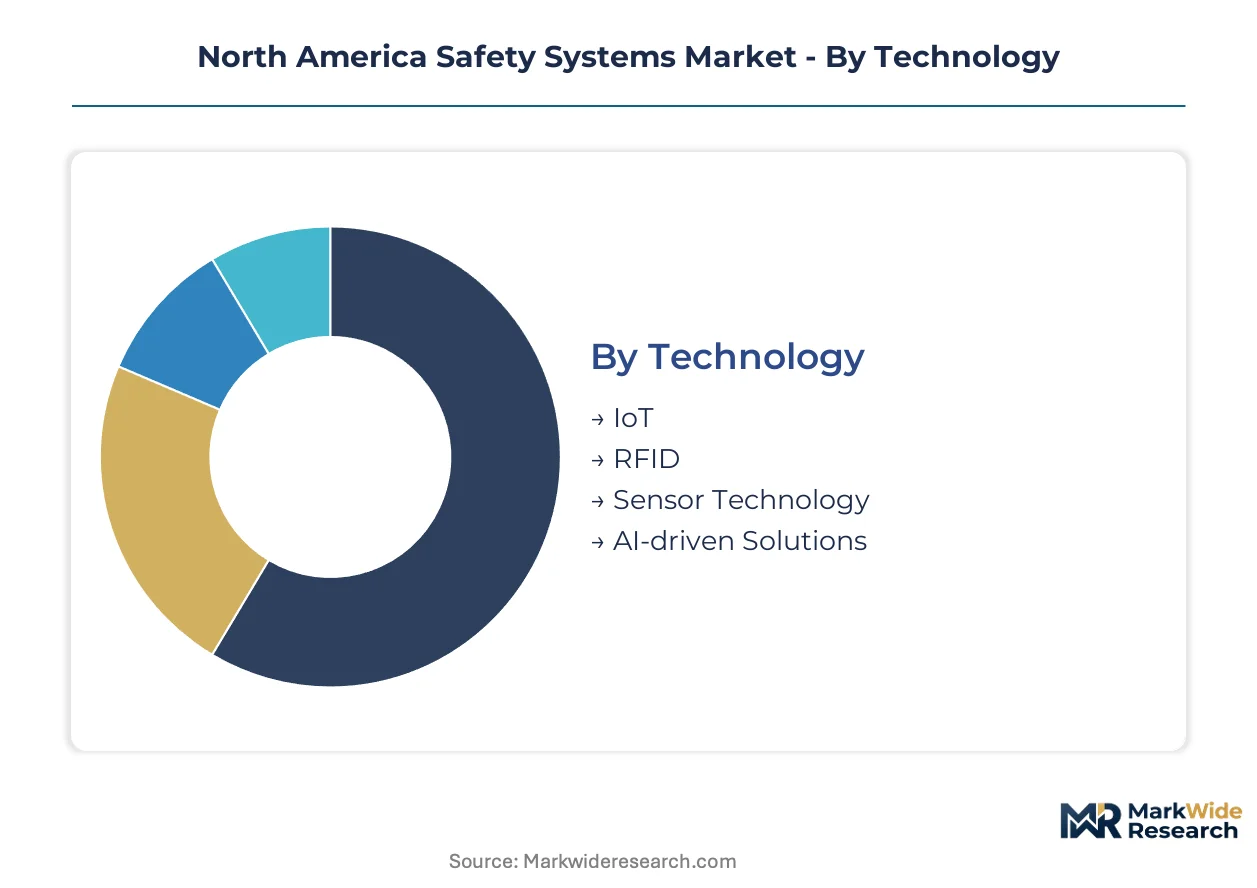
Safety system procurement in North America fragments across multiple technical and operational dimensions. End-users prioritize integration depth over standalone functionality, compressing vendor margins in commoditized hardware while amplifying returns on predictive analytics layers.
Technology:
Sensor Technology faces the most acute substitution pressure as optical gas imaging and thermal imaging platforms displace legacy point-detector networks in petrochemical facilities.
- Sensor Technology:Catalytic bead, electrochemical, and infrared detection modules form the hardware foundation for gas and flame monitoring. Texas and Louisiana refineries are densifying sensor deployments to satisfy EPA Risk Management Program amendments requiring quantified passive mitigation effectiveness.
- AI-driven Solutions:Edge-deployed inference engines process multi-sensor streams to reduce false alarm rates and enable condition-based maintenance. US Gulf Coast ethylene crackers prioritize these systems for predictive emergency shutdown sequencing.
- IoT:Wireless sensor networks connect distributed safety nodes across unmanned well pads and remote pipeline stations.
- RFID:Personnel tracking and access verification systems integrate with mustering protocols during facility evacuations.
Sensor Technology anchors the volume base while AI-driven Solutions gain share at the steepest rate.
End User:
Cost tier stratification separates high-complexity process industries from price-sensitive commercial installations.
- Manufacturing:Heavy industrial facilities deploy IEC 61508-certified safety instrumented systems with redundant architectures. OSHA Process Safety Management mandates are triggering systematic replacement of aging relay-based systems in Midwest automotive stamping plants and Southeast aluminum smelters.
- Transportation:NHTSA collision avoidance mandates are extending lidar and radar-based proximity sensing from autonomous vehicles to industrial mobile equipment. Port operators in Long Beach and Houston are retrofitting container handling equipment with these technologies.
- Construction:Temporary worksite safety relies on wearable panic buttons and geofenced exclusion zones.
- Healthcare:Hospital emergency departments and pharmaceutical cleanrooms require specialized gas detection for anesthetic agents and cryogenic hazards.
Manufacturing captures the dominant revenue share while Transportation climbs fastest on regulatory mandate acceleration.
Product Type:
Application maturity varies sharply, with fire safety commanding entrenched installed bases and access control experiencing technology disruption.
- Fire Safety Systems:Smoke detection, sprinkler activation, and emergency voice communication networks constitute the largest installed base across North American industrial facilities. NFPA code updates are driving replacement of legacy ionization detectors with photoelectric and multi-criteria sensors in California and New York commercial high-rises.
- Surveillance Equipment:Thermal and optical cameras enable continuous perimeter monitoring and fugitive emissions visualization. Midstream pipeline operators in Alberta and Oklahoma are deploying these for automated methane leak detection.
- Intrusion Detection:Perimeter breach sensors and motion analytics protect critical infrastructure from unauthorized access.
- Access Control:Biometric and credential-based entry systems integrate with mustering and time-and-attendance platforms.
Fire Safety Systems maintains the deepest penetration while Surveillance Equipment expands most quickly on environmental compliance drivers.
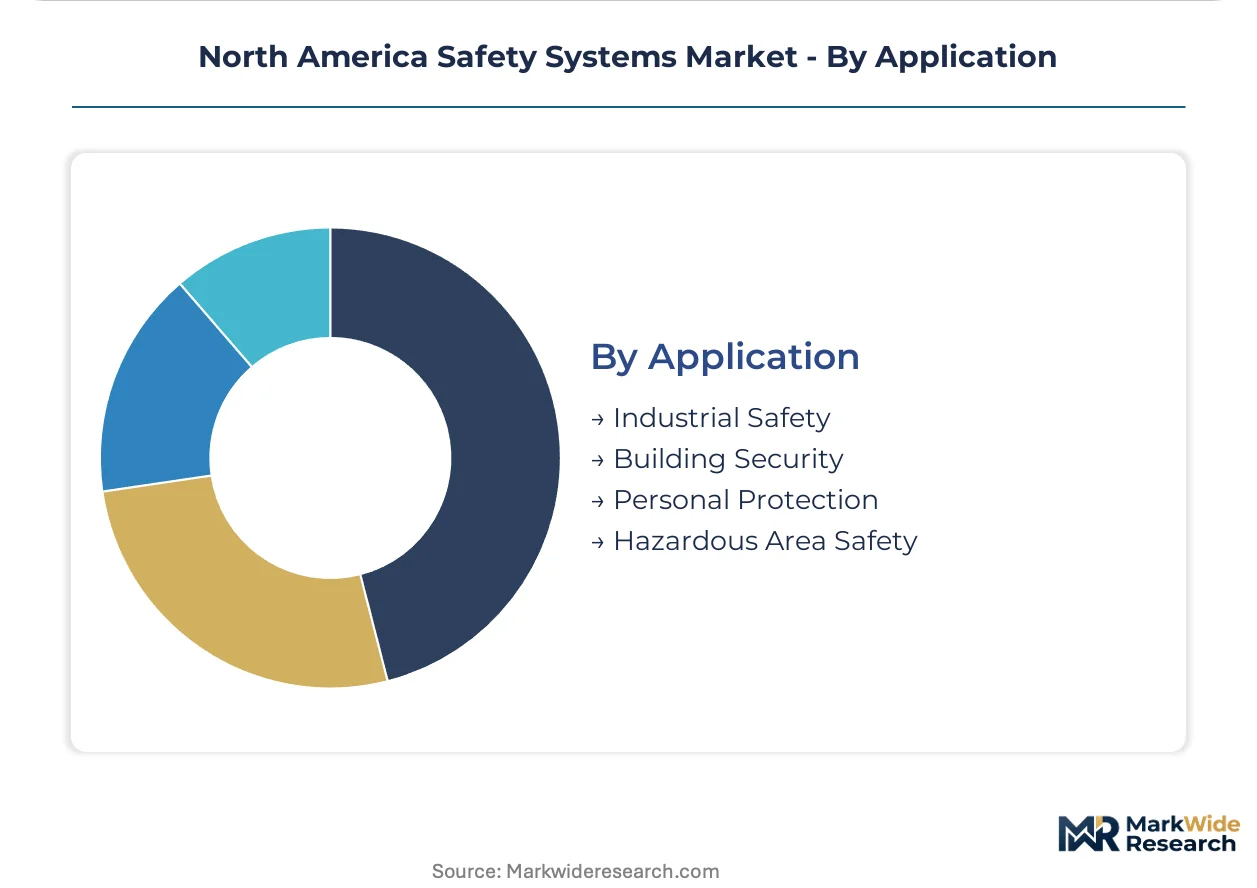
Application:
Customer type segmentation separates owner-operated facilities from contractor-managed sites with diverging procurement authority structures.
- Industrial Safety:Process hazard management systems protect high-consequence operations in chemical, oil and gas, and power generation. Canadian oil sands SAGD operators are retrofitting unmanned well pads with wireless safety shutdown systems to reduce personnel exposure.
- Hazardous Area Safety:Explosion-proof equipment and intrinsic safety barriers enable instrumentation in classified zones. US Gulf Coast polyethylene units are prioritizing integrated hazard detection across ethylene crackers and downstream derivatives.
- Building Security:Integrated life safety and security platforms serve commercial office and retail portfolios.
- Personal Protection:Wearable gas monitors and lone-worker communication devices protect individual personnel in isolated field conditions.
Industrial Safety dominates current deployment value while Hazardous Area Safety shows the steepest expansion trajectory on facility modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America maintains a modest safety systems trade surplus with Canada and Mexico, though specialized sensor components and flame detection modules flow inbound from European and Asian suppliers to meet domestic petrochemical demand.
United States
OSHA Process Safety Management mandates are accelerating replacement cycles for aging safety instrumented systems across Texas and Louisiana refineries. EPA Risk Management Program amendments now require quantified passive mitigation effectiveness in worst-case release modeling. The US Gulf Coast petrochemical corridor concentrates facility modernization programs around integrated hazard detection for ethylene crackers and polyethylene derivatives.
Canada
Steam-assisted gravity drainage operators in Alberta are retrofitting unmanned well pads with wireless safety shutdown systems to reduce personnel exposure in remote oil sands fields. Canadian Centre for Occupational Health and Safety guidelines extend coverage to chemical release scenarios in cross-border facility operations. Ontario's manufacturing belt around Toronto and Hamilton is densifying gas detection deployments to satisfy provincial occupational health mandates.
Mexico
Refinery modernization at Pemex facilities in Tula and Salamanca is importing integrated fire and gas detection systems from US suppliers. Mexico's federal labor law reforms are tightening workplace safety enforcement across maquiladora operations in Nuevo León and Baja California. The northern border states concentrate automotive stamping plant upgrades where OSHA-aligned safety standards govern supplier qualification.
North America Safety Systems Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing distributed control architectures and certified safety portfolios. The vendor base organizes around three strategic archetypes: process automation specialists with integrated safety layers, building infrastructure providers extending into life safety, and pure-play safety instrumented system manufacturers. Competitive dynamics revolve around ASIL-D functional safety certification timelines and edge computing integration capabilities. Dominant moves include strategic partnerships for AI-driven sensor fusion and geographic expansion through local system integrator networks.
Within the diversified industrial tier, Honeywell International Inc, Schneider Electric SE, and ABB Ltd occupy positions exemplifying contrasting architectural approaches. Honeywell leverages process safety contracts in downstream oil and gas through distributed control heritage. Schneider Electric sustains positioning via EcoStruxure platform integration into building safety infrastructure. ABB differentiates through electrification hazard targeting in heavy manufacturing environments. These three represent how certification depth, platform breadth, and vertical application focus create defensible positioning against specialized challengers.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Honeywell International Inc |
| ABB Ltd |
| Rockwell Automation Inc |
| Siemens AG |
| Yokogawa Electric Corporation |
| Emerson Electric Co |
| Mitsubishi Electric Corporation |
| Johnson Controls |
| Others |
Value Network & Pricing Analysis
Specialized foundry capacity utilization in Taiwan and South Korea anchors component economics for flame detection modules, compressing margin structures for mid-tier system integrators while amplifying pricing power among ASIL-D certified suppliers. This scale concentration creates asymmetric cost pass-through where petrochemical buyers absorb premium sensor pricing more readily than commercial construction clients.
Pricing Analysis
Industrial OEM buyers anchor project-based contracting structures across the North America Safety Systems Market. Three-tier pricing structure across SIL-certified premium, standard IEC 61508-compliant, and economy relay-based tiers separates procurement budgets. Price differentiation rests on certification depth and after-sales predictive analytics bundling. Cost compression in the economy tier is intensifying because Mexican maquiladora facilities prioritize OSHA-aligned compliance at minimum capex. Commercial building operators show highest price sensitivity versus Gulf Coast petrochemical owner-operators who prioritize uptime guarantees.
Supply Chain Analysis
Strait of Malacca transit congestion exposes flame sensor module shipments from Malaysian assembly plants to Texas refineries. Supply concentration spans Taiwan for specialized analog chips, Germany for precision electromechanical actuators, and Japan for infrared detection elements. Raw material dependencies include copper for solenoid windings, rare earth magnets for servo motors, and sapphire substrates for optical gas imaging. Single-source vulnerability in ASIC fabrication for gas detection creates procurement risk. Distribution runs through authorized system integrator networks with regional stocking agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Gulf Coast petrochemical facility consolidation, with supermajor operators extracting volume discounts that compress vendor margins across the supplier base.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance subscriptions that raise switching costs for Texas and Louisiana refineries. Accelerate ASIL-D certification pipelines to defend against modular AI-driven entrants. Prioritize backward integration into specialized sensor fabrication to reduce Taiwan foundry dependency. For New Entrants and Emerging Players: Predictive analytics service gaps in Canadian oil sands SAGD operations create white-space entry points where incumbents under-serve remote unmanned facilities. Target Alberta wireless safety shutdown retrofits as the most penetrable geography. Pursue channel partnerships with Calgary-based system integrators possessing Indigenous land access agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among edge-AI safety platform providers with pharmaceutical sector subscriptions in New Jersey and Pennsylvania. Long-term viability favors vendors with SIL certification depth and SaaS-layer attach rates. Monitor NHTSA autonomous vehicle rulemaking acceleration as inflection signal for industrial mobile equipment sensor demand.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Accelerates product launch timelines for automotive-qualified safety components targeting NHTSA mandates. |
| Edge Computing Partnership | Enables on-premise AI inference for predictive maintenance in upstream oil and gas remote facilities. |
| Wireless Sensor Network Deployment | Reduces personnel exposure in Canadian SAGD unmanned well pad retrofits. |
| Optical Gas Imaging Integration | Displaces legacy catalytic bead sensors for EPA Risk Management Program compliance in Midwest ammonia plants. |
| Predictive Analytics Subscription Launch | Captures service unbundling demand from New Jersey biologics manufacturers seeking vendor-independent monitoring. |
Research Methodology
Cross-validation between plant manager interviews and OSHA enforcement data anchors the qualitative findings across the North America Safety Systems Market. Primary fieldwork engaged safety instrumented system engineers, petrochemical procurement leads, Canadian oil sands operations managers, and building automation integrators. Secondary validation drew from EPA Risk Management Program filings, NFPA code revision dockets, SEC 10-K safety system revenue disclosures, and Canadian Centre for Occupational Health and Safety guideline updates. Bottom-up demand modeling triangulated against top-down industrial capex projections.
Sensitivity analysis tested forecast robustness across semiconductor supply scenarios and regulatory acceleration cases over the projection horizon. Segmentation dimensions modeled include technology tier, end-use industry vertical, product type maturity, and application hazard classification. CAGRs were derived from installed base replacement cycles and new facility automation intensity. Industry-specific inputs incorporated OSHA PSM inspection frequency trends and EPA RMP amendment implementation pacing.
Forecasts assume regulatory continuity in OSHA process safety enforcement and EPA risk management protocols; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Programmable Safety Systems Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
North America Access Control Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Access Control Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Car Security System Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Access Control As a Service Market