
 Indoor Electromagnetic Lock Market | 2026-2036
Indoor Electromagnetic Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Electromagnetic Lock Market Foresight
Multi-source procurement is pivoting toward captive magnet assembly programs among tier-one suppliers. Securitron leverages its North American manufacturing footprint to control coil-winding quality and reduce lead times. Assa Abloy anchors its position through backward integration into rare-earth magnet sourcing. Dynaloc competes by specializing in compact form factors for retrofit installations.
An indoor electromagnetic lock generates holding force through a current-excited coil attracting an armature plate, typically delivering 600 to 1,200 pounds of holding force depending on core material and winding density. The device serves commercial access-control systems by enabling remote release, audit logging, and integration with credential readers. Surface mount configurations dominate volume in existing-building retrofits where door-frame modification is constrained. Dual-circuit technology commands premium positioning by providing redundant monitoring paths for high-security government facilities. Fail-secure electrified locks retain growing share in educational institutions where life-safety codes require mechanical override capability during power loss.
UL 294 access-control system standards and NFPA 101 life-safety codes govern electromagnetic lock deployment in US commercial and institutional buildings, mandating timed bypass and emergency release interfaces. The EU Construction Products Regulation and CE marking requirements shape electromagnetic lock market access across European member states by enforcing electromagnetic compatibility and fire-resistance testing protocols. Stakeholders must monitor evolving biometric-credential integration standards and cybersecurity frameworks for networked locking systems as physical access control converges with IT infrastructure governance.
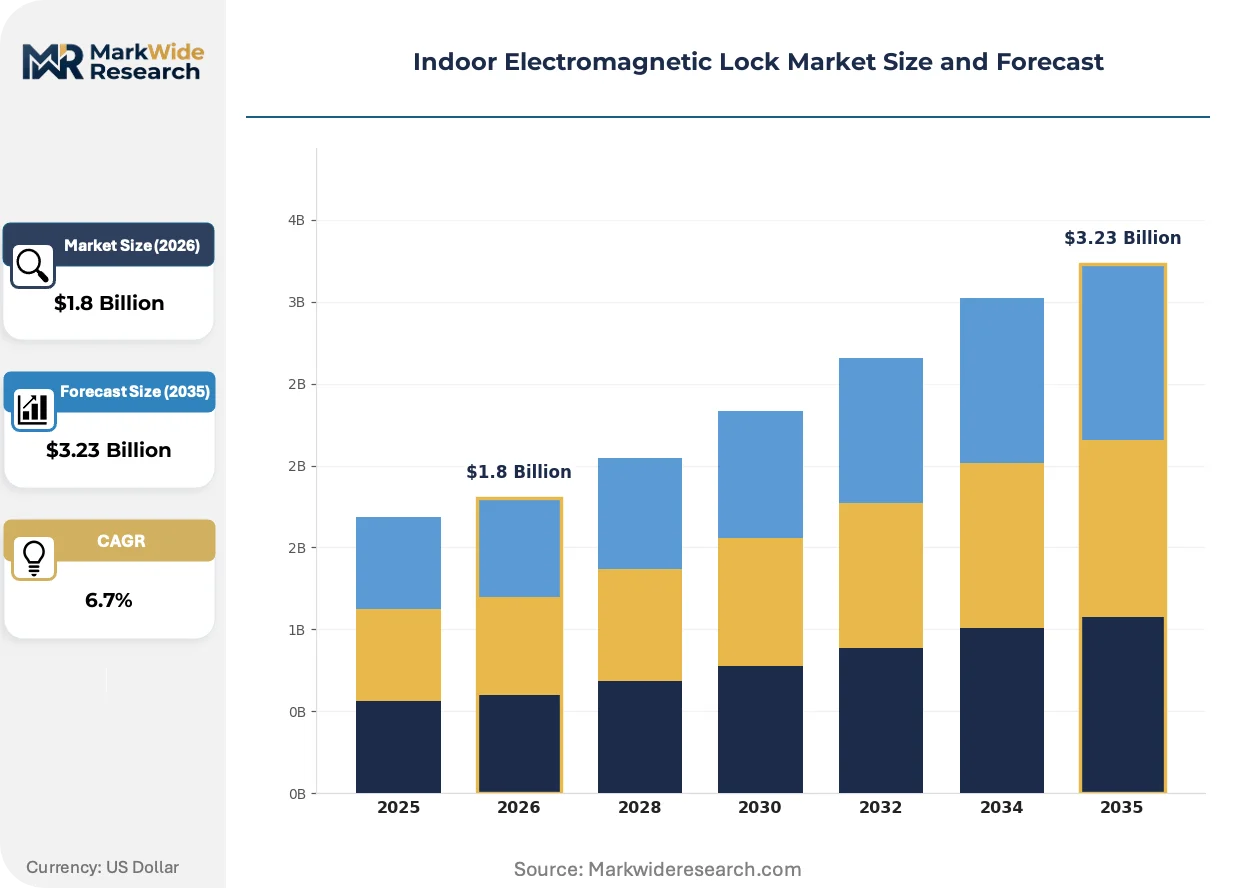
Market Dynamics
Commercial building operators are consolidating access-control infrastructure around networked electromagnetic lock systems that integrate credential readers, video surveillance, and identity management platforms into unified security stacks.
Growth Catalysts
- Smart Building Retrofit Mandates:Municipal energy-efficiency ordinances in Shanghai and Shenzhen are accelerating electromagnetic lock deployment as part of integrated building automation retrofits in Class A office towers.
- EU AI Act Compliance:Biometric access-control systems must now meet algorithmic transparency requirements, pulling demand toward certified electromagnetic lock manufacturers with embedded audit-logging capabilities.
- Rare-Earth Magnet Supply Security:China's dominance in neodymium processing is prompting facility managers to lock in long-term magnet supply contracts through direct supplier relationships.
Market Restraints
- Copper Coil Cost Volatility:Electromagnetic lock manufacturers face margin compression from fluctuating copper prices in coil-winding operations, with no viable conductor substitutes at equivalent conductivity.
- Single-Source Rare-Earth Dependency:Neodymium-iron-boron magnet supply concentrates in Chinese processing facilities, creating geopolitical exposure for North American and European lock assemblers.
- Mechanical Override Requirements:NFPA 101 life-safety codes in US educational facilities limit pure electromagnetic lock penetration where fail-secure mechanical backup remains mandatory.
Strategic Opportunities
- Underpenetrated Healthcare Vertical:Hospital expansion in India offers white-space demand for antimicrobial-finish electromagnetic locks meeting infection-control protocols in surgical suites and pharmaceutical storage.
- Cybersecurity Certification Tailwind:UL 2900 IoT security standards for networked locking systems create competitive differentiation for vendors achieving third-party penetration-test validation.
- Cloud-Access Convergence:Integration between electromagnetic locks and SaaS-based identity platforms is opening recurring-revenue service models for system integrators serving mid-market commercial tenants.
Industry Challenges
- Electromechanical Integration Skill Gap:Installer certification for dual-circuit redundant monitoring systems requires specialized training that outpaces vocational program output in several European markets.
- Legacy Panel Compatibility:Retrofit projects encounter protocol fragmentation between proprietary access-control panels and open-architecture electromagnetic lock controllers, extending commissioning timelines.
- Fire-Rating Certification Delays:CE marking under EU Construction Products Regulation demands extended electromagnetic compatibility and fire-resistance testing that stretches product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Electromagnetic Lock Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Mount, Flush Mount, Mini Electric, Heavy-Duty Electromagnetic Technology: Single-Circuit, Dual-Circuit, Fail-Safe, Fail-Secure Application: Commercial Buildings, Government Facilities, Residential Properties, Educational Institutions End User: Security Companies, Facility Managers, Contractors, Maintenance Services |
| Companies Covered | Dynaloc, Faradays, Securitron, FSH Fire & Security Hardware, Styrax Instruments, Assa Abloy, Security Door Controls, Oubao Security Technology, BSI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Electromagnetic Lock Market Shifts & Advancements
Electromagnetic lock architecture is converging with IT infrastructure governance, forcing hardware manufacturers to embed cybersecurity capabilities and API interoperability that were previously outside core competency boundaries.
Dual-circuit monitoring technology is consolidating high-security facility specifications around redundant signal paths that detect armature plate tampering and power anomalies in real time. Government and data center operators are mandating this architecture for new construction. The technology is consolidating supplier tiers by disqualifying single-circuit vendors from premium bid opportunities.
The EU AI Act's risk-classification framework for biometric access systems is tightening algorithmic audit requirements across European member states. Electromagnetic lock OEMs must now document data handling protocols for credential readers integrated with their hardware. German building security directives are accelerating compliance timelines, compressing certification cycles for suppliers serving federal facility contracts.
Specification authority is migrating from mechanical contractors to IT security officers as electromagnetic locks join networked access-control ecosystems. Value-added distributors with in-house cybersecurity expertise are displacing traditional electrical wholesalers in commercial project channels. This shift is most pronounced in US enterprise campus deployments where CISO oversight now governs physical security procurement decisions.
Indoor Electromagnetic Lock Market Segmentation
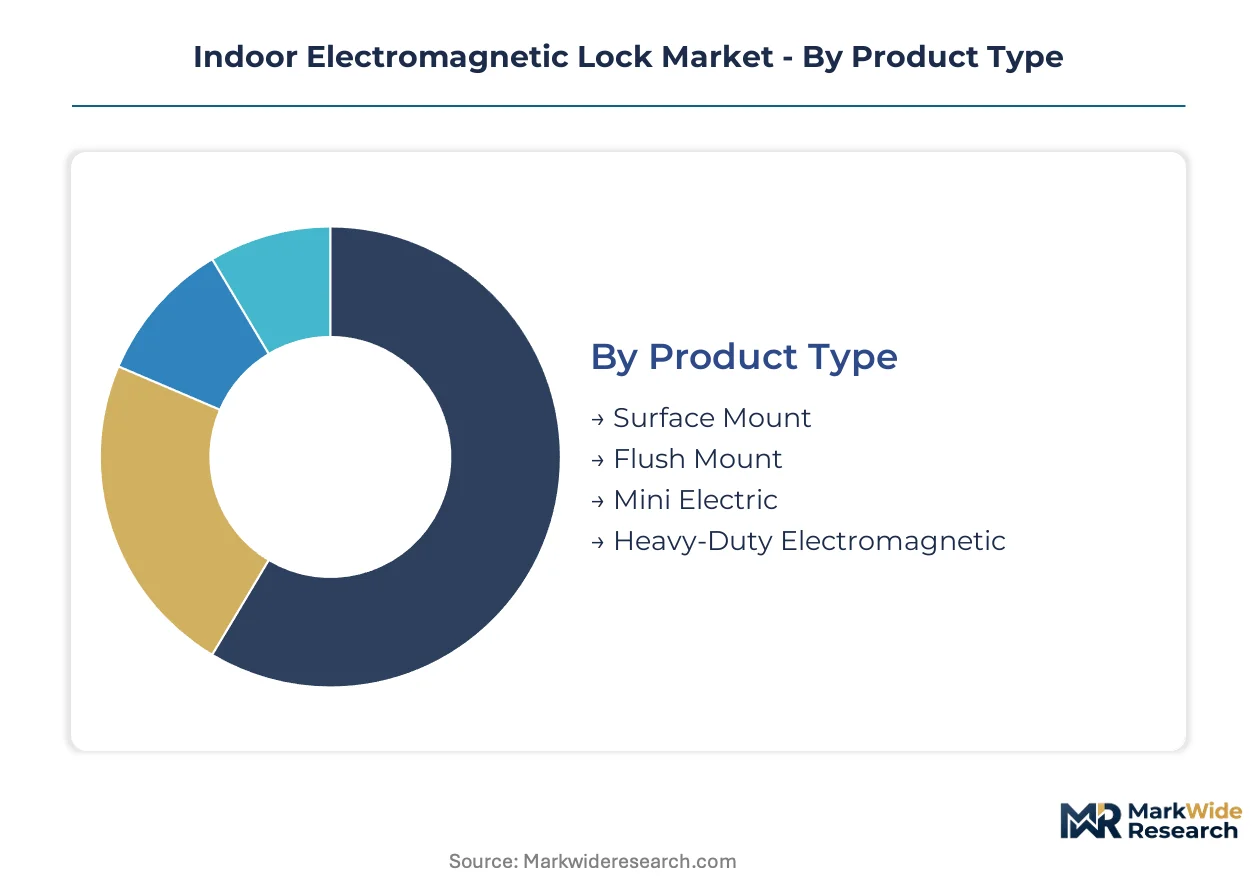
Electromagnetic lock procurement decisions split sharply between standardized commodity hardware and application-engineered configurations. Specification authority now rests with IT security officers who prioritize API interoperability over mechanical specifications, fragmenting traditional product hierarchies.
Product Type:
Customization intensity varies from mass-produced surface units to project-engineered heavy-duty systems, creating distinct margin tiers across the installation spectrum.
- Surface Mount:These units attach externally to door frames without cutting or mortising, preserving fire ratings in existing structures. Demand concentrates in US educational retrofits where NFPA 101 compliance mandates minimal frame modification alongside mechanical override capability.
- Heavy-Duty Electromagnetic:Engineered for 1,200+ pound holding force with reinforced armature plates and thermal management systems. High-security government facilities in Germany specify these for data center mantraps under EU AI Act audit-logging requirements.
- Flush Mount:Recessed installation delivers clean aesthetic lines for premium commercial interiors in Shanghai Class A towers.
- Mini Electric:Compact form factors serve cabinet and pharmaceutical storage applications in Indian hospital expansions.
Most installed capacity flows through Surface Mount. Expansion is steepest in Heavy-Duty Electromagnetic.
Technology:
Circuit architecture and failure-mode selection determine compliance eligibility across regulated end-uses, with premium positioning reserved for redundant monitoring systems.
- Dual-Circuit:Independent signal paths monitor armature position and power integrity simultaneously. Data center operators in Shenzhen mandate this architecture for tier-three facilities, disqualifying single-circuit vendors from premium bids.
- Fail-Secure:Mechanical locking persists during power loss, satisfying US educational life-safety codes. School districts in Texas and California specify these for classroom door hardware under district-wide security upgrades.
- Single-Circuit:Basic monitoring suffices for standard commercial access control in low-risk tenant spaces.
- Fail-Safe:Power loss releases the lock, deployed in healthcare corridors where emergency egress takes priority.
Dual-Circuit commands the highest specification rates. Fail-Secure is climbing the fastest as institutional security budgets harden against active-threat scenarios.
Application:
End-use verticals impose divergent certification burdens, from antimicrobial finishes in healthcare to electromagnetic compatibility in federal facilities.
- Commercial Buildings:Class A office towers drive volume through integrated building automation retrofits. Municipal energy ordinances in Shanghai and Shenzhen bundle electromagnetic locks with HVAC and lighting controls, accelerating replacement cycles.
- Government Facilities:Algorithmic transparency mandates under the EU AI Act reshape procurement workflows. German federal contracts now require documented data handling protocols for credential reader integration, compressing supplier certification timelines.
- Educational Institutions:US school districts balance security hardening against life-safety override requirements.
- Residential Properties:Smart home convergence pulls demand toward WiFi-enabled compact units in high-rise developments.
Commercial Buildings absorb the greatest unit volume. Government Facilities show the steepest expansion trajectory as cybersecurity frameworks tighten.
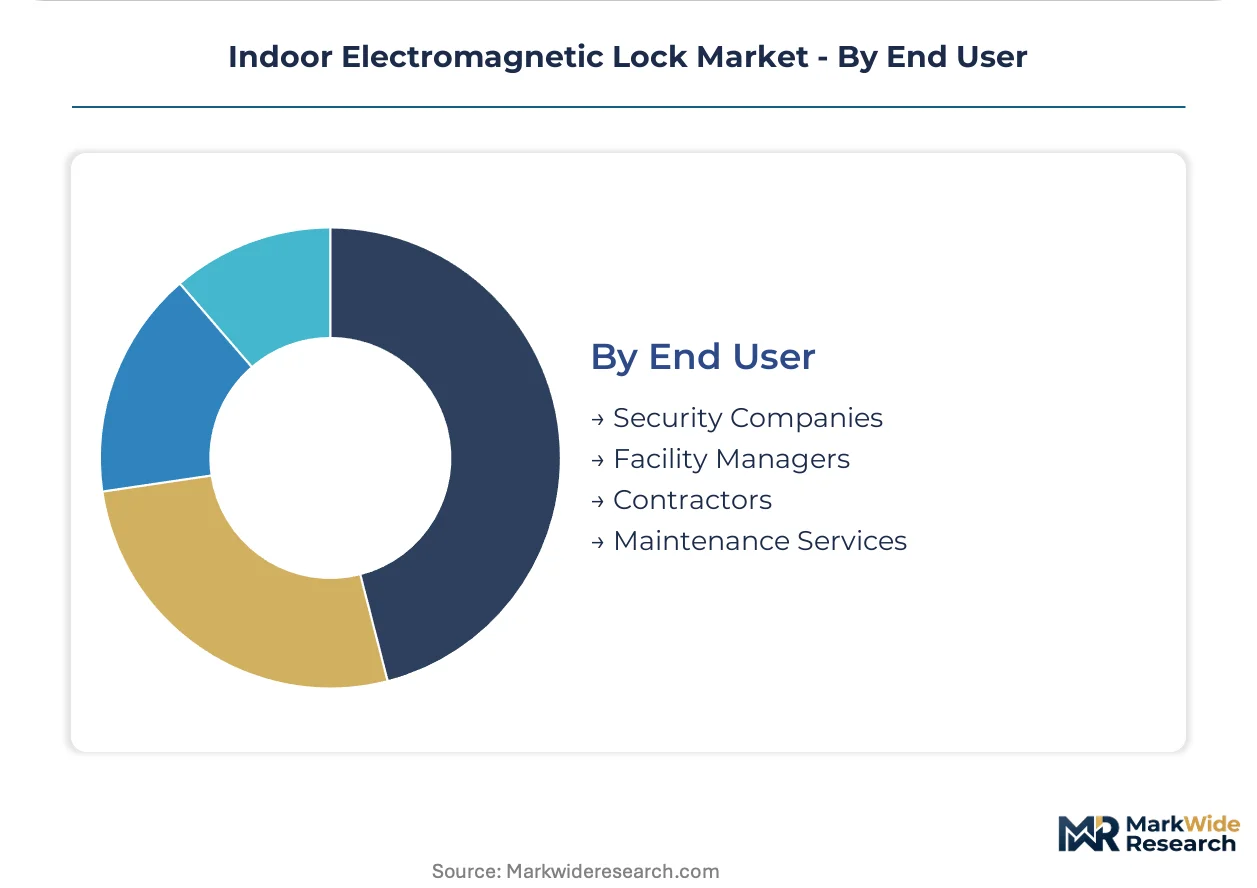
End User:
Procurement authority is migrating from traditional mechanical contractors to technology-integrated service providers with cybersecurity competencies.
- Security Companies:These integrators now specify electromagnetic locks as components of unified security stacks. Value-added distributors with in-house penetration-testing expertise displace electrical wholesalers in US enterprise campus channels.
- Facility Managers:Building operators in Germany consolidate access-control infrastructure around networked systems that merge credential readers, video surveillance, and identity platforms.
- Contractors:Installation certification gaps for dual-circuit systems create bottlenecks in several European markets.
- Maintenance Services:Recurring-revenue service models emerge from cloud-access convergence with SaaS identity platforms.
Security Companies control the dominant procurement channel. Facility Managers are gaining specification authority fastest as smart building investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as manufacturers relocate assembly to jurisdictions with streamlined electromagnetic compatibility certification. Cost-of-compliance gaps between EU Construction Products Regulation markets and alternative manufacturing bases are accelerating this migration.
United States
Educational security retrofits and federal facility hardening drive specification volume. NFPA 101 life-safety codes mandate fail-secure mechanical override for classroom installations. Texas and California school districts concentrate demand for institutional-grade hardware.
Germany
Federal facility contracts require documented data handling protocols under EU AI Act algorithmic transparency mandates. KBA building security directives compress supplier certification timelines. Bavaria anchors high-security data center construction with dual-circuit specifications.
China
Smart building ordinances in Shanghai and Shenzhen bundle electromagnetic locks with integrated automation systems. MIIT standards govern networked access-control cybersecurity. Yangtze River Delta manufacturing clusters supply rare-earth magnet assemblies to tier-one lock producers.
India
Hospital expansion in Maharashtra and Karnataka creates demand for antimicrobial-finish hardware meeting infection-control protocols. BIS certification requirements shape import substitution strategies. Tamil Nadu pharmaceutical manufacturing zones specify compact locks for cleanroom storage.
United Kingdom
Enterprise campus security consolidations pull procurement authority toward CISO-governed specifications. CE marking alignment post-Brexit maintains EU market access for UK-based assemblers. London financial district retrofits prioritize API-interoperable networked systems.
Indoor Electromagnetic Lock Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cybersecurity-certified premium positioning. The vendor base clusters around three strategic archetypes: rare-earth-integrated manufacturers controlling upstream magnet supply, compact-form-factor specialists serving retrofit channels, and IT-convergent integrators embedding API interoperability. Dominant competitive moves include backward integration into coil-winding operations and strategic partnerships with SaaS identity platform providers.
Among North American manufacturers, Securitron exemplifies the captive-production archetype through controlled coil-winding quality. Assa Abloy anchors the rare-earth-integrated tier with upstream magnet sourcing capabilities. Dynaloc occupies the specialization vector for compact retrofit configurations. These three represent distinct competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Dynaloc |
| Faradays |
| Securitron |
| FSH Fire & Security Hardware |
| Styrax Instruments |
| Assa Abloy |
| Security Door Controls |
| Oubao Security Technology |
| BSI |
| Others |
Supply & Pricing Matrix
Dual-circuit specification mandates from data center operators in Shenzhen are compressing supplier qualification timelines and forcing coil-winding investments that reshape cost structures across tier-one manufacturers. Buyers now bundle electromagnetic locks with building automation contracts, concentrating procurement volume and amplifying price leverage for certified vendors.
Pricing Analysis
Copper coil cost pass-through dominates pricing dynamics, with winding density specifications directly translating to material cost exposure. Three-tier pricing structure across premium, standard, and economy levels separates dual-circuit government-grade units from single-circuit commercial hardware and commodity surface mounts. Price differentiation hinges on UL 294 certification tier and rare-earth magnet sourcing transparency. Cost compression in standard-tier hardware is intensifying because of copper volatility, while educational buyers exhibit highest price sensitivity and federal security contractors show lowest.
Supply Chain Analysis
CE marking and UL 294 certification gating restricts supplier participation, with qualified production anchored in China, Germany, and the United States. Rare-earth magnet assemblies draw from Yangtze River Delta processing clusters, copper coil supply rests on Chilean and Zambian mining output, and armature plate fabrication centers on German and Japanese precision metalworking. Single-source neodymium dependency creates geopolitical exposure for North American assemblers. Distribution runs through value-added security integrators with cybersecurity competencies rather than traditional electrical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium-tier electromagnetic locks as cybersecurity certification requirements displace uncertified competitors and copper hedging programs stabilize input costs for integrated manufacturers.
For Market Incumbents: Anticipate specification authority migration toward IT security officers by embedding API interoperability and audit-logging capabilities that satisfy EU AI Act mandates. Defend position through captive coil-winding quality control and backward integration into rare-earth magnet sourcing that insulates against Chinese supply disruption. Prioritize dual-circuit certification maintenance as single-circuit vendors face disqualification from government facility bids. For New Entrants and Emerging Players: Cybersecurity-first product architectures offer viable entry wedges against established mechanical specialists lacking IT governance expertise. Target Indian hospital expansion zones where antimicrobial-finish electromagnetic locks face limited domestic competition and BIS certification creates import substitution openings. Lead with cloud-access SaaS integration partnerships that generate recurring revenue streams distinct from hardware margins. For Investors and Strategic Acquirers: Asymmetric upside sits with rare-earth-integrated mid-cap manufacturers controlling upstream magnet supply and coil-winding operations. Long-term viability favors vendors positioned across both physical security hardware and IT infrastructure governance domains. Watch for EU AI Act enforcement acceleration as inflection indicator compressing certification timelines and disqualifying non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Sourcing | Assa Abloy's upstream control insulates against Chinese neodymium processing concentration. |
| Dual-Circuit Certification Investment | Securitron's redundant monitoring capabilities capture German federal facility contracts under KBA directives. |
| Cloud-Access SaaS Partnership | Dynaloc's platform integration opens recurring-revenue models for mid-market commercial tenants. |
| Cybersecurity Penetration-Testing Validation | UL 2900 IoT certification creates competitive differentiation against legacy hardware vendors. |
| Compact Form Factor Specialization | Retrofit-focused engineering captures Shanghai Class A tower flush-mount specifications. |
Research Methodology
Direct dialogue with access-control system integrators, facility security managers, electromagnetic lock procurement officers, and building automation engineers grounded qualitative insights in operational reality. Secondary validation drew from UL certification databases, EU Construction Products Regulation filings, MIIT cybersecurity standards documentation, and BIS import registration records. Bottom-up installation volume estimates triangulated against top-down building automation retrofit spending patterns.
Bottom-up modeling aggregated unit shipments by product type, technology tier, and application vertical, then cross-referenced against top-down construction spending and security equipment capex allocations across the analysis window. Segmentation dimensions included mounting configuration, circuit architecture, end-use facility type, and regional regulatory cluster. CAGRs derived from regression analysis of historical penetration rates and projected replacement cycles, with inputs from rare-earth magnet supply constraints and smart building ordinance enforcement timelines.
The model holds under steady copper price bands and stable EU AI Act implementation schedules; deviation in neodymium export restrictions or accelerated cybersecurity certification deadlines would shift volume trajectories. Forecasts reflect documented assumptions regarding municipal retrofit mandate pacing and installer certification program expansion. A model refresh is warranted upon material change in MIIT networked access-control standards or NFPA 101 code amendments affecting electromagnetic lock deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
China Access Control Market
Access Control Systems
Japan Access Control Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
US Access Control Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Europe Pin-Based Access Control Market