
 Canada Access Control Market | 2026-2036
Canada Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Access Control Market Insights
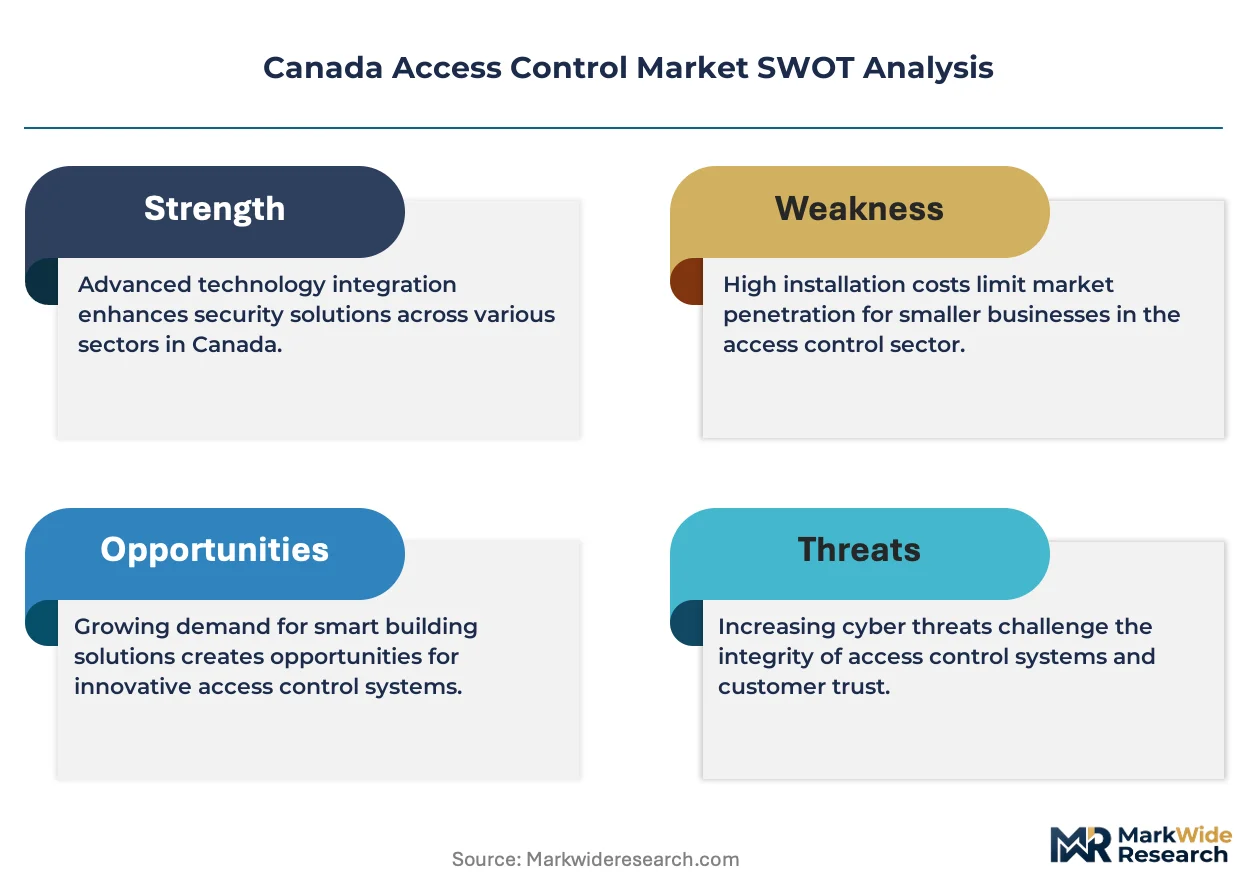
The capital-intensity divergence between hardware manufacturers and cloud-native platform providers is reorganizing competitive tiers in Canada. Allegion PLC leverages its captive manufacturing of electrified locks to sustain margin control across federal and provincial installations. Honeywell International Inc anchors its position through integrated building automation bundles that dominate Toronto and Vancouver commercial verticals. Genetec Inc differentiates via software-centric architecture that navigates Canadian privacy requirements for video-integrated access deployments.
Access control systems encompass electronic hardware and software solutions that authenticate credentials through RFID readers, biometric scanners, or mobile tokens to grant or deny physical entry to secured facilities. These systems serve critical commercial and institutional functions by logging entry events, enforcing time-based permissions, and centralizing security management across distributed sites. Biometric Systems and Mobile Credentials represent the fastest-expanding product and technology categories, with facial recognition modules capturing disproportionate R&D investment from vendors seeking Health Canada alignment on data handling protocols. Card-Based Systems remain the mature revenue baseline across Government Facilities and Educational Institutions, where legacy infrastructure upgrade cycles extend replacement timelines.
Health Canada's privacy guidance under PIPEDA shapes biometric data retention mandates, while the Communications Security Establishment issues cybersecurity certifications that gate federal procurement eligibility for access control vendors. Provincial building codes in Ontario and British Columbia increasingly reference CAN/ULC standards for fire-alarm integration with electronic locking mechanisms, tightening compliance thresholds for retrofit installations. Stakeholders must monitor whether Ottawa advances federal procurement rules that mandate domestic data residency for credential databases serving critical infrastructure sites.
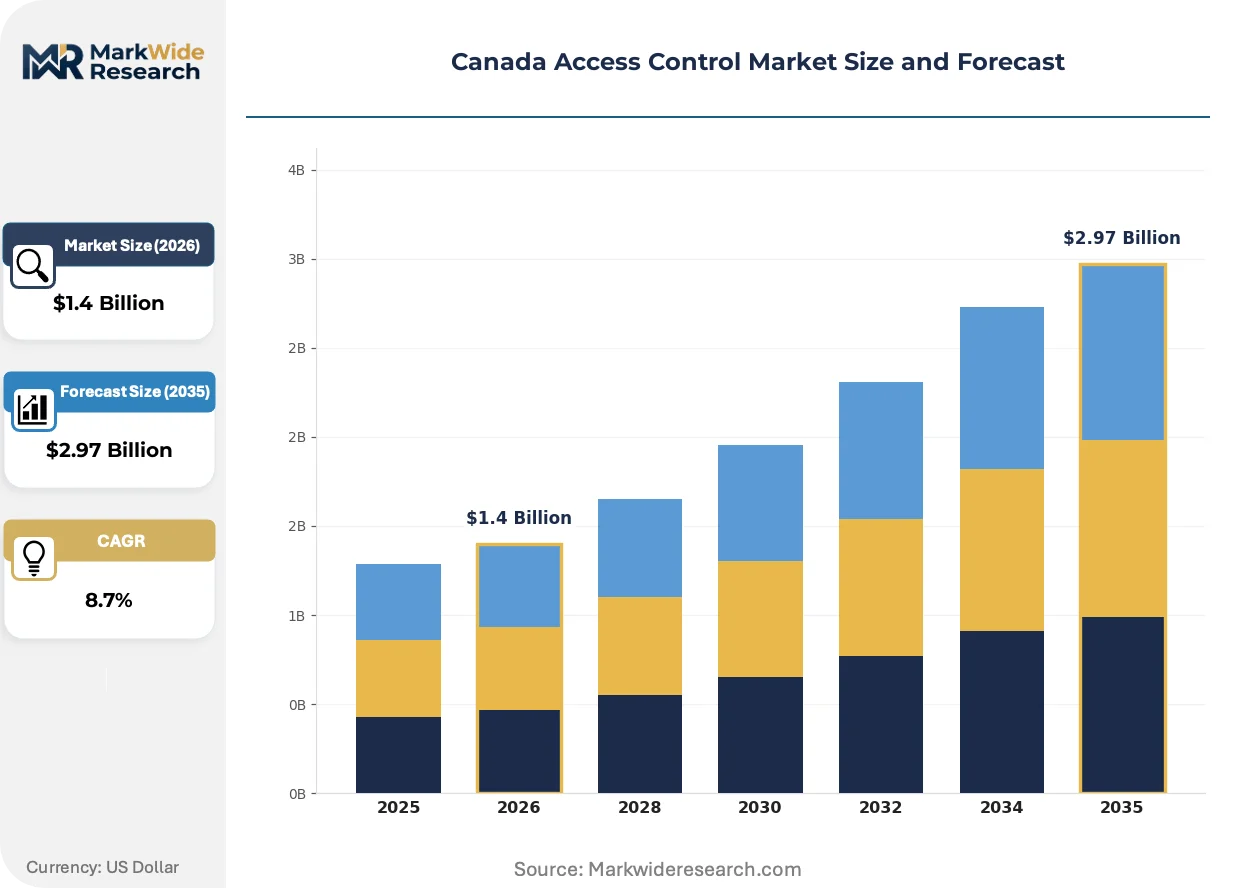
Market Dynamics
Health Canada's tightening PIPEDA guidance on biometric data retention is forcing vendors to reengineer credential architectures, while Ontario's commercial tower construction boom concentrates procurement power among Toronto-area developers.
Growth Catalysts
- PIPEDA Compliance Mandates:Health Canada's privacy guidance requires hardened data handling protocols, compelling federal facilities to upgrade legacy card systems with privacy-certified biometric modules.
- CAN/ULC Standards Integration:Provincial building codes in Ontario and British Columbia mandate fire-alarm interoperability with electronic locks, accelerating replacement cycles in institutional retrofit projects.
- Greater Toronto Area Development:Commercial tower construction in downtown Toronto and Mississauga generates concentrated demand for integrated access and building automation bundles.
Market Restraints
- Semiconductor Supply Concentration:RFID reader chip fabrication concentrates in East Asian foundries, exposing Canadian hardware vendors to lead-time volatility and tariff exposure.
- Legacy Infrastructure Lock-in:Educational institutions and government facilities operate 15-20 year card-based system lifecycles, compressing near-term replacement revenue.
- Domestic Data Residency Uncertainty:Pending federal procurement rules may mandate on-premise credential database hosting, complicating cloud-native platform deployments.
Strategic Opportunities
- Mobile Credential Convergence:Smartphone-based access tokens paired with Bluetooth Low Energy readers offer greenfield penetration in Vancouver's tech sector campuses.
- Video-Integrated Access Architectures:Software-centric platforms that unify video surveillance with door control address Health Canada's audit trail requirements for facial recognition deployments.
- Alberta Energy Sector Expansion:Oil sands facilities and Calgary corporate headquarters present underpenetrated demand for perimeter access and visitor management systems.
Industry Challenges
- Cybersecurity Certification Timelines:Communications Security Establishment evaluation cycles for federal procurement eligibility extend 18-24 months, delaying vendor revenue recognition.
- Interoperability Fragmentation:Proprietary credential formats between incumbent hardware vendors complicate multi-site enterprise rollouts requiring unified management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Access Control Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Card-Based Systems, Password Systems, Remote Access Systems End User: Government Facilities, Commercial Buildings, Residential Properties, Educational Institutions Installation Type: Wireless, Wired, Standalone, Integrated Systems Technology: RFID, Biometrics, Facial Recognition, Mobile Credentials |
| Companies Covered | Allegion PLC, Dahua Technology, Honeywell International Inc, Bosch Security System Inc, Hanwha Techwin Co Ltd, ASSA ABLOY AB Group, Genetec Inc, Johnson Controls, HID Global Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Access Control Market Trends and Innovations
Biometric authentication architectures are splitting between privacy-preserving edge processing and cloud-dependent facial recognition, reshaping vendor R&D allocation and procurement specifications across Canadian institutional buyers.
Facial recognition modules with on-device template storage are bifurcating the biometric hardware category. Federal facilities in Ottawa prioritize these edge-computing units to satisfy PIPEDA data minimization requirements. Health Canada's draft guidance on biometric retention is accelerating this split, compressing demand for server-dependent recognition systems.
Health Canada's PIPEDA enforcement guidance now mandates explicit consent protocols and 90-day deletion windows for biometric templates. Hardware vendors must certify data handling architectures through third-party privacy audits to maintain federal eligibility. Ontario's provincial procurement offices have adopted these federal standards, extending compliance burdens to municipal and educational buyers.
Enterprise buyers in Toronto's commercial vertical increasingly unbundle hardware procurement from software licensing and maintenance contracts. Building operators now source electrified locks and readers through construction contractors while negotiating SaaS management platforms separately. This purchasing fragmentation is most pronounced in Class A office developments where developer-controlled initial fit-out differs from long-term facility management ownership.
Canada Access Control Market Segmentation
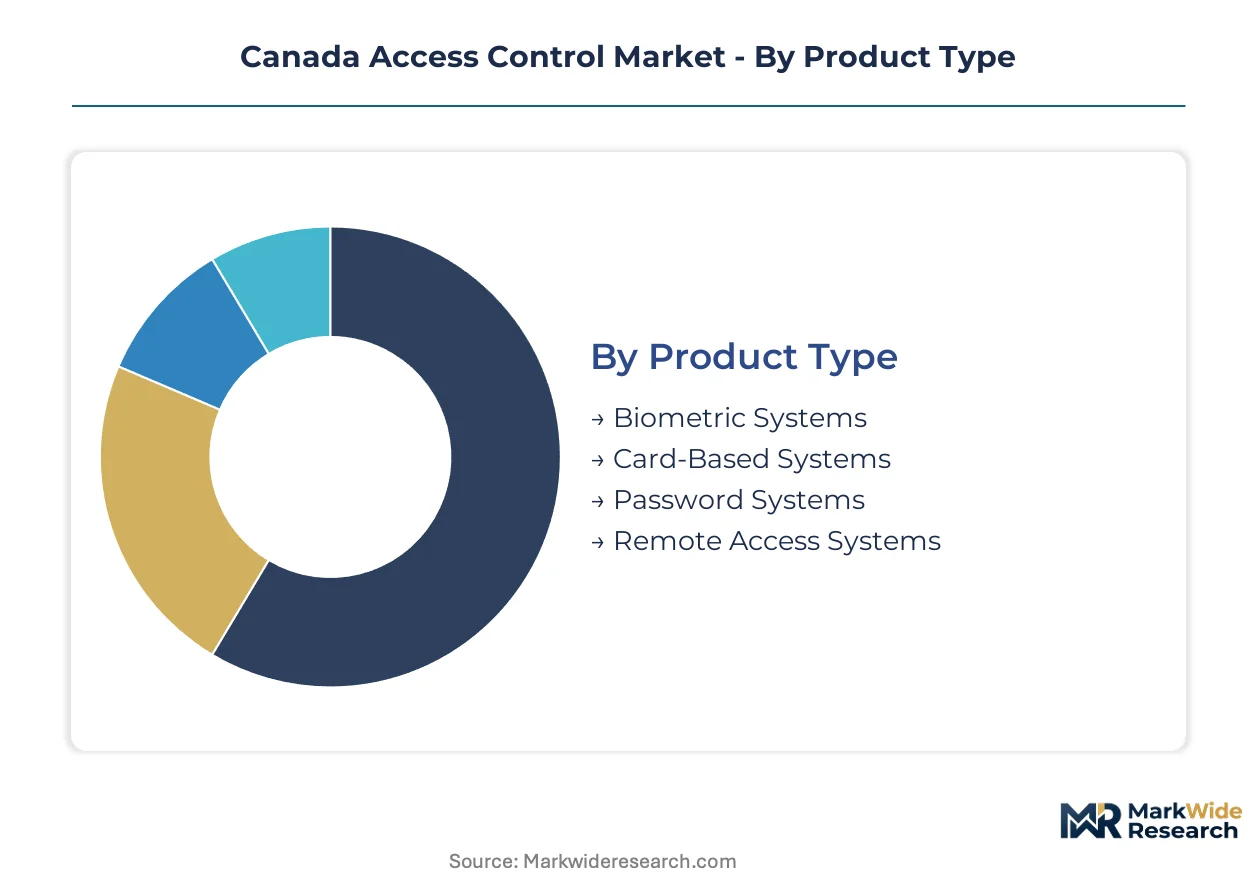
Segmentation in the Canada Access Control Market reveals distinct procurement pathways. Federal buyers prioritize biometric compliance under Health Canada guidance, while Toronto developers favor bundled automation systems.
Product Type:
Channel mix varies sharply: card-based hardware flows through construction contractors, biometric modules through security integrators, and cloud-native platforms direct to enterprise IT procurement.
- Biometric Systems:Edge-processing facial recognition units with on-device template storage satisfy PIPEDA data minimization mandates. Federal facilities in Ottawa deploy these for credential verification without centralized biometric databases.
- Card-Based Systems:Proximity and smart card readers constitute the mature installed base across educational campuses and provincial government buildings. Legacy 125kHz proximity systems persist in retrofit-constrained environments.
- Password Systems:Keypad entry with PIN authentication serves cost-sensitive residential and small commercial installations in secondary Canadian markets.
- Remote Access Systems:Browser-based and mobile-administered platforms enable distributed facility management for multi-site retail and logistics operators.
Card-Based Systems dominate installed base. Biometric Systems is where expansion concentrates.
End User:
Margin structure separates these segments: government facilities pay compliance premiums, commercial buildings drive volume, and residential properties compress hardware margins.
- Government Facilities:Federal buildings in Ottawa and provincial capitals mandate Communications Security Establishment certification for access control procurement. Health Canada's PIPEDA enforcement tightens biometric data handling specifications.
- Commercial Buildings:Class A office towers in Toronto's downtown core and Vancouver's Broadway Corridor generate concentrated demand for integrated access and building automation bundles.
- Residential Properties:Multi-unit condominiums in Montreal and Calgary adopt smartphone-based entry systems for amenity differentiation.
- Educational Institutions:Universities and K-12 districts operate extended replacement cycles, with 15-20 year card system lifecycles limiting near-term upgrade revenue.
Government Facilities command premium pricing for certified systems. Commercial Buildings represent the steepest expansion trajectory.
Installation Type:
Volume distribution reflects building vintage: new construction favors integrated and wireless architectures, while retrofits wrestle with wired infrastructure constraints.
- Wireless:Battery-powered locks with Wi-Fi or Bluetooth connectivity reduce installation labor in heritage building retrofits where conduit runs prove prohibitive.
- Wired:PoE and hardwired electrified locks deliver reliability for high-security federal and financial services installations.
- Standalone:Single-door electronic locks with local credential storage serve remote resource extraction sites and small retail locations.
- Integrated Systems:Unified access, video, and intrusion platforms anchor enterprise security operations centers in Toronto and Vancouver commercial portfolios.
Wired installations retain share in security-critical environments. Wireless architectures are gaining share fastest in retrofit applications.
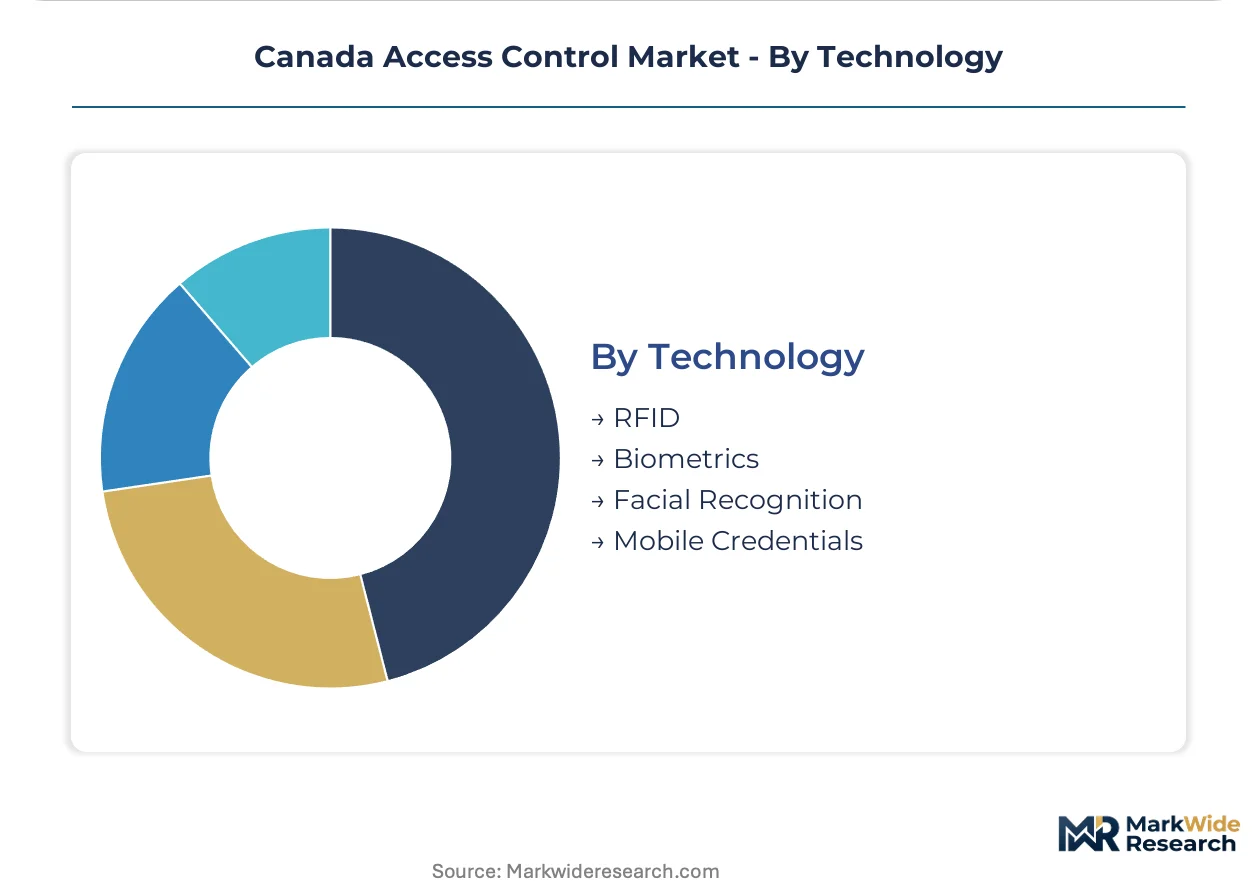
Technology:
Supply concentration shapes availability: RFID reader chips concentrate in East Asian fabrication, while facial recognition algorithm development localizes to North American and European software vendors.
- RFID:13.56MHz smart cards and UHF long-range readers serve parking and logistics gate applications across Canadian distribution centers.
- Biometrics:Fingerprint and iris recognition modules with template encryption address Health Canada data retention requirements for healthcare facility deployments.
- Facial Recognition:3D depth-sensing cameras with liveness detection capture disproportionate R&D investment as vendors align with federal privacy guidance.
- Mobile Credentials:Smartphone-based access tokens using Bluetooth Low Energy and NFC protocols penetrate Vancouver tech campuses and Toronto co-working developments.
RFID anchors legacy infrastructure. Mobile Credentials is where vendor R&D and pilot deployments concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario consumes access control systems differently from other provinces, prioritizing commercial tower integration bundles over federal compliance premiums. Quebec and Alberta follow distinct procurement pathways shaped by linguistic contracting requirements and energy sector security demands respectively.
Ontario
Toronto's downtown core and Mississauga corridor drive concentrated demand for integrated building automation systems. The Ontario Building Code mandates CAN/ULC fire-alarm interoperability with electronic locks, accelerating replacement cycles in institutional retrofits. Class A office developments in the Greater Toronto Area unbundle hardware procurement from SaaS management platforms.
Quebec
Montreal's multi-unit condominium market adopts smartphone-based entry systems for amenity differentiation. Provincial procurement regulations require French-language documentation for security integrators bidding on government contracts. Laval and Quebec City educational campuses operate extended 15-20 year card system lifecycles that compress near-term upgrade revenue.
British Columbia
Vancouver's Broadway Corridor generates demand for unified access and video platforms serving tech sector campuses. The British Columbia Building Code references CAN/ULC standards for fire-alarm integration with electronic locking mechanisms. Victoria's provincial government facilities mandate Communications Security Establishment certification for access control procurement.
Alberta
Calgary corporate headquarters and oil sands facilities present underpenetrated demand for perimeter access and visitor management systems. Provincial energy sector regulations require hardened credential architectures for critical infrastructure sites. Edmonton federal facilities align with Health Canada PIPEDA guidance on biometric data retention mandates.
Atlantic Canada
Halifax government facilities and St. John's offshore energy operations drive specialized maritime security requirements. Federal procurement rules for Atlantic Canada infrastructure projects increasingly reference domestic data residency specifications. Regional universities in Nova Scotia and New Brunswick maintain legacy card-based infrastructure with constrained replacement budgets.
Canada Access Control Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Canada's access control market. Hardware manufacturers with captive lock production control margin structures across federal installations, while software-centric vendors navigate privacy certification requirements. Two strategic archetypes dominate: electrified hardware fabricators bundling physical security components, and cloud-native platform providers unbundling management software from device procurement. Competitive moves concentrate on portfolio diversification into adjacent building automation categories and strategic partnerships with construction contractors controlling tower development specifications.
Within the integrated hardware tier, Allegion PLC and Honeywell International Inc exemplify contrasting approaches to the Canadian market. Allegion leverages its manufacturing footprint to sustain margin control across provincial and federal installations. Honeywell anchors its position through building automation bundles that dominate Toronto and Vancouver commercial verticals. Genetec Inc occupies a distinct position as a software-centric vendor navigating Health Canada privacy requirements for video-integrated access deployments.
| Leading Market Players |
|---|
| Allegion PLC |
| Dahua Technology |
| Honeywell International Inc |
| Bosch Security System Inc |
| Hanwha Techwin Co Ltd |
| ASSA ABLOY AB Group |
| Genetec Inc |
| Johnson Controls |
| HID Global Corporation |
| Others |
Pricing and Supply Chain Analysis
Edge-processing biometric modules replacing server-dependent facial recognition systems are simultaneously shifting procurement toward North American software vendors and compressing hardware margins as on-device storage eliminates recurring cloud subscription tiers. This substitution dynamic redistributes value capture from SaaS platforms to electrified lock manufacturers while exposing integrators to compressed installation complexity pricing.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value capture across federal installations where Communications Security Establishment certification requirements extend vendor relationships. Three-tier pricing structure across premium, standard, and economy levels separates CSE-certified biometric bundles from Ontario Building Code-compliant fire-alarm integrated systems and cost-sensitive residential keypad offerings. Pricing pressure stems from semiconductor cost volatility in East Asian fabrication, squeezing RFID reader margins. Educational institutions exhibit highest price sensitivity due to constrained capital budgets, while Ottawa federal facilities accept compliance premiums.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Shanghai and Busan extend lead times for RFID reader chip shipments into Vancouver and Prince Rupert ports. Hardware fabrication concentrates in China, Taiwan, and South Korea, with Canadian vendors drawing from these sources for proximity card readers and biometric sensors. Supply chain risk centers on single-source vulnerability for 13.56MHz smart card controllers. Distribution runs through security integrators serving Toronto commercial towers and construction contractors controlling new build specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the unbundling of hardware procurement from SaaS management platforms, as Toronto Class A developers separate initial fit-out purchasing from long-term facility ownership structures.
For Market Incumbents: Shield federal market position by deepening captive manufacturing of electrified locks with PIPEDA-compliant edge-processing biometric modules, while extending CSE certification maintenance to block cloud-native platform entrants from Ottawa procurement cycles. Priority lever rests on channel control through construction contractor partnerships dominating Greater Toronto Area tower specifications. For New Entrants and Emerging Players: Post-installation analytics and predictive maintenance services for legacy card-based infrastructure represent the service-layer gap where incumbents under-serve, creating entry points for software-centric vendors. Alberta oil sands perimeter access and Calgary corporate headquarters present the most penetrable geography. Go-to-market angle targets energy sector security managers through visitor management system pilots. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hardware manufacturers holding federal installation relationships but lacking software platform capabilities. Five-to-ten year viability hinges on biometric-to-mobile credential transition pacing. Acquisition target archetype: regional security integrators with Toronto commercial tower relationships. Signal to watch is Health Canada advancement of domestic data residency mandates for critical infrastructure credential databases.| Strategic Initiative | Industry Significance |
|---|---|
| PIPEDA-Certified Biometric Module Development | Health Canada compliance gates federal procurement eligibility for Ottawa installations. |
| Construction Contractor Partnership Expansion | Toronto tower developers control initial access system specifications and subcontractor selection. |
| Mobile Credential Platform Launch | Vancouver tech campuses pilot Bluetooth Low Energy smartphone access for amenity differentiation. |
| Alberta Energy Sector Sales Force Buildout | Oil sands facilities present underpenetrated demand for hardened perimeter access architectures. |
| Video-Integrated Access Software Acquisition | Unified surveillance-door control platforms satisfy Health Canada audit trail requirements. |
Research Methodology
A spread of perspectives from security integrators, federal procurement officers, building automation engineers, and construction project managers converged on the working assumptions underlying demand sizing. Primary fieldwork combined structured interviews with Toronto-area facility managers and Ottawa critical infrastructure security directors. Secondary validation drew from Communications Security Establishment procurement databases, Ontario Building Code amendment records, Health Canada PIPEDA guidance documents, and Canadian Construction Association project tracking. Bottom-up installation estimates triangulated against top-down building stock analysis.
Segmentation dimensions modeled span product type, end-user vertical, installation architecture, and credential technology across the analysis window. Analytical framework projected replacement cycles for legacy card systems against greenfield biometric and mobile credential adoption curves. CAGRs derived from weighted scenario analysis incorporating federal compliance mandate timing, commercial construction permit volumes, and semiconductor supply normalization assumptions. Industry-specific inputs included CSE certification backlog estimates and provincial building code amendment schedules.
Forecasts assume regulatory continuity in Health Canada PIPEDA enforcement and Communications Security Establishment procurement frameworks; material policy shifts would require re-modeling credential architecture demand. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Digital Security Control Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Network Access Control Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Locks Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Global Automated Border Control Market