
 Pre-Departure Clearance System Market | 2026-2036
Pre-Departure Clearance System Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Departure Clearance System Market Analytics
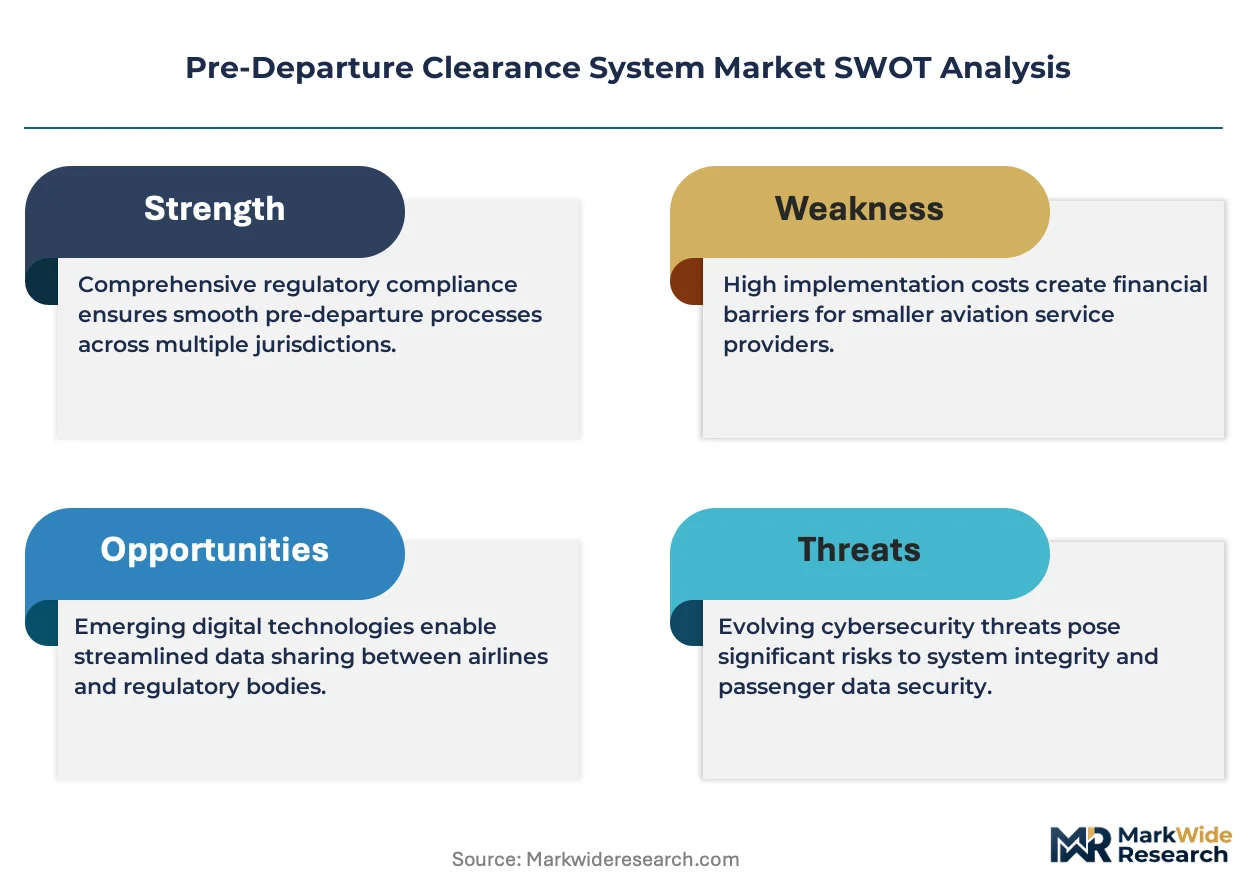
Project finance and long-term leasing of avionics infrastructure is tilting competitive dynamics toward vendors with balance-sheet capacity to underwrite multi-year contracts. Honeywell International leverages its integrated flight-deck ecosystem to bundle clearance services with hardware refresh cycles. SITA anchors its position through ownership of the AIRCOM messaging backbone that carries PDC and DCL traffic across three continents. ForeFlight competes by specializing in mobile-native pilot workflows that reduce training friction for regional operators.
A pre-departure clearance system electronically transmits flight clearance instructions from air traffic control to aircraft, replacing voice radio exchanges with data-link protocols such as ACARS or CPDLC operating over VHF or satellite channels. The system eliminates read-back errors, reduces frequency congestion, and enables gate-to-gate digital trajectory management in high-density terminal airspace. Cloud-based deployments are capturing the fastest expansion as aviation authorities outsource infrastructure to avoid capital-intensive ground-station builds, while on-premises installations retain dominance among defense-sensitive operators and states with strict data-sovereignty rules. Custom solutions command the deepest margin pools where airlines require bespoke integrations with proprietary operations-control software.
FAA NextGen mandates and EUROCONTROL's Link 2000+ program shape product roadmaps by requiring CPDLC capability for core European routes and selected US terminal domains, effectively gating market access for non-compliant vendors. EASA certification standards for ground-system software integrity add a secondary compliance layer that favors suppliers with established European airworthiness credentials. Stakeholders must monitor which regulators will mandate departure-clearance data logging for carbon-accounting audit trails, as this would force retrofits across legacy installed bases.
Market Dynamics
Digital trajectory management is compressing clearance-cycle times from minutes to seconds, forcing infrastructure vendors to decouple hardware refresh from software deployment schedules.
Growth Catalysts
- FAA NextGen mandates:Terminal domain CPDLC requirements are pulling legacy voice-system replacements across United States hub airports, creating immediate procurement windows for compliant ground-station providers.
- Gate-to-gate automation:Airlines operating from Singapore Changi and Frankfurt are demanding contiguous data-link coverage from pushback to top-of-climb, expanding addressable infrastructure spend per airport.
- Cloud outsourcing:ANSPs in Germany and the Netherlands are abandoning capital-intensive ground-station builds in favor of subscription-based clearance services, accelerating vendor revenue recognition.
Market Restraints
- Defense-sensitive operator requirements:Military and state-airline fleets in France and Israel insist on on-premises installations with air-gapped redundancy, capping cloud-service penetration in high-margin segments.
- Data-sovereignty fragmentation:China's GB standards and Russia's FSB certification create incompatible national clearance networks, fragmenting vendor R&D across non-interoperable protocol stacks.
- Legacy VHF infrastructure sunk costs:Regional airports in Italy and Spain face stranded asset risk if they accelerate ACARS-to-CPDLC transitions before depreciation cycles complete.
Strategic Opportunities
- Carbon-accounting audit mandates:EASA and the United Kingdom CAA are evaluating departure-clearance data logging requirements for emissions verification, which would force retrofits across Europe's installed base of legacy systems.
- Mobile-native pilot workflows:Regional operators in Australia and Brazil are bypassing traditional FMS-integrated solutions for tablet-based clearance receipt, opening a channel not controlled by incumbent avionics bundlers.
- Satellite-based CPDLC:Iridium Certus and Inmarsat SwiftBroadband convergence with terrestrial VHF is enabling oceanic and remote-airspace clearance automation where ground infrastructure was previously uneconomical.
Industry Challenges
- Multi-protocol software integrity certification:Vendors must maintain simultaneous EASA, FAA, and CAAC ground-system approvals, with each regulator demanding distinct failure-mode analysis documentation that extends development timelines.
- Legacy FMS integration complexity:Airlines operating mixed fleets of Boeing and Airbus aircraft face non-standard message formats between manufacturer-specific avionics and third-party clearance applications, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Departure Clearance System Market |
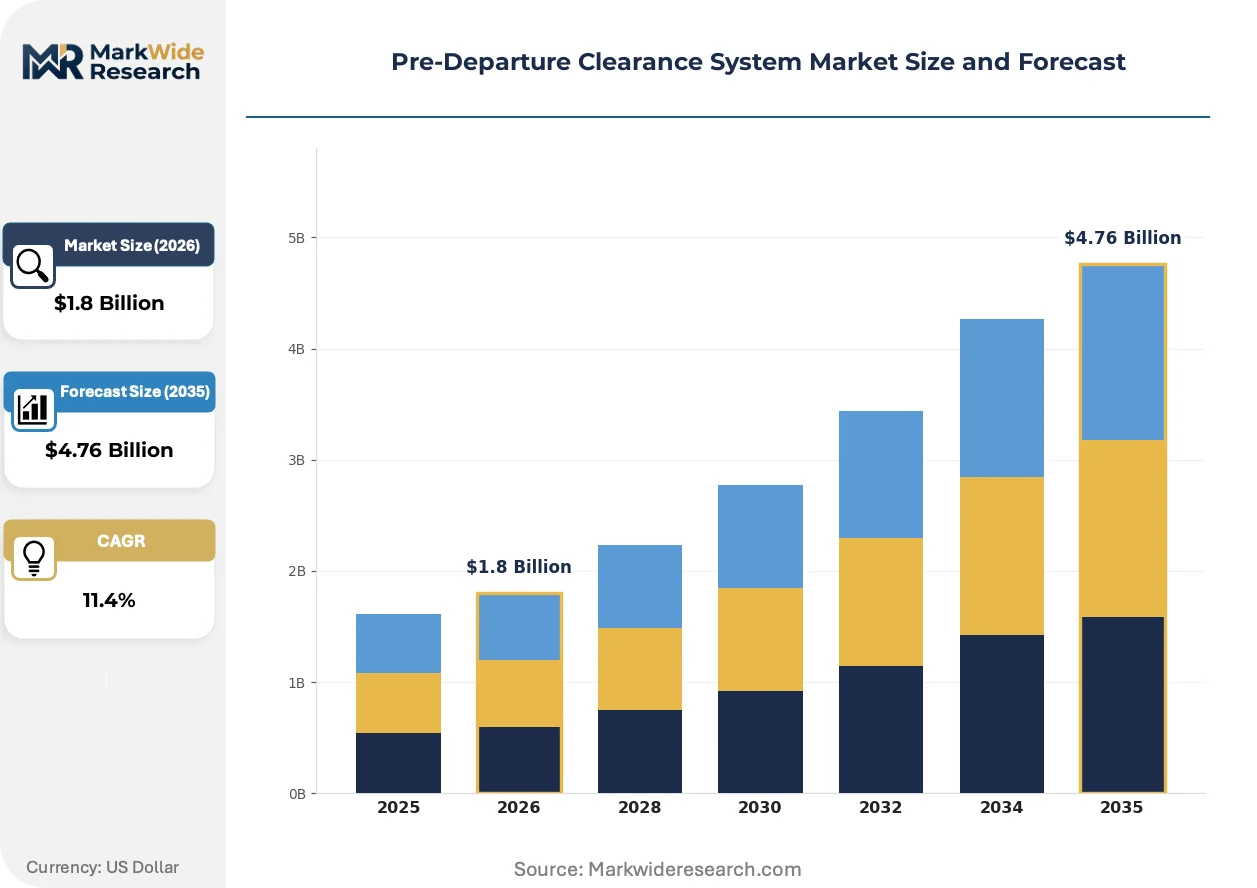
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, On-Premises, Hybrid, Desktop End User: Aviation Authorities, Airlines, Freight Forwarders, Travel Agencies Solution: Custom Solutions, Off-the-Shelf Software, API Integrations, Mobile Apps Deployment: Public Cloud, Private Cloud, Multi-Tenant, Single-Tenant |
| Companies Covered | ForeFlight, Honeywell International, Satcom Direct, Amadeus IT Group, SITA, RTX Corporation, Thales Group, Airbus, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Departure Clearance System Market Evolving Landscape
Pre-departure clearance systems are undergoing a protocol transition that privileges software-defined architectures over purpose-built hardware, compressing vendor margins while expanding service-addressable markets.
CPDLC-ATN B1 over IP is rendering obsolete the ACARS character-set limitations that constrained message length and formatting flexibility. Low-cost carriers in Southeast Asia are deploying this stack faster than legacy full-service operators, attracted by reduced per-message satellite charges. The shift is rendering obsolete the hardware-centric business models of traditional ground-station manufacturers who bundled proprietary modems with long-term service contracts.
EUROCONTROL's Link 2000+ program mandates CPDLC capability for core European routes by 2027, with non-compliant aircraft facing mandatory re-routing or slot penalties. This is forcing rapid avionics upgrades among European charter operators who previously deferred capital spend. The regulation is compressing competitive timelines for ground-system vendors seeking EASA certification, with first-mover advantage accruing to those who completed software-integrity audits before the mandate announcement.
Airlines are unbundling clearance services from integrated flight-planning suites, treating data-link connectivity as a standalone procurement category with distinct SLA negotiations. Regional operators in Canada and Scandinavia are leading this disaggregation, sourcing CPDLC ground services from specialized messaging providers while retaining incumbent vendors for flight-planning software. The pattern is visible most acutely among carriers with fewer than fifty aircraft, where bundled avionics economics previously favored single-source relationships.
Pre-Departure Clearance System Market Segmentation
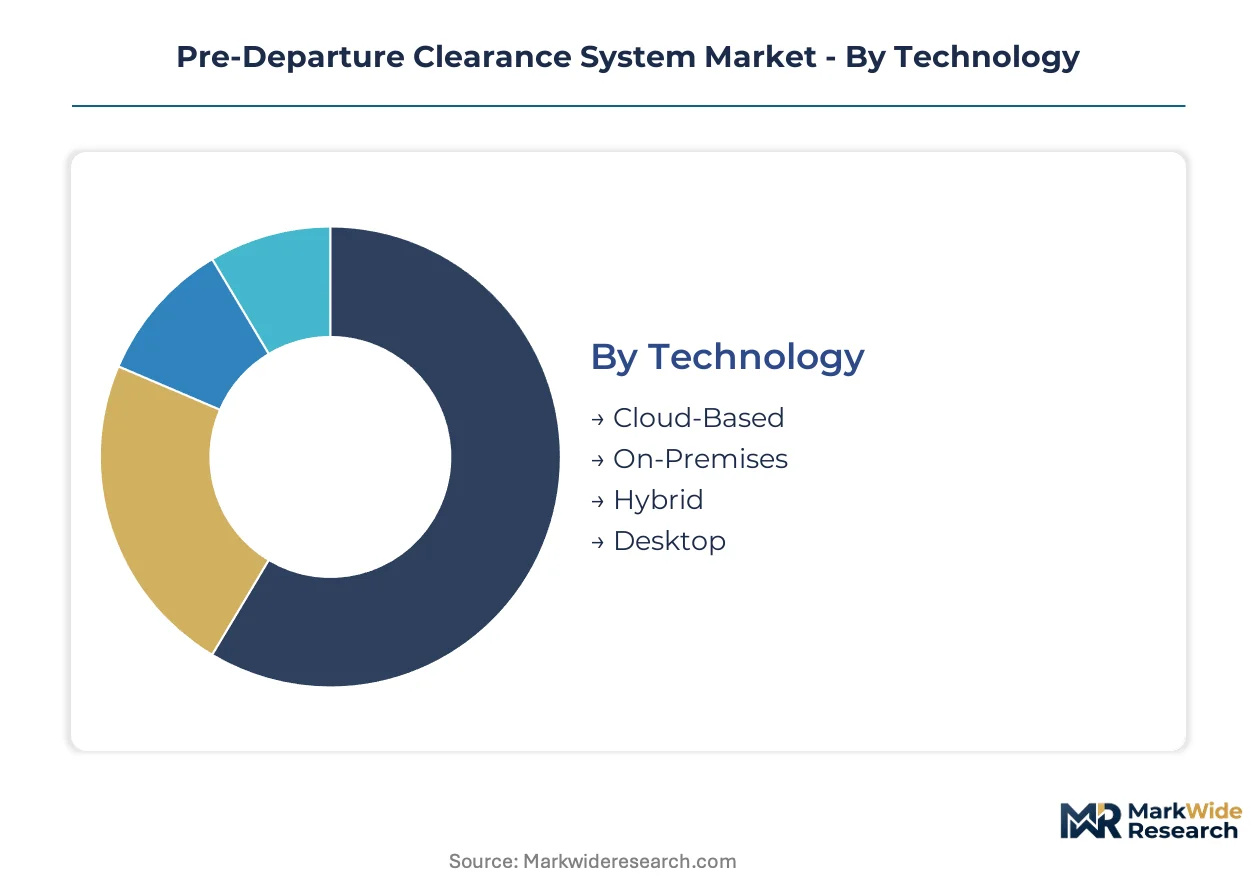
Segmentation in pre-departure clearance systems reveals how procurement priorities diverge between capital-constrained regional operators and hub carriers demanding gate-to-gate automation. Technology choices, end-user workflows, and deployment architectures each create distinct margin pools and competitive entry points for vendors.
Technology:
Cycle times vary dramatically across technology segments, with cloud-native stacks refreshing quarterly while on-premises hardware lingers across decade-long depreciation schedules.
- Cloud-Based:Multi-tenant SaaS architectures enable ANSPs in Germany and the Netherlands to outsource ground-station infrastructure without capital deployment. Subscription pricing aligns vendor incentives with uptime performance, accelerating procurement decisions among budget-constrained authorities.
- On-Premises:Air-gapped installations with redundant VHF modems serve military fleets and state airlines requiring sovereign data control. France and Israel maintain strict requirements here, preserving premium pricing despite higher total cost of ownership.
- Hybrid:Split architectures route sensitive flight-plan data through private links while pushing non-critical telemetry to public cloud endpoints.
- Desktop:Legacy thick-client applications persist at regional airports with limited IT staffing, though maintenance contracts face renewal pressure.
On-Premises deployments anchor the volume base among defense-sensitive operators while Cloud-Based configurations gain share at the steepest rate as European ANSPs abandon owned infrastructure.
End User:
Procurement sophistication correlates directly with fleet scale and regulatory exposure, fragmenting vendor sales motions across dramatically different buying committees.
- Aviation Authorities:National regulators mandate protocol standards and certify ground-system integrity, controlling market access through EASA and FAA approval gates. Their procurement emphasizes multi-year service availability and audit logging for trajectory verification.
- Airlines:Hub carriers at Singapore Changi and Frankfurt demand contiguous data-link coverage from pushback to top-of-climb, driving integrated hardware-software bundles with strict SLA penalties.
- Freight Forwarders:Cargo operators prioritize API accessibility for warehouse management system integration, valuing real-time clearance status over pilot-interface refinements.
- Travel Agencies:Niche demand concentrates on passenger notification services, with marginal influence on core infrastructure procurement decisions.
Airlines command the largest contract values while Aviation Authorities determine competitive eligibility through certification requirements that reshape vendor R&D priorities.
Solution:
Margin structures invert between standardized offerings with volume economics and bespoke developments capturing deep integration premiums.
- Custom Solutions:Proprietary middleware development connects airline operations-control software with manufacturer-specific avionics formats. Mixed Boeing-Airbus fleets drive demand here, particularly among legacy carriers with decades of accumulated operations logic.
- Off-the-Shelf Software:Pre-certified CPDLC clients accelerate deployment for regional operators lacking internal avionics engineering teams, compressing implementation timelines from years to months.
- API Integrations:RESTful endpoints enable third-party flight-planning tools to embed clearance receipt without full system replacement, appealing to disaggregating procurement strategies in Canada and Scandinavia.
- Mobile Apps:Tablet-native pilot workflows reduce training friction for regional operators in Australia and Brazil, bypassing traditional FMS-integrated solutions controlled by incumbent avionics vendors.
Off-the-Shelf Software dominates transaction counts among mid-tier carriers while Custom Solutions extract the highest margins from complex fleet integration requirements.
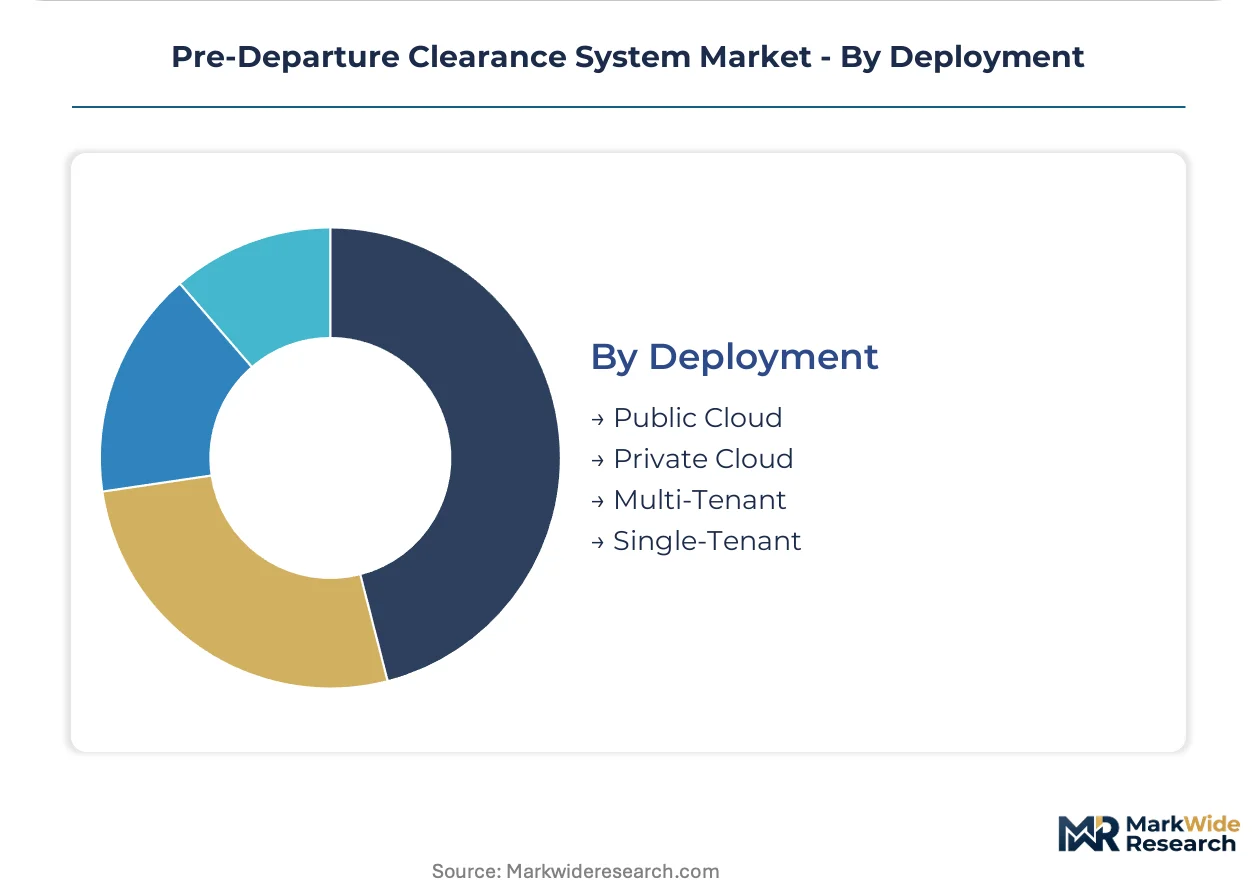
Deployment:
Architecture choices reflect sovereignty concerns and multi-tenant efficiency trade-offs that reshape vendor infrastructure economics.
- Public Cloud:Shared infrastructure pools deliver lowest per-message costs for low-cost carriers in Southeast Asia, with satellite charge reductions accelerating CPDLC-ATN B1 adoption over legacy ACARS.
- Private Cloud:Dedicated virtual environments satisfy data-residency requirements without full on-premises hardware commitment, gaining traction among European charter operators facing compressed compliance timelines.
- Multi-Tenant:Resource sharing across unrelated operators maximizes ground-station utilization at secondary airports with irregular traffic patterns.
- Single-Tenant:Isolated instances serve carriers with strict change-control protocols or classified mission profiles.
Multi-Tenant deployments spread fixed infrastructure costs widest while Private Cloud configurations expand most quickly among operators balancing compliance flexibility with capital avoidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Singapore where gate-to-gate automation commands premium infrastructure spend, while regional airports in Italy and Spain face stranded asset risk from legacy VHF depreciation cycles.
United States
FAA NextGen terminal domain mandates are pulling legacy voice-system replacements across hub airports. The FAA requires CPDLC capability for selected terminal domains, creating immediate procurement windows for compliant ground-station providers. Chicago O'Hare and Atlanta Hartsfield-Jackson anchor demand as these hubs modernize air traffic management infrastructure under federal mandate timelines.
Germany
ANSPs are abandoning capital-intensive ground-station builds in favor of subscription-based clearance services. EUROCONTROL's Link 2000+ program harmonizes requirements across core European routes, with non-compliant aircraft facing mandatory re-routing. Frankfurt Airport demands contiguous data-link coverage from pushback to top-of-climb, expanding addressable infrastructure spend per installation.
Singapore
Changi Airport's gate-to-gate automation requirements are setting regional standards for contiguous data-link coverage. The Civil Aviation Authority of Singapore prioritizes digital trajectory management to reduce ground delays in high-density Southeast Asian airspace. The city-state's hub status attracts vendor investment in multi-tenant cloud architectures serving low-cost carriers across the ASEAN corridor.
France
Military and state-airline fleets insist on on-premises installations with air-gapped redundancy, capping cloud-service penetration in high-margin segments. EASA certification standards for ground-system software integrity add compliance layers favoring suppliers with established European airworthiness credentials. Paris-Charles de Gaulle maintains hybrid deployments balancing sovereign data control with multi-tenant efficiency for commercial traffic.
Netherlands
Schiphol Airport's ANSP is outsourcing infrastructure to avoid capital-intensive ground-station builds, accelerating vendor revenue recognition through subscription models. EUROCONTROL harmonization requirements align Dutch procurement with broader European CPDLC mandates. Amsterdam's hub position drives demand for split architectures routing sensitive flight-plan data through private links while pushing non-critical telemetry to public cloud endpoints.
Pre-Departure Clearance System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the protocol stack. The vendor base organizes around three strategic archetypes: avionics bundlers with integrated flight-deck ecosystems, messaging backbone operators controlling data-link infrastructure, and mobile-native specialists reducing training friction for regional operators. Consolidation pressures favor balance-sheet capacity to underwrite multi-year contracts, while disaggregating procurement patterns in Canada and Scandinavia open entry points for specialized providers.
Within the integrated systems tier, Honeywell International and Thales Group exemplify platform bundlers leveraging hardware refresh cycles to anchor recurring clearance service revenue. SITA occupies a distinct position as messaging infrastructure owner, with AIRCOM backbone carriage spanning three continents. ForeFlight represents the mobile-native archetype, capturing regional operators in Australia and Brazil through tablet-based workflows that bypass traditional FMS integration complexity. These three patterns—bundled avionics, backbone control, and mobile disruption—structure competitive rivalry across procurement segments.
| Leading Market Players |
|---|
| ForeFlight |
| Honeywell International |
| Satcom Direct |
| Amadeus IT Group |
| SITA |
| RTX Corporation |
| Thales Group |
| Airbus |
| L3Harris Technologies |
| Others |
Value Network & Pricing Analysis
Ground-station hardware manufacturing concentrates in Germany and the United States, anchoring margin capture among avionics bundlers who control proprietary modem production while cloud-native vendors compete on subscription economics at lower per-unit yields.
Pricing Analysis
The customization-premium spread separates configured-to-order middleware development for mixed Boeing-Airbus fleets from standardized CPDLC client deployments. Three-tier pricing structure across premium, standard, and economy levels reflects EASA certification grade, after-sales service bundling, and volume scale. Cost compression in the standard tier is intensifying because low-cost carriers in Southeast Asia favor per-message satellite pricing over capital-intensive hardware purchases. Regional operators with fewer than fifty aircraft exhibit highest price sensitivity, while hub carriers at Frankfurt and Singapore Changi accept premium positioning for gate-to-gate SLA guarantees.
Supply Chain Analysis
Contract manufacturing for VHF modem assemblies and satellite transceiver modules concentrates with EMS providers in Germany, the United States, and Singapore. Component sourcing draws from specialized semiconductor foundries for aviation-grade processors, precision RF filter manufacturers, and certified antenna subsystem suppliers. Single-source vulnerability in aviation-specific integrated circuits creates exposure to extended lead times when foundry capacity reallocates toward consumer electronics. Distribution runs through direct OEM relationships for integrated flight-deck systems and specialized aviation distributors for aftermarket retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pre-departure clearance system market sits at a platform-economics inflection where CPDLC-ATN B1 over IP is displacing ACARS-centric hardware bundling, rewarding vendors who control messaging infrastructure rather than proprietary modem production.
For Market Incumbents: Insulate recurring revenue by deepening captive supply of cloud-native clearance services and accelerating EASA software-integrity certification ahead of EUROCONTROL's Link 2000+ enforcement deadlines. Mobile-native specialists like ForeFlight threaten regional operator relationships previously secured through FMS-integrated hardware refresh cycles. Vertical integration into satellite messaging partnerships with Iridium or Inmarsat preserves data-link control against disaggregating procurement patterns in Canada and Scandinavia. For New Entrants and Emerging Players: Tablet-native pilot workflows in Australia and Brazil represent the most penetrable entry point, bypassing incumbent avionics bundlers who struggle with training friction reduction. API-first clearance receipt integration for regional operators disaggregating from bundled flight-planning suites offers a channel not controlled by Honeywell or Thales. Target ANSPs in the Netherlands and Germany abandoning capital-intensive ground-station builds through subscription-based SaaS positioning with uptime-based pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed messaging infrastructure operators holding AIRCOM-class backbone carriage across multiple continents. Long-term viability hinges on protocol transition completion from ACARS to CPDLC-ATN B1 and carbon-accounting audit mandate timing across European jurisdictions. Monitor EASA and United Kingdom CAA regulatory filings for departure-clearance data logging requirements as the inflection signal forcing retrofit spend across legacy installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| CPDLC-ATN B1 Protocol Migration | Eliminates ACARS message-length constraints for low-cost carriers in Southeast Asia. |
| Cloud-Native Ground Station Outsourcing | Enables German and Dutch ANSPs to shift capital expenditure to operational budgets. |
| Satellite-Terrestrial Hybrid Deployment | Extends clearance automation to oceanic routes via Iridium Certus convergence. |
| Mobile-Native Pilot Interface Development | Bypasses FMS integration complexity for regional operators in Australia and Brazil. |
| Carbon-Accounting Audit Trail Integration | Positions vendors for mandatory EASA logging requirements across European fleets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA NextGen implementation documentation, EUROCONTROL Link 2000+ program filings, and EASA ground-system certification registers. Conversations with air traffic management procurement officers, airline avionics engineering directors, ANSP infrastructure planners, and CPDLC software vendors informed demand-side validation. Supply-side perspectives drew from ground-station manufacturers, satellite messaging operators, and aviation electronics distributors. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against ANSP budget disclosures anchored market sizing.
Forecast inputs incorporate technology transition timelines, regulatory mandate enforcement schedules, and fleet avionics refresh cycles across the projection horizon. Segmentation modeling spans deployment architecture, end-user procurement sophistication, solution customization depth, and regional regulatory cluster. CAGRs derive from protocol adoption curves, cloud outsourcing penetration rates, and gate-to-gate automation investment intensity. Industry-specific inputs include EUROCONTROL compliance deadlines and FAA terminal domain CPDLC requirement phasing.
Practitioners should monitor EASA carbon-accounting audit proposals, FAA NextGen mandate expansion announcements, and CPDLC-ATN B1 adoption rates among low-cost carriers for early signals of forecast revision. Assumptions reflect current regulatory trajectories and infrastructure investment commitments. Quarterly review of ANSP procurement disclosures and airline fleet avionics upgrade announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Smart Lock Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Vehicle Security System Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
North America Access Control Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
RFID Locks Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market