
 Global Industrial Security Systems Market | 2026-2036
Global Industrial Security Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Security Systems Market Foresight
Artificial intelligence-based video analytics is broadening the functional scope of perimeter detection beyond traditional motion sensing. Honeywell International Inc. leverages its building automation heritage to integrate physical and cyber security dashboards for energy facilities. Siemens AG anchors European demand through IEC 62443-compliant industrial control protection. Bosch Security Systems specializes in thermal imaging arrays for unmanned perimeter patrol in harsh-climate extraction sites.
Industrial security systems encompass integrated hardware and software platforms designed to protect physical assets, operational technology networks, and personnel within manufacturing and infrastructure environments; these deployments typically operate across temperature ranges from minus 40 to plus 70 degrees Celsius and achieve mean-time-between-failures exceeding 100,000 hours for mission-critical sensors. Video surveillance occupies the largest product category as refinery operators mandate continuous flare-stack and tank-farm monitoring, while biometric authentication represents the fastest-growing technology segment as maritime terminals replace card-based access with palm-vein readers to prevent credential sharing. Access control systems command premium margins in data center applications where multi-factor authentication gates every mantrap entry.
The US EPA enforces risk management program requirements that compel chemical facilities to deploy layered detection and response architectures, while the EU AI Act imposes conformity assessments on automated surveillance systems deployed in public-adjacent industrial zones. IEC 62443 and NIST SP 800-82 together shape procurement specifications for OT-security integration, effectively filtering vendors without certified development lifecycles. Stakeholders must weigh the capital efficiency of cloud-managed security platforms against sovereignty requirements that favor on-premise command centers in defense and nuclear applications.
Market Dynamics
Edge AI video analytics is consolidating supplier hierarchies as petrochemical operators retire rule-based detection systems, forcing vendors to requalify around neural-network inference performance rather than hardware durability alone.
Growth Catalysts
- EPA Risk Management Plan Updates:Chemical processing facilities in the United States must deploy layered detection architectures, expanding security budgets for integrated perimeter and cyber-physical systems.
- IEC 62443 Certification Mandates:European critical infrastructure operators now require certified secure development lifecycles for industrial control protection, filtering procurement toward compliant vendors.
- Maritime Terminal Modernization:Palm-vein biometric authentication is replacing card-based access at container ports to prevent credential sharing and enable contactless personnel tracking.
Market Restraints
- Semiconductor Supply Concentration:Thermal imaging sensor fabrication concentrates in East Asian foundries, exposing project timelines to single-source vulnerability for harsh-climate extraction deployments.
- EU AI Act Conformity Costs:Automated surveillance systems in public-adjacent industrial zones face mandatory third-party assessment, extending deployment cycles by twelve to eighteen months.
- Legacy System Entrenchment:Decades-old analog CCTV infrastructure at refineries creates technical debt that complicates API-based integration with cloud-managed security platforms.
Strategic Opportunities
- Saudi Aramco Megaproject Pipeline:Giga-scale refinery and blue hydrogen investments are concentrating demand for unmanned perimeter patrol systems with extreme-temperature ratings.
- Edge-to-Cloud Convergence:Hybrid architectures combining on-premise inference with sovereign data residency are opening defense and nuclear applications previously blocked by classification requirements.
- Biometric-as-a-Service Models:Subscription-based palm-vein authentication is penetrating mid-tier manufacturing sites that lacked capital for perpetual-license access control systems.
Industry Challenges
- OT-Cybersecurity Skill Scarcity:Industrial security integrators face acute shortages of engineers certified in both IEC 62443-3-3 zone segmentation and legacy PLC programming.
- Mean-Time-Between-Failures Validation:Achieving 100,000-hour sensor reliability claims requires eighteen-month accelerated lifecycle testing, compressing product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Security Systems Market |
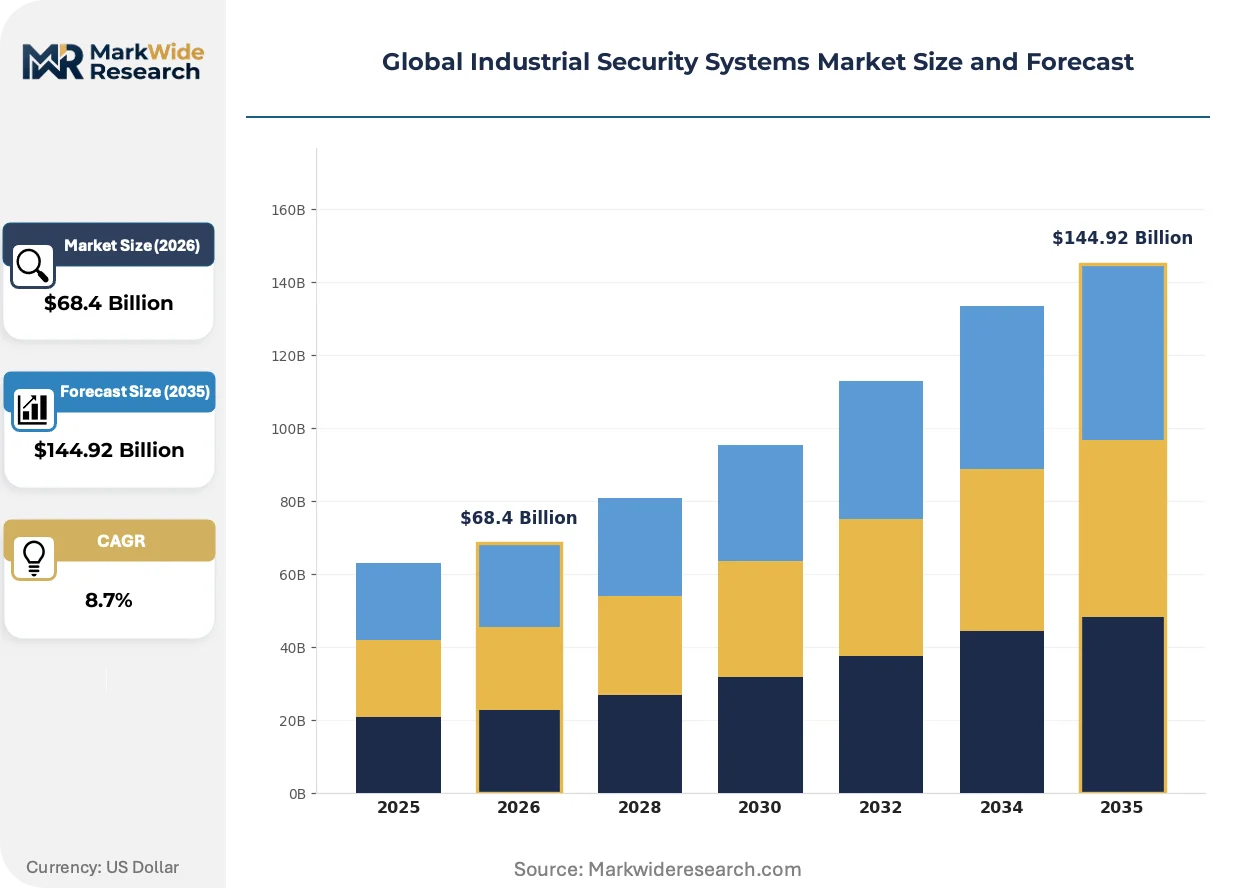
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control Systems, Video Surveillance, Intrusion Detection, Fire Protection, Perimeter Security Technology: Biometric Authentication, RFID, IP Cameras, Wireless Sensors, CCTV Analytics Application: Manufacturing Plants, Warehouses, Transportation Hubs, Energy Facilities, Data Centers End User: Oil & Gas Operators, Power Generation Units, Logistics Companies, Critical Infrastructure, Defense Facilities |
| Companies Covered | Honeywell International Inc., Siemens AG, Johnson Controls International plc, Schneider Electric SE, ABB Ltd., Bosch Security Systems, Cisco Systems Inc., Rockwell Automation Inc., Fortinet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Security Systems Market Shifts & Advancements
Neural-network inference at the network edge is redistributing computational load and reshaping how petrochemical operators architect detection hierarchies across tank farms and flare stacks.
Multimodal edge AI processors are consolidating video, thermal, and vibration signal analysis onto single-chip platforms. Refinery operators in the Rotterdam-Antwerp-Ghent cluster are adopting these systems to reduce server rack counts by sixty percent while maintaining sub-200-millisecond alert latency. This consolidation is compressing the vendor landscape around semiconductor suppliers capable of delivering automotive-grade temperature tolerance alongside inference acceleration.
The EU AI Act's conformity assessment framework for automated surveillance is mandating algorithmic transparency documentation and bias testing protocols. Industrial zone operators must now submit risk management files to notified bodies before deploying facial recognition or behavioral analysis. German chemical parks are responding by pre-certifying entire platform stacks rather than individual camera models, shifting procurement criteria toward integrated system liability.
Outcome-based security service contracts are displacing equipment-centric sales models at European petrochemical complexes. Operators now pay per prevented intrusion event rather than per installed camera, transferring performance risk to integrators. This reconfiguration is most advanced in the Netherlands, where Shell Pernis and Chemelot have unbundled hardware ownership from monitoring responsibility, forcing vendors to price cyber-physical response capabilities rather than sensor density.
Global Industrial Security Systems Market Segmentation
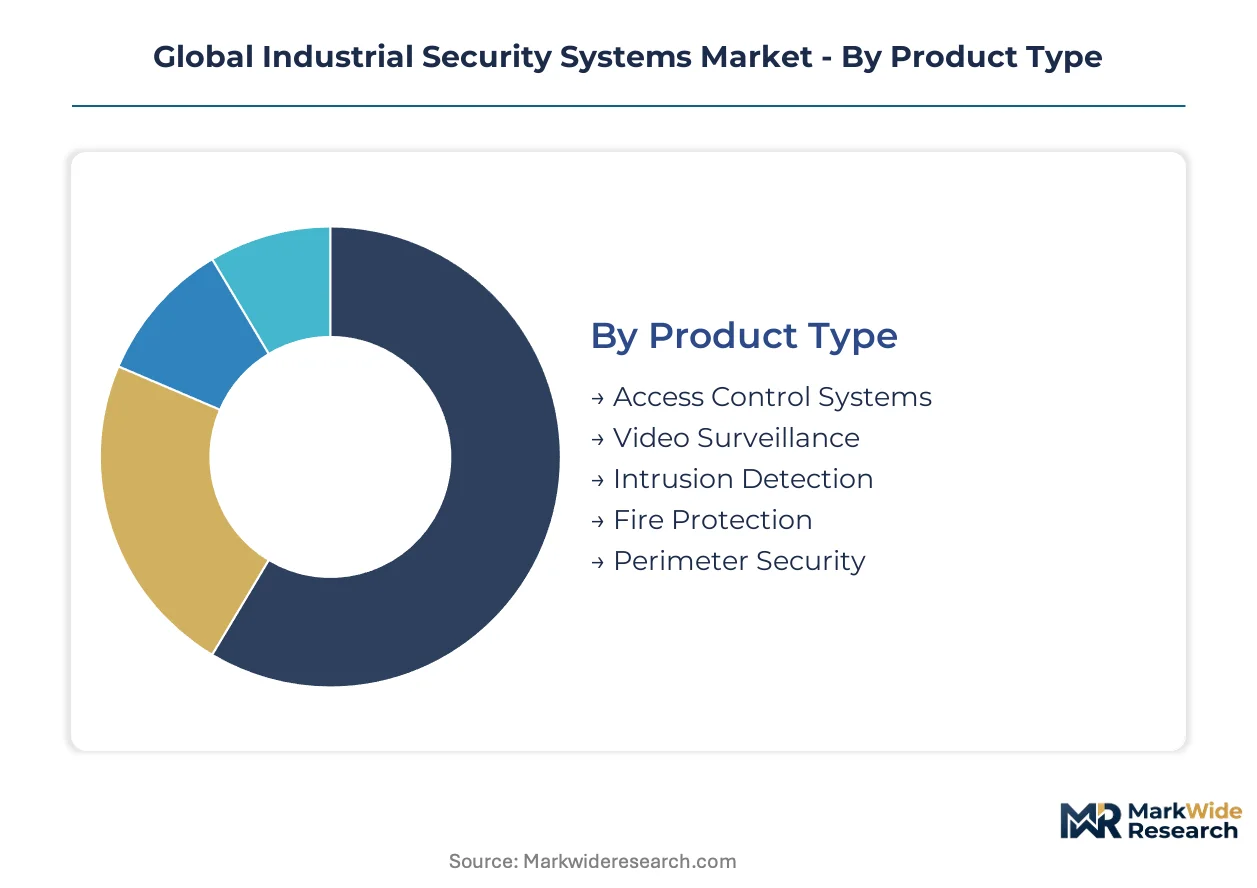
Industrial security procurement varies sharply across facility types, with petrochemical operators prioritizing explosion-proof ratings while data centers demand biometric precision. Understanding these divergent specifications enables vendors to align R&D and channel strategies with buyer willingness-to-pay.
Product Type:
Cost tier differentiation separates commodity perimeter hardware from integrated cyber-physical platforms commanding premium pricing.
- Video Surveillance:Continuous flare-stack and tank-farm monitoring dominates refinery capital allocation. Demand concentrates in Germany and Saudi Arabia as critical infrastructure investment accelerates, driven by EPA risk management plan enforcement and unmanned perimeter patrol mandates.
- Access Control Systems:Multi-factor authentication gates every mantrap entry in hyperscale data centers. Premium margins persist where palm-vein readers replace card-based credentials at maritime terminals to prevent sharing.
- Intrusion Detection:Layered sensor arrays protect chemical processing perimeters against unauthorized entry.
- Fire Protection:Flame detection networks integrate with emergency shutdown systems in hydrocarbon storage facilities.
- Perimeter Security:Thermal imaging arrays patrol extraction sites across extreme temperature ranges.
Volume sits with Video Surveillance; growth tilts toward Access Control Systems.
Technology:
Application maturity separates proven RFID deployments from emerging biometric modalities requiring certification.
- Biometric Authentication:Palm-vein recognition eliminates credential sharing while enabling contactless personnel tracking. Maritime terminals in Rotterdam and Singapore are expanding fastest as port operators modernize access infrastructure.
- IP Cameras:Edge AI inference at the network edge redistributes computational load across tank farms. European petrochemical complexes in the Rotterdam-Antwerp-Ghent cluster adopt neural-network platforms to retire rule-based detection.
- RFID:Legacy card-based systems persist in mid-tier manufacturing with lower security requirements.
- Wireless Sensors:Battery-powered vibration and acoustic monitors extend coverage without trenching.
- CCTV Analytics:Cloud-managed platforms face integration friction against decades-old analog infrastructure.
Deployment breadth favors IP Cameras; steepest expansion trajectory belongs to Biometric Authentication.
Application:
Customer type concentration shapes procurement scale, with hyperscale operators demanding enterprise-wide standardization.
- Energy Facilities:Integrated physical and cyber security dashboards protect downstream and upstream assets. Honeywell leverages building automation heritage to capture share across US Gulf Coast refineries and Middle Eastern giga-projects.
- Data Centers:Sovereign data residency requirements favor on-premise command centers in defense and nuclear applications. Multi-factor authentication at every mantrap entry commands pricing premiums.
- Manufacturing Plants:Discrete automation environments require IEC 62443-compliant industrial control protection.
- Warehouses:Inventory visibility drives convergence of security and logistics management systems.
- Transportation Hubs:Container ports balance throughput velocity against credential verification thoroughness.
Revenue concentration rests with Energy Facilities; share gains flow fastest to Data Centers.
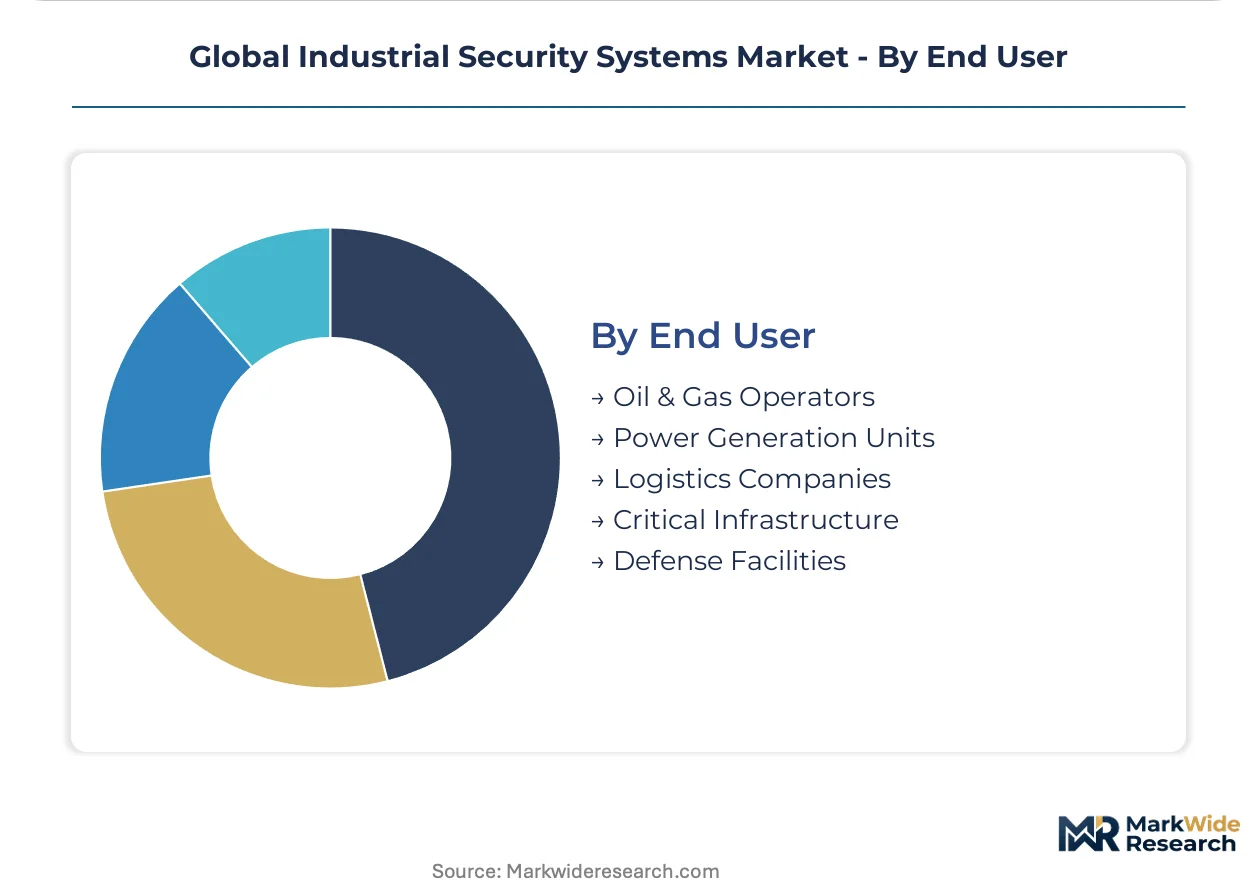
End User:
Margin structure diverges between price-sensitive logistics operators and specification-driven defense procurement.
- Oil & Gas Operators:Unmanned perimeter patrol systems with extreme-temperature ratings protect Saudi Aramco megaprojects and North Sea platforms. Siemens anchors European demand through IEC 62443-compliant development lifecycles.
- Critical Infrastructure:Chemical facilities deploy layered detection architectures following EPA risk management plan updates. EU AI Act conformity assessments extend deployment cycles for automated surveillance.
- Power Generation Units:Nuclear sites impose sovereign data residency blocking cloud-managed platforms.
- Logistics Companies:Subscription-based biometric-as-a-service models penetrate mid-tier sites lacking capital for perpetual licenses.
- Defense Facilities:Classification requirements mandate hybrid edge-to-cloud architectures with on-premise inference.
Contract value peaks with Oil & Gas Operators; fastest penetration occurs in Critical Infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, Saudi Arabia, and South Korea as critical infrastructure investment accelerates, with chemical processing and energy facilities driving procurement volumes across distinct regulatory environments.
United States
Gulf Coast refineries and chemical processing facilities are expanding security budgets following EPA risk management plan updates. The EPA enforces layered detection and response architectures that compel facility operators to integrate perimeter and cyber-physical systems. Houston and the broader Texas-Louisiana petrochemical corridor anchor procurement concentration as operators retire legacy analog CCTV infrastructure.
Germany
European petrochemical complexes in the Rhine-Ruhr and Ludwigshafen clusters are adopting edge AI video analytics to displace rule-based detection systems. The EU AI Act imposes conformity assessments on automated surveillance deployed in public-adjacent industrial zones, extending deployment cycles. Siemens anchors domestic demand through IEC 62443-compliant industrial control protection platforms.
Saudi Arabia
Giga-scale refinery and blue hydrogen investments are concentrating demand for unmanned perimeter patrol systems with extreme-temperature ratings. Saudi Aramco megaprojects require thermal imaging arrays capable of operating across harsh-climate extraction sites. The Eastern Province and Jubail Industrial City host the primary deployment clusters for integrated physical and cyber security dashboards.
South Korea
Maritime terminals in Busan and Ulsan are modernizing access infrastructure with palm-vein biometric authentication to replace card-based credentials. The MFDS and national critical infrastructure programs shape procurement specifications for OT-security integration. Samsung-heavy industrial zones drive demand for edge-to-cloud hybrid architectures that satisfy sovereign data residency requirements.
Netherlands
The Rotterdam-Antwerp-Ghent petrochemical cluster leads European adoption of multimodal edge AI processors that consolidate video, thermal, and vibration signal analysis. Outcome-based security service contracts are displacing equipment-centric sales models at Shell Pernis and Chemelot facilities. Dutch operators now pay per prevented intrusion event rather than per installed camera, transferring performance risk to integrators.
Global Industrial Security Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding premium positioning in energy and defense applications while component suppliers serve price-sensitive mid-tier manufacturing. The vendor landscape concentrates around semiconductor suppliers capable of delivering automotive-grade temperature tolerance alongside inference acceleration. Three archetypes dominate: building automation heritage players with cyber-physical integration capabilities, IEC 62443-certified industrial control specialists, and thermal imaging array developers for unmanned patrol. Competitive moves center on pre-certifying entire platform stacks under EU AI Act frameworks and unbundling hardware ownership from monitoring responsibility through subscription service models.
Among building automation heritage players, Honeywell International Inc. and Johnson Controls International plc occupy positions that exemplify integrated physical and cyber security dashboard development. Siemens AG represents the IEC 62443-certified archetype anchoring European industrial control protection demand. Bosch Security Systems sits within the thermal imaging specialization tier serving harsh-climate extraction deployments. These three entities collectively illustrate how vendor positioning stratifies around certification compliance, temperature tolerance specifications, and service model innovation rather than hardware durability alone.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Johnson Controls International plc |
| Schneider Electric SE |
| ABB Ltd. |
| Bosch Security Systems |
| Cisco Systems Inc. |
| Rockwell Automation Inc. |
| Fortinet Inc. |
| Others |
Supply & Pricing Matrix
Edge AI processor consolidation onto single-chip platforms is compressing server rack counts by sixty percent while simultaneously concentrating procurement leverage around semiconductor suppliers capable of delivering automotive-grade temperature tolerance alongside inference acceleration. This dual effect tightens margins for system integrators even as it elevates component costs for thermal imaging arrays and neural-network accelerators deployed across petrochemical tank farms.
Pricing Analysis
Volume concentrates in commodity perimeter hardware while margins accrue to integrated cyber-physical platforms commanding premium positioning. Pricing stratifies across IEC 62443-certified systems, standard IP camera deployments, and economy-tier analog retrofit kits, with certification grade and temperature tolerance specifications as primary price differentiation drivers. Cost compression in the standard tier is intensifying because cloud-managed platform vendors are absorbing integration friction with legacy CCTV infrastructure. Mid-tier manufacturing sites exhibit highest price sensitivity, while defense and nuclear applications show lowest sensitivity due to sovereign data residency mandates.
Supply Chain Analysis
Freight costs for explosion-proof enclosures and thermal imaging arrays escalate sharply for deployments into Saudi Arabia's Eastern Province and North Sea platforms, compressing project economics for remote extraction sites. Thermal imaging sensor fabrication concentrates in Taiwan, South Korea, and Japan, drawing from germanium substrates, indium gallium arsenide detectors, and automotive-grade FPGA processors. Single-source vulnerability for neural-network inference chips exposes timelines to foundry capacity allocation decisions. Distribution runs through industrial systems integrators with IEC 62443 certification credentials rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural-network inference at the edge is displacing rule-based detection architectures, creating a technology-transition window where vendor requalification around AI performance metrics is rewriting competitive hierarchies across petrochemical and maritime terminal deployments.
For Market Incumbents: Extend IEC 62443 certification coverage into edge AI processor supply chains to preempt compliance gaps as the EU AI Act mandates algorithmic transparency documentation. Deepen backward integration into thermal imaging sensor sourcing to mitigate single-source vulnerability from East Asian foundries. Anchor platform liability through pre-certified system stacks rather than individual component warranties. For New Entrants and Emerging Players: The price-point gap between palm-vein biometric premium systems and legacy card-based access control creates entry space for subscription-based biometric-as-a-service models targeting mid-tier manufacturing sites lacking perpetual-license capital. Maritime terminals in Southeast Asia present the most penetrable geography given modernization mandates and contactless personnel tracking requirements. Partner with industrial security integrators possessing existing OT-cybersecurity certifications to bypass channel development timelines. For Investors and Strategic Acquirers: Re-rating potential sits with IEC 62443-certified development lifecycle specialists given accelerating European critical infrastructure procurement filtering. Long-term viability over a five-to-ten year window favors vendors with proven mean-time-between-failures validation and extreme-temperature deployment track records in harsh-climate extraction environments. Monitor Saudi Aramco megaproject award announcements as inflection indicators for unmanned perimeter patrol system demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Platform Certification | EU AI Act conformity assessments force pre-certification of entire system stacks rather than individual cameras. |
| Thermal Imaging Backward Integration | Captive supply of germanium substrates and infrared detectors mitigates East Asian foundry concentration risk. |
| Biometric-as-a-Service Launch | Subscription pricing penetrates mid-tier manufacturing sites lacking capital for perpetual-license access control. |
| Hybrid Edge-to-Cloud Deployment | Sovereign data residency architectures open defense and nuclear applications previously blocked by classification requirements. |
| Outcome-Based Service Contracting | Shell Pernis and Chemelot unbundle hardware ownership from monitoring responsibility, transferring performance risk to integrators. |
Research Methodology
Independent corroboration across security systems procurement officers at Gulf Coast refineries, OT-cybersecurity engineers certified in IEC 62443 zone segmentation, and maritime terminal operations directors underwrites the qualitative findings in this study. Primary interviews with plant managers at Rotterdam-Antwerp-Ghent petrochemical complexes, distribution channel partners specializing in industrial automation, and technical R&D directors at thermal imaging array developers were combined with secondary validation from customs and trade data, SEC 10-K filings of building automation heritage players, and EPA risk management plan enforcement records. Bottom-up segment sizing and top-down market triangulation were applied consistently.
Rate-of-change decomposition across technology substitution curves, regulatory compliance timelines, and critical infrastructure investment cycles structures the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, technology modality, application facility category, and end-user industry vertical alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves anchored to disclosed procurement volumes and facility expansion announcements. Forecast inputs incorporate semiconductor foundry capacity allocation patterns and EPA enforcement intensity indices.
Inputs from industrial security integrators and petrochemical facility operators were available through the study window; gaps in Saudi Aramco megaproject timeline specificity and EU AI Act notified body processing rates introduce uncertainty bands around near-term deployment forecasts. Forecasts reflect assumptions about edge AI inference performance maturation and thermal imaging sensor supply continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Smart Locks Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
US Access Control Market
Access Control Systems
Border Security System Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Network Access Control Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
Port Security Systems Market