
 GCC Home Security Systems Market | 2026-2036
GCC Home Security Systems Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Home Security Systems Market Intelligence
Residential villa complexes across the United Arab Emirates is broadening the addressable base for integrated perimeter protection. Honeywell International Inc. leverages its building automation heritage to anchor premium commercial installations across Saudi Arabia. Johnson Controls International competes through its Tyco security division, sustaining strong relationships with government and hospitality end users in the Gulf. Hangzhou Hikvision Digital Technology Co., Ltd. dominates video surveillance supply, extending its channel presence through distributor partnerships in Dubai and Riyadh.
GCC home security systems encompass electronic devices and networked platforms designed for intrusion detection, access control, and real-time monitoring, typically operating through IP-based communication protocols with cloud data relay and mobile application interfaces. These systems serve primarily to protect residential and light commercial assets against unauthorized entry, environmental hazards, and remote surveillance gaps. Wired systems retain preference in large villa compounds where infrastructure reliability outweighs installation flexibility, while wireless systems capture faster growth in apartment retrofits where minimal disruption matters. Cloud-based systems concentrate emerging margin pools as recurring software revenue displaces one-time hardware sales across technology segments.
Saudi Arabia's Civil Defense Authority and the UAE's Telecommunications and Digital Government Regulatory Authority shape product certification and data sovereignty requirements for connected security devices. The Emirates Authority for Standardization and Metrology enforces electrical safety and electromagnetic compatibility standards that filter non-compliant imports from regional distribution channels. Stakeholders must weigh the trade-off between localized data storage mandates and the operational cost of regional cloud infrastructure as regulatory frameworks tighten across Gulf jurisdictions.
Market Dynamics
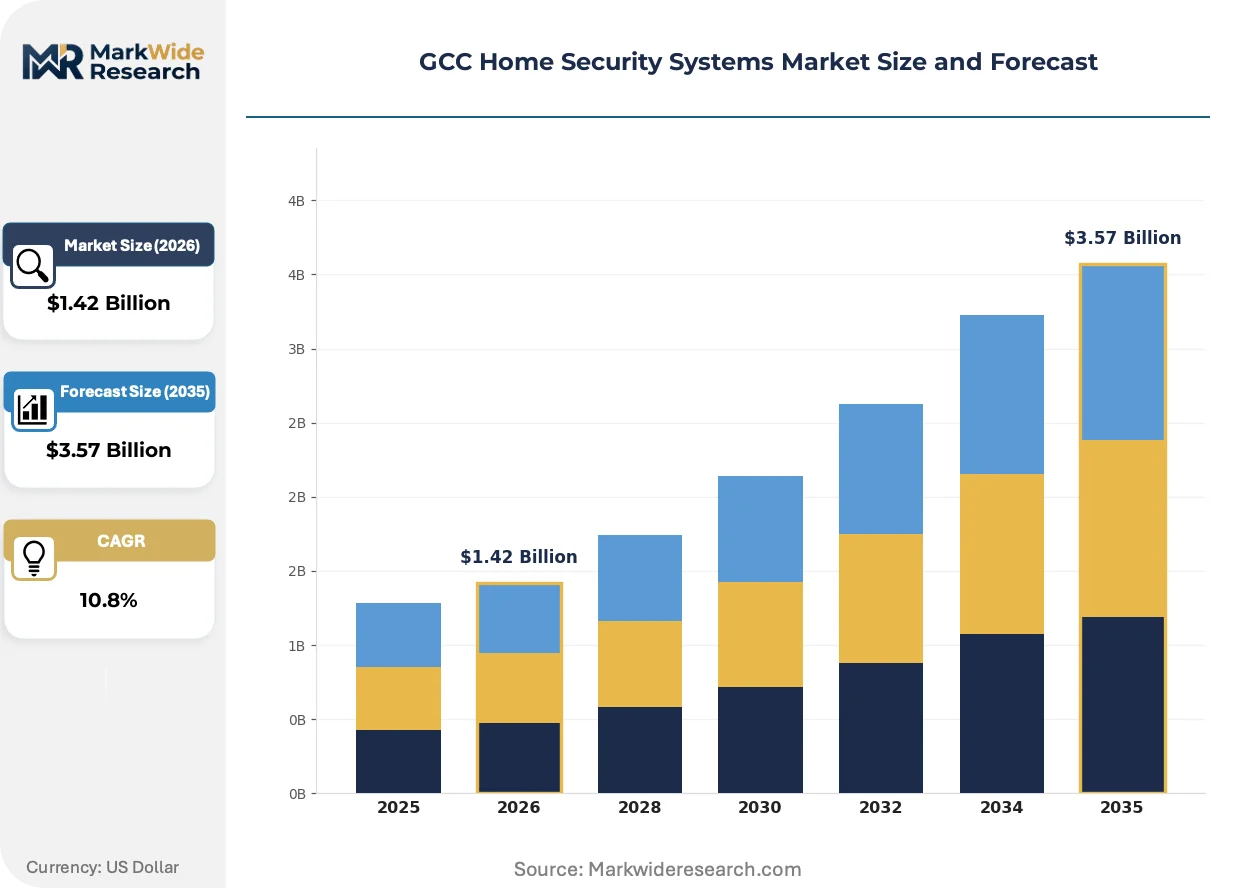
Cloud migration is compressing hardware margins while expanding recurring revenue pools across GCC residential and commercial installations. The shift from one-time equipment sales to subscription-based monitoring services is restructuring vendor economics and customer lifetime value calculations throughout the Gulf.
Growth Catalysts
- Smart City Mandates:Saudi Arabia's Vision 2030 smart district initiatives in Riyadh and NEOM are embedding security infrastructure into urban master plans from conception.
- SFDA Device Certification:Saudi Arabia's national regulator has streamlined approval pathways for connected safety devices, accelerating product launches for compliant manufacturers.
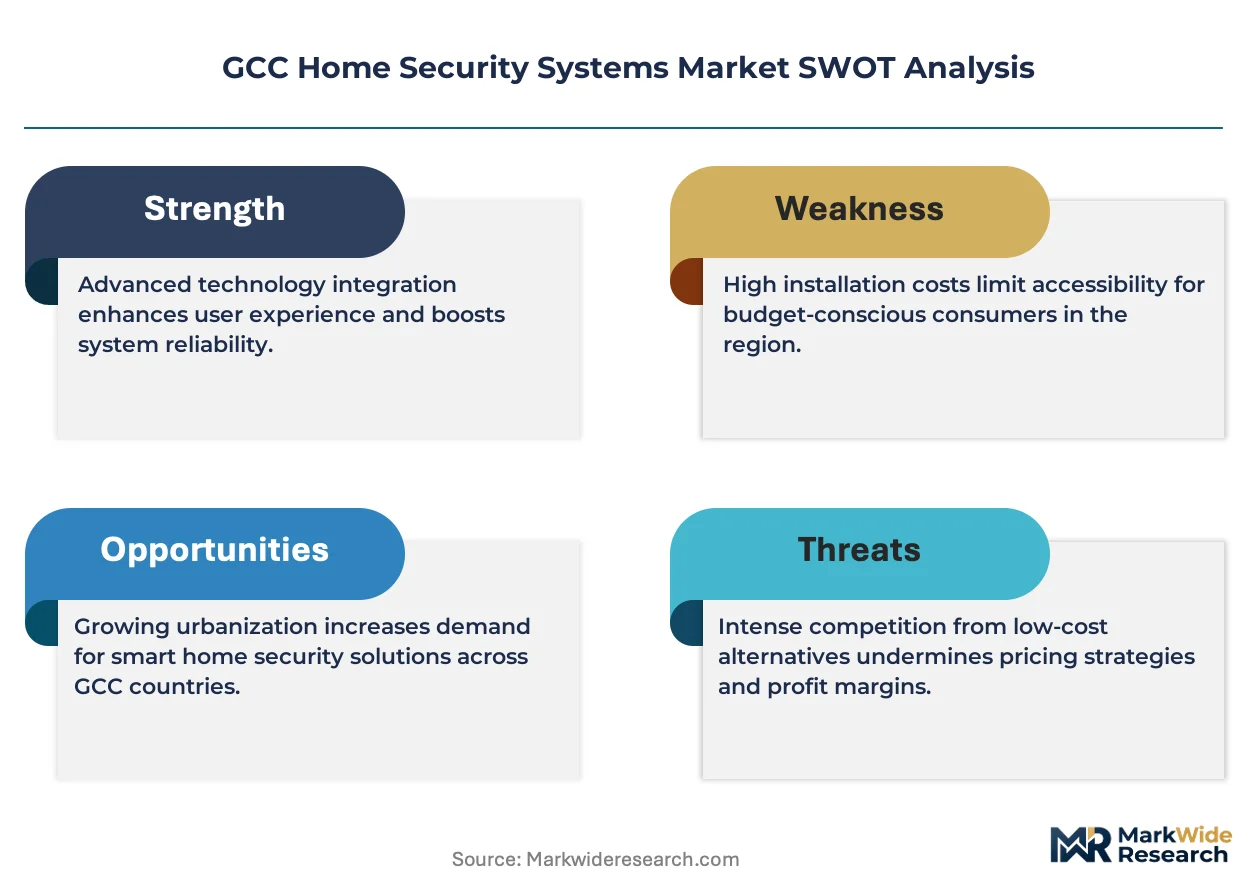
- Perimeter AI Analytics:Machine learning-powered intrusion detection is reducing false alarm rates below 2% in Dubai's premium villa compounds, driving replacement cycles.
Market Restraints
- Copper and Semiconductor Input Volatility:Wired system components face 15-25% material cost swings, compressing margins on legacy installations in large compounds.
- Chinese Supply Concentration:Video analytics chipsets and camera sensors depend heavily on Shenzhen and Hangzhou manufacturing clusters, exposing distributors to geopolitical logistics disruptions.
- Data Sovereignty Friction:UAE's Telecommunications and Digital Government Regulatory Authority mandates local data residency, forcing foreign vendors to build regional cloud infrastructure at 40% higher operational cost than global centralized hosting.
Strategic Opportunities
- Kuwait's Underserved Apartment Stock:Retrofit wireless penetration in Kuwait City residential towers sits below 15%, offering first-mover expansion for channel partners with installer networks.
- Insurance Premium Linkage:UAE insurers are beginning to price home policies contingent on certified alarm system installation, creating policy-driven demand pull.
- Voice-Assistant Integration:Amazon Alexa and Google Home interoperability is opening new installation triggers through smart home ecosystem bundling in Dubai and Riyadh.
Industry Challenges
- Cybersecurity Skill Scarcity:Network security engineers with IoT hardening expertise command 35% salary premiums in Dubai, constraining vendor technical support scaling.
- Legacy Analog Integration:Hybrid deployments requiring coaxial-to-IP bridge equipment add 20% project complexity and extended commissioning timelines in established villa compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Home Security Systems Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.57 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, Alarms, Motion Sensors, Smart Locks End User: Residential, Apartments, Villas, Condominiums Technology: Wired Systems, Wireless Systems, Hybrid Systems, Cloud-Based Systems Installation Type: Professional Installation, DIY Systems, Integrated Solutions, Managed Services |
| Companies Covered | ADT Inc., Honeywell International Inc., Johnson Controls International, Hangzhou Hikvision Digital Technology Co., Ltd., Robert Bosch GmbH, ASSA ABLOY AB, Resideo Technologies Inc., SimpliSafe Inc., Vivint Smart Home Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Home Security Systems Market Strategic Shifts & Innovations
Artificial intelligence inference at the network edge is eliminating latency-dependent cloud processing for critical security events. This architectural shift is redistributing computational load and reshaping hardware specifications across Gulf installations.
Edge-based video analytics is converging with thermal imaging sensors to deliver perimeter detection without visible-light dependency. Large villa compounds in Abu Dhabi's Saadiyat Island and Riyadh's Diplomatic Quarter are deploying these fused systems for 24-hour coverage regardless of sandstorm conditions. The convergence is compressing demand for standalone infrared illuminators and separate thermal camera installations.
MOHAP in the UAE has introduced cybersecurity certification requirements for connected medical and safety devices, extending compliance obligations to home health monitoring integrations within security platforms. Manufacturers must now submit penetration testing documentation alongside traditional electrical safety certificates. The regulation most heavily affects vendors targeting elderly care applications where fall detection and emergency response systems merge.
Subscription financing is displacing upfront capital expenditure in commercial security procurement across Saudi Arabia's retail and hospitality sectors. Riyadh-based property management firms are bundling alarm monitoring, maintenance, and periodic hardware refresh into single monthly service agreements. This model is most visible in the kingdom's emerging entertainment and tourism districts where operators prioritize operational expenditure predictability over asset ownership.
GCC Home Security Systems Market Segmentation
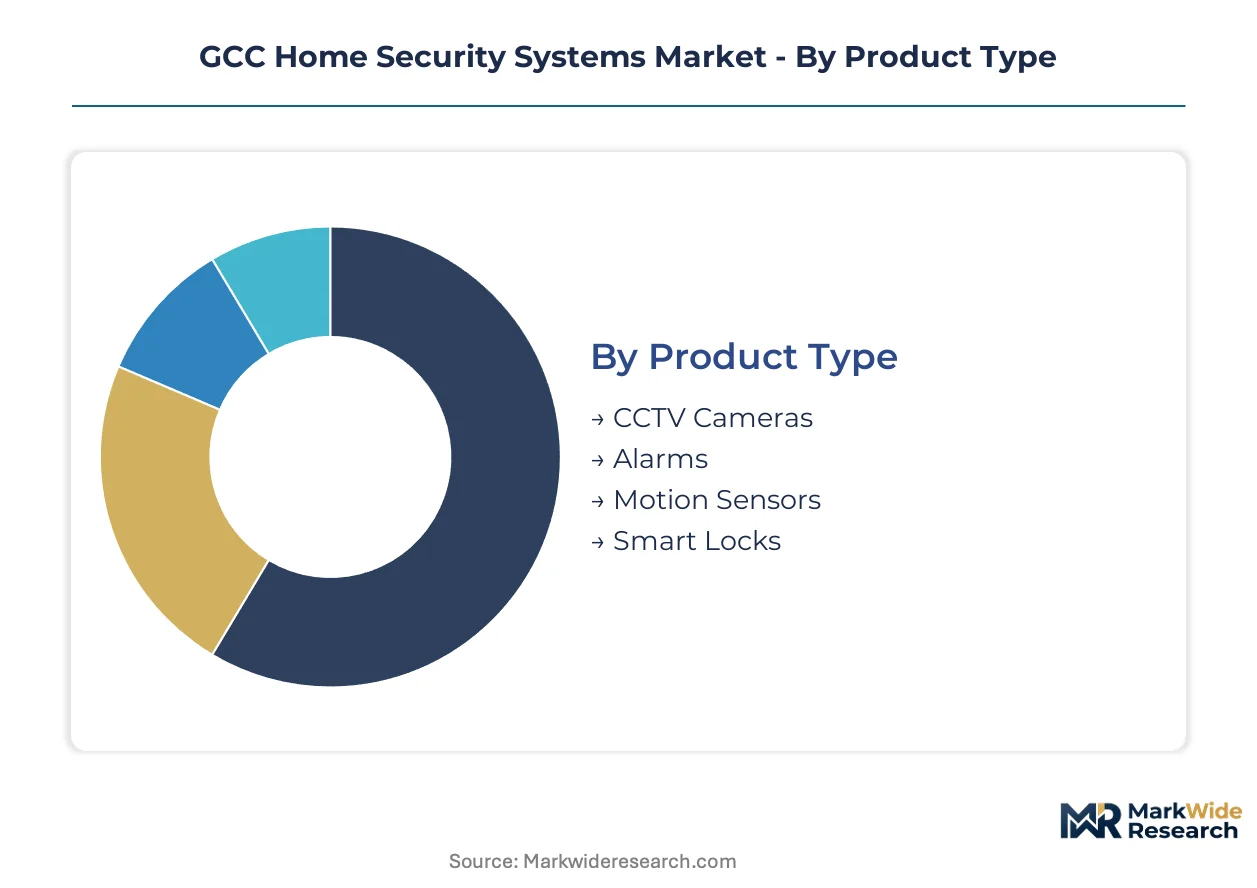
Segmentation in GCC home security reveals distinct procurement patterns across housing typologies and technology preferences. Product mix varies sharply between villa compounds requiring perimeter-heavy configurations and apartment towers favoring discrete entry-point solutions. Understanding these divides enables targeted channel strategies and margin optimization across the Gulf's heterogeneous residential landscape.
Product Type:
Standalone devices dominate retrofit installations, while embedded sensor networks anchor new-build smart home specifications in Saudi Arabia's Vision 2030 districts.
- CCTV Cameras:IP-based dome and bullet cameras with 4K resolution and edge analytics comprise the hardware revenue base. Dubai's premium gated communities specify AI-enhanced video verification, while Riyadh's diplomatic quarter demands thermal-visible fusion for sandstorm resilience.
- Alarms:Intrusion detection panels integrate fire, gas, and environmental sensors through unified control interfaces. Saudi Arabia's Civil Defense Authority mandates certified alarm compliance in all new residential developments, driving replacement cycles in legacy compounds.
- Motion Sensors:PIR and microwave dual-technology devices reduce false triggers in extreme heat conditions.
- Smart Locks:Biometric and keypad-enabled deadbolts connect to property management platforms in UAE serviced apartment towers.
CCTV cameras lead volumes today; smart locks are gaining share fastest.
End User:
Cost tier stratification separates mass-market apartment retrofits from bespoke villa installations commanding premium service margins.
- Residential:Broad category spanning single-family dwellings to multi-unit buildings with unified security infrastructure. Kuwait's underserved apartment stock presents first-mover expansion opportunities for wireless system providers.
- Apartments:Compact units in high-rise towers prioritize door-entry systems and internal monitoring over perimeter protection. Minimal-disruption wireless retrofits capture faster growth where drilling restrictions apply.
- Villas:Standalone compounds require layered perimeter-to-interior coverage with dedicated control rooms. Abu Dhabi's Saadiyat Island developments specify fused thermal-visible analytics for 24-hour detection reliability.
- Condominiums:Managed communities blend individual unit autonomy with shared lobby and parking surveillance. Riyadh's emerging smart districts embed security into master-planned infrastructure from conception.
Villas anchor premium revenue pools; apartments offer steepest volume expansion trajectory.
Technology:
Maturity curves separate legacy wired infrastructure from cloud-native architectures restructuring vendor economics toward recurring software revenue.
- Wired Systems:Coaxial and Ethernet-based installations deliver uninterrupted power and signal integrity in large compounds. Copper price volatility compresses margins on legacy specifications across established UAE villa communities.
- Wireless Systems:Battery and mesh-networked devices enable rapid deployment without structural modification. Kuwait City residential towers show sub-15% penetration, offering channel expansion for installer-network partners.
- Hybrid Systems:Bridge architectures connecting analog legacy to IP backbones extend equipment lifecycles. Coaxial-to-IP conversion adds project complexity in older compounds with mixed infrastructure generations.
- Cloud-Based Systems:Subscription-managed platforms with mobile application interfaces displace one-time hardware sales. UAE data sovereignty mandates force regional cloud infrastructure investment at elevated operational cost.
Wired systems retain installed base dominance; cloud-based systems are climbing the fastest.
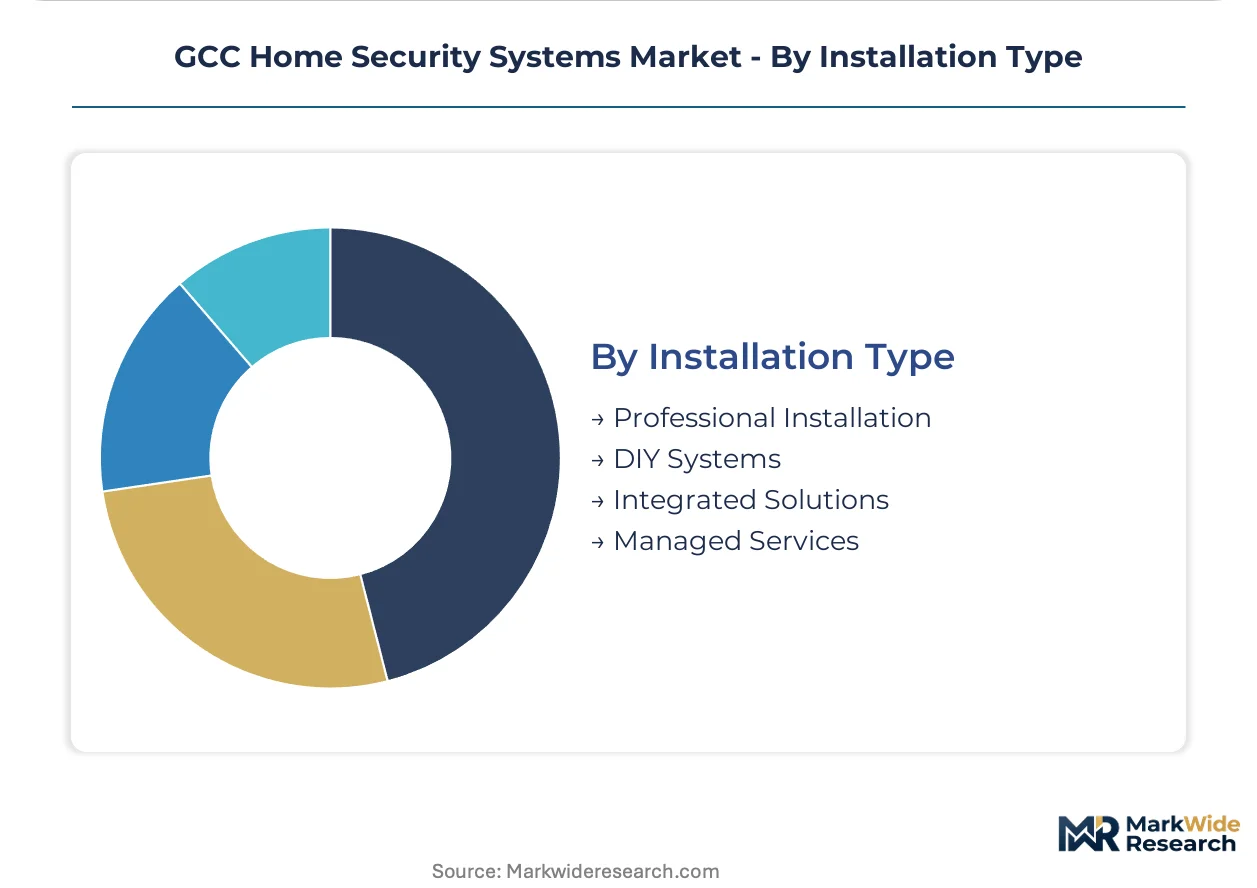
Installation Type:
Customer type segmentation separates technically proficient end-users from buyers requiring full-service procurement and ongoing technical support.
- Professional Installation:Certified technician deployment ensures code compliance and warranty validity. Saudi Arabia's SFDA streamlined certification accelerates product launch timelines for compliant manufacturers.
- DIY Systems:Self-configured kits distributed through retail and e-commerce channels appeal to cost-conscious apartment dwellers. Amazon Alexa and Google Home interoperability creates installation triggers through smart home ecosystem bundling.
- Integrated Solutions:Single-contractor responsibility for security, automation, and building management systems. Honeywell leverages building automation heritage to anchor premium commercial specifications.
- Managed Services:Subscription bundles covering monitoring, maintenance, and periodic hardware refresh. Riyadh property management firms prioritize operational expenditure predictability in entertainment and tourism districts.
Professional installation commands current revenue share; managed services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor investment patterns across the Gulf Cooperation Council, with data localization mandates in the UAE and streamlined device certification in Saudi Arabia creating divergent cost-of-compliance environments that influence regional cloud infrastructure deployment decisions.
United Arab Emirates
Dubai's premium gated communities and Abu Dhabi's Saadiyat Island developments anchor high-value installations of AI-enhanced perimeter systems. The Telecommunications and Digital Government Regulatory Authority enforces strict data residency requirements for connected security devices, compelling foreign vendors to establish regional cloud infrastructure. Dubai Internet City and Abu Dhabi's Masdar City concentrate channel partner networks and system integrator operations serving villa compounds and commercial towers.
Saudi Arabia
NEOM and Riyadh's emerging smart districts embed security infrastructure into urban master plans from conception, generating demand for unified control systems. The Saudi Food and Drug Authority streamlined certification pathways for connected safety devices, accelerating product launches for compliant manufacturers. Riyadh's Diplomatic Quarter and Jeddah's Red Sea Project developments specify thermal-visible fusion analytics for sandstorm-resilient 24-hour coverage.
Kuwait
Kuwait City residential towers exhibit sub-15% wireless security penetration, presenting first-mover expansion opportunities for installer-network partners with retrofit expertise. The country's national telecommunications regulator maintains equipment type-approval requirements that filter non-compliant imports. Salmiya and Hawalli districts concentrate aging apartment stock where minimal-disruption wireless deployments capture faster growth trajectories.
Qatar
Lusail City and Msheireb Downtown Doha integrate security platforms into smart city infrastructure, favoring vendors with building automation heritage. The Qatar General Electricity and Water Corporation sets electrical safety standards affecting device certification timelines. Doha's West Bay and The Pearl-Qatar developments prioritize unified lobby and parking surveillance in managed condominium configurations.
Bahrain
Manama's financial district and residential towers in Seef and Juffair drive demand for discrete entry-point solutions over perimeter-heavy configurations. The country's telecommunications regulator enforces cybersecurity baseline requirements for IoT-connected devices. Diyar Al Muharraq and Bahrain Bay developments concentrate new-build smart home specifications favoring embedded sensor networks.
GCC Home Security Systems Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors seek to bridge capability gaps in cloud infrastructure and localized compliance expertise. The market exhibits a tiered structure with diversified building automation conglomerates anchoring premium commercial installations, specialized security technology firms capturing video surveillance volumes, and agile smart home platforms penetrating apartment retrofit segments. Three archetypes define competitive positioning: heritage building automation providers leveraging integrated system expertise, pure-play security technology specialists dominating camera and sensor supply, and subscription-native platforms restructuring procurement toward recurring revenue models. Geographic expansion through distributor partnerships and backward integration into regional cloud infrastructure represent the two dominant competitive moves reshaping vendor economics.
Among heritage-anchored conglomerates, Honeywell International Inc. and Johnson Controls International occupy positions exemplifying the building automation-to-security extension archetype, while Hangzhou Hikvision Digital Technology Co., Ltd. represents the scale-driven video technology specialist tier. These three entities collectively illustrate the competitive tension between integrated system bundling and component-level dominance across Gulf installations.
| Leading Market Players |
|---|
| ADT Inc. |
| Honeywell International Inc. |
| Johnson Controls International |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Robert Bosch GmbH |
| ASSA ABLOY AB |
| Resideo Technologies Inc. |
| SimpliSafe Inc. |
| Vivint Smart Home Inc. |
| Others |
Cost & Logistics Intelligence
Semiconductor chipsets from Shenzhen and Hangzhou manufacturing clusters flow through distributor markups into three distinct pricing tiers across GCC security installations, with copper cabling costs for wired villa compounds compressing margins at the premium end while wireless retrofit kits compete on volume at the economy tier.
Pricing Analysis
Distributor margins of 25-40% separate factory-gate hardware costs from end-user prices across Dubai and Riyadh channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with SFDA-compliant devices commanding 15-20% premiums over uncertified alternatives. Pricing pressure stems from Chinese supply concentration exposing distributors to logistics disruptions. Apartment retrofit buyers in Kuwait City exhibit highest price sensitivity; diplomatic quarter villa compounds in Riyadh show lowest.
Supply Chain Analysis
Video analytics chipsets and camera sensors draw from concentrated manufacturing in China, South Korea, and Taiwan. Raw material dependencies span copper for wired infrastructure, lithium for wireless device batteries, and rare earth elements for thermal imaging sensors. Single-source vulnerability in Shenzhen packaging facilities creates disruption risk. Distribution runs through Dubai Internet City and Riyadh channel partners serving installer networks across the Gulf.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC home security market represents a late-cycle quality story as cloud-connected surveillance specifications displace analog legacy across Saudi Vision 2030 districts and Dubai premium communities.
For Market Incumbents: Cement cloud infrastructure ownership in UAE data centers to neutralize TDRA residency mandates as a competitive moat. Deepen backward integration into regional technical support capabilities, where cybersecurity engineer scarcity constrains rival scaling. Threat vector: subscription-native platforms restructuring procurement toward recurring revenue models. For New Entrants and Emerging Players: Installer-network partnerships in Kuwait City unlock sub-15% wireless penetration in aging residential towers. Voice-assistant ecosystem bundling through Amazon Alexa and Google Home interoperability creates installation triggers in Dubai and Riyadh apartment segments. White-space targets: managed services bundles for Saudi entertainment district property managers prioritizing operational expenditure predictability. For Investors and Strategic Acquirers: Roll-up economics work for regional cloud infrastructure specialists because data sovereignty mandates force foreign vendors into 40% higher operational cost structures that local players can arbitrage. Long-term viability hinges on recurring software revenue displacement of hardware sales. Acquisition target archetype: UAE-based managed services platforms with existing TDRA-compliant hosting. Signal to watch: insurance premium linkage spreading beyond pilot UAE programs into Saudi and Kuwait regulatory frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Cloud Infrastructure Buildout | UAE TDRA data residency mandates force foreign vendors into localized hosting investments at elevated operational cost. |
| SFDA Certification Pathway Investment | Streamlined Saudi device approval accelerates product launch timelines for compliant manufacturers entering Riyadh smart districts. |
| Installer Network Acquisition | Kuwait City wireless retrofit expertise commands scarcity premiums as apartment penetration sits below regional benchmarks. |
| Voice-Assistant Platform Integration | Amazon Alexa and Google Home interoperability creates installation triggers through smart home ecosystem bundling in Dubai. |
| Managed Services Subscription Launch | Riyadh property management firms in entertainment districts prioritize operational expenditure predictability over capital ownership. |
Research Approach
Direct dialogue with system integrators, channel distribution partners, property management executives, and regulatory compliance officers grounded qualitative findings, validated against customs import records, SFDA device registration databases, UAE Telecommunications and Digital Government Regulatory Authority filings, and Saudi Vision 2030 infrastructure procurement disclosures. Bottom-up and top-down triangulation reconciled installation volume estimates with hardware shipment data.
Bottom-up modeling aggregated product-type and technology-segment trajectories across the projection horizon, while top-down validation cross-checked aggregate market evolution against smart city infrastructure budgets in NEOM and Riyadh. Segmentation dimensions spanned housing typology, connectivity architecture, and installation service model. CAGRs derived from fitted growth curves incorporating SFDA regulatory acceleration effects and copper price volatility inputs.
Revisions become necessary when Saudi Civil Defense Authority mandates extend beyond new developments to retrofit requirements, or when UAE data sovereignty enforcement tightens further. Forecasts reflect assumptions about cloud migration pace and insurance premium linkage adoption. A small set of named triggers—regulatory mandate expansion, semiconductor supply disruption severity, and cybersecurity certification scope creep—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Car Security System Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Locks Market
Access Control Systems
Japan Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Network Access Control Market
Access Control Systems
US Access Control Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
North America Access Control Market