
 Asia-Pacific Proximity Access Control Market | 2026-2036
Asia-Pacific Proximity Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Proximity Access Control Market Insights
Cloud-native credential architectures are broadening the addressable base for mid-tier building operators previously locked out of enterprise-grade systems. Honeywell International Inc. leverages its building automation integration to bundle climate and access platforms across ASEAN commercial towers. Hangzhou Hikvision Digital Technology Co. Ltd anchors regional supply through captive semiconductor sourcing for RFID module production. Suprema Inc. differentiates via deep specialization in fingerprint-to-mobile credential fusion for financial institution vaults.
Proximity access control denotes contactless authentication systems that verify identity through radio-frequency or optical signal exchange within a 10-centimeter to 10-meter range, typically employing 13.56 MHz ISO/IEC 14443 protocols for near-field communication. These systems govern physical entry points, time-attendance logging, and zone-based permission hierarchies across facilities requiring audited personnel movement. Biometric scanners command premium positioning where multi-factor authentication is non-negotiable, while mobile credentials represent the fastest-expanding product type as smartphone penetration eliminates dedicated hardware proliferation. Within end-user verticals, healthcare facilities generate outsized margin pools due to HIPAA-aligned audit trail mandates and infection-control protocols that favor touchless interfaces.
China's SAMR enforces GB standards for biometric data storage and cross-border transfer limitations that constrain foreign vendor architectures. Japan's METI drives JIS-compliant interoperability mandates ensuring NFC-B platforms integrate with legacy FeliCa transit infrastructure. India's BIS certification requirements for electronic security products create procedural barriers that domestic assemblers navigate more fluidly than importers. Stakeholders must weigh sovereign data-localization trajectories against the cost of maintaining fragmented credential ecosystems across national boundaries.
Market Dynamics
Smart city infrastructure mandates across Southeast Asian metros are compressing procurement cycles for contactless entry systems, forcing vendors to pre-certify hardware against divergent national biometric data standards before deployment.
Growth Catalysts
- Healthcare infection-control protocols:Post-pandemic hygiene mandates in hospitals and clinics across India and Thailand are accelerating touchless authentication adoption for patient and staff zones.
- China's GB standards for biometric storage:SAMR-enforced data localization requirements are creating captive demand for domestic-certified hardware that foreign vendors must adapt to access.
- Mobile credential penetration:Smartphone ubiquity in South Korea and Japan is eliminating dedicated card reader hardware from mid-tier commercial installations.
Market Restraints
- Semiconductor supply concentration:Captive RFID module production by Hangzhou Hikvision and limited alternative suppliers in Taiwan create input bottlenecks for second-tier system integrators.
- BIS certification timelines:India's mandatory electronics testing for security products extends import lead times by 4-6 months versus domestic assembly routes.
- Legacy FeliCa infrastructure lock-in:Japan's transit-integrated access systems create technical barriers to NFC-B migration for foreign credential platforms.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for local manufacturing are opening cost-competitive assembly pathways for ASEAN and Chinese component suppliers.
- Cloud-native credential architectures:Subscription-based access management is penetrating mid-tier building operators in Vietnam and Indonesia previously excluded from enterprise systems.
- Greater Bay Area integrated security zones:Cross-border facility clusters between Shenzhen, Hong Kong, and Macau require unified credential systems spanning three regulatory jurisdictions.
Industry Challenges
- Firmware security certification gaps:India's STQC and China's ITSEC evaluation timelines for biometric algorithms lag product development cycles by 8-12 months.
- Interoperability fragmentation:Divergent national encryption standards prevent credential portability across Japan's JIS-compliant, China's GB-aligned, and India's BIS-certified installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Proximity Access Control Market |
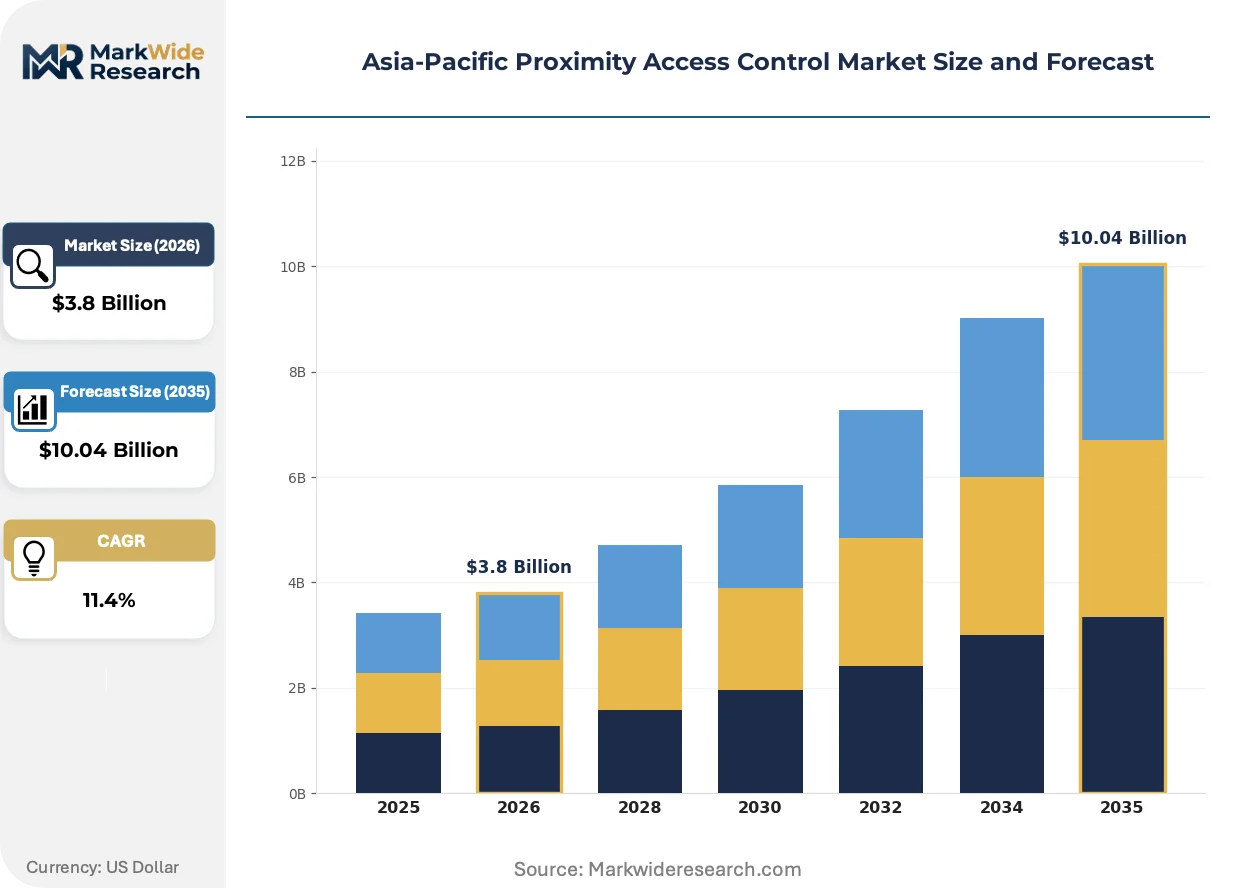
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Card Readers, Biometric Scanners, Keypads, Mobile Credentials End User: Corporations, Educational Institutions, Healthcare Facilities, Government Offices Technology: RFID, NFC, Bluetooth, Infrared Application: Building Access, Attendance Tracking, Data Security, Visitor Management |
| Companies Covered | Johnson Controls, Honeywell International Inc., Hangzhou Hikvision Digital Technology Co. Ltd, Suprema Inc., Schneider Electric, Dahua Technology Co. Ltd, Avigilon (Motorola Solutions Inc.), ASSA ABLOY, Identiv Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Proximity Access Control Market Trends and Innovations
Credential authentication architectures are fragmenting along sovereign data boundaries while converging on mobile-first delivery models that compress hardware refresh cycles across the region.
Biometric-to-mobile credential fusion is converging with Bluetooth Low Energy beacon networks to enable seamless handoff between physical entry points and time-attendance logging. Financial institution vaults in Seoul and Singapore are piloting fingerprint-activated smartphone credentials that eliminate dedicated reader hardware at perimeter gates. This convergence is compressing the addressable market for standalone biometric terminals while expanding software licensing revenue pools for platform vendors.
China's SAMR enforcement of GB/T 35273 biometric data protection standards is mandating on-device template storage and prohibiting cloud-based facial recognition archives for commercial access control. Foreign vendors must architect edge-computing credential verification to maintain market presence. Healthcare facilities in Shanghai and Beijing are prioritizing hardware with domestic encryption certification over international ISO/IEC 27001-aligned alternatives.
Building automation unbundling is disrupting traditional bundled procurement in ASEAN commercial towers. Facility managers in Bangkok and Jakarta are separating climate control from access system selection, enabling best-of-breed credential platforms to displace integrated building management suites. This pattern is most visible in Class-A office developments where tenant experience apps demand API-open credential systems rather than proprietary protocols.
Asia-Pacific Proximity Access Control Market Segmentation
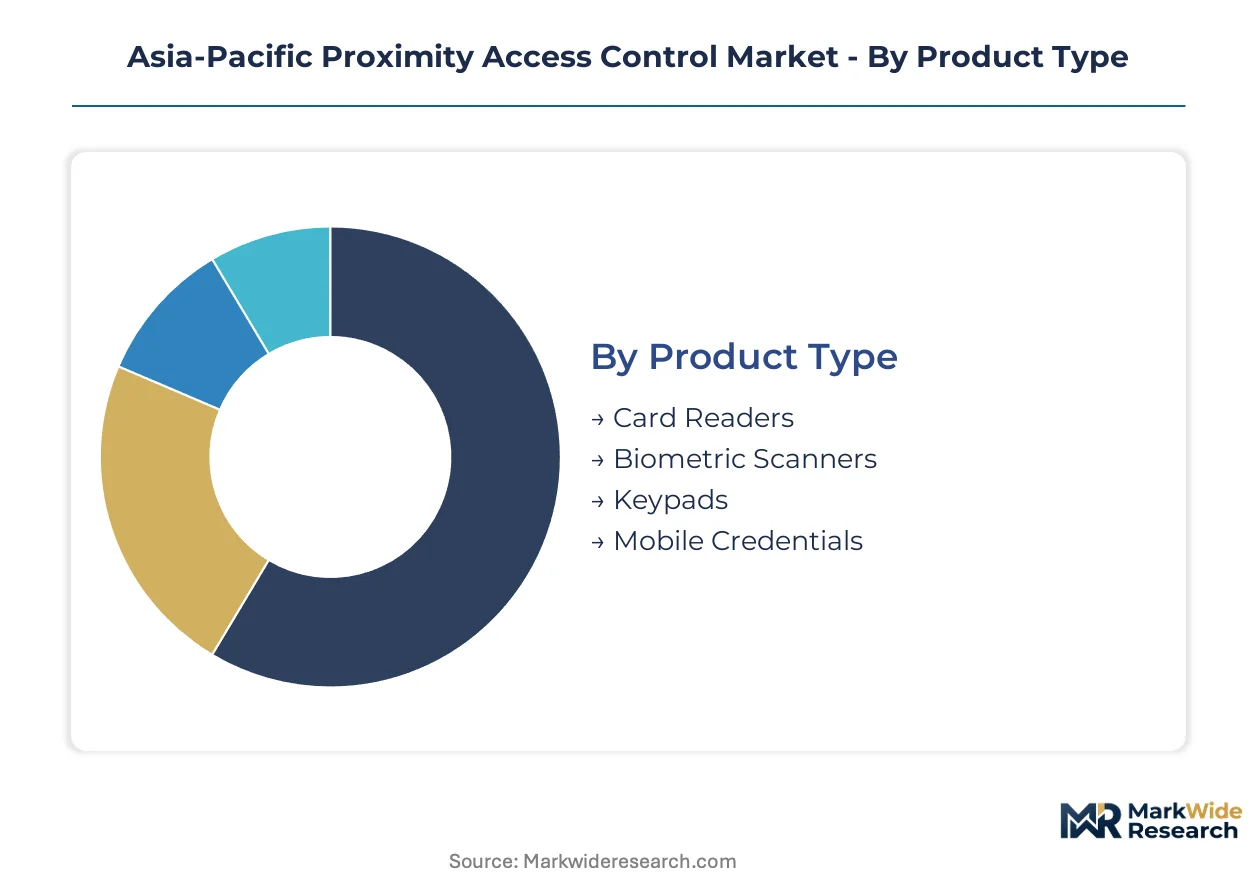
Proximity access control systems fragment across hardware form factors, credential technologies, and facility-specific compliance requirements. Each segment carries distinct procurement cycles, certification burdens, and integration complexity that reshape vendor competitive positioning across Asia-Pacific.
Product Type:
Capital intensity varies sharply across hardware categories, with biometric terminals demanding the highest upfront investment in sensor arrays and encryption modules.
- Card Readers:ISO/IEC 14443-compliant readers dominate legacy installations across Southeast Asian commercial towers. Procurement concentrates in Bangkok and Jakarta Class-A offices where tenant turnover necessitates frequent credential reissuance.
- Biometric Scanners:Fingerprint and facial recognition terminals integrate liveness detection and on-device template storage to satisfy China's GB/T 35273 data localization mandates. Financial institution vaults in Seoul and Singapore generate premium demand for multi-factor fusion systems.
- Keypads:PIN-entry systems persist in cost-sensitive Indian manufacturing facilities and Indonesian logistics warehouses where smartphone penetration remains uneven.
- Mobile Credentials:Smartphone-based authentication eliminates dedicated reader hardware in South Korean and Japanese mid-tier commercial deployments.
Most installed capacity flows through Card Readers. Expansion is steepest in Mobile Credentials.
End User:
Compliance stringency separates customer tiers, with healthcare and government verticals imposing the most rigorous audit trail and data protection requirements.
- Corporations:Multi-tenant commercial towers across China's Greater Bay Area drive demand for API-open credential platforms that integrate with tenant experience applications.
- Educational Institutions:Campus-wide deployments in Indian tier-1 cities prioritize cost-optimized RFID systems with centralized time-attendance logging for administrative compliance.
- Healthcare Facilities:HIPAA-aligned audit mandates and infection-control protocols in Thai and Indian hospitals accelerate touchless biometric adoption for patient and staff zone separation.
- Government Offices:India's BIS certification and China's SAMR enforcement restrict procurement to domestically certified hardware with sovereign encryption standards.
Healthcare Facilities command the highest margin pools. Government Offices are gaining share fastest due to security infrastructure modernization programs.
Technology:
Radio-frequency protocols anchor volume deployment while optical and beacon technologies capture emerging use cases requiring seamless handoff capabilities.
- RFID:13.56 MHz proximity systems remain the default for Indian manufacturing plants and Indonesian logistics hubs where electromagnetic interference is minimal.
- NFC:Near-field protocols integrate with Japan's legacy FeliCa transit infrastructure, creating technical barriers for foreign credential platforms seeking METI-compliant interoperability.
- Bluetooth:Low Energy beacon networks enable seamless handoff between perimeter gates and time-attendance logging in Seoul financial district pilot programs.
- Infrared:Optical signal exchange persists in legacy Chinese government facilities with limited connectivity infrastructure.
RFID carries the largest installed base. Bluetooth is climbing the fastest as smartphone ubiquity eliminates dedicated hardware requirements.
Application:
Use-case complexity determines integration depth, with data security applications demanding the most sophisticated multi-factor architectures.
- Building Access:Perimeter and zone-based entry control dominates procurement across ASEAN smart city infrastructure projects with compressed deployment timelines.
- Attendance Tracking:Time-logging systems concentrate in Indian IT corridors where labor compliance mandates drive enterprise-wide workforce visibility requirements.
- Data Security:Server room and vault access in Singapore and Hong Kong financial centers requires fingerprint-to-mobile credential fusion with edge-computing verification.
- Visitor Management:Temporary credential issuance for contractor and guest access expands fastest in Vietnam and Indonesia mid-tier facilities adopting cloud-native architectures.
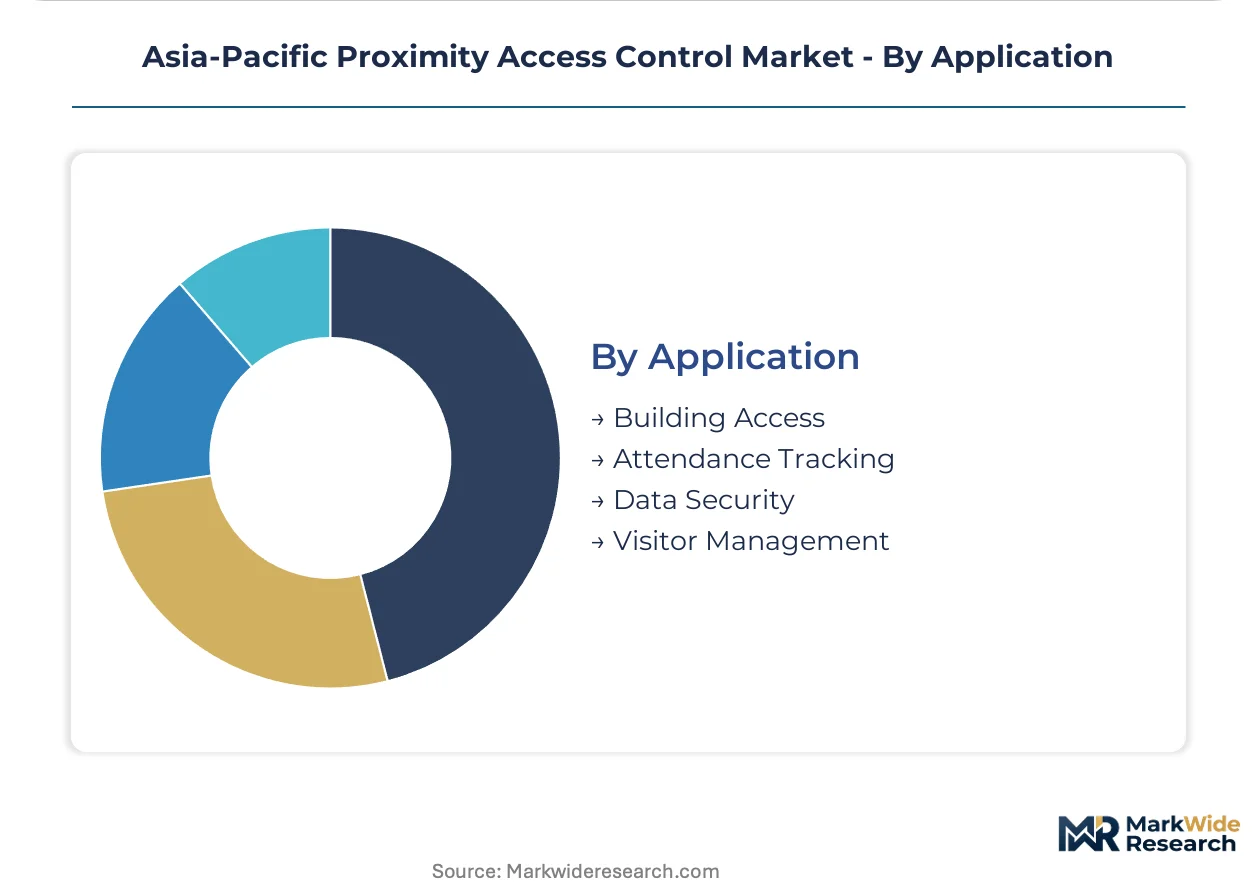
Building Access absorbs the majority of hardware shipments. Visitor Management is expanding most quickly as subscription-based platforms penetrate previously excluded market tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Greater Bay Area anchors regional demand through integrated security zones spanning Shenzhen, Hong Kong, and Macau. Smart city infrastructure mandates across Southeast Asian metros compress procurement cycles for contactless entry systems. Divergent national biometric data standards force vendors to pre-certify hardware against multiple regulatory regimes.
China
GB/T 35273 biometric data protection standards enforced by SAMR mandate on-device template storage and prohibit cloud-based facial recognition archives. Foreign vendors must architect edge-computing credential verification to maintain market presence. Healthcare facilities in Shanghai and Beijing prioritize hardware with domestic encryption certification over international ISO/IEC 27001-aligned alternatives.
India
PLI scheme incentives for electronics manufacturing open cost-competitive assembly pathways for ASEAN and Chinese component suppliers. BIS certification requirements for electronic security products create procedural barriers that domestic assemblers navigate more fluidly than importers. Tier-1 IT corridors in Bangalore and Hyderabad concentrate demand for enterprise-grade workforce visibility systems.
Japan
METI drives JIS-compliant interoperability mandates ensuring NFC-B platforms integrate with legacy FeliCa transit infrastructure. Smartphone ubiquity in Tokyo and Osaka eliminates dedicated card reader hardware from mid-tier commercial installations. Technical barriers to NFC-B migration persist for foreign credential platforms seeking METI-compliant market entry.
South Korea
Bluetooth Low Energy beacon networks enable seamless handoff between perimeter gates and time-attendance logging in Seoul financial district pilot programs. Financial institution vaults pilot fingerprint-activated smartphone credentials that eliminate dedicated reader hardware. Post-pandemic hygiene mandates accelerate touchless authentication adoption across commercial complexes.
Singapore
Cross-border facility clusters require unified credential systems spanning multiple regulatory jurisdictions with stringent data localization requirements. Server room and vault access in financial centers demands fingerprint-to-mobile credential fusion with edge-computing verification. Smart nation infrastructure investments compress deployment timelines for API-open credential platforms.
Asia-Pacific Proximity Access Control Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge sovereign data boundaries and fragmented certification regimes. The vendor base separates into three tiers: multinational building automation conglomerates with bundled climate-access platforms, regional semiconductor-integrated hardware specialists, and mobile-first credential pure-plays. Two strategic archetypes predominate: building automation integrators leveraging climate system relationships to displace standalone access vendors, and captive semiconductor producers controlling RFID module supply chains. M&A activity concentrates on mobile credential software acquisitions, while capacity expansion focuses on India-based assembly facilities exploiting PLI scheme incentives.
Within the building automation integration tier, Honeywell International Inc. exemplifies the bundled platform approach across ASEAN commercial towers. Hangzhou Hikvision Digital Technology Co. Ltd anchors regional hardware supply through captive semiconductor sourcing for RFID module production. Suprema Inc. occupies a specialist position in biometric-to-mobile credential fusion for high-security financial vaults in Seoul and Singapore.
| Leading Market Players |
|---|
| Johnson Controls |
| Honeywell International Inc. |
| Hangzhou Hikvision Digital Technology Co. Ltd |
| Suprema Inc. |
| Schneider Electric |
| Dahua Technology Co. Ltd |
| Avigilon (Motorola Solutions Inc.) |
| ASSA ABLOY |
| Identiv Inc. |
| Others |
Pricing and Supply Chain Analysis
Smart city procurement programs across Southeast Asian metros concentrate buying power among municipal authorities and Class-A commercial developers, forcing vendors into project-based pricing with extended service bundling rather than pure hardware transactions. This buyer consolidation amplifies cost pass-through sensitivity for semiconductor-intensive biometric terminals while compressing margins for standardized RFID reader shipments.
Pricing Analysis
Input-cost pass-through from captive RFID module suppliers in China and Taiwan directly shapes hardware pricing tiers across the region. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified biometric terminals with on-device encryption from ISO/IEC 14443-compliant card readers and basic keypad systems. Pricing pressure stems from India's PLI scheme enabling domestic assembly cost advantages that undercut import-heavy competitor offerings. Tier-2 commercial developers in Vietnam and Indonesia exhibit highest price sensitivity, while financial institution vaults in Singapore and Seoul accept premium positioning for multi-factor fusion systems.
Supply Chain Analysis
Single-source vulnerability sits with Hangzhou Hikvision's captive semiconductor sourcing for RFID module production, creating input bottlenecks for second-tier system integrators lacking alternative supplier relationships. Component manufacturing concentrates in China, Taiwan, and South Korea, with final assembly increasingly shifting to India under PLI incentives. Raw material dependencies span silicon wafers, NFC antenna substrates, and biometric sensor arrays. Tariff exposure on Chinese-sourced encryption modules threatens cost structures for foreign vendors serving India's BIS-certified procurement channels. Distribution runs through regional system integrators with SAMR, BIS, or METI certification capabilities rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
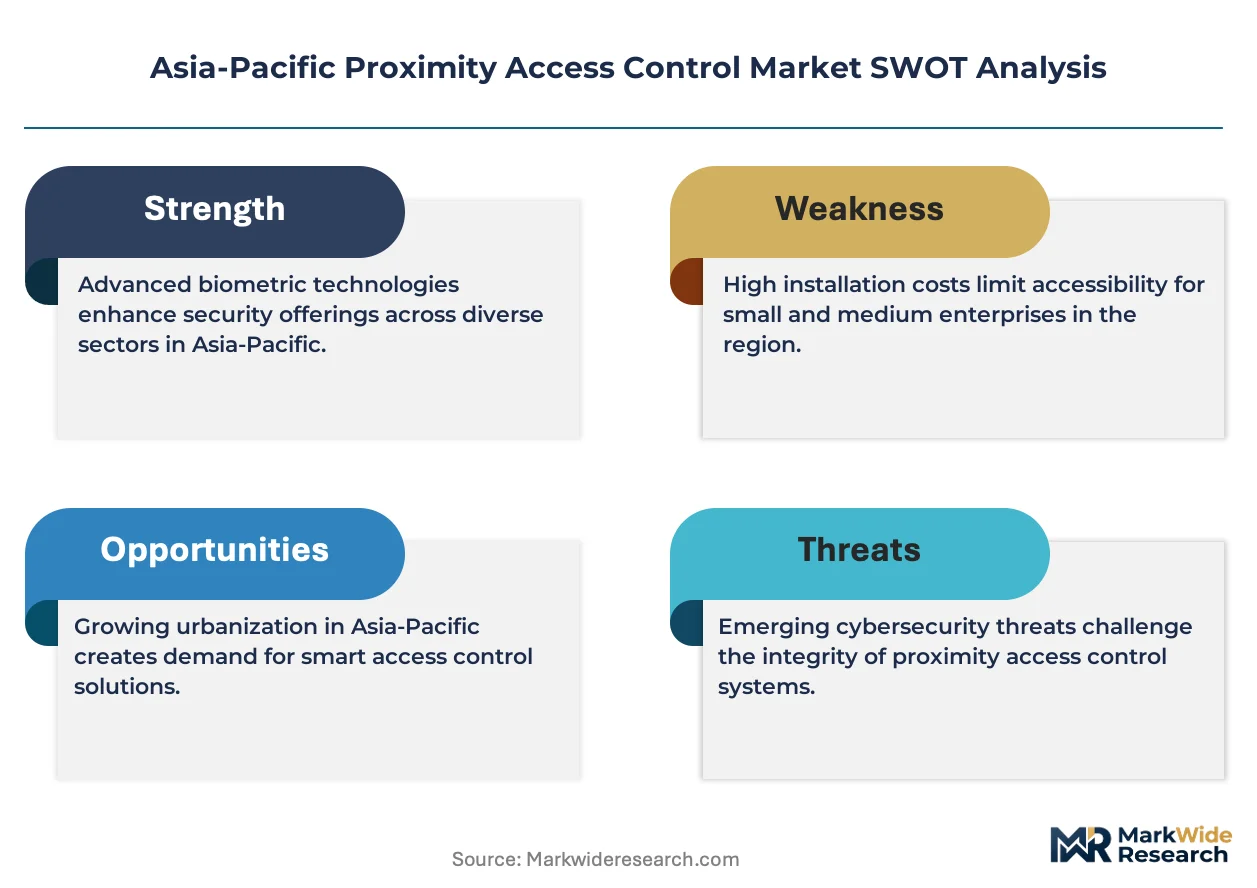
India's PLI assembly incentives against China's GB certification requirements create a geographic-arbitrage corridor where component sourcing from ASEAN suppliers and final integration in Indian facilities captures regulatory cost differentials.
For Market Incumbents: Lock in captive semiconductor supply relationships through long-term offtake agreements with Taiwan and South Korea wafer foundries before input concentration worsens. Defend against mobile credential pure-plays by embedding API-open architectures into building automation bundles for ASEAN commercial towers. Prioritize BIS pre-certification investments in India to compress 4-6 month import lead times versus domestic assembly routes. For New Entrants and Emerging Players: Mid-tier healthcare facilities in Thailand and Indonesia represent the most penetrable buyer archetype, as infection-control mandates accelerate touchless adoption without the certification burden of government or financial verticals. Cloud-native subscription models bypass upfront hardware capital requirements that exclude these operators from enterprise systems. Partner with regional system integrators possessing SAMR or BIS certification capabilities rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Building automation conglomerates are the most active acquirer in this space, seeking mobile credential software capabilities to unbundle climate-access procurement patterns in ASEAN commercial developments. Long-term viability hinges on edge-computing verification architectures that satisfy China's data localization mandates without sacrificing interoperability across Japan's FeliCa infrastructure. Watch for firmware security certification timeline compression at India's STQC as the signal indicating regulatory barriers are easing for foreign algorithm vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Verification Architecture | SAMR's GB/T 35273 mandates on-device biometric template storage, favoring vendors with localized processing capabilities over cloud-dependent platforms. |
| India PLI Assembly Footprint | Domestic electronics manufacturing incentives enable cost-competitive final integration that bypasses BIS certification delays for imported finished goods. |
| API-Open Credential Platform | Tenant experience applications in Greater Bay Area commercial towers demand interoperable systems that displace proprietary building management protocols. |
| Mobile Credential Software Acquisition | Bluetooth Low Energy beacon networks in Seoul financial districts eliminate dedicated reader hardware, shifting value to software licensing revenue pools. |
| Multi-Jurisdiction Certification Pre-Investment | Pre-certification against SAMR, BIS, and METI standards compresses procurement cycles for cross-border facility clusters spanning Shenzhen, Hong Kong, and Macau. |
Research Methodology
Multiple input streams — facility manager interviews across ASEAN commercial towers, procurement officer discussions at Indian IT corridor enterprises, and regulatory affairs consultations with SAMR and BIS certification specialists — were reconciled against secondary validation from customs trade data, SEC filings of listed building automation vendors, and smart city infrastructure procurement databases. Primary fieldwork captured deployment timelines, credential technology preferences, and pricing sensitivity across healthcare, government, and financial verticals. Bottom-up unit shipment estimates triangulated against top-down market value assessments derived from component cost structures and service revenue attachments.
Cross-referencing historical adoption curves with panel input from system integrators and semiconductor suppliers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include hardware form factor, credential technology protocol, end-user vertical compliance stringency, and application use-case complexity. CAGRs were derived from installed base evolution, replacement cycle compression, and smartphone penetration trajectories. Industry-specific forecast inputs incorporated METI interoperability mandates, PLI scheme capacity buildout schedules, and GB standard enforcement timelines for biometric data localization.
Underlying measurement precision varies by segment; mobile credential and cloud-native architecture projections carry tighter precision than legacy keypad system forecasts given divergent visibility into software subscription versus hardware transaction reporting. Forecasts reflect assumptions around certification timeline stability, semiconductor supply continuity, and sovereign data boundary enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Border Security System Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Automated Barriers and Bollards Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
US Access Control Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market