
 North America Safety Connection Devices Market | 2026-2036
North America Safety Connection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Safety Connection Devices Market Foresight
Software-defined diagnostics bundled with safety connection hardware is recalibrating vendor revenue models across North America. Honeywell International Inc. leverages its building automation ecosystem to cross-sell connected safety modules into existing facility management contracts. Rockwell Automation, Inc. anchors its position through deep integration with programmable logic controller architectures that dominate automotive and food processing lines. Schneider Electric SE differentiates by embedding cybersecurity protocols directly into safety switch firmware, addressing NERC CIP-aligned concerns from utility buyers.
Safety connection devices are electromechanical and electronic apparatus engineered to sever power, isolate energy sources, or block hazardous motion when triggered by human intervention or automated sensing, typically rated for SIL 2 or SIL 3 functional safety integrity under IEC 61508 derivative standards. These devices serve to prevent injury and equipment damage in environments where machinery operates at lethal energy levels. Lockout devices and safety switches together command the largest share of product type revenue, though interlock systems are expanding fastest as collaborative robot installations multiply across automotive assembly plants. On the end user dimension, manufacturing absorbs the majority of unit volume, while oil and gas commands premium pricing due to explosion-proof certification requirements and remote operational demands.
OSHA lockout/tagout standards under 29 CFR 1910.147 mandate periodic verification of energy isolation devices, directly sustaining replacement demand and inspection service attach rates. The Canadian Centre for Occupational Health and Safety coordinates provincial adoption of CSA Z460 control of hazardous energy guidelines, creating a harmonized but distinct compliance pathway for cross-border suppliers. CSA Group certification and UL 508 industrial control equipment listings function as de facto market access gates for any safety connection device sold in the United States or Canada. Stakeholders must monitor how NERC CIP physical security directives and evolving state-level machinery safety statutes in California and Texas reshape product specification requirements and channel certification burdens.
Market Dynamics
Wireless IoT architectures are systematically displacing hardwired safety installations across United States and Canadian industrial facilities, compressing installation timelines from weeks to days while forcing incumbent vendors to restructure hardware-software bundling strategies.
Growth Catalysts
- OSHA 29 CFR 1910.147 enforcement:Periodic verification mandates for energy isolation devices sustain replacement cycles and inspection service attach rates across manufacturing facilities.
- Collaborative robot proliferation:Automotive assembly plants in Michigan and Ohio are multiplying interlock system deployments to safeguard human-robot workcells.
- NERC CIP physical security directives:Utility buyers in Texas and California now specify cybersecurity-hardened safety switches, expanding addressable market for firmware-embedded solutions.
Market Restraints
- Copper and rare earth magnet volatility:Electromechanical switch production faces input cost pressure from commodity swings, squeezing margin on standard-rated devices.
- UL 508 certification backlog:Third-party testing laboratory capacity constraints in the United States extend product launch timelines by four to six months.
- Functional safety talent scarcity:SIL 2 and SIL 3 system design expertise concentrates among a limited pool of engineers, inflating labor costs for system integrators.
Strategic Opportunities
- Underpenetrated Canadian prairie provinces:Saskatchewan and Alberta oil sands operations lag Great Lakes corridor in wireless safety adoption, presenting first-mover expansion terrain.
- Outcome-based maintenance contracts:Safety device vendors can capture recurring revenue by guaranteeing uptime rather than selling hardware outright.
- CSA Z460 harmonization:Provincial coordination of hazardous energy control guidelines creates unified certification pathway, reducing cross-border compliance friction.
Industry Challenges
- Legacy PLC integration complexity:Rockwell Automation and Schneider Electric ecosystems dominate automotive and food processing lines, forcing third-party safety module vendors to develop costly protocol adapters.
- SIL certification timeline compression:IEC 61508 derivative assessments for new wireless architectures require eighteen to twenty-four months, delaying product-market fit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Safety Connection Devices Market |
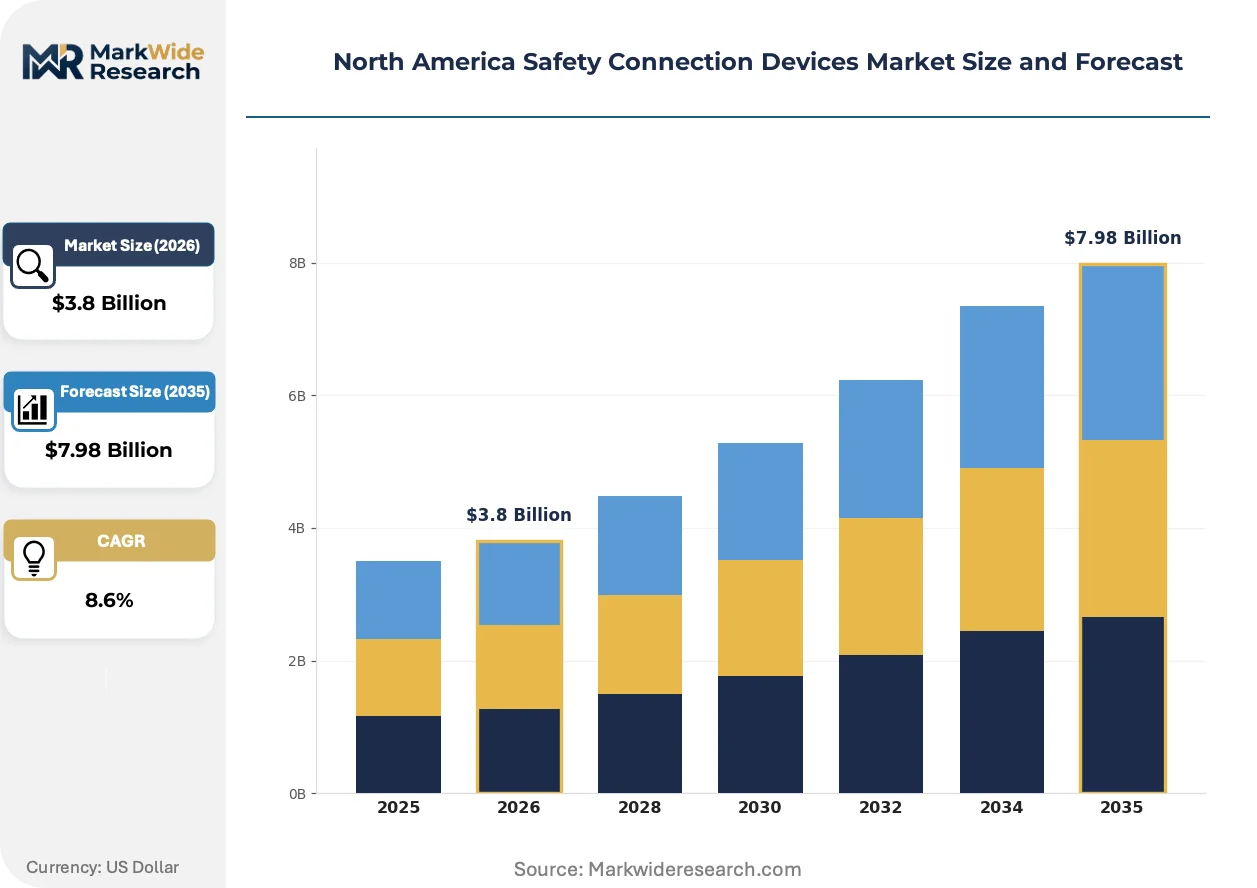
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lockout Devices, Safety Switches, Emergency Stop Buttons, Interlock Systems End User: Manufacturing, Construction, Oil & Gas, Transportation Technology: Mechanical, Electrical, Pneumatic, Hydraulic Application: Industrial Safety, Personal Protection, Equipment Safety, Workplace Safety |
| Companies Covered | Honeywell International Inc., ABB Ltd., Siemens AG, Rockwell Automation, Inc., Schneider Electric SE, Emerson Electric Co., Hubbell Incorporated, Leviton Manufacturing Co., Inc., Advantech Co Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Safety Connection Devices Market Shifts & Advancements
Software-defined functionality is penetrating electromechanical safety hardware, enabling remote diagnostics and predictive maintenance that alter traditional capital equipment depreciation cycles.
Safety-over-Ethernet protocols are modularizing device architectures across the United States manufacturing base. EtherCAT and PROFIsafe implementations now dominate new automotive line installations in Ohio and Illinois. System integrators are compressing commissioning schedules by seventy percent versus hardwired alternatives.
California and Texas state-level machinery safety statutes are tightening beyond federal OSHA baselines, mandating redundant sensing channels for high-risk equipment categories. Food processing facilities in these states face accelerated replacement schedules for single-channel safety switches. Vendors are responding with pre-certified dual-channel product variants.
Buyers in the Great Lakes corridor are consolidating vendor relationships, preferring single-source contracts for safety hardware plus diagnostics software. Distributor networks in Michigan are losing attach rates as direct OEM partnerships capture service revenue. This concentration is most visible among tier-one automotive suppliers operating just-in-time assembly lines.
North America Safety Connection Devices Market Segmentation
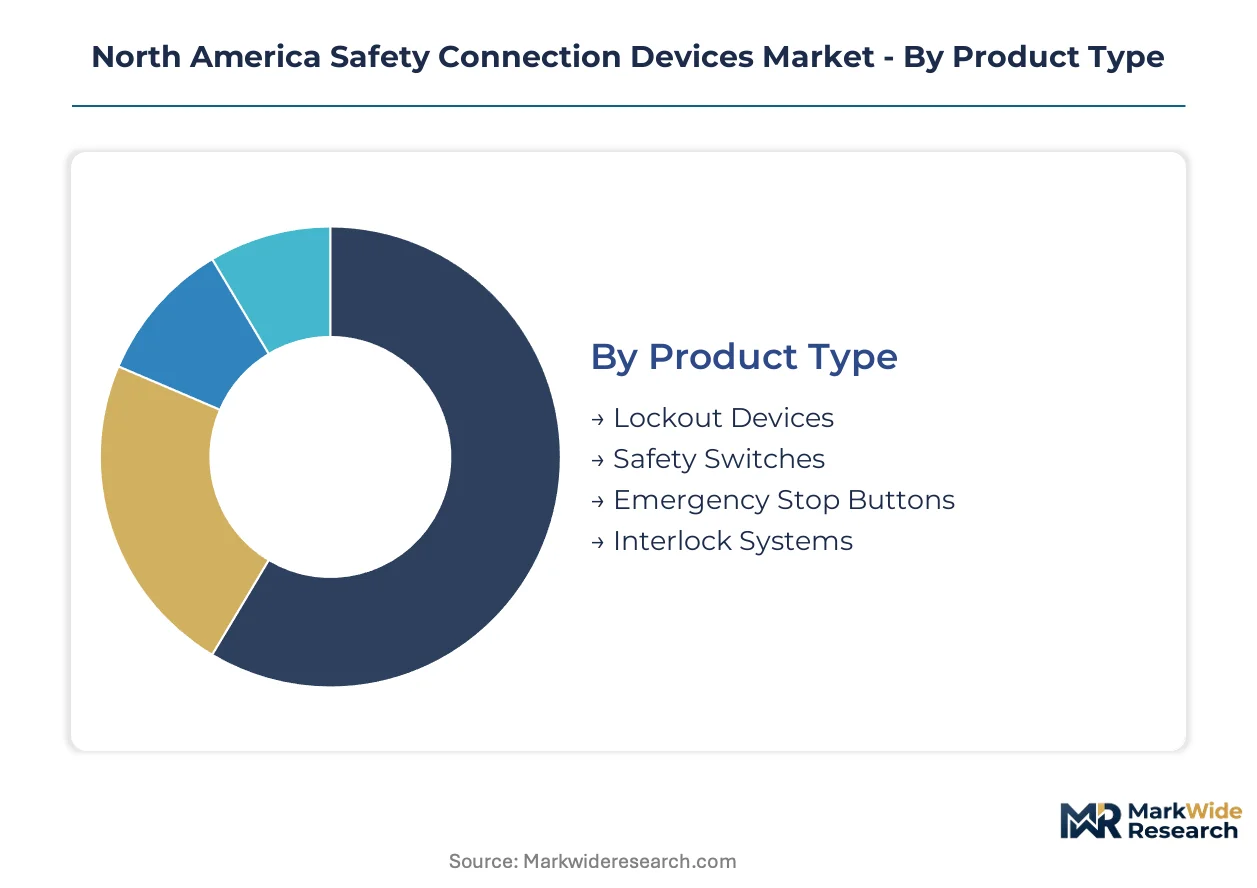
Safety connection device procurement in North America stratifies sharply across product architectures and operational environments. Buyers in Michigan automotive plants specify differently than Alberta oil sands operators, creating distinct margin pools within each segment cluster.
Product Type:
Standardization dominates at the commodity tier while custom-engineered variants command premium positioning in hazardous environments.
- Safety Switches:Electromechanical and solid-state configurations rated for SIL 2 or SIL 3 functional safety integrity under IEC 61508 derivatives. Demand concentrates in Ohio and Illinois food processing lines where redundant sensing channels are now mandated by state-level machinery safety statutes beyond federal OSHA baselines.
- Lockout Devices:Portable and permanent energy isolation apparatus engineered for mechanical, electrical, pneumatic, and hydraulic source verification per 29 CFR 1910.147. Manufacturing facilities across the Great Lakes corridor sustain replacement cycles through periodic verification mandates, with inspection service attach rates expanding vendor recurring revenue.
- Emergency Stop Buttons:Human-machine interface components designed for immediate power severance in lethal energy environments.
- Interlock Systems:Collaborative robot safeguarding architectures multiplying across Michigan and Ohio automotive assembly plants.
Most installed capacity flows through Safety Switches. Expansion is steepest in Interlock Systems.
End User:
Volume concentration sits with high-frequency replacement cycles, while premium pricing attaches to explosion-proof certification requirements.
- Manufacturing:Automotive, food processing, and general industrial facilities absorbing majority unit volume across the United States and Canada. OSHA 29 CFR 1910.147 enforcement sustains hardware refresh schedules and diagnostic service bundling in Michigan, Ohio, and Illinois corridor operations.
- Oil & Gas:Upstream, midstream, and downstream operations in Texas and California commanding premium pricing tiers due to explosion-proof certification requirements and remote operational demands. NERC CIP physical security directives now specify cybersecurity-hardened safety switches, expanding addressable market for firmware-embedded solutions.
- Construction:Temporary and permanent installation sites with mobile equipment safeguarding requirements.
- Transportation:Rail, aviation, and logistics infrastructure with motion-blocking and energy isolation specifications.
Manufacturing absorbs the heaviest unit flow. Oil & Gas climbs fastest on value per unit.
Technology:
Legacy mechanical architectures retain installed base dominance while electrical and smart-enabled variants capture new specification share.
- Electrical:Solid-state and electromechanical switching architectures with embedded diagnostics capability. Wireless IoT-enabled electrical safety devices are compressing installation timelines from weeks to days across United States industrial facilities, forcing incumbent vendors to restructure hardware-software bundling strategies.
- Mechanical:Purely electromechanical apparatus without electronic control elements, facing displacement in new installations.
- Pneumatic:Compressed-air actuated isolation and interlock systems for explosive atmosphere environments.
- Hydraulic:High-force energy isolation for heavy machinery and press applications.
Mechanical retains the largest legacy footprint. Electrical gains specification share fastest in new builds.
Application:
Equipment-centric safeguarding commands hardware margins while personal protection layers drive software attach rates.
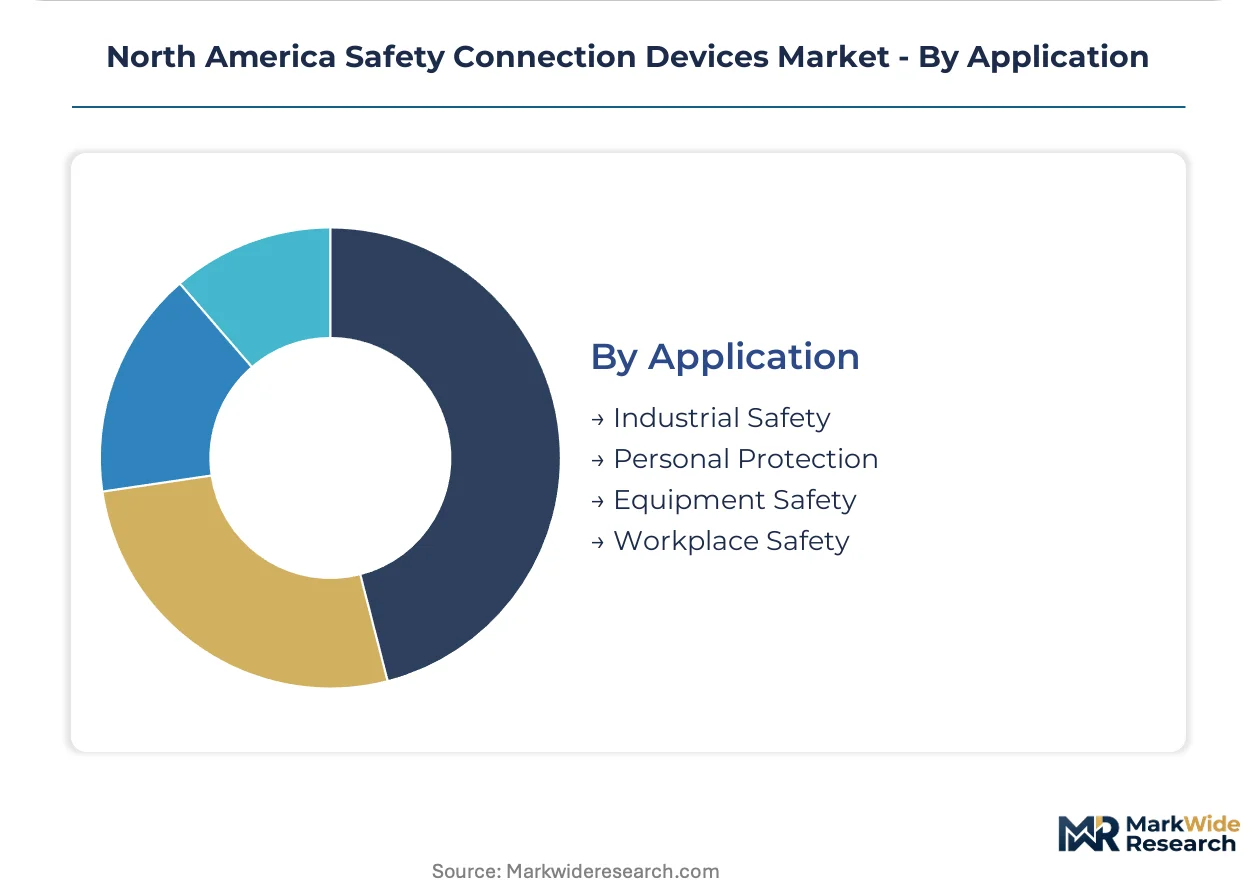
- Industrial Safety:Machinery safeguarding, energy isolation, and process interlocking across production environments. EtherCAT and PROFIsafe implementations now dominate new automotive line installations in Ohio and Illinois, with system integrators compressing commissioning schedules by seventy percent versus hardwired alternatives.
- Equipment Safety:Asset protection and damage prevention specifications with predictive maintenance integration.
- Personal Protection:Direct human safeguarding with wearable and proximity-sensing architectures.
- Workplace Safety:Facility-wide hazard control and environmental monitoring systems.
Industrial Safety carries the deepest specification volume. Equipment Safety is expanding most quickly through predictive maintenance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal across the North American trade bloc, yet provincial and state-level enforcement variance creates localized procurement advantages for vendors with flexible certification pathways.
United States
OSHA 29 CFR 1910.147 enforcement tightens periodically across Michigan, Ohio, and Illinois automotive corridors, sustaining replacement demand for lockout devices and inspection services. The Department of Labor's regional offices in Chicago and Detroit coordinate multi-facility compliance sweeps that accelerate hardware refresh cycles. Cleveland and Toledo assembly plants now specify dual-channel safety switches ahead of anticipated state-level machinery safety statute revisions.
Canada
CSA Z460 provincial harmonization across Ontario, Alberta, and British Columbia reduces cross-border compliance friction for integrated North American supply chains. Health Canada coordinates with provincial ministries to align hazardous energy control guidelines, though Quebec maintains distinct workplace safety administration. Calgary oil sands operations and Vancouver port facilities lag Great Lakes manufacturing in wireless safety adoption, presenting expansion terrain for first-mover vendors.
Mexico
STPS enforcement of NOM-004-STPS-1999 safety standards intensifies across Nuevo León and Baja California maquiladora zones as nearshoring accelerates. Mexican federal labor inspectors now reference OSHA-equivalent lockout/tagout protocols during multinational facility audits. Tijuana and Monterrey electronics assembly plants are importing SIL-rated safety connection devices to satisfy parent company risk management protocols.
North America Safety Connection Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated automation conglomerates commanding premium positioning in automotive and utility verticals while regional electrical distributors capture commoditized replacement volume. Market structure tilts toward consolidation at the high-performance tier, where functional safety certification and cybersecurity-hardened firmware create defensive moats. Three archetypes dominate: full-stack automation platforms with embedded safety modules, standalone safety device specialists with deep SIL certification expertise, and electrical component distributors with private-label sourcing capabilities. Competitive moves center on direct OEM partnerships that displace distributor networks, and outcome-based maintenance contracts that convert capital sales into recurring revenue streams.
Among diversified automation platforms, Honeywell International Inc., Rockwell Automation, Inc., and Schneider Electric SE exemplify the integrated-ecosystem archetype, each leveraging adjacent building or process control franchises to cross-sell connected safety modules. These entities occupy positions where facility management contracts and programmable logic controller architectures create natural attach points for safety connection hardware, with cybersecurity-embedded firmware differentiation addressing utility sector procurement specifications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd. |
| Siemens AG |
| Rockwell Automation, Inc. |
| Schneider Electric SE |
| Emerson Electric Co. |
| Hubbell Incorporated |
| Leviton Manufacturing Co., Inc. |
| Advantech Co Ltd. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between SIL 3-rated safety switches and standard industrial controls manifests in both pricing power and supply chain sourcing strategies across North American procurement networks. Premium-tier vendors command hardware margins through embedded cybersecurity firmware and bundled diagnostics software, while commodity electromechanical suppliers compete on copper input costs and distributor volume rebates.
Pricing Analysis
Distributor margin compression now defines channel economics as direct OEM partnerships displace traditional electrical supply houses in Michigan and Ohio automotive corridors. Three-tier pricing structure across premium, standard, and economy levels aligns with functional safety certification grades, with SIL 3-rated devices carrying brand premiums against UL 508-listed alternatives. Pricing pressure stems from rare earth magnet cost volatility squeezing electromechanical switch margins. Tier-one automotive suppliers exhibit lowest price sensitivity due to just-in-time liability exposure, while general industrial facilities in secondary markets prioritize unit cost over predictive maintenance bundling.
Supply Chain Analysis
UL 508 and CSA Group certification gating concentrates qualified manufacturing among United States, Mexico, and China production bases with established third-party testing relationships. Copper winding assemblies, rare earth magnetic components, and flame-retardant thermoplastic housings constitute critical input dependencies. Single-source vulnerability attaches to specialized SIL certification testing capacity at limited United States laboratories. Distribution runs through integrated automation conglomerates and regional electrical distributors, with direct OEM partnerships capturing increasing attach rates for diagnostics software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Safety Connection Devices Market represents a late-cycle quality story as OSHA enforcement and state-level machinery safety statutes drive specification upgrades toward redundant-channel architectures and firmware-embedded cybersecurity.
For Market Incumbents: Anchor defensive positioning through captive SIL certification expertise and backward integration into safety-over-Ethernet protocol development. Consolidate distributor relationships in the Great Lakes corridor before emerging IoT-native vendors establish direct OEM partnerships. Prioritize CSA Z460 harmonization investments to reduce cross-border compliance friction against Mexican nearshoring competitors. For New Entrants and Emerging Players: Direct-to-OEM digital sales channels offer the lowest customer acquisition cost entry vector for wireless-enabled safety module vendors without legacy distributor encumbrance. Target Saskatchewan and Alberta oil sands operations where wireless adoption lags Great Lakes manufacturing benchmarks. Lead with outcome-based maintenance contracts that convert capital sales into recurring revenue streams. For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety talent scarcity and eighteen-to-twenty-four-month SIL certification timelines create defensive moats for established players. Mid-cap specialists with deep IEC 61508 derivative expertise and automotive vertical penetration represent optimal acquisition profiles. Monitor NERC CIP physical security directive enforcement intensity as inflection indicator for cybersecurity-hardened safety switch demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Maintenance Contracts | Converts capital equipment sales into recurring revenue streams with uptime guarantees. |
| Backward Integration into Safety-over-Ethernet Protocols | Reduces commissioning timelines seventy percent versus hardwired alternatives in automotive lines. |
| CSA Z460 Harmonization Investment | Creates unified certification pathway across Ontario, Alberta, and British Columbia provincial markets. |
| Cybersecurity Firmware Embedding | Addresses NERC CIP physical security directives specifying hardened safety switches for utility buyers. |
| Direct OEM Partnership Development | Displaces distributor networks in Michigan and Ohio automotive corridor consolidation trend. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through OSHA enforcement databases and CSA Group certification records, and customs trade data on electromechanical switch imports — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included maintenance directors at Tier 1 automotive suppliers, safety system integrators specializing in collaborative robot installations, distributor category managers, and regulatory affairs leads at integrated automation conglomerates. Secondary sources encompassed 29 CFR 1910.147 enforcement action reports, provincial adoption tracking of CSA Z460 guidelines, and SEC filings from publicly traded safety device manufacturers.
Historical shipment data was cross-referenced against panel input from system integrators and OEM procurement teams to construct the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, functional safety integrity level, end-use vertical, and technology adoption stage. CAGRs were derived through regression analysis of replacement cycle frequencies and regulatory enforcement intensity trends. Industry-specific forecast inputs incorporated collaborative robot installation rates in Michigan and Ohio automotive plants and NERC CIP directive implementation timelines in Texas and California utility sectors.
The model assumes a particular technology adoption path; alternative pathways for wireless IoT-enabled safety architectures would alter the outlook if UL 508 certification backlogs persist beyond current laboratory capacity constraints. Forecasts reflect assumptions regarding OSHA regional enforcement intensity and provincial harmonization velocity for CSA Z460 guidelines. A model refresh is warranted upon material change in NERC CIP physical security directive scope or state-level machinery safety statute adoption beyond federal baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
United Kingdom Access Control Market
Access Control Systems
Vehicle Security System Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Japan Access Control Market
Access Control Systems
France Access Control Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
North America Home Security System Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Pre-Departure Clearance System Market