
 US Access Control Market | 2026-2036
US Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
US Access Control Market Outlook
UL 294 certification for access control system units is redrawing competitive boundaries for incumbents and challengers alike. Honeywell International leverages its building automation footprint to bundle access control with HVAC and fire safety systems. ASSA ABLOY anchors its position through captive manufacturing of electromechanical locks and door hardware. Allegion specializes in cloud-connected commercial entry solutions that bridge physical and logical security layers.
Access control systems comprise credential readers, controllers, locking mechanisms, and management software that authenticate and authorize entry to secured facilities, typically operating on 12-24V DC power with Wiegand or OSDP communication protocols. Biometric technology leads segment value due to fingerprint and facial recognition deployments in high-assurance environments, while RFID maintains volume dominance across commercial real estate for its cost efficiency. The service type dimension concentrates margin pools in integration and consulting, where channel partners configure multi-site enterprise rollouts.
FCC regulations govern wireless access control transmissions, while NIST standards shape federal procurement requirements for cryptographic modules and identity verification. OSHA workplace safety directives indirectly drive demand for emergency lockdown and muster reporting capabilities in industrial settings. Buyers should monitor how NIST's zero-trust architecture mandates migrate from federal to commercial adoption patterns.
Market Dynamics
The NIST Cybersecurity Framework revision is compressing procurement cycles for federal contractors while forcing commercial buyers toward zero-trust architectures that revalidate identity at every access point. This regulatory pressure is restructuring vendor qualification requirements and channel partner certification programs across the installed base.
Growth Catalysts
- Healthcare biometric mandates:HIPAA-covered entities are deploying fingerprint and facial recognition systems to satisfy audit requirements for patient data access logging. Hospital systems in Texas and California lead deployment velocity.
- OSHA workplace safety directives:Industrial facilities must install emergency lockdown and muster reporting capabilities, driving controller upgrades and integration with mass notification systems.
- FCC spectrum allocation:Wireless access control devices operating in designated frequency bands enable retrofit installations without conduit runs, accelerating adoption in historic buildings and leased commercial space.
Market Restraints
- Semiconductor supply concentration:Controller board fabrication depends on concentrated Asian foundry capacity, creating lead time volatility for OSDP-compliant edge devices.
- Copper and rare earth input costs:Electromechanical locking mechanisms require neodymium for high-torque motor assemblies, exposing margins to commodity price swings.
- Legacy Wiegand protocol persistence:Installed base of non-encrypted credential readers creates security vulnerabilities that delay full OSDP migration and fragment procurement decisions.
Strategic Opportunities
- Cloud-native management platforms:Multi-site enterprises in the Midwest are replacing on-premise servers with subscription-based access control as a service, unbundling hardware from software revenue.
- IRA energy efficiency incentives:Federal tax credits for building electrification are bundling access control upgrades with HVAC and lighting retrofits in commercial real estate portfolios.
- Mobile credential convergence:Integration of smartphone-based authentication with existing physical security infrastructure opens retrofit opportunities in university and corporate campuses.
Industry Challenges
- UL 294 certification bottlenecks:Third-party testing laboratory capacity constraints extend product validation timelines for new controller designs, delaying market entry.
- Integration complexity:Multi-vendor environments require specialized labor for Wiegand-to-OSDP protocol bridging and legacy database migration, stretching systems integrator capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Access Control Market |
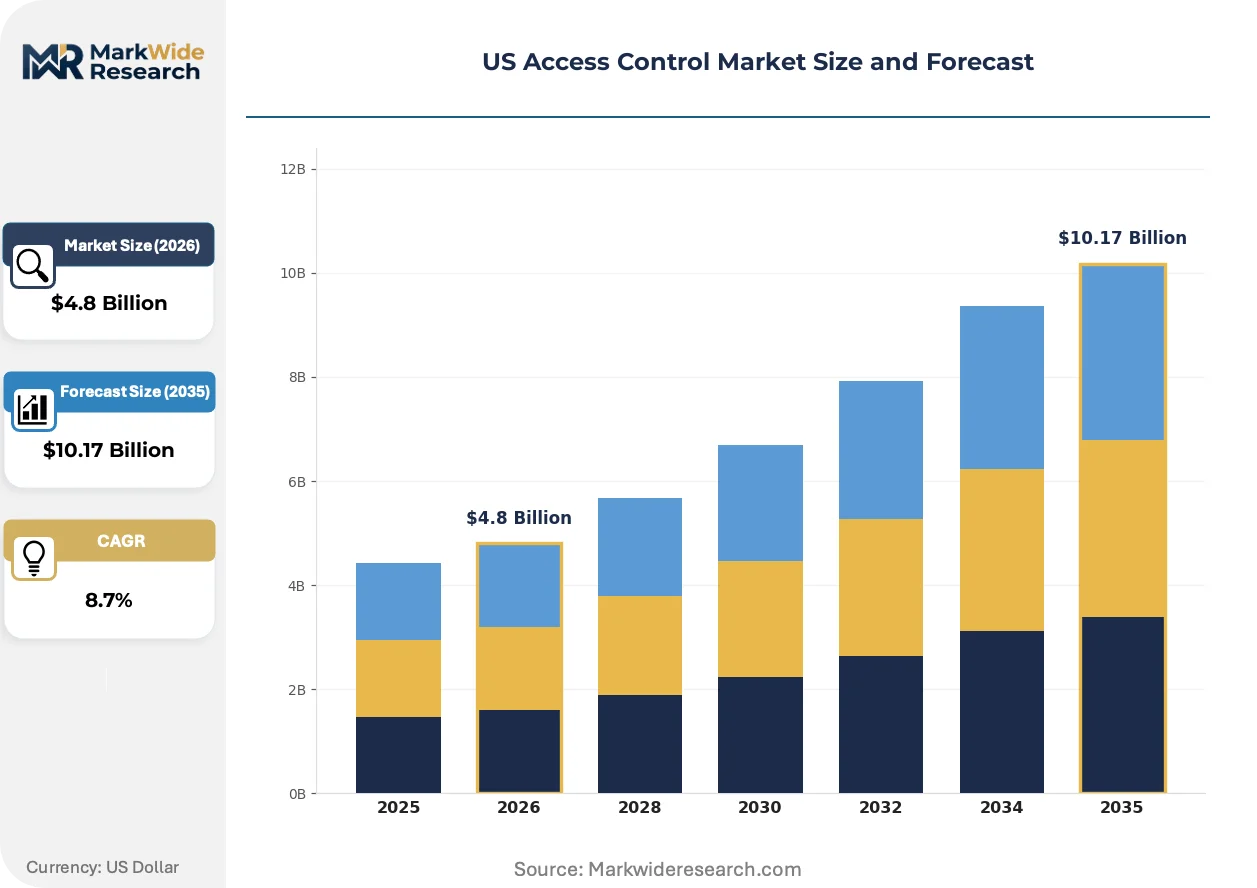
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric, RFID, Keypad, Smart Card End User: Commercial, Residential, Government, Healthcare Application: Physical Security, Employee Access, Visitor Management, Remote Monitoring Service Type: Installation, Maintenance, Consulting, Integration |
| Companies Covered | Honeywell International, Robert Bosch, ASSA ABLOY, Suprema, Stanley Black and Decker, Johnson Controls International, dormakaba Group, Axis Communications, Allegion, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Access Control Market Strategic Shifts
Credential authentication methods are fragmenting across biometric, mobile, and traditional card formats as buyers prioritize risk-appropriate security tiers over uniform deployment. This diversification is forcing manufacturers to support multiple credential technologies within single platform architectures.
Biometric access control is bifurcating between high-assurance facial recognition deployments for federal and healthcare facilities and cost-optimized fingerprint readers for commercial real estate. Financial services buyers in New York and Chicago are adopting touchless facial authentication to satisfy hygiene protocols and audit requirements. This technology split is compressing mid-tier product lines and forcing vendors to choose between premium certification investments or volume commodity positioning.
The NIST Cybersecurity Framework 2.0 revision mandates continuous identity verification and least-privilege access for federal contractors, cascading into state procurement specifications. Defense industrial base suppliers must re-architect their physical access systems to satisfy CMMC 2.0 audit criteria. Commercial manufacturers serving this segment are accelerating zero-trust feature development while federal agencies extend these requirements to grant-funded infrastructure projects.
Enterprise buying committees are unbundling hardware procurement from integration and managed services, compressing traditional channel markups. Fortune 500 facilities teams in California and Texas are issuing separate RFPs for credential readers, software licenses, and ongoing support, bypassing single-source systems integrators. This disintermediation is most visible in technology corridor campuses where in-house security operations centers demand direct API access to management platforms.
US Access Control Market Segmentation
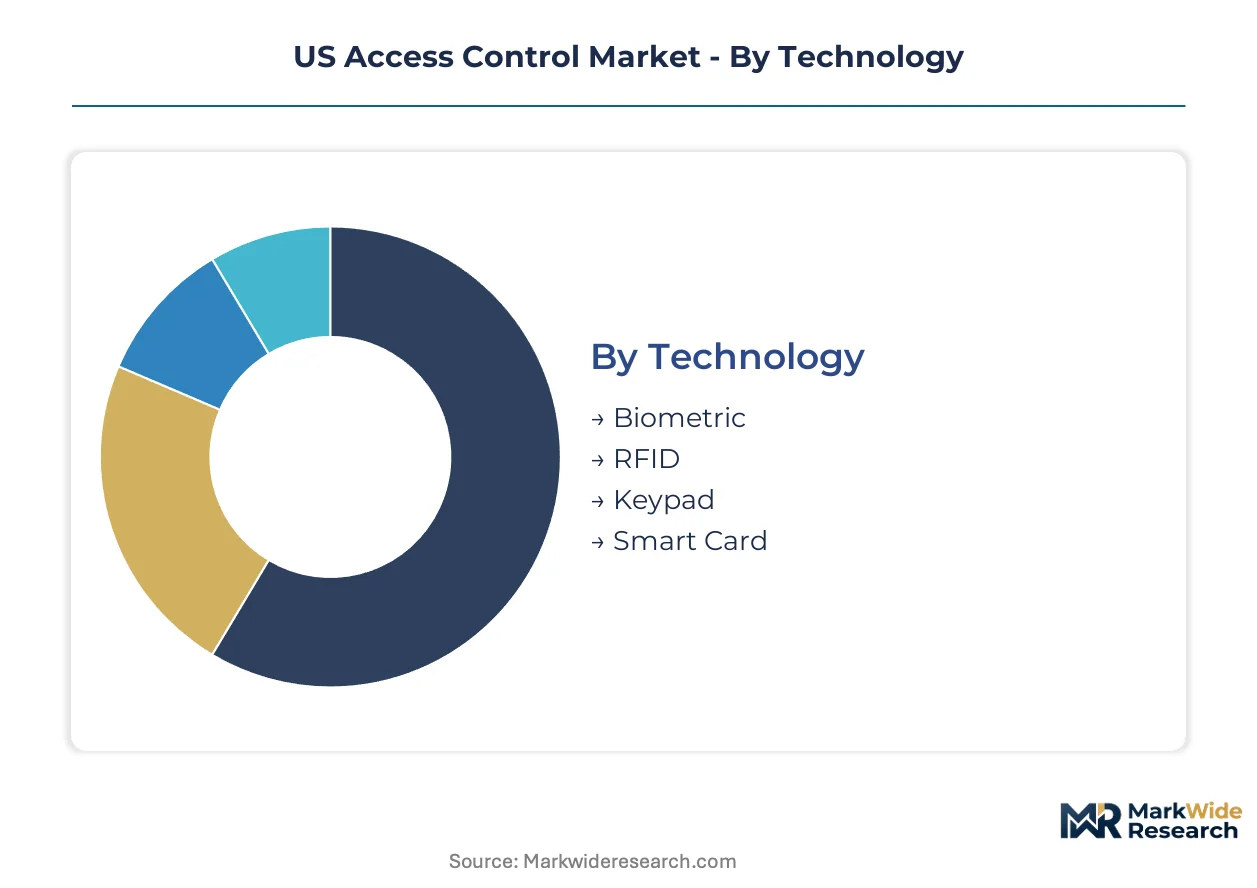
Access control procurement patterns diverge sharply across technology maturity, end-user risk profiles, and service delivery models. Understanding these fault lines reveals where federal mandates reshape buying behavior versus where commercial retrofit economics dominate deployment decisions.
Technology:
Biometric and RFID deployments concentrate in domestic federal and healthcare facilities, while keypad and smart card systems serve price-sensitive commercial retrofits with lighter certification burdens.
- Biometric:Fingerprint and facial recognition systems authenticate identity through physiological characteristics, requiring NIST-compliant cryptographic modules for federal installations. Hospital systems in Texas and California deploy these for HIPAA audit trails, with defense contractors in Virginia adopting touchless variants to satisfy CMMC 2.0 criteria.
- RFID:Radio-frequency credential readers operate at 125kHz or 13.56MHz frequencies, enabling hands-free entry in high-throughput commercial environments. Corporate campuses in Illinois and Massachusetts favor these for employee parking and building entry, though legacy Wiegand protocol vulnerabilities delay full OSDP migration.
- Keypad:PIN-based entry systems offer standalone authentication without credential issuance overhead.
- Smart Card:Contactless IC cards with embedded microprocessors support multi-application credentials.
RFID commands the established base across commercial real estate portfolios. The steepest expansion runs through biometric deployments driven by federal zero-trust mandates and healthcare audit requirements.
End User:
Cost tiers separate mission-critical federal installations from commoditized residential retrofits, with government and healthcare buyers absorbing premium pricing for certified systems.
- Commercial:Office buildings, retail centers, and hospitality properties prioritize cost efficiency and rapid tenant turnover accommodation. Property managers in Florida and Arizona favor wireless retrofit solutions to avoid conduit runs in leased spaces, bundling access control with HVAC upgrades under IRA tax credit programs.
- Healthcare:HIPAA-covered entities require comprehensive audit logging for patient data access points. Hospital networks in Pennsylvania and Ohio lead fingerprint deployment for pharmacy and records room entry, with emergency departments adopting facial recognition for hygiene compliance.
- Government:Federal agencies and defense contractors face NIST Cybersecurity Framework 2.0 mandates for continuous identity verification.
- Residential:Multi-family housing and smart home installations emphasize smartphone integration and subscription-based management.
Commercial end users represent the volume anchor across installed access points. Healthcare and government segments are climbing the fastest as regulatory compliance compresses procurement cycles.
Application:
Physical security and employee access applications dominate domestic facility hardening, while visitor management and remote monitoring gain traction in distributed enterprise architectures.
- Physical Security:Perimeter protection, door control, and intrusion prevention systems form the foundational layer of facility protection. Critical infrastructure operators in Louisiana petrochemical corridors deploy these with OSHA-mandated emergency lockdown integration.
- Remote Monitoring:Cloud-connected controllers enable centralized oversight of geographically dispersed sites. Fortune 500 security operations centers in Washington and Colorado demand API-accessible platforms for real-time status visibility.
- Employee Access:Workforce credentialing and time-and-attendance integration streamline building entry.
- Visitor Management:Temporary credential issuance and pre-registration systems manage guest workflows.
Physical security applications hold the dominant share of controller deployments. Remote monitoring capabilities are expanding most quickly as multi-site enterprises unbundle hardware from cloud-native management subscriptions.
Service Type:
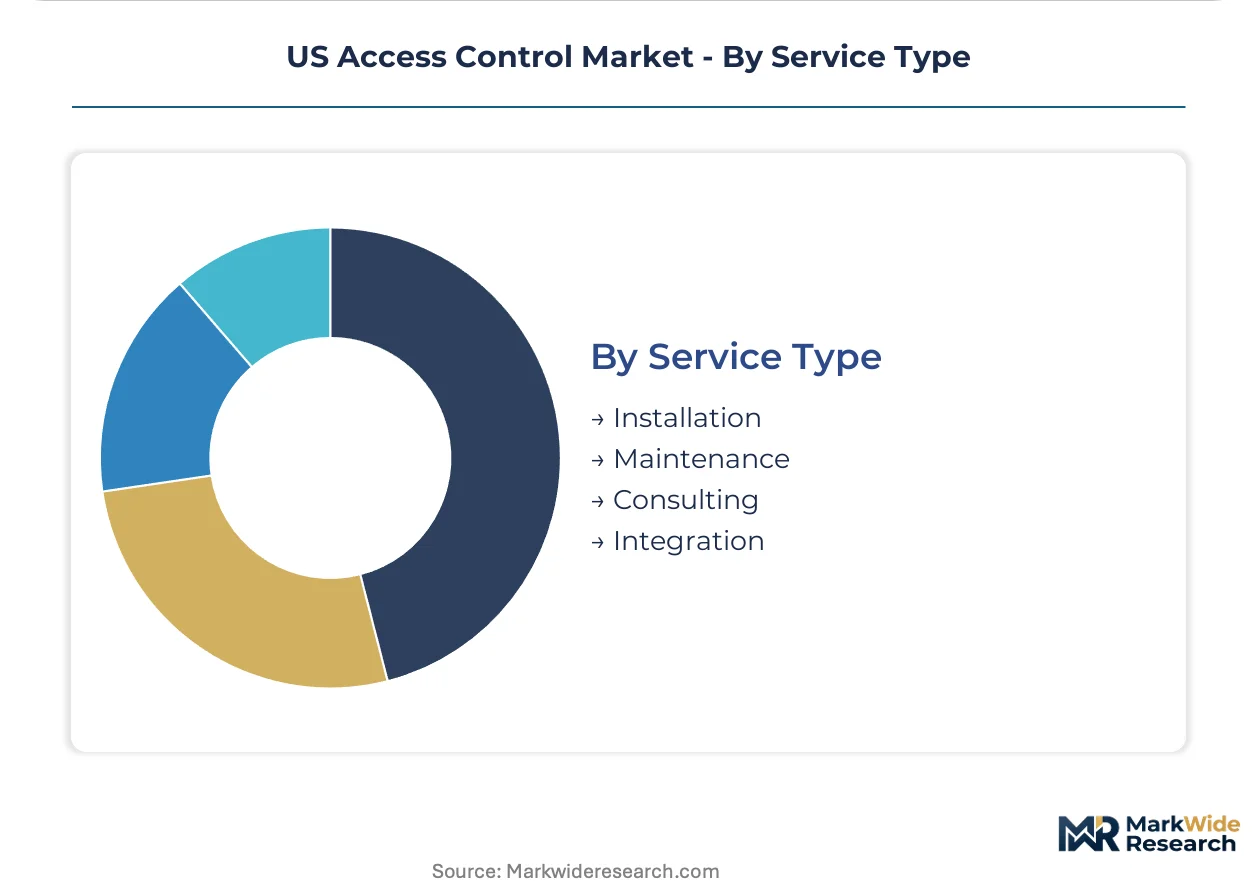
Margin concentration favors consulting and integration services where specialized labor bridges multi-vendor complexity, while installation and maintenance compete on labor arbitrage.
- Integration:Multi-site enterprise rollouts require protocol bridging between legacy Wiegand and modern OSDP infrastructures, plus database migration and API configuration. Systems integrators in Michigan and Georgia command premium rates for federal contractor compliance projects.
- Consulting:Risk assessment, zero-trust architecture design, and CMMC 2.0 readiness planning guide procurement strategy. Security consultants advise defense industrial base suppliers on physical-logical security convergence.
- Installation:Controller mounting, reader placement, and wiring termination represent labor-intensive deployment phases.
- Maintenance:Firmware updates, credential lifecycle management, and hardware replacement sustain system performance.
Installation services anchor the revenue base through new construction and retrofit volumes. Integration and consulting are gaining share fastest as procurement disintermediation fragments buying committees and compliance complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach cargo volume underwrites California's role as the primary demand node for enterprise access control systems serving technology and logistics corridors.
California
Technology corridor campuses in Silicon Valley and San Francisco drive cloud-native access control procurement for multi-site enterprises. NIST Cybersecurity Framework 2.0 mandates cascade through federal contractors in San Diego defense clusters. Hospital systems in Los Angeles deploy biometric facial recognition for HIPAA audit compliance.
Texas
Energy sector facilities in Houston petrochemical corridors require OSHA-mandated emergency lockdown integration with access controllers. Federal tax credits under the Inflation Reduction Act bundle access control with HVAC electrification retrofits in Dallas-Fort Worth commercial portfolios. Defense contractors in Austin adopt CMMC 2.0-compliant biometric systems.
Illinois
Financial services buyers in Chicago prioritize touchless facial authentication for trading floor hygiene protocols and audit trails. Corporate campuses in suburban Cook County favor RFID credentialing for employee parking and building entry. Legacy Wiegand protocol migration creates integration demand for OSDP-compliant edge devices.
Pennsylvania
Hospital networks in Philadelphia and Pittsburgh lead fingerprint deployment for pharmacy and patient records room entry. Federal grant-funded infrastructure projects extend zero-trust physical security requirements to state agencies. Industrial facilities in the Delaware Valley integrate muster reporting with mass notification systems.
Virginia
Defense industrial base suppliers in Northern Virginia re-architect physical access systems to satisfy CMMC 2.0 audit criteria. NIST standards shape procurement for cryptographic modules across federal contractor facilities. Cloud-connected controllers enable centralized oversight of dispersed classified sites.
US Access Control Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and service delivery models. The vendor base stratifies between building automation conglomerates bundling access control with HVAC and fire safety, electromechanical lock manufacturers with captive hardware production, and cloud-native software platforms unbundling hardware from subscription revenue. Three archetypes dominate: integrated building systems providers, specialized door hardware fabricators, and identity management software vendors. Competitive moves concentrate on UL 294 certification acceleration and zero-trust feature development for federal compliance.
Within the integrated systems tier, Honeywell International and Johnson Controls International exemplify building automation bundling strategies. ASSA ABLOY occupies a position as a hardware-centric specialist with captive manufacturing capabilities. Among cloud-native platforms, Allegion represents the bridge between physical and logical security layers. These three anchors illustrate how certification investments and channel relationships structure competitive positioning.
| Leading Market Players |
|---|
| Honeywell International |
| Robert Bosch |
| ASSA ABLOY |
| Suprema |
| Stanley Black and Decker |
| Johnson Controls International |
| dormakaba Group |
| Axis Communications |
| Allegion |
| Others |
Value Chain & Pricing Dynamics
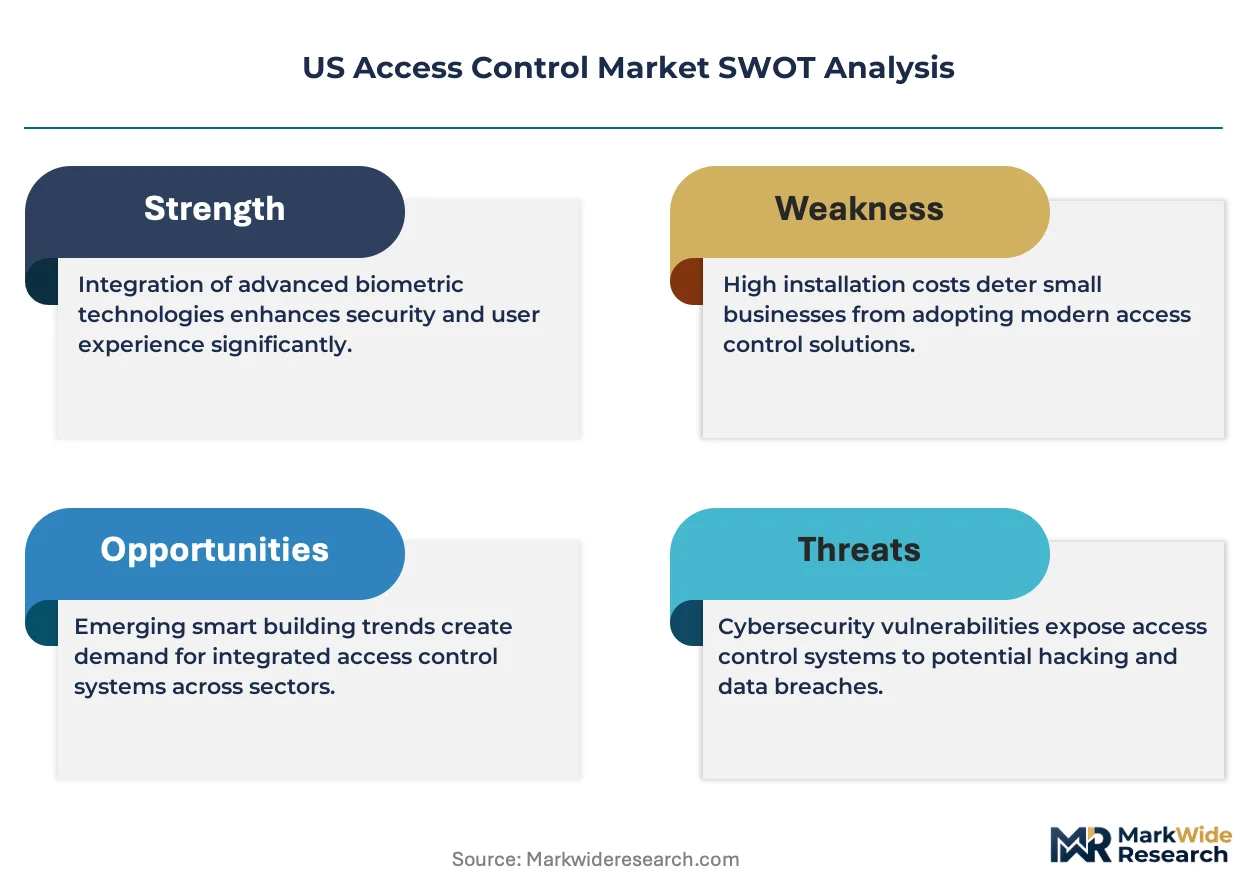
UL 294 certification gates both vendor qualification and price differentiation in the US access control market, creating a bifurcated structure where certified incumbents command premium positioning while uncertified challengers compete on hardware margins alone. This regulatory threshold simultaneously constrains supply-side entry and enables tiered pricing power for compliant manufacturers serving federal and healthcare verticals.
Pricing Analysis
Volume-discount tiering separates enterprise multi-site rollouts from single-facility retrofits, with Fortune 500 buyers extracting 15-25% hardware concessions on OSDP-compliant controller orders above 500 units. Price differentiation hinges on NIST FIPS 140-2 cryptographic module certification and UL 294 listing status, with federal contractors absorbing 40-60% premiums for zero-trust-ready platforms. Pricing pressure stems from cloud-native software vendors unbundling subscription revenue from hardware margins, compressing traditional channel markups. Commercial real estate property managers exhibit highest price sensitivity, while defense industrial base suppliers prioritize audit compliance over unit economics.
Supply Chain Analysis
Controller inventory lead times stretch 16-24 weeks for OSDP-compliant edge devices, reflecting concentrated Taiwanese and South Korean foundry capacity for secure microcontroller fabrication. Electromechanical locking mechanisms draw from Chinese rare earth processing for neodymium motor assemblies and Chilean copper cathode for winding wire. Single-source vulnerability concentrates in cryptographic module packaging, where domestic NIST-accredited laboratories represent sole qualified suppliers. Distribution runs through authorized systems integrators in Michigan and Georgia, with direct OEM relationships penetrating Fortune 500 security operations centers demanding API access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Fortune 500 facilities teams and federal procurement offices, fragmenting traditional single-source integrator relationships and forcing vendors to unbundle hardware, software, and service components.
For Market Incumbents: Compound defensive positioning by accelerating UL 294 certification for next-generation biometric controllers before NIST Cybersecurity Framework 2.0 mandates cascade to state procurement specifications. Deepen backward integration into captive electromechanical lock manufacturing to offset rare earth price volatility, while establishing direct API partnerships with California and Texas technology corridor campuses to bypass disintermediating channel partners. For New Entrants and Emerging Players: Cloud-native integration services represent the most penetrable white-space, as incumbent hardware vendors under-serve Midwest multi-site enterprises replacing on-premise servers with subscription-based access control as a service. Target Illinois financial services buyers seeking touchless facial authentication retrofit without full infrastructure replacement. Lead with managed compliance offerings bundling CMMC 2.0 readiness planning with hardware procurement to differentiate from product-centric competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software platforms, enabling asset-light scaling without foundry investments or certification laboratory buildouts. Long-term viability favors vendors with recurring revenue exposure and federal compliance moats. Watch NIST zero-trust architecture migration patterns as the inflection signal distinguishing sustainable subscription growth from hardware commoditization traps.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | NIST compliance enables federal contractor premium positioning and defensible recurring revenue. |
| Cloud-Native Platform Migration | Subscription unbundling from hardware captures Midwest enterprise multi-site replacement cycles. |
| Biometric Controller Development | Touchless facial recognition satisfies Texas and California healthcare hygiene mandates. |
| Systems Integrator Acquisition | Channel control restores margin capture from disintermediating Fortune 500 direct procurement. |
| OSDP Protocol Migration Services | Legacy Wiegand bridging addresses Illinois and Pennsylvania integration complexity demand. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with security operations center directors, federal contractor compliance officers, systems integrators in Michigan and Georgia, and healthcare facilities managers in Texas and Pennsylvania. Secondary validation drew from FCC equipment authorization databases, NIST Cybersecurity Framework revision documents, UL 294 certification listings, and OSHA workplace safety directive filings. Bottom-up deployment tallies triangulated against top-down vendor revenue segmentation across technology, end-user, and service type dimensions.
Across the analysis window, the forecasting framework modeled biometric, RFID, keypad, and smart card technology segments alongside commercial, healthcare, government, and residential end-user categories. Integration, consulting, installation, and maintenance service types were separately projected. CAGRs were derived from facility construction permit flows, federal procurement pipeline visibility, and healthcare capital expenditure survey data. IRA tax credit utilization rates and CMMC 2.0 audit timeline assumptions informed retrofit acceleration scenarios.
Forecasts assume regulatory continuity in NIST Cybersecurity Framework implementation, OSHA emergency lockdown mandates, and FCC spectrum allocation for wireless devices; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Keyless Vehicle Access Control System Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Border Security System Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Smart Entry System Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Automated Smart Locker System Market