
 Electronic Cylinder Lock Credentials Market | 2026-2036
Electronic Cylinder Lock Credentials Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Cylinder Lock Credentials Market Analysis
Germany is narrowing the competitive gap in electronic cylinder lock manufacturing through precision engineering clusters around Stuttgart and Munich. ASSA ABLOY leverages its vertically integrated European production network to dominate high-security institutional contracts. SALTO Systems anchors its position through specialized wireless credential platforms for hospitality and education verticals. Dormakaba Holding AG competes on modular cylinder architectures that simplify retrofit installation across aging European building stock.
Electronic cylinder lock credentials are electromechanical access control devices that authenticate users through encrypted digital keys, biometric templates, or radio-frequency identifiers before actuating a motorized locking mechanism. These systems typically operate on battery or Power-over-Ethernet supplies and integrate with building management networks to log entry events in real time. Smart locks and RFID locks command the largest installed bases, though biometric locks are capturing disproportionate margin pools in high-assurance government and data center applications. Wireless and Bluetooth technologies lead volume shipments, while Z-Wave and Zigbee installations cluster in integrated smart home and commercial automation ecosystems where protocol standardization reduces deployment friction.
The EU Cybersecurity Act and EN 50133 alarm systems standards shape product certification timelines and technical requirements for connected locks sold across Europe. Germany's KBA and France's CNIL influence data governance and physical security convergence through divergent interpretations of credential storage and transmission protocols. Stakeholders must monitor whether emerging EU AI Act provisions will extend to biometric lock algorithms and force recertification of existing facial and fingerprint recognition modules.
Market Dynamics
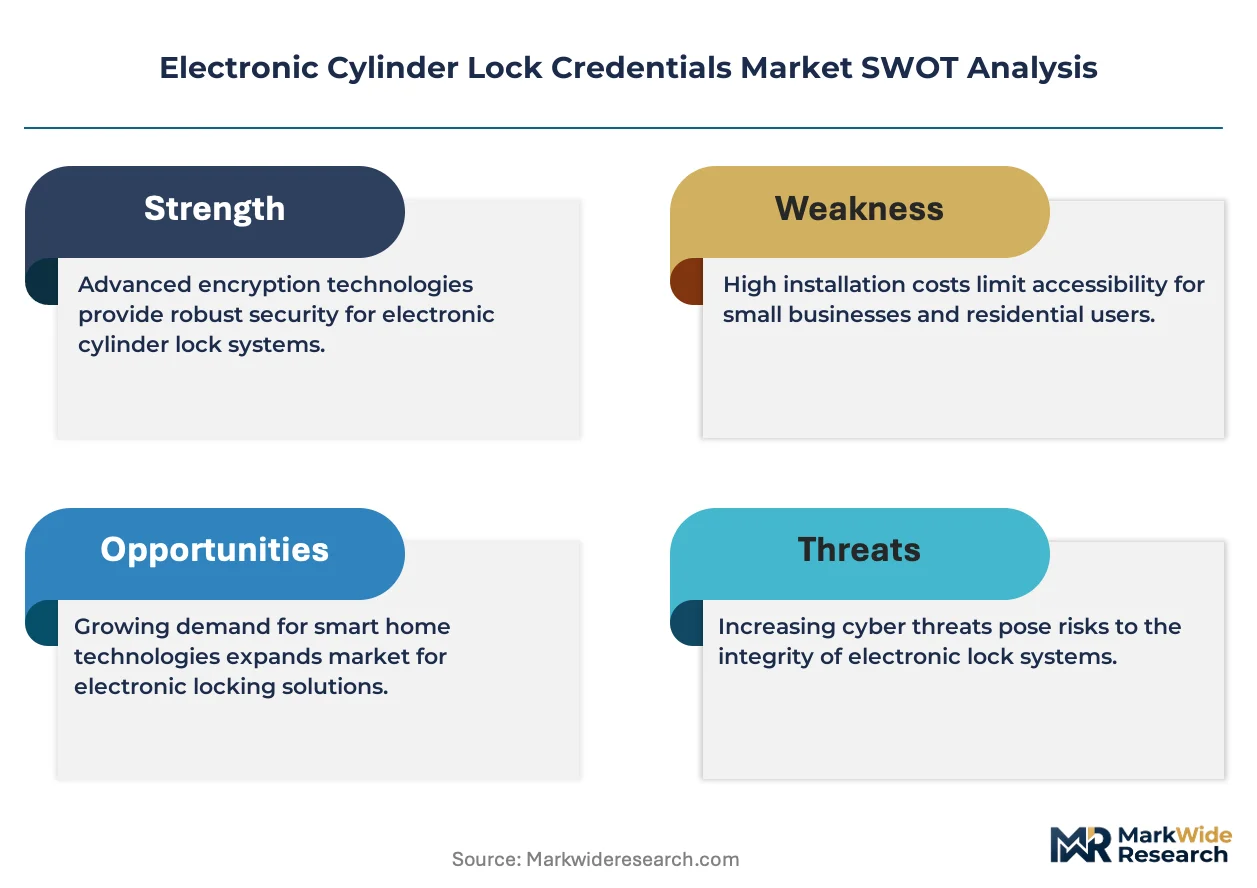
The Electronic Cylinder Lock Credentials Market is experiencing a structural compression between cybersecurity mandates and retrofit economics, as EN 50133 certification timelines extend product development cycles while aging European building stock demands faster deployment. This tension concentrates competitive advantage among manufacturers with captive testing facilities and modular hardware architectures.
Growth Catalysts
- EU Cybersecurity Act certification pathways:Mandatory third-party assessment for connected locking devices creates order backlog visibility for pre-qualified suppliers and locks out uncertified competitors from institutional procurement pools.
- Multi-unit housing operators:Property managers across Germany and France are consolidating access control under single-platform mobile credential systems to reduce rekeying costs and streamline tenant turnover workflows.
- Bluetooth Low Energy module cost curves:Semiconductor pricing for wireless credential transceivers has compressed hardware BOMs, enabling mid-market lock manufacturers to match premium wireless feature sets.
Market Restraints
- Lithium primary battery supply concentration:Cylindrical cell production for lock power supplies clusters in East Asian manufacturing zones, exposing European assemblers to freight cost volatility and customs processing delays.
- EN 50133-1 alarm system integration mandates:Connected locks sold into French and German commercial buildings must demonstrate interoperability with certified intrusion detection panels, extending engineering validation timelines.
- Mechanical master key systems:Legacy pin-tumbler infrastructures in government and educational facilities retain installed base advantages through sunk capital and maintenance staff familiarity.
Strategic Opportunities
- Smart building retrofit mandates in Germany:Federal funding streams for energy-efficient building automation create procurement windows where access control upgrades piggyback on HVAC and lighting system replacements.
- Biometric-facial recognition convergence:3D structured light modules originally developed for smartphone authentication are migrating into high-assurance cylinder form factors for data center and pharmaceutical cleanroom applications.
- Insurance premium incentives:Commercial property underwriters in France are introducing documented access logging requirements that favor electronic credential systems with tamper-evident audit trails.
Industry Challenges
- Cyber-physical security skill scarcity:Installation contractors lack cross-training in both mechanical lock servicing and network security hardening, forcing manufacturers to absorb field support costs.
- Multi-protocol firmware maintenance:Product lines supporting simultaneous Bluetooth, Z-Wave, and Zigbee stacks require ongoing vulnerability patching across divergent certification regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Cylinder Lock Credentials Market |
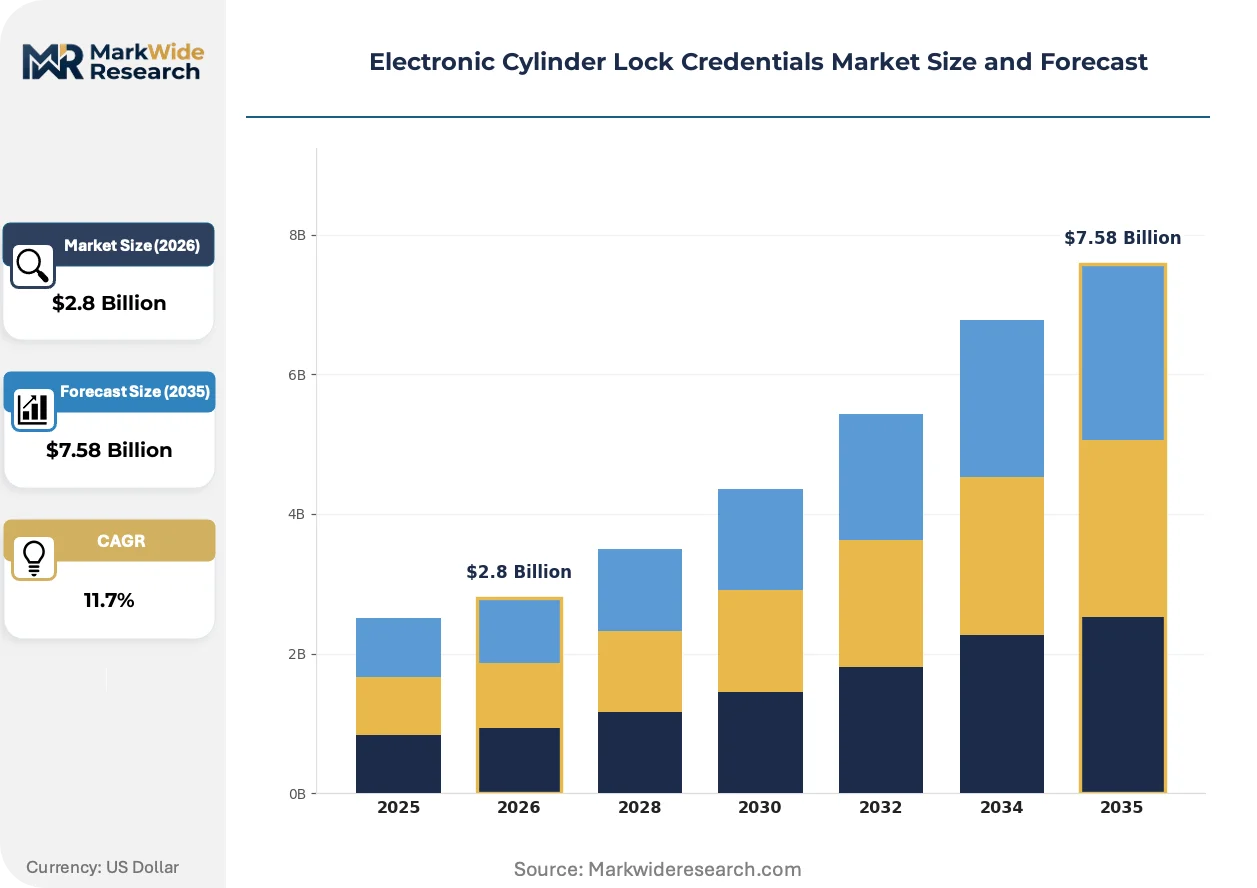
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Locks, Keypads, Biometric Locks, RFID Locks Technology: Wireless, Bluetooth, Z-Wave, Zigbee Application: Residential, Commercial, Industrial, Institutional End User: Homeowners, Property Managers, Businesses, Government |
| Companies Covered | ASSA ABLOY, SALTO Systems, iLOQ Limited, SimonsVoss Technologies GmbH, Dormakaba Holding AG, Allegion plc, AIT Ltd., WFE Technology Corp., Ed. Schulte GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Cylinder Lock Credentials Market Emerging Trajectories
Credential authentication architectures are fragmenting across hardware-based secure elements, cloud-hosted encryption services, and edge biometric processing. This diversification is compressing product lifecycle expectations and forcing lock manufacturers to maintain parallel development tracks.
Near-field communication credential storage is hybridizing with offline biometric template matching in cylinder modules destined for healthcare and critical infrastructure sites. Siemens Healthineers and similar operators are piloting these dual-factor configurations in German hospital pharmacies where network outages cannot disable access. The hybridizing architecture reduces dependency on live server connectivity while preserving audit trail completeness.
France's CNIL has issued binding guidance on biometric data retention limits for access control systems, requiring facial templates to reside solely on-device with no cloud backup permitted. Hardware manufacturers must redesign firmware architectures to enforce this locality constraint without sacrificing multi-door synchronization. Healthcare and financial services verticals in France are absorbing the highest compliance engineering costs.
Facility managers are unbundling hardware procurement from credential lifecycle management, contracting access rights administration to specialized software vendors. This separation shifts margin capture toward recurring SaaS fees and compresses upfront equipment pricing. German commercial real estate investment trusts are pioneering this disaggregation model across their multi-tenant office portfolios.
Electronic Cylinder Lock Credentials Market Segmentation
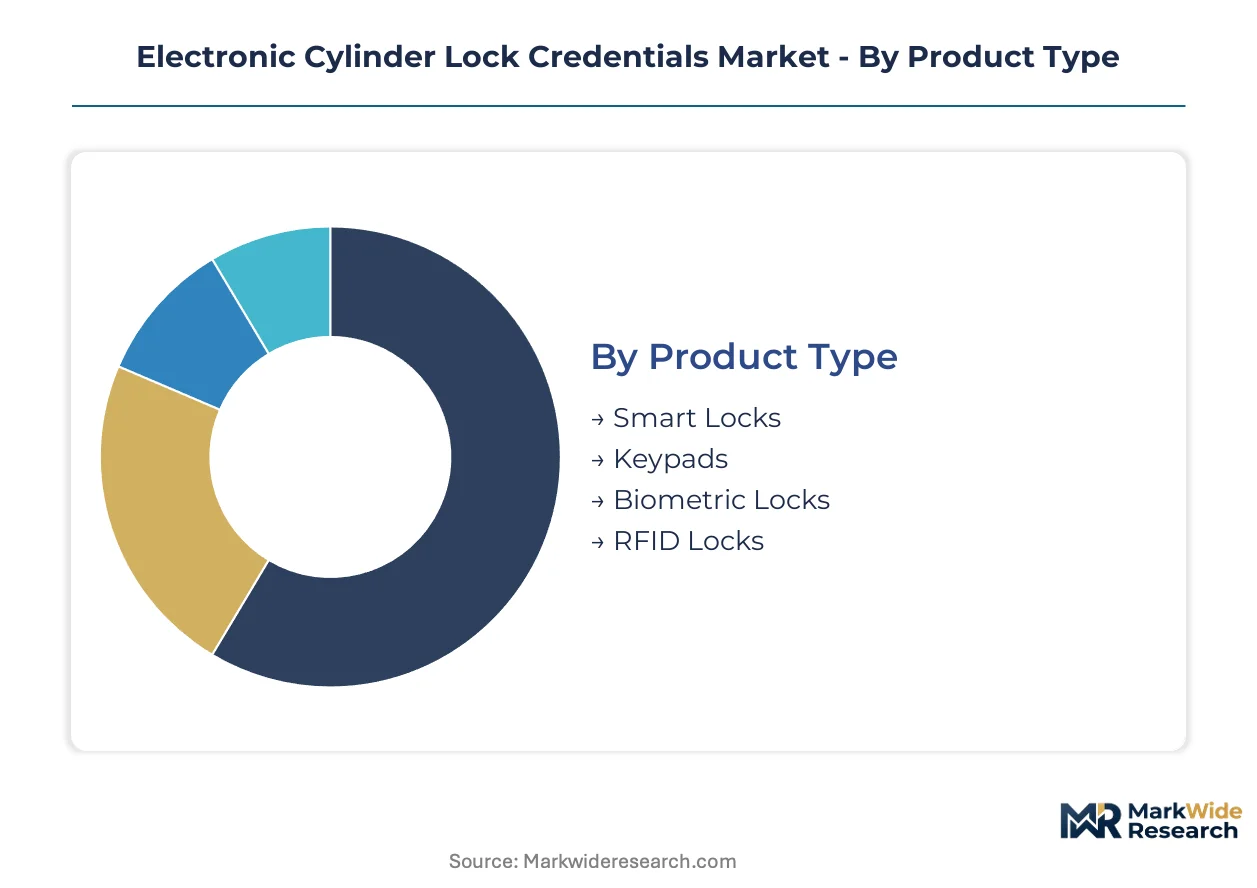
Electronic cylinder lock credentials fragment across four intersecting dimensions that determine procurement priorities and margin capture. Product type and technology choices lock in hardware BOM costs and firmware maintenance burdens, while application and end-user segments dictate compliance requirements and installation complexity.
Product Type:
Use-case spectrum spans from consumer convenience through high-assurance perimeter control, with each form factor optimizing for distinct threat models and operational workflows.
- Smart Locks:Battery-powered electromechanical cylinders with Wi-Fi or cellular backhaul enable remote credential provisioning and real-time entry logging. Property managers across Germany and France are consolidating multi-unit portfolios under single-platform mobile credential systems to eliminate rekeying costs during tenant turnover.
- Biometric Locks:On-device fingerprint or facial template matching eliminates credential loss risks and supports non-repudiable audit trails. Demand concentrates in French healthcare and pharmaceutical cleanrooms where CNIL mandates prohibit cloud storage of biometric data, forcing edge-only processing architectures.
- Keypads:PIN-entry cylinders with tamper-evident logging serve cost-sensitive commercial retrofits where smartphone penetration among users remains uneven.
- RFID Locks:Proximity card and fob systems dominate legacy institutional deployments with established credential issuance workflows and sunk infrastructure.
The dominant share belongs to smart locks, while biometric locks are closing the gap fastest.
Technology:
Cost tier stratification separates premium wireless stacks from commoditized protocols, with module pricing and certification burden determining competitive positioning.
- Bluetooth:Low Energy transceiver modules have compressed hardware BOMs to parity with legacy RFID, enabling mid-market manufacturers to match premium wireless feature sets. Volume shipments concentrate in residential and light commercial retrofits where smartphone-native credential storage eliminates dedicated reader hardware.
- Wireless:Proprietary RF protocols and Power-over-Ethernet implementations serve hardwired commercial installations demanding guaranteed latency and centralized firmware management.
- Z-Wave:Sub-GHz mesh networking clusters in integrated smart home and commercial automation ecosystems where protocol standardization reduces deployment friction across multi-vendor installations.
- Zigbee:IEEE 802.15.4-based stacks dominate building automation convergence projects requiring interoperability with HVAC and lighting control networks under unified management platforms.
Bluetooth commands the largest installed base, though Z-Wave is expanding most quickly in converged automation deployments.
Application:
Volume concentration sits with residential retrofits, while margin pools concentrate in institutional contracts with extended certification requirements.
- Residential:Single-family and multi-unit housing drives unit volume through direct-to-consumer channels and property manager bulk procurement. German federal funding streams for energy-efficient building automation create procurement windows where access control upgrades piggyback on HVAC and lighting replacements.
- Commercial:Office, retail, and hospitality verticals demand flexible credential lifecycle management with SaaS-based administration platforms. French commercial property underwriters are introducing documented access logging requirements that favor electronic credential systems with tamper-evident audit trails.
- Industrial:Manufacturing and logistics facilities prioritize ruggedized hardware with offline operation capability during network outages.
- Institutional:Government, education, and healthcare sites impose EN 50133 alarm system integration mandates that extend engineering validation timelines and lock out uncertified suppliers.
Residential applications retain the dominant share, while institutional deployments are gaining share fastest on compliance-driven replacement cycles.
End User:
Customer type determines procurement authority structure and total cost of ownership calculation methodology.
- Property Managers:Multi-unit housing operators consolidate access control under single-platform systems to streamline tenant turnover workflows and reduce physical key management overhead.
- Businesses:Corporate facilities teams prioritize integration with existing identity management directories and visitor management platforms.
- Homeowners:Direct purchasers emphasize smartphone-native installation and DIY configuration to avoid contractor fees.
- Government:Public sector procurement pools mandate third-party cybersecurity certification under EU Cybersecurity Act pathways, creating order backlog visibility for pre-qualified suppliers.
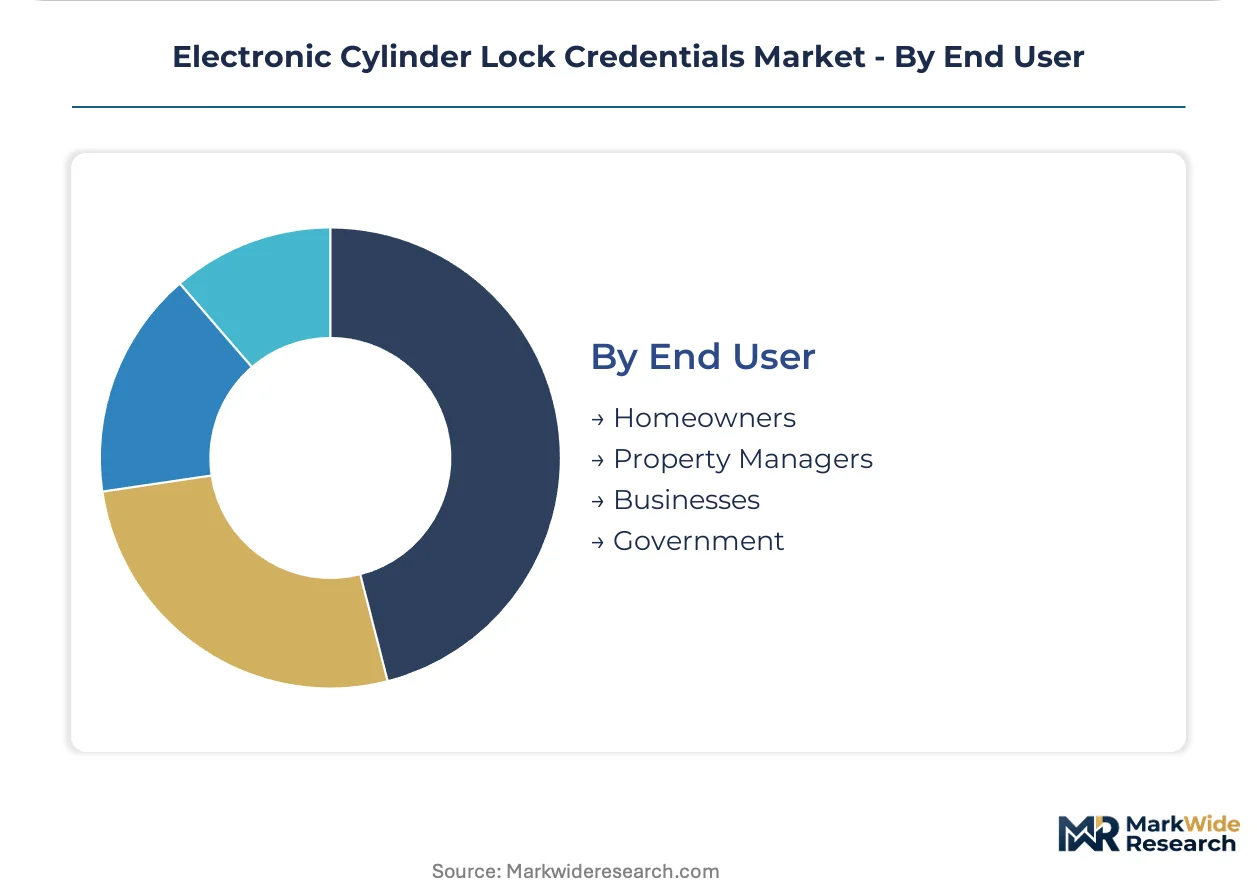
Property managers represent the largest addressable segment, while government buyers are climbing the fastest on mandated security upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main corridor's high-speed rail interconnects Frankfurt's financial district with Stuttgart's precision engineering belt, anchoring Germany's dominance in smart building retrofit procurement.
Germany
Federal funding streams for energy-efficient building automation are accelerating access control upgrades in multi-unit housing across Bavaria and Baden-Württemberg. The KBA enforces strict data governance protocols for connected locking devices through divergent interpretations of credential storage standards. Precision engineering clusters around Stuttgart and Munich are narrowing the competitive gap in electronic cylinder lock manufacturing through advanced electromechanical integration.
France
Commercial property underwriters in Paris and Lyon are introducing documented access logging requirements that favor tamper-evident electronic credential systems. CNIL binding guidance mandates facial templates reside solely on-device with no cloud backup permitted for healthcare and financial services verticals. The Île-de-France region hosts concentrated demand from hospital pharmacies piloting hybrid NFC-offline biometric configurations.
United States
Property managers across Texas and Florida are expanding deployment of mobile credential systems for multi-unit housing to streamline tenant turnover workflows. FCC certification requirements for wireless locking devices create order backlog visibility for pre-qualified suppliers in institutional procurement pools. The Southeast corridor's rapid residential development is absorbing mid-market Bluetooth-enabled cylinder volumes.
United Kingdom
Corporate facilities teams in London and Manchester prioritize integration with existing identity management directories and visitor management platforms. Post-Brexit regulatory divergence from EN 50133 standards is extending engineering validation timelines for connected locks sold into commercial buildings. The Midlands manufacturing belt is developing modular cylinder architectures that simplify retrofit installation across aging building stock.
China
Manufacturing and logistics facilities in the Yangtze River Delta prioritize ruggedized hardware with offline operation capability during network outages. MIIT standards for IoT device cybersecurity are tightening certification requirements for connected locking devices in smart building deployments. Shenzhen's electronics ecosystem is compressing Bluetooth Low Energy module costs to parity with legacy RFID systems.
Electronic Cylinder Lock Credentials Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying electromechanical modules and wireless transceiver stacks. The vendor base stratifies across three tiers: vertically integrated European conglomerates with captive testing facilities, mid-scale wireless credential platform developers, and regional mechanical lock converters adding electronic actuation. Consolidation pressure concentrates among manufacturers with modular hardware architectures that compress EN 50133 certification timelines. Dominant competitive moves include backward integration into semiconductor sourcing and strategic partnerships with property management software platforms.
Within the integrated systems tier, ASSA ABLOY and Dormakaba Holding AG exemplify archetypes of scale-driven platform consolidation. SALTO Systems occupies a specialized position representing wireless credential platform developers focused on hospitality and education verticals. These three anchors illustrate the competitive tension between breadth of product portfolio and depth of vertical specialization.
| Leading Market Players |
|---|
| ASSA ABLOY |
| SALTO Systems |
| iLOQ Limited |
| SimonsVoss Technologies GmbH |
| Dormakaba Holding AG |
| Allegion plc |
| AIT Ltd. |
| WFE Technology Corp. |
| Ed. Schulte GmbH |
| Others |
Supply Flow & Price Mechanics
Shenzhen's electronics ecosystem compresses Bluetooth Low Energy module costs to parity with legacy RFID systems, transferring pricing power downstream to European cylinder assemblers who can now match premium wireless feature sets at mid-market price points. This cost convergence accelerates hardware commoditization while shifting margin capture toward credential lifecycle management services.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EN 50133-certified institutional cylinders from commercial retrofit units and consumer-grade smart locks. Price differentiation hinges on certification grade and after-sales service bundling, with SaaS-based credential administration commanding recurring fees that hardware-only transactions cannot match. Cost compression in the standard tier intensifies because semiconductor pricing for wireless transceivers has collapsed, forcing manufacturers to absorb field support costs or cede share. Property managers exhibit highest price sensitivity, while government procurement pools prioritize cybersecurity certification over unit economics.
Supply Chain Analysis
Tariff exposure between East Asian manufacturing zones and European assembly plants dominates supply chain risk planning for cylinder lock producers. Lithium primary battery production clusters in China, South Korea, and Japan, leaving European assemblers exposed to freight cost volatility and customs processing delays. Electromechanical actuators, secure element chips, and BLE transceiver modules constitute critical component dependencies. Distribution runs through specialist security distributors and direct-to-installer channels, with property management software platforms emerging as an alternative route-to-market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring SaaS fees for credential lifecycle management expand faster than hardware shipments, rewarding manufacturers who unbundle equipment procurement from access rights administration.
For Market Incumbents: Insulate installed base positions by deepening backward integration into semiconductor sourcing and securing captive testing facilities that compress EN 50133 certification timelines. Modular hardware architectures defend against emerging mid-market competitors who match wireless feature sets at lower price points. Certification investment represents the critical lever for locking out uncertified rivals from institutional procurement pools. For New Entrants and Emerging Players: Pursue white-space targets in German multi-unit housing retrofits where federal funding streams for energy-efficient building automation create procurement windows piggybacking HVAC and lighting replacements. The most penetrable segment sits with property managers consolidating access control under single-platform mobile credential systems. A software-first go-to-market angle, partnering with established property management platforms, bypasses hardware certification barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wireless credential platform developers with established hospitality and education verticals, offering superior cash flow quality over hardware-centric assemblers. Long-term viability across the next decade favors manufacturers with modular architectures and captive certification capabilities. The signal to watch is consolidation pressure among mid-scale wireless credential specialists unable to absorb multi-protocol firmware maintenance burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive supply of BLE modules and secure elements insulates margins from East Asian freight volatility. |
| EN 50133 Certification Investment | Pre-qualified status locks out competitors from French and German institutional procurement pools. |
| Property Management Software Partnership | Distribution through SaaS platforms shifts margin capture toward recurring credential administration fees. |
| Modular Cylinder Architecture Development | Simplified retrofit installation accelerates penetration of aging European commercial building stock. |
| Biometric-Facial Recognition Convergence | 3D structured light modules from smartphone supply chains enable high-assurance healthcare and data center applications. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and hyperscaler IoT deployment disclosures. Primary interviews engaged lock manufacturer product managers, property management software platform executives, commercial security installers, and facility managers at German multi-unit housing operators. Secondary validation drew from KBA and CNIL guidance documents, EU Cybersecurity Act certification databases, and SEC filings of publicly traded access control conglomerates. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Forecast inputs span product type, technology protocol, application vertical, and end-user archetype across the analysis window. Segmentation modeling captures smart lock, biometric lock, keypad, and RFID form factors intersecting with Bluetooth, Z-Wave, Zigbee, and proprietary wireless stacks. CAGRs derive from installation base growth rates, replacement cycle assumptions, and retrofit penetration curves calibrated to German federal funding program uptake. Industry-specific inputs include EN 50133 certification timeline data and BLE module cost curve trajectories.
Sensitivities concentrate around EU AI Act provisions extending to biometric lock algorithms and lithium battery supply disruptions. Forecasts reflect assumptions about certification pathway stability and wireless protocol standardization momentum. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
RFID Locks Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Port Security Systems Market
Access Control Systems
China Access Control Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market