
 Physical Security Equipment Market | 2026-2036
Physical Security Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Security Equipment Market Outlook
Shortages of certified cybersecurity technicians is redrawing how integrators staff large-scale deployments. Honeywell International Inc. leverages its building automation heritage to bundle climate and security controls for commercial real estate clients. Johnson Controls International Plc anchors its position through deep vertical expertise in healthcare and education facilities. Hangzhou Hikvision Digital Technology Co., Ltd. competes aggressively on manufacturing scale, sustaining cost advantages in camera and video management system production.
Physical security equipment encompasses electromechanical and electronic systems designed to detect intrusion, control access, verify identity, and monitor environments through sensors, cameras, readers, and barriers operating across wired and wireless networks. These systems integrate with IT infrastructure to provide real-time alerting, forensic recording, and automated response coordination for asset protection and personnel safety. Surveillance cameras dominates hardware volumes but faces margin compression as commoditization spreads across basic IP camera models. Access control systems, particularly biometric-enabled and mobile credential platforms, captures expanding margin pools as enterprises replace card-based systems. Cloud-based solutions in video analytics and remote management is the fastest-expanding technology dimension, displacing on-premise server architectures in mid-market deployments.
FDA facility security guidelines, FCC equipment authorization rules for wireless sensors, and EU GDPR video surveillance constraints collectively shape product design, data handling protocols, and market access requirements across major economies. The EU AI Act introduces additional compliance layers for facial recognition and behavioral analytics systems, forcing vendors to reengineer software architectures for European deployments. Stakeholders must weigh cybersecurity certification investments against regional market entry timelines as regulatory fragmentation between North American and European frameworks intensifies.
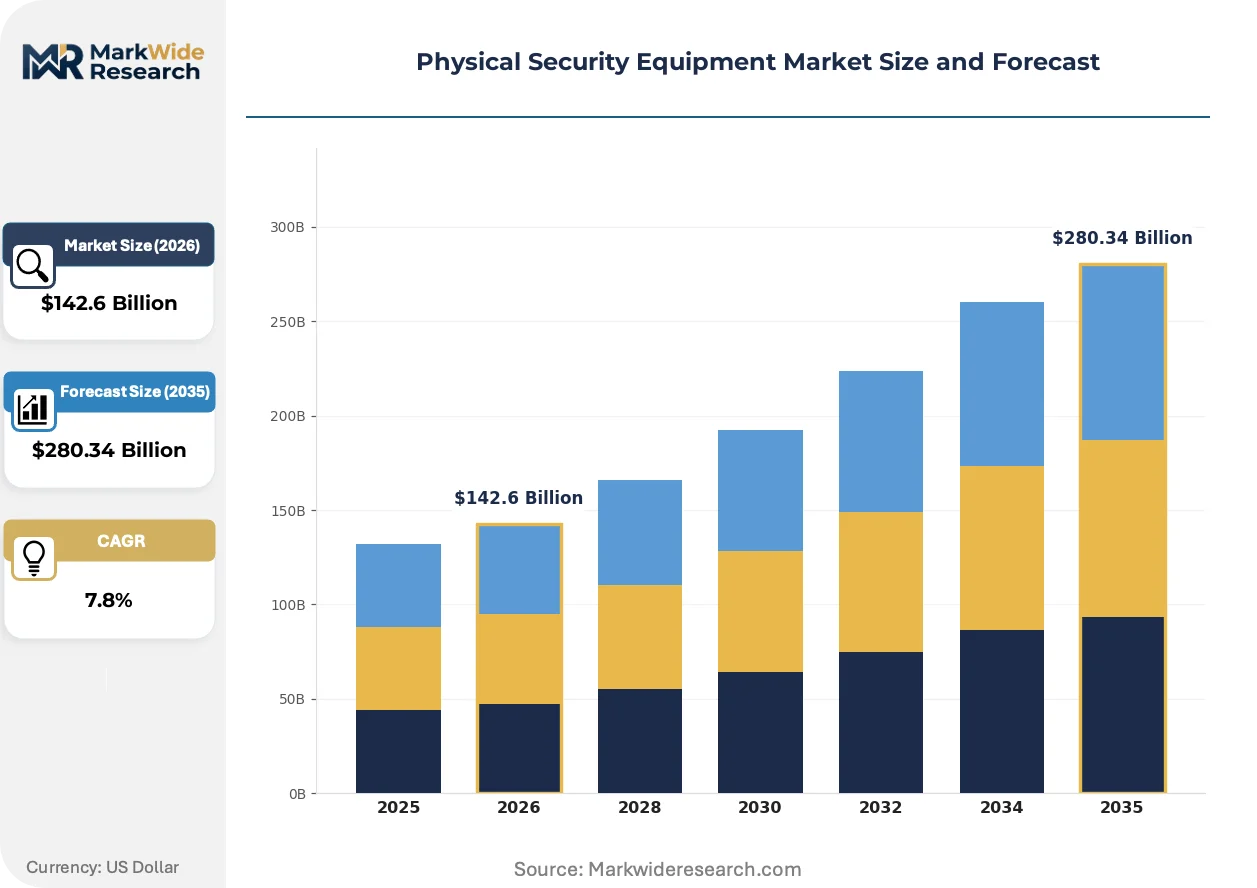
Market Dynamics
Critical infrastructure operators are consolidating standalone security systems into unified command platforms, forcing vendors to reengineer product architectures for interoperability rather than proprietary lock-in. This integration imperative is compressing margins for hardware specialists while expanding service revenue pools for software-fluent integrators.
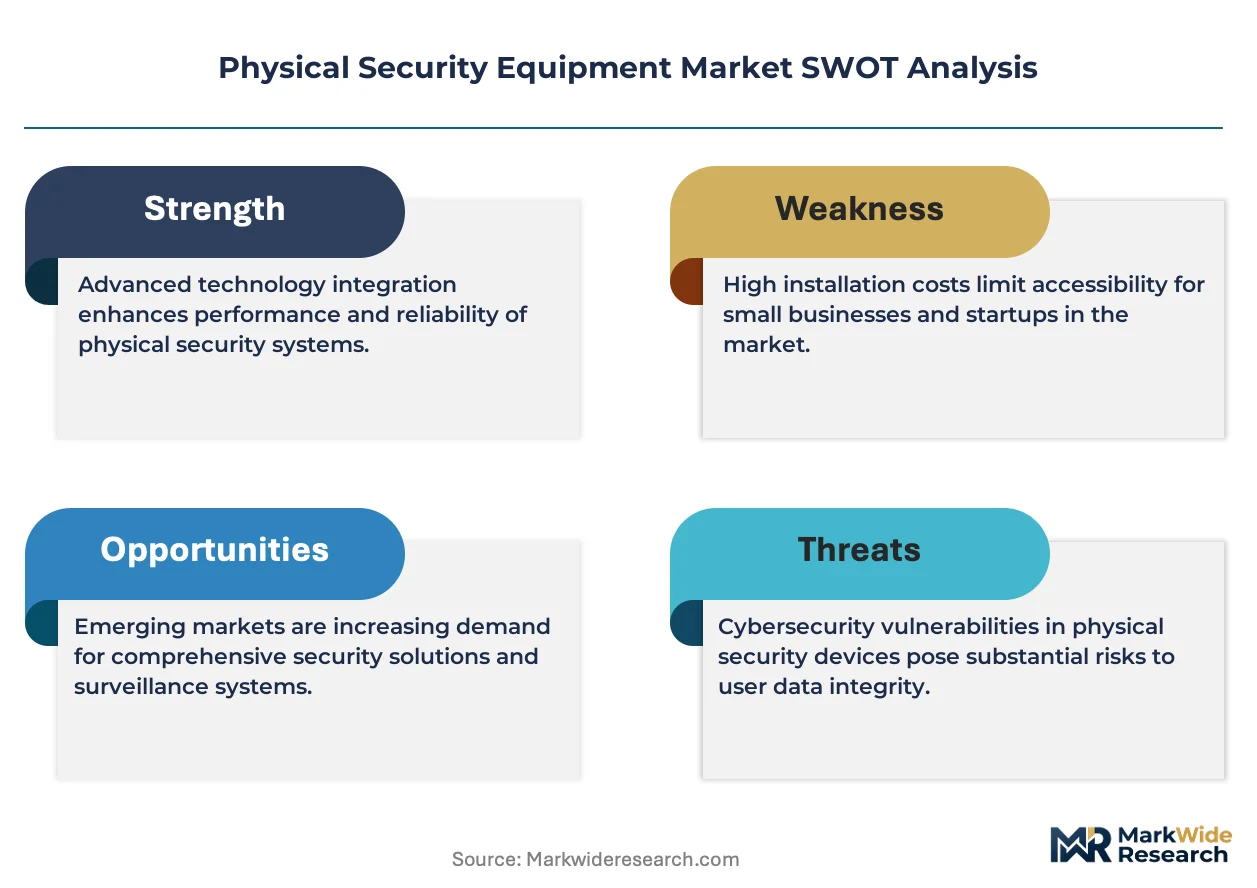
Growth Catalysts
- EU AI Act compliance mandates:European facilities must replace legacy facial recognition systems with auditable algorithms, accelerating replacement cycles for video analytics hardware.
- Data center construction booms:Hyperscale cloud operators in the United States and Germany are specifying biometric access control and perimeter intrusion detection for new facilities.
- Smart city infrastructure budgets:Municipal governments in China are deploying integrated surveillance and traffic management systems as core urban planning components.
Market Restraints
- Semiconductor supply concentration:Image sensor and edge processing chip fabrication concentrates in Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- GDPR data localization costs:European video surveillance operators face mandatory on-premise storage requirements that inflate infrastructure expenditure versus cloud alternatives.
- Cybersecurity skill scarcity:Shortages of technicians holding IEC 62443 certification delay deployment timelines and inflate labor costs for integrated systems.
Strategic Opportunities
- India critical infrastructure modernization:Airport and metro expansion projects under the PLI scheme create demand for baggage screening and passenger authentication systems.
- Healthcare facility security mandates:Joint Commission accreditation requirements in the United States are driving behavioral analytics adoption for patient wandering and violence detection.
- Mobile credential convergence:Integration of access control with smartphone wallets and digital identity frameworks opens new subscription revenue models for platform vendors.
Industry Challenges
- Interoperability certification bottlenecks:ONVIF and OSDP compliance testing backlogs delay product launches and fragment ecosystem compatibility.
- Legacy analog infrastructure stranding:Enterprises with coaxial cable plant face rip-and-replace costs that stall IP migration timelines despite cybersecurity vulnerabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Security Equipment Market |
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $280.34 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alarm Systems, Access Control, Surveillance Cameras, Barriers Technology: Biometrics, Video Analytics, RFID, Cloud-Based Solutions End User: Government, Healthcare, Retail, Education Installation: On-Site Installation, Remote Configuration, Retrofit, Integrated Systems |
| Companies Covered | Honeywell International Inc., Johnson Controls International Plc, Hangzhou Hikvision Digital Technology Co., Ltd., Bosch Security Systems, Axis Communications AB, Zhejiang Dahua Technology Co., Ltd., ADT LLC, Cisco Systems Inc., Genetec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Security Equipment Market Strategic Shifts
Edge computing architectures are redistributing processing load from centralized servers to camera and sensor hardware, enabling real-time response without network dependency. This shift is compressing system latency while complicating firmware update and security patch management workflows.
Multi-spectral imaging sensors are miniaturizing thermal and low-light capabilities into standard dome camera form factors. Critical infrastructure operators in energy and transportation are specifying these unified devices to reduce mounting hardware and cabling complexity. The technology is miniaturizing what previously required separate camera deployments, collapsing installation labor and maintenance contract values.
The EU AI Act introduces mandatory conformity assessments for biometric identification systems before market placement. Vendors must document algorithm training data provenance and accuracy benchmarking across demographic groups, extending product development cycles by twelve to eighteen months. European deployments of facial recognition in public spaces face the strictest compliance burden, pushing investment toward behavioral analytics that avoid direct identity matching.
Enterprise buyers are unbundling hardware procurement from installation and managed services, issuing separate RFPs for each layer. Systems integrators respond by certifying technicians across multiple vendor platforms rather than maintaining exclusive partnerships. This fragmentation is most visible in United States commercial real estate, where property managers prioritize interoperability over single-source accountability to preserve future upgrade flexibility.
Physical Security Equipment Market Segmentation
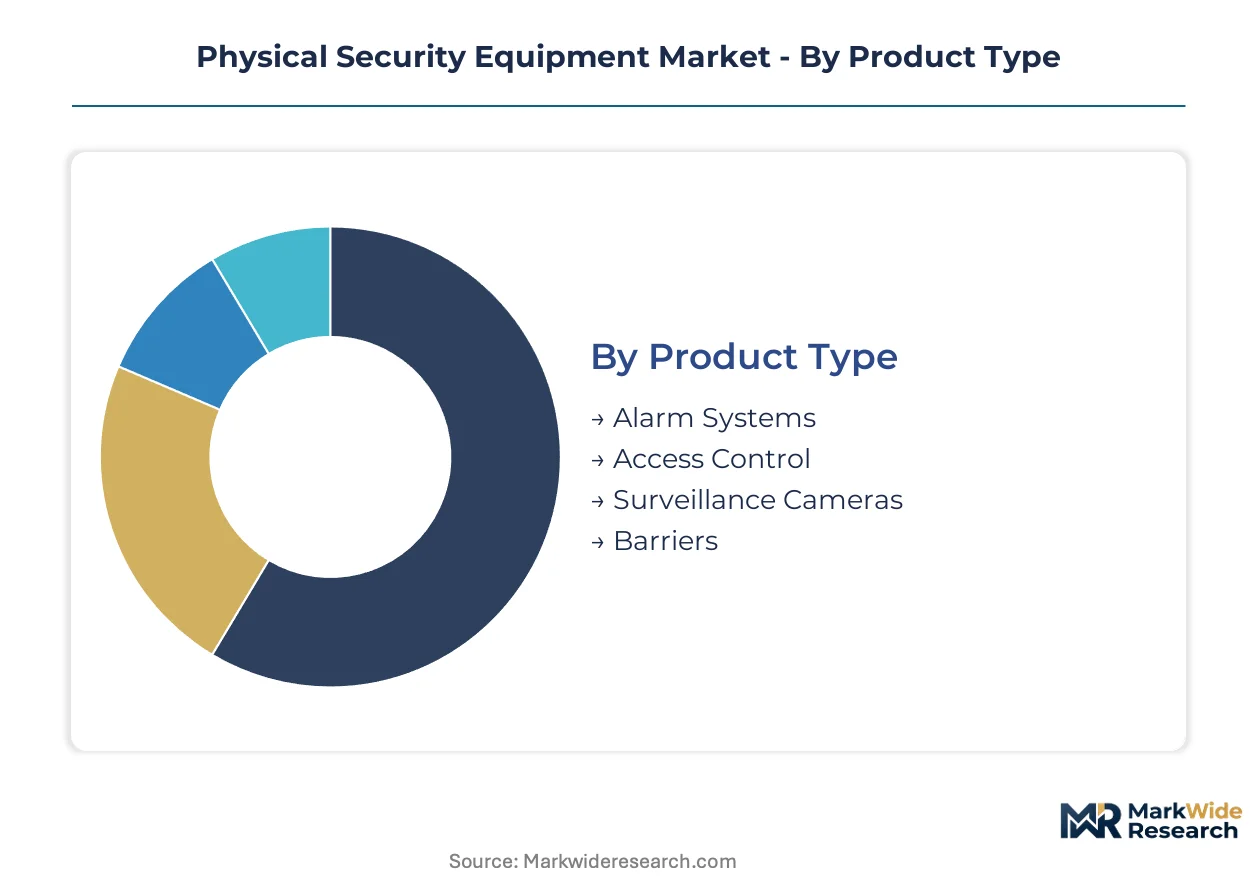
Equipment segmentation in physical security reflects divergent compliance burdens across biometric, video, and access technologies. Vendors configure product lines to match regulatory intensity rather than pure functional performance.
Product Type:
FDA facility security guidelines and FCC equipment authorization rules create divergent certification pathways for electromechanical versus electronic systems.
- Surveillance Cameras:IP camera assemblies with edge processing chips and multi-spectral imaging capabilities now dominate hardware volumes. Data center operators in Germany and hyperscale cloud facilities in the United States specify these for perimeter coverage, though margin compression spreads across basic models as commoditization accelerates.
- Access Control:Biometric-enabled and mobile credential platforms capture expanding margin pools as enterprises replace card-based systems. Healthcare facilities under Joint Commission pressure and European sites facing GDPR video surveillance constraints drive specification of these systems for identity verification without centralized biometric storage.
- Alarm Systems:Sensor networks with wireless connectivity and centralized monitoring interfaces serve residential and small commercial installations where FCC authorization compliance adds cost but enables rapid deployment.
- Barriers:Physical turnstiles, bollards, and gate assemblies integrate with access control electronics for layered perimeter defense at critical infrastructure sites.
Surveillance cameras handles the majority of throughput; access control is the fastest mover on share.
Technology:
Cost tier differentiation separates enterprise-grade certified platforms from mid-market alternatives.
- Cloud-Based Solutions:Video analytics and remote management platforms displace on-premise server architectures in mid-market deployments. European operators face mandatory on-premise storage under GDPR data localization requirements that inflate infrastructure expenditure versus cloud alternatives available to United States buyers.
- Biometrics:Facial recognition and fingerprint systems face mandatory conformity assessments under the EU AI Act before market placement. Vendors must document algorithm training data provenance and accuracy benchmarking across demographic groups, extending product development cycles substantially.
- Video Analytics:Behavioral analysis software avoids direct identity matching to evade strictest European compliance burdens while delivering intrusion detection and crowd monitoring capabilities.
- RFID:Card and tag-based identification systems persist in legacy installations where rip-and-replace costs stall migration to biometric alternatives despite cybersecurity vulnerabilities.
Cloud-based solutions delivers the steepest expansion trajectory; biometrics carries the heaviest compliance overhead.
End User:
Application-specific mandates reshape procurement priorities across facility types.
- Government:Critical infrastructure operators consolidate standalone systems into unified command platforms, forcing interoperability over proprietary lock-in. Airport and metro expansion projects under India's PLI scheme create concentrated demand for baggage screening and passenger authentication.
- Healthcare:Joint Commission accreditation requirements in the United States drive behavioral analytics adoption for patient wandering and violence detection. FDA facility security guidelines shape product design for pharmaceutical manufacturing sites.
- Retail:Loss prevention and occupancy analytics deploy across store networks with varying tolerance for cloud dependency based on regional data handling protocols.
- Education:K-12 and university campuses balance access control against emergency egress requirements, with funding cycles tied to municipal budget approvals.
Government absorbs the largest absolute spend; healthcare is climbing the fastest on compliance-driven replacement.
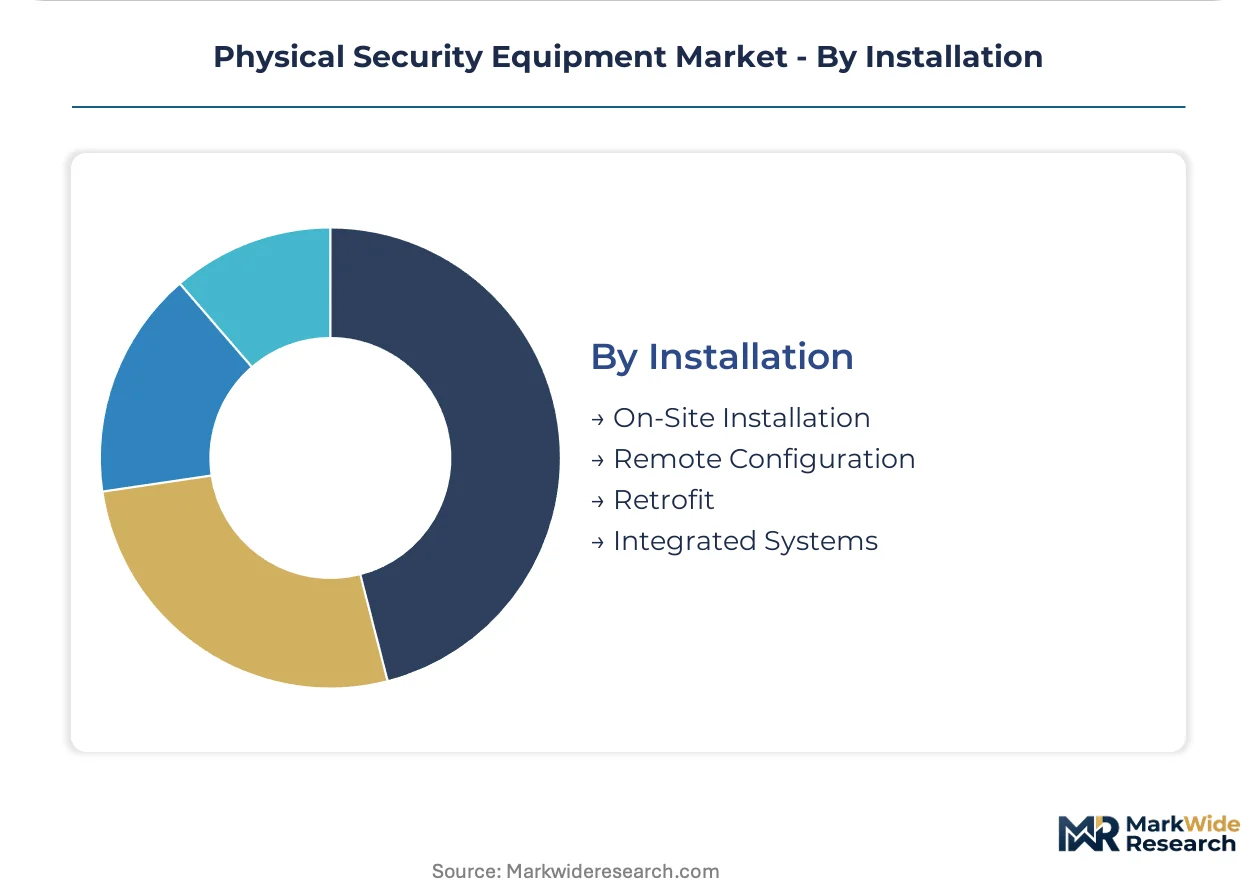
Installation:
Customer type separates enterprise self-managed deployments from integrator-dependent implementations.
- Integrated Systems:Unified command platforms combining surveillance, access, and alarm functions require IEC 62443 certified technicians whose scarcity delays deployment timelines and inflates labor costs. Enterprise buyers unbundle hardware procurement from installation services to preserve upgrade flexibility.
- Retrofit:Coaxial cable plant in aging facilities faces rip-and-replace costs that stall IP migration despite known cybersecurity vulnerabilities in analog infrastructure.
- On-Site Installation:Traditional technician-deployed systems dominate high-security environments where physical tampering risks preclude remote configuration.
- Remote Configuration:Cloud-managed platforms enable centralized parameter adjustment and firmware updates, complicating security patch management workflows but reducing truck-roll expenses.
Integrated systems commands the premium tier; remote configuration is gaining share fastest among mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Physical security equipment consumption patterns diverge sharply across geographies. United States buyers prioritize cloud-managed platforms and biometric integration for data center and commercial real estate applications. European procurement emphasizes GDPR-compliant architectures and EU AI Act conformity assessments. Chinese deployment concentrates on smart city surveillance and traffic management integration.
United States
Hyperscale cloud operators and data center developers drive demand for biometric access control and perimeter intrusion detection systems. FCC equipment authorization rules govern wireless sensor deployments across critical infrastructure sites. Northern Virginia's data center corridor and Dallas-Fort Worth metroplex anchor concentrated procurement of integrated surveillance platforms.
Germany
Industrial facilities and logistics hubs specify multi-spectral imaging and edge-computing cameras for perimeter monitoring. EU AI Act mandates force replacement of legacy facial recognition with auditable algorithms. The Rhine-Ruhr industrial belt and Frankfurt data center cluster absorb premium-tier access control and video analytics systems.
China
Municipal governments deploy integrated surveillance and traffic management as core urban planning infrastructure. GB standards and MIIT regulations shape product certification for domestic and export markets. The Yangtze River Delta and Pearl River Delta megacity clusters concentrate manufacturing and deployment of camera and video management systems.
India
Airport and metro expansion under the PLI scheme creates demand for baggage screening and passenger authentication equipment. BIS certification requirements and CEA facility security guidelines reshape procurement specifications. Delhi-Mumbai Industrial Corridor and Bangalore's tech park developments drive adoption of cloud-based remote management platforms.
United Kingdom
Commercial real estate and education facilities balance access control against emergency egress requirements. GDPR video surveillance constraints and national critical infrastructure protection standards influence system design. London's financial district and Manchester's commercial property market prioritize interoperability-certified integrated command platforms.
Physical Security Equipment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the physical security equipment market. The upper tier comprises diversified industrial conglomerates with building automation heritage and deep vertical expertise. The specialist tier fragments across camera manufacturers, access control pure-plays, and software-centric analytics vendors. Three archetypes dominate: scale-driven hardware fabricators, software-fluent platform vendors, and vertically integrated building technology conglomerates. Competitive moves center on interoperability certification investments and unbundled service revenue models that separate hardware from installation and managed services.
Among diversified technology conglomerates, Honeywell International Inc. and Johnson Controls International Plc exemplify the building-automation-anchored archetype, leveraging climate and security control bundling for commercial real estate clients. Hangzhou Hikvision Digital Technology Co., Ltd. occupies a position within the scale-driven manufacturing tier, sustaining cost advantages in camera and video management system production through manufacturing scale. These three entities represent distinct competitive vectors: vertical integration through building systems convergence, horizontal dominance through production scale, and software-centric platform development.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International Plc |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Bosch Security Systems |
| Axis Communications AB |
| Zhejiang Dahua Technology Co., Ltd. |
| ADT LLC |
| Cisco Systems Inc. |
| Genetec Inc. |
| Others |
Value Chain & Pricing Dynamics
Manufacturing scale advantages in Taiwan and South Korea for image sensors and edge processing chips create asymmetric pricing power that propagates through hardware tiers, compressing margins for basic IP camera assemblies while preserving premium tiers for multi-spectral and AI-enabled devices.
Pricing Analysis
Contract structures in physical security equipment favor project-based procurement with multi-year managed service attachments over pure hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62443-certified integrated platforms from FCC-authorized mid-market alternatives and basic commodity cameras. Cost compression in standard-tier IP cameras is intensifying because manufacturing scale from Chinese producers floods distribution channels. Government and critical infrastructure buyers exhibit the least price sensitivity due to compliance mandates, while small commercial and residential segments drive volume through economy-tier wireless alarm systems.
Supply Chain Analysis
Inventory cycles for edge processing chips and multi-spectral sensors currently stretch delivery timelines, forcing integrators to pre-position stock ahead of deployment commitments. Component fabrication concentrates in Taiwan, South Korea, and China, with final assembly distributed across Malaysia, Mexico, and Eastern European facilities. Supply chains draw from specialized inputs including CMOS image sensors, thermal detector arrays, and biometric algorithm licenses. Single-source vulnerability in advanced semiconductor lithography creates exposure to geopolitical disruption. Distribution runs through authorized integrator networks rather than direct OEM sales for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed service and remote monitoring subscriptions expand at multiples of hardware growth, transforming procurement economics toward recurring-revenue relationships that extend customer lifetime value beyond initial installation.
For Market Incumbents: Consolidate interoperability certification investments across ONVIF and OSDP standards to lock in ecosystem positioning against software-centric challengers. Acquire IEC 62443-certified technician networks to defend service revenue pools from independent integrators. Capacity addition in India and Southeast Asia addresses PLI-scheme demand while hedging tariff exposure on Chinese-origin equipment. For New Entrants and Emerging Players: Lead with cloud-native video analytics platforms targeting mid-market commercial real estate in the United States, where unbundled procurement practices favor interoperability over incumbent relationships. India's airport and metro expansion under infrastructure modernization programs offers the most penetrable geography for baggage screening and passenger authentication specialists. Partner with mobile wallet providers to embed access credentials in smartphone-native applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-fluent platform vendors with vertical-specific analytics modules, positioning these archetypes for premium valuations over hardware-centric manufacturers. Long-term viability over a multi-year horizon favors vendors with demonstrated EU AI Act compliance pathways and documented algorithm provenance. Monitor hyperscale cloud operator capital expenditure disclosures as the critical inflection signal for data center security equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | ONVIF and OSDP compliance accelerates product launch timelines and ecosystem integration for multi-vendor deployments. |
| Managed Service Platform Development | Cloud-based remote monitoring subscriptions capture recurring revenue from mid-market buyers unbundling hardware procurement. |
| EU AI Act Compliance Engineering | Documented algorithm training provenance enables market access for biometric systems across European critical infrastructure. |
| Technician Network Acquisition | IEC 62443-certified labor pools defend installation and maintenance revenue from independent systems integrators. |
| Mobile Credential Integration | Smartphone wallet embedding opens subscription revenue models for access control platform vendors. |
Study Parameters
Operator-level perspectives from security systems integrators, critical infrastructure facility managers, and enterprise IT procurement officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization databases, EU AI Act conformity assessment registries, and customs trade data for camera and sensor imports. Bottom-up equipment shipment estimates triangulated against top-down facility construction and upgrade spending patterns across data center, healthcare, and transportation verticals.
Sensitivity analysis tested forecast outputs against alternative scenarios for semiconductor supply disruption, regulatory enforcement intensity, and hyperscale cloud capital expenditure cycles. Segmentation modeling spanned product type, technology architecture, end-user vertical, and installation methodology across regional adoption clusters. CAGRs derived from equipment replacement cycle analysis, greenfield project pipelines, and compliance-driven upgrade mandates. Forecast inputs incorporated edge computing penetration rates, biometric system accuracy benchmarks, and cloud-managed platform adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained data center construction activity, stable geopolitical conditions for Taiwan semiconductor access, or consistent regulatory enforcement timelines would require recalibration. Forecasts reflect documented assumptions about technology substitution rates and procurement pattern evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Global Wearable Security Device Market
Physical Security
Airport Full Body Scanner Market
Physical Security
Active Geofencing Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Europe Physical Security Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Smart Police Helmet Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Tactical Lights Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Border Security Technologies Market
Physical Security
Security Market
Physical Security
Body Armor Plates Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
Tactical Vests Market