
 Electronic Access Control Systems Market | 2026-2036
Electronic Access Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Access Control Systems Market Intelligence
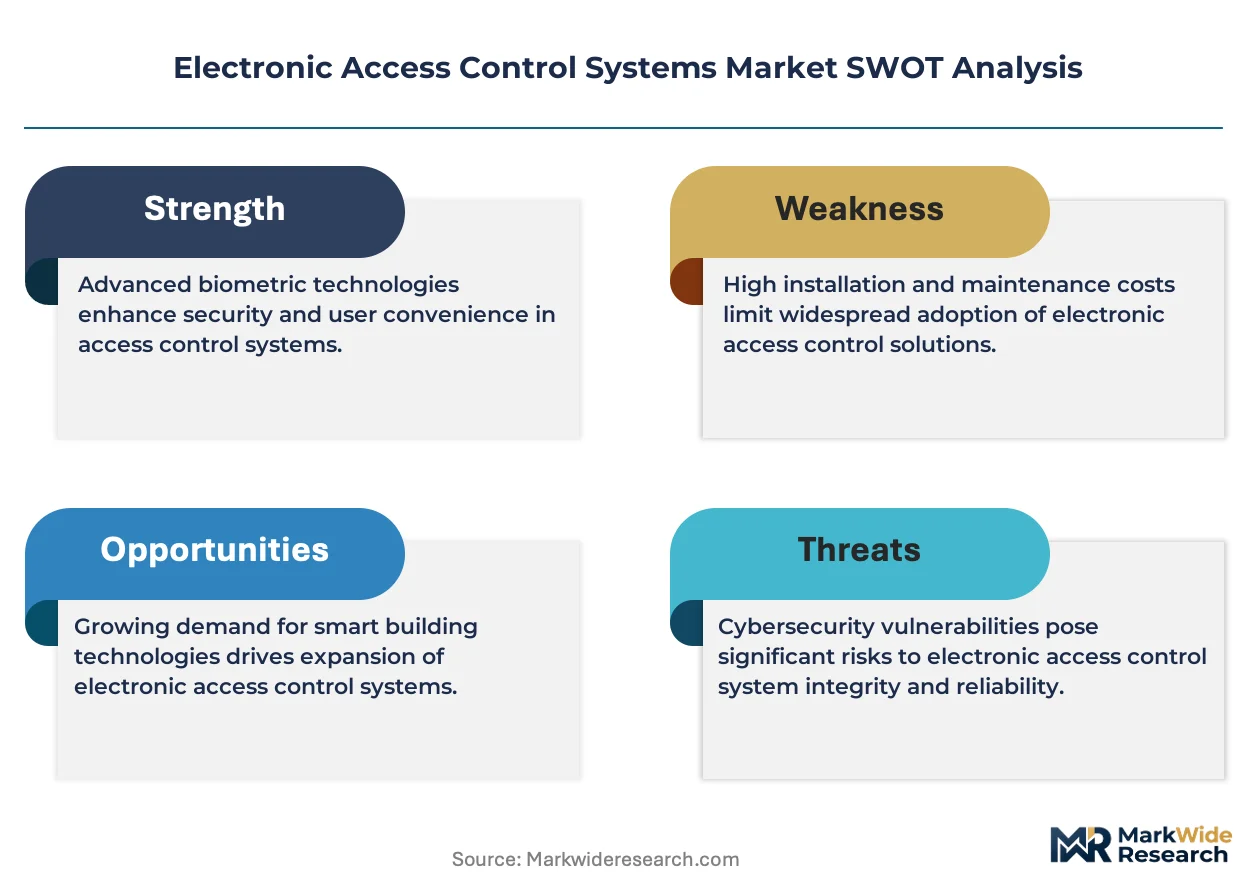
Subscription-based access control leasing is rewriting competitive entry barriers across the electronic security sector. ASSA ABLOY leverages its hardware-to-software integration to sustain recurring revenue streams from enterprise clients. Johnson Controls International plc anchors its position through building-automation convergence, while Honeywell International Inc. differentiates via AI-enhanced threat detection layered into credentialing infrastructure.
Electronic access control systems integrate credential readers, locking mechanisms, and identity management software to authenticate and authorize physical entry, typically operating across 125 kHz low-frequency or 13.56 MHz high-frequency RFID protocols with AES-128 encryption for secure token exchange. Biometric systems and cloud-based technology command expanding margin pools as enterprises shift from on-premise servers to SaaS-delivered identity platforms. Smart cards retain volume leadership in government and healthcare verticals where FIPS 201 compliance mandates standardized credential formats.
The U.S. General Services Administration enforces FICAM guidelines for federal facility access, while the EU Cybersecurity Act mandates CE marking with EN 60839 compliance for intrusion and access systems sold across member states. China's MIIT issues GB standards for IoT security that directly shape product development cycles for manufacturers targeting domestic smart city projects. Stakeholders must weigh regulatory divergence against platform standardization bets as credential interoperability becomes a procurement differentiator.
Market Dynamics
Cloud-native credentialing platforms are compressing hardware refresh cycles while forcing incumbent vendors to restructure revenue models around recurring software subscriptions rather than one-time equipment sales.
Growth Catalysts
- FICAM Compliance Mandates:U.S. federal facilities must deploy standardized PIV credentialing systems, creating locked-in demand for FIPS 201-compliant hardware and identity verification infrastructure.
- Smart Building Retrofit Cycles:Commercial real estate operators in Germany and China are integrating access control with HVAC and lighting automation, pulling cloud-connected readers into multi-year facility upgrade programs.
- Biometric Authentication Maturation:Fingerprint and facial recognition sensors have crossed cost thresholds that enable deployment across mid-market healthcare and education campuses previously limited to card-based systems.
Market Restraints
- Semiconductor Supply Concentration:RFID reader chip fabrication concentrates in Taiwan and South Korea, exposing hardware manufacturers to geopolitical disruption and allocation rationing during demand spikes.
- EN 60839 Certification Burden:European manufacturers face extended testing timelines and documentation requirements for CE marking, delaying product launches by six to eighteen months relative to less regulated markets.
- Mobile Credential Substitution:Smartphone-based digital keys embedded in Apple Wallet and Google Wallet reduce reliance on dedicated physical cards and standalone readers in hospitality and corporate verticals.
Strategic Opportunities
- India Smart City Infrastructure:Municipal surveillance and public building security programs under the Ministry of Housing and Urban Affairs create procurement pipelines for integrated access and video management systems.
- Zero Trust Architecture Convergence:Enterprise IT departments are merging physical and logical access policies, opening integration contracts for vendors that bridge building security with identity governance platforms.
- Subscription Financing Channels:Equipment-as-a-service leasing through facility management firms and security integrators lowers upfront capital barriers for mid-sized commercial tenants.
Industry Challenges
- Cybersecurity Skill Scarcity:Deployment of AES-256 encrypted and TLS-secured endpoints requires field technicians trained in network hardening, a competency pool that remains shallow across installer networks.
- Legacy Wiegand Protocol Interoperability:Brownfield sites with decades-old wiring infrastructure resist full rip-and-replace upgrades, forcing manufacturers to engineer backward-compatible signal converters that add cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Access Control Systems Market |
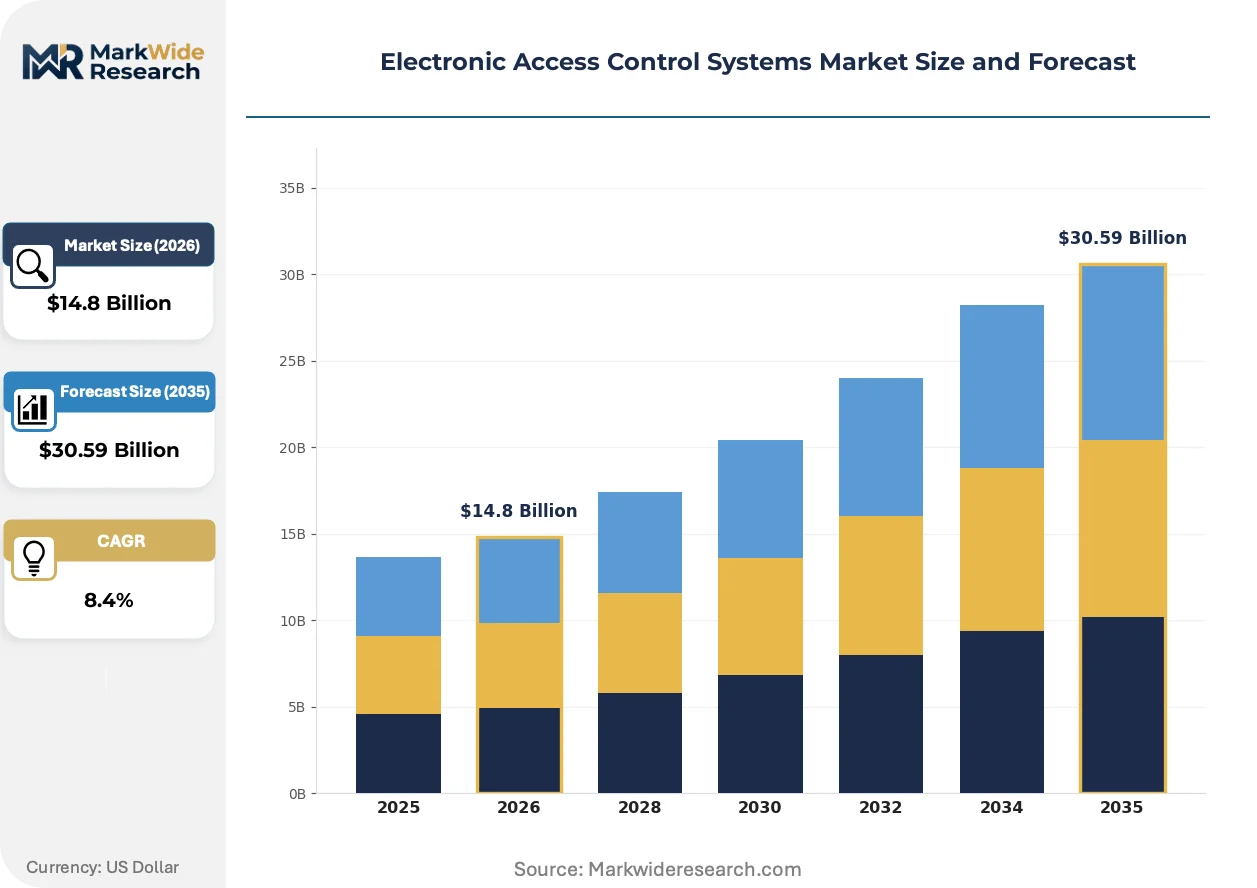
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Smart Cards, Key Fobs, RFID Systems Technology: Wireless, Wired, Cloud-Based, Hybrid End User: Residential, Commercial, Government, Industrial Application: Secure Access, Time Attendance, Visitor Management, Intrusion Detection |
| Companies Covered | ASSA ABLOY, Johnson Controls International plc, Honeywell International Inc., dormakaba Group, Allegion plc, Bosch Security Systems, Axis Communications, Nedap N.V., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Access Control Systems Market Strategic Shifts & Innovations
Artificial intelligence inference at the edge is rewriting how access events are processed, authenticated, and audited across distributed facility networks.
Multi-factor biometric fusion readers combining iris, facial, and vascular pattern recognition are rendering obsolete single-modal fingerprint scanners in high-assurance environments such as data centers and pharmaceutical manufacturing cleanrooms. Financial services and critical infrastructure operators are deploying these systems to eliminate credential sharing and tailgating vulnerabilities. The technology is compressing hardware vendor margins on legacy card readers while opening software licensing revenue from liveness detection algorithms.
The EU Cybersecurity Act's EN 303645 baseline requirements for IoT devices now extend to cloud-connected access control endpoints sold across member states. Manufacturers must submit to third-party conformity assessment bodies and maintain vulnerability disclosure programs. Healthcare and government verticals in France and Germany are prioritizing suppliers with certified security development lifecycles, shifting procurement evaluation weight toward documentation depth rather than feature checklists alone.
Building owners are unbundling security system procurement from general construction contracts, creating direct vendor relationships that bypass traditional mechanical contractor intermediaries. This disintermediation concentrates in Class A office developments in the United States and United Kingdom where facility managers retain specialized technology budgets independent of capital project financing. The pattern favors vendors with dedicated specification sales teams and certified installer training programs over legacy distribution-dependent competitors.
Electronic Access Control Systems Market Segmentation
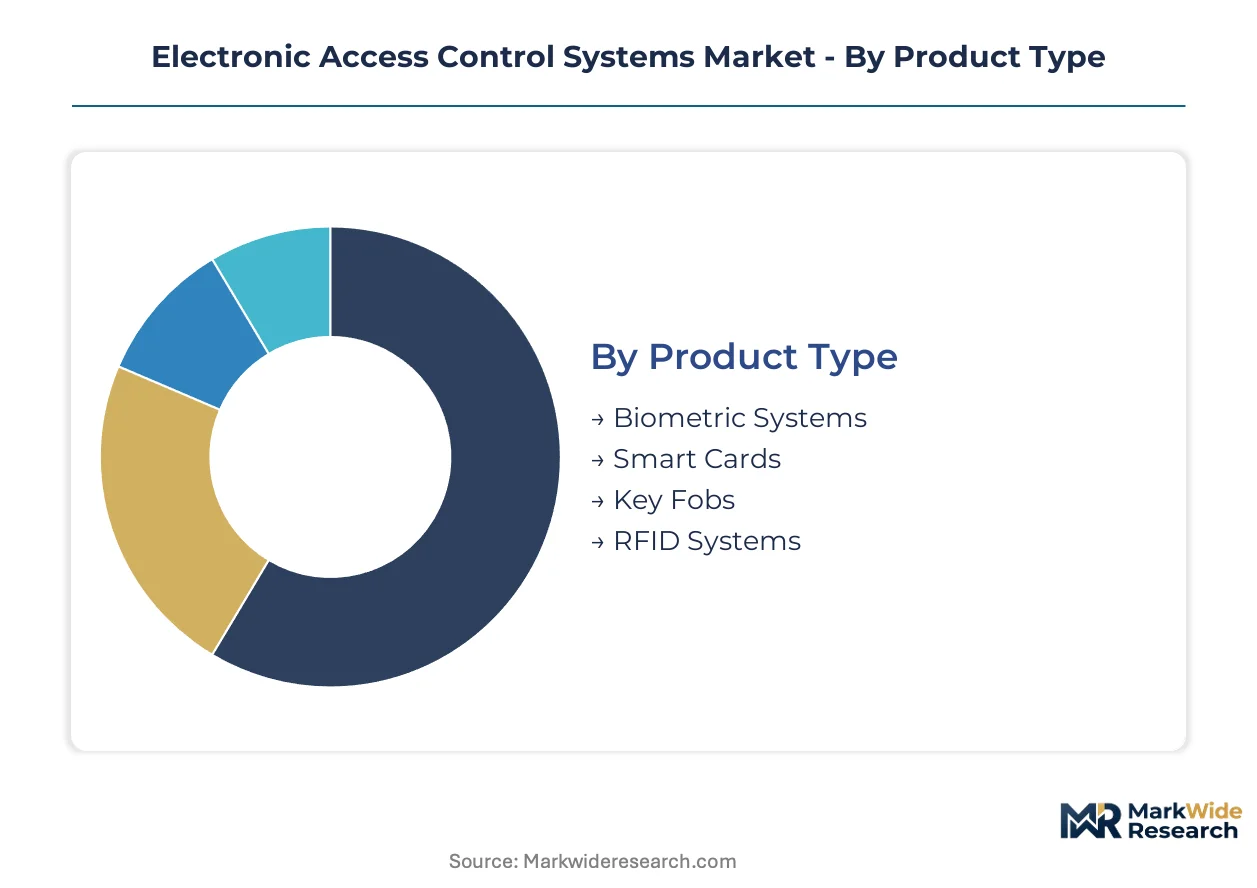
Segmentation in electronic access control systems reveals how credential formats, connectivity architectures, and facility types create divergent margin structures and procurement cycles across the value chain. Vendors configure product portfolios around these divides to capture recurring software revenue versus one-time hardware sales.
Product Type:
Mature credential formats dominate transaction volumes while biometric modalities reshape high-assurance installations.
- Smart Cards:Contactless credentials operating at 13.56 MHz with DESFire EV3 or MIFARE Plus encryption remain the default for federal government campuses under FIPS 201 mandates and healthcare networks requiring HIPAA audit trails. German municipal buildings and U.S. General Services Administration facilities standardize on this format, locking in multi-year procurement contracts for PIV-compatible readers.
- Biometric Systems:Multi-factor fusion readers combining facial recognition with iris or vascular pattern matching eliminate credential sharing in pharmaceutical cleanrooms and financial data centers. China's MIIT GB standards for biometric data protection and the EU's GDPR Article 9 processing restrictions shape deployment architectures, with liveness detection algorithms becoming a software licensing battleground.
- RFID Systems:Long-range UHF readers for vehicle gates and loading docks concentrate in logistics hubs and airport perimeters.
- Key Fobs:125 kHz proximity tokens persist in legacy multifamily residential retrofits where wiring replacement costs outweigh security upgrades.
Smart cards retain volume leadership; biometric systems hold the steepest expansion curve.
Technology:
Connectivity architectures segment by infrastructure investment depth and cybersecurity compliance burden.
- Cloud-Based:SaaS-delivered identity platforms with TLS-encrypted edge gateways compress hardware refresh cycles while shifting revenue to monthly per-door subscriptions. Commercial real estate operators in Class A office towers across Manhattan and London bypass mechanical contractors to contract directly with cloud-native vendors, unbundling security procurement from construction budgets.
- Hybrid:Architectures pairing on-premise credential databases with cloud analytics satisfy data residency requirements in German healthcare and Chinese state-owned enterprises. The EU Cybersecurity Act's EN 303645 baseline and China's MIIT IoT security GB standards force manufacturers to maintain dual certification tracks, extending product launch timelines.
- Wired:RS-485 and OSDP-secured hardwired readers anchor federal facilities and critical infrastructure where air-gapped networks resist cloud migration.
- Wireless:Battery-operated locks with BLE or Zigbee connectivity enable rapid deployment in historic building retrofits where conduit installation is prohibited.
Cloud-based deployments are gaining share fastest; wired systems anchor the highest-assurance installations.
End User:
Customer types diverge sharply in procurement authority, compliance drivers, and lifetime value metrics.
- Commercial:Corporate campuses and mixed-use developments drive demand for mobile credential integration with Apple Wallet and Google Wallet, reducing plastic card issuance. Facility managers in U.S. and German Class A properties retain dedicated technology budgets independent of capital projects, creating direct vendor relationships that disintermediate traditional security integrators.
- Government:Federal, state, and municipal facilities enforce the strictest certification requirements. The U.S. FICAM framework mandates PIV credentialing, while the EU Cybersecurity Act requires CE marking with EN 60839 compliance for intrusion and access systems sold across member states.
- Industrial:Manufacturing plants and energy facilities prioritize ruggedized readers with IP65+ ratings and explosion-proof certifications for hazardous zones.
- Residential:Multifamily landlords and homeowners associations favor retrofit-friendly wireless locks with smartphone app management, trading security depth for installation convenience.
Commercial verticals generate the highest recurring revenue per door; government segments impose the steepest compliance costs.
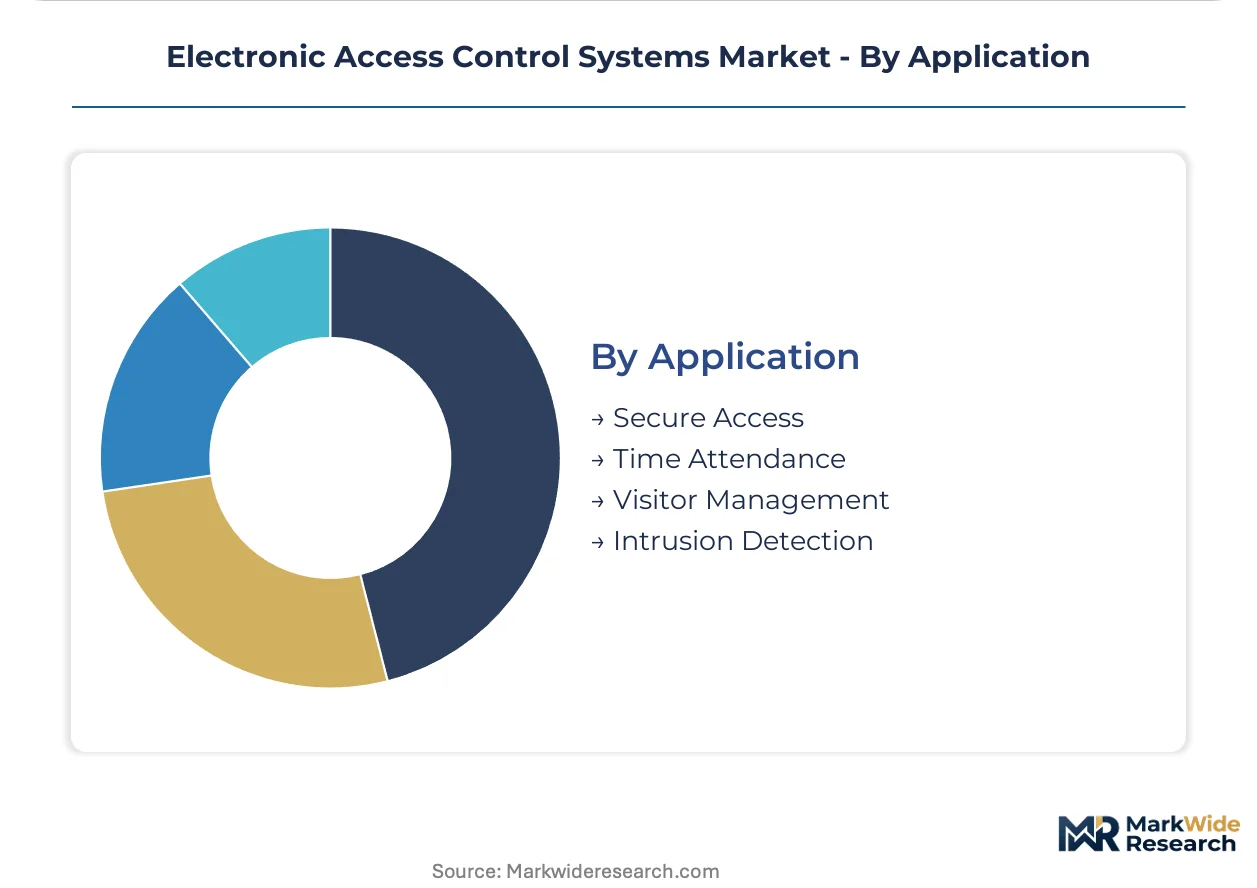
Application:
Use-case specialization determines sensor configuration, software module requirements, and integration complexity.
- Secure Access:Entry authentication remains the core function, with demand concentrating in data centers, pharmaceutical manufacturing, and financial trading floors where tailgating prevention justifies multi-factor biometric deployment.
- Time Attendance:Workforce management integration pulls access control into HRIS platforms, particularly in healthcare systems and educational institutions with complex shift patterns.
- Visitor Management:Temporary credential issuance and pre-registration workflows expand in corporate headquarters and government reception facilities, with GDPR and state privacy laws complicating data retention policies.
- Intrusion Detection:Perimeter hardening with door position sensors and glass-break detectors converges with access control panels, reducing separate alarm system procurement.
Secure access commands the installed base; visitor management is climbing the fastest as privacy-compliant workflow automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement mandates and smart city infrastructure programs are concentrating demand in the United States, Germany, and China. Commercial real estate retrofit cycles and tightening cybersecurity certification requirements are reshaping vendor priorities across these markets.
United States
Class A office towers in Manhattan and Chicago are unbundling security procurement from construction contracts, creating direct vendor relationships. The General Services Administration enforces FICAM guidelines mandating PIV credentialing for federal facilities. Silicon Valley data centers and pharmaceutical manufacturing clusters in New Jersey are deploying multi-factor biometric fusion readers to eliminate tailgating vulnerabilities.
Germany
Municipal building retrofit programs across Bavaria and North Rhine-Westphalia are integrating access control with HVAC automation. The EU Cybersecurity Act requires EN 60839 compliance and CE marking for intrusion and access systems, extending testing timelines. Frankfurt financial district operators and Stuttgart automotive headquarters prioritize suppliers with certified security development lifecycles under EN 303645 baseline requirements.
China
State-owned enterprises and smart city projects under MIIT direction are driving cloud-connected reader deployment. GB standards for IoT security issued by MIIT shape product development cycles for domestic manufacturers. Yangtze River Delta manufacturing hubs and Beijing-Tianjin-Hebei administrative centers concentrate procurement for integrated access and video management systems.
India
Municipal surveillance programs under the Ministry of Housing and Urban Affairs are creating procurement pipelines for integrated security systems. The country's national cybersecurity regulator mandates baseline encryption standards for government facility access. Bangalore technology campuses and Delhi-NCR commercial developments are bypassing traditional integrators to contract directly with cloud-native credentialing vendors.
United Kingdom
London financial services firms are merging physical and logical access policies under zero trust architecture frameworks. GDPR Article 9 processing restrictions shape biometric deployment architectures in healthcare and government verticals. Canary Wharf Class A developments and Cambridge research parks retain dedicated technology budgets independent of capital project financing.
Electronic Access Control Systems Market Key Industry Players
On the supply side, the industry is consolidating around hardware-to-software integration capabilities and recurring revenue platform economics. Incumbent industrial conglomerates with building automation portfolios compete against cloud-native specialists and regional hardware fabricators. Three archetypes dominate: integrated building technology conglomerates, pure-play access control specialists, and diversified security electronics manufacturers. Competitive moves center on SaaS revenue model transitions and strategic partnerships with facility management firms.
Within the integrated conglomerate tier, ASSA ABLOY and Johnson Controls International plc exemplify archetypes anchoring enterprise recurring revenue streams through hardware-software convergence. Honeywell International Inc. occupies a position representing AI-enhanced threat detection layering into credentialing infrastructure. These three entities sit within distinct strategic vectors—credentialing hardware dominance, building automation convergence, and intelligence-augmented security platforms—illustrating how vendor positioning fragments across technology stack control points rather than geographic or vertical boundaries.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Johnson Controls International plc |
| Honeywell International Inc. |
| dormakaba Group |
| Allegion plc |
| Bosch Security Systems |
| Axis Communications |
| Nedap N.V. |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Taiwan's semiconductor fabrication clusters anchor RFID reader chip production, concentrating upstream capacity and granting foundries outsized leverage over hardware OEMs negotiating annual supply agreements. This geographic concentration feeds directly into pricing power dynamics across credential reader manufacturing tiers.
Pricing Analysis
Certification level (FIPS 201/EN 60839/GB tier) creates the primary spread between hardware price bands. SaaS-delivered identity platforms command recurring per-door subscriptions, while on-premise licensing retains project-based pricing for federal installations. Cost compression in standard-grade readers is intensifying because mobile credential substitution erodes dedicated hardware demand. Government verticals show least price sensitivity due to compliance mandates; mid-market commercial tenants exhibit highest sensitivity, driving equipment-as-a-service financing adoption.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard as Taiwanese foundries and South Korean memory suppliers tighten working capital requirements on downstream hardware manufacturers. RFID reader chip fabrication draws from Taiwan and South Korea, with mechanical lock assemblies sourcing from China and Germany. Single-source vulnerability concentrates in 13.56 MHz transceiver silicon. Distribution runs through certified security integrators and direct vendor relationships with Class A facility managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as cloud-native credentialing platforms displace legacy on-premise systems, creating niches for specialized biometric fusion vendors and regional compliance consultants.
For Market Incumbents: Build switching-cost moats through deep building-automation integration with HVAC and lighting control systems. Incumbents should anchor enterprise recurring revenue via hardware-software convergence while investing in EN 303645-certified security development lifecycles to defend against cloud-native entrants. Channel control through certified installer training programs locks out distribution-dependent competitors. For New Entrants and Emerging Players: Mid-market commercial buildings in India and Southeast Asia represent the most penetrable entry point, with municipal smart city programs under the Ministry of Housing and Urban Affairs creating procurement pipelines. Subscription financing partnerships with facility management firms lower upfront capital barriers. A zero-trust architecture integration angle opens enterprise IT department contracts. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because physical-cybersecurity convergence locks in multi-year identity platform contracts. Acquisition targets should display SaaS revenue model transitions with demonstrated facility management firm partnerships. The signal to watch is federal PIV credentialing mandate expansion beyond current GSA facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Convergence with building automation systems deepens enterprise switching costs and recurring revenue. |
| Certification Investment | EN 303645 and FIPS 201 compliance opens federal and EU healthcare procurement channels. |
| Strategic Partnership | Equipment-as-a-service leasing through facility management firms lowers mid-market barriers. |
| Acquisition of Specialist Firm | Biometric fusion algorithm vendors add software licensing revenue to hardware portfolios. |
| Geographic Expansion | India smart city infrastructure under Ministry of Housing and Urban Affairs creates procurement pipelines. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with facility managers, security integrators, and identity platform engineers. Secondary validation drew from NIST cybersecurity guideline publications, EU Cybersecurity Act implementation documents, MIIT GB standard filings, and commercial real estate retrofit procurement databases. Bottom-up credential reader shipment estimates triangulated against top-down building automation spend allocations.
Calibration against historical FICAM deployment timelines and smart building retrofit cycle data anchored the projection framework across the analysis window. Segmentation dimensions modeled include credential format, connectivity architecture, end-user vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating semiconductor supply constraints and mobile credential substitution rates.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate capital expenditure cycles or Taiwan semiconductor foundry allocation would shift the trajectory. Forecasts reflect documented assumptions about FICAM mandate expansion and EN 60839 certification timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
North America Keyless Vehicle Access Control System Market
Access Control Systems
Locks Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
North America Home Security System Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Global Industrial Security Systems Market