
 Asia-Pacific Low Voltage Switchgear Market | 2026-2036
Asia-Pacific Low Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Low Voltage Switchgear Market Insights
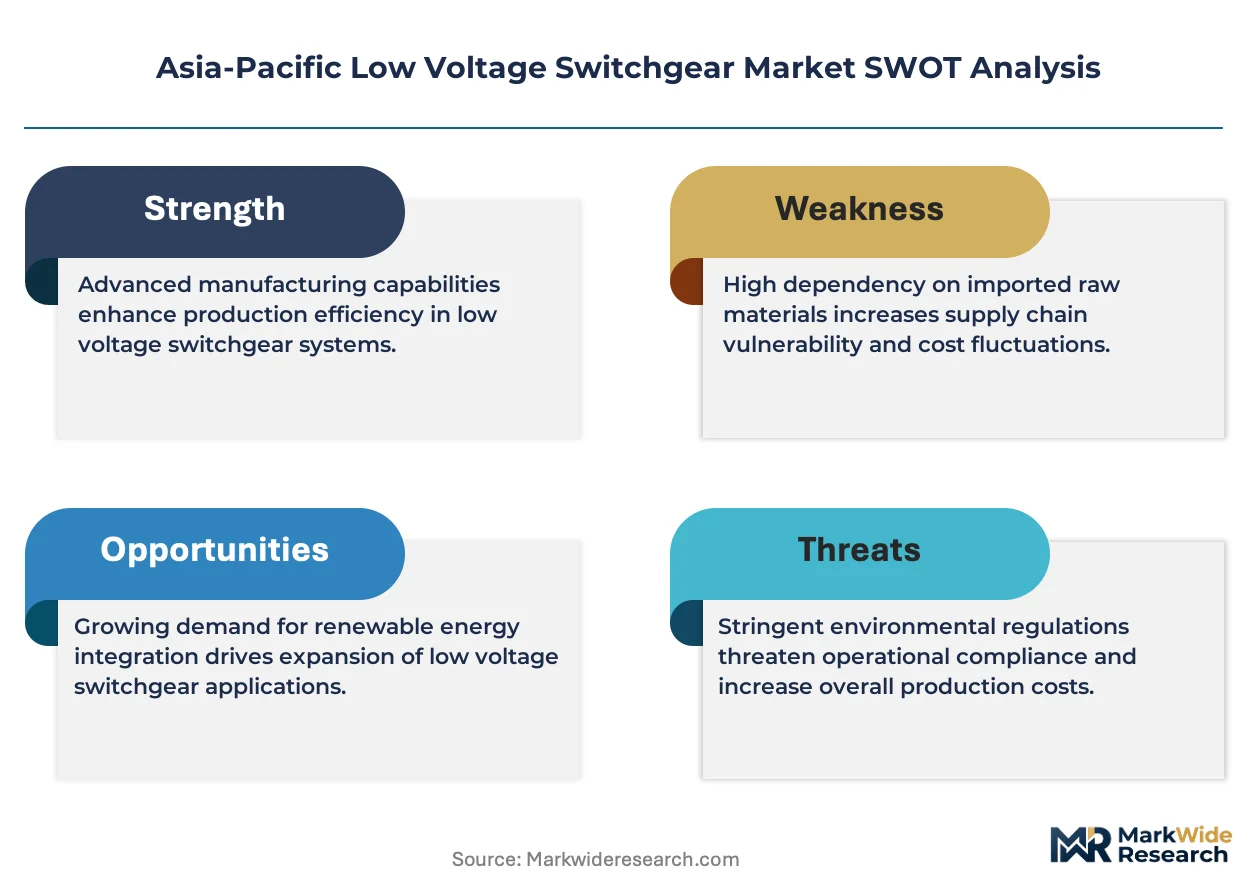
IEC 61439 compliance for low-voltage switchgear assemblies is redrawing competitive boundaries across the Asia-Pacific. Schneider Electric leverages its R&D footprint in India and China to sustain certification leadership across tropicalized product lines. CHINT anchors its position through backward integration into contactor and relay manufacturing, while ABB competes on digital switchgear platforms integrated with asset management software.
Asia-Pacific low voltage switchgear encompasses electrical distribution equipment rated up to 1,000 volts AC or 1,500 volts DC, comprising molded-case and air circuit breakers, contactors, and protective relays housed in metal-enclosed assemblies. These systems interrupt fault currents, isolate equipment, and distribute power across commercial buildings, industrial plants, and utility substations. Circuit breakers command the largest product share due to mandatory protection requirements in heavy industrial installations, while smart technology represents the fastest-expanding segment as facilities managers adopt IoT-enabled condition monitoring. Indoor installations dominate the regional stock given density constraints in East Asian urban centers, though outdoor variants gain traction in Australia's mining and utility sectors.
China's GB/T 7251 series and India's BIS IS/IEC 61439 standards enforce thermal and short-circuit withstand testing that foreign suppliers must satisfy through local testing partnerships. Japan's METI technical standards and South Korea's KC certification add further compliance layers for entrants targeting Northeast Asian procurement channels. Stakeholders must weigh certification lead times against the margin premium available in smart switchgear segments where software differentiation increasingly separates winners from commodity suppliers.
Market Dynamics
IEC 61439 compliance mandates are compressing supplier margins while simultaneously locking out uncertified competitors across Southeast Asian procurement channels. Data center operators in Singapore and Vietnam now specify tropicalized switchgear assemblies as standard, forcing manufacturers to absorb retooling costs or exit tender processes.
Growth Catalysts
- Smart grid modernization:Distribution utilities in South Korea and Australia are deploying IoT-enabled circuit breakers with embedded condition monitoring. This creates recurring software revenue streams for hardware suppliers.
- India's PLI scheme for electrical equipment:Production-linked incentives are attracting domestic manufacturing investment in Gujarat and Tamil Nadu industrial corridors. Local assembly reduces import duty exposure for multinational suppliers.
- GB/T 7251.12 thermal testing mandates:China's updated national standards require enhanced heat dissipation validation for switchgear in tropical climates. Certified products command procurement preference in state-owned utility tenders.
Market Restraints
- Copper and silver price volatility:Contact and busbar materials constitute 35-45% of raw material costs. Price spikes in LME copper futures directly compress gross margins for assembled switchgear producers.
- Concentrated relay and contactor supply:Japanese and German component suppliers control premium electromechanical device production. Asian switchgear assemblers face extended lead times and volume allocation constraints.
- Legacy air circuit breaker substitution:Molded-case breakers with electronic trip units are displacing traditional ACBs in commercial buildings below 4000A ratings. This erodes service revenue from mechanical refurbishment.
Strategic Opportunities
- Underpenetrated Philippine industrial zones:Subic Bay and Clark Freeport manufacturing parks lack localized switchgear assembly capacity. First-mover facilities can capture Batangas refinery and Cebu data center demand.
- Digital twin integration:Convergence of switchgear hardware with asset performance management software enables predictive maintenance contracts. This shifts revenue from capital sales to recurring subscriptions.
- Vietnam's direct power purchase agreements:New regulations allow industrial consumers to contract renewable energy directly. This drives demand for grid-interactive switchgear with bi-directional protection capabilities.
Industry Challenges
- Certification timeline compression:BIS IS/IEC 61439 testing at Indian laboratories now exceeds 16 weeks for foreign-designed products. Delayed market entry cedes early-mover advantage to domestic competitors.
- Legacy SCADA integration complexity:Brownfield industrial facilities in Japan and South Korea operate proprietary communication protocols. New smart switchgear deployments require costly gateway development for interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Low Voltage Switchgear Market |
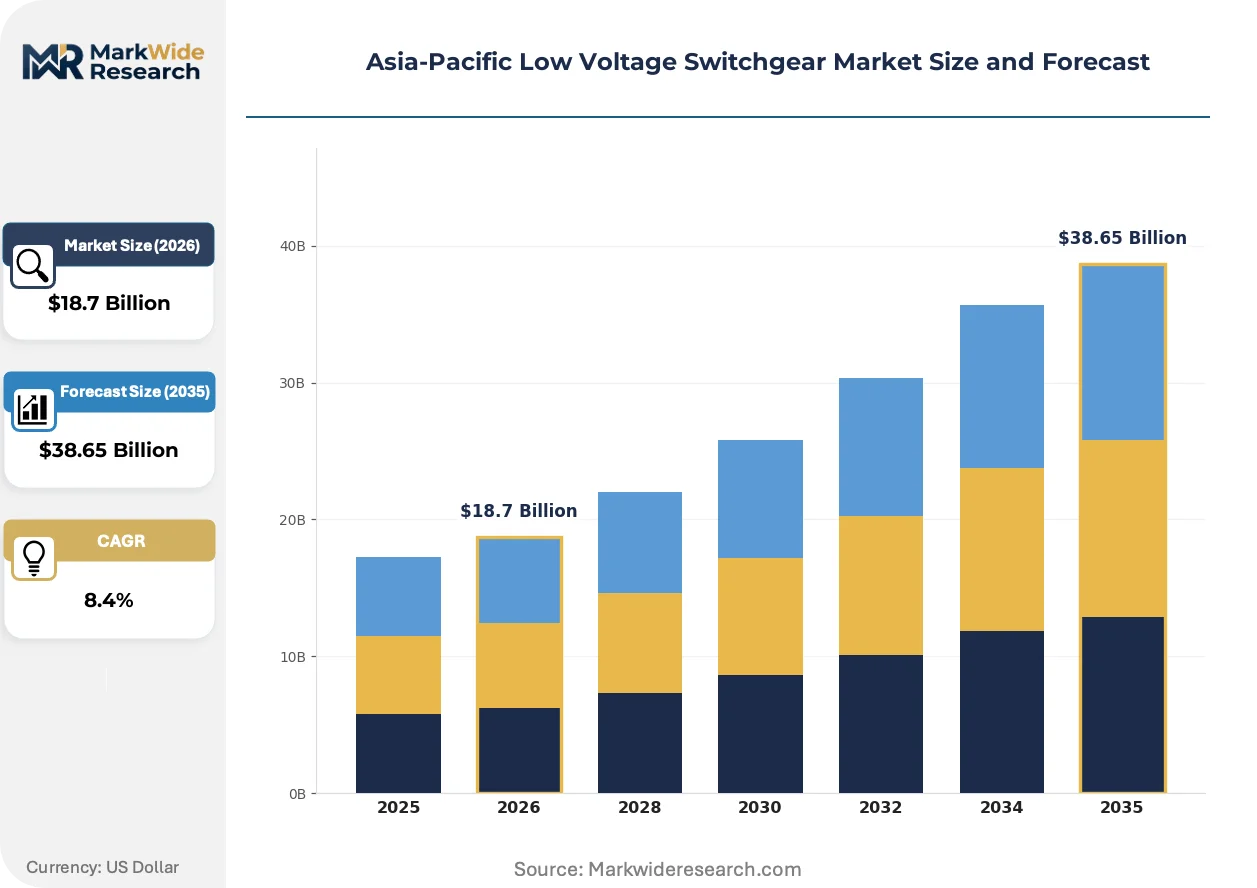
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Disconnectors, Fuses, Switches End User: Commercial, Residential, Industrial, Utilities Installation Type: Indoor, Outdoor, Wall-mounted, Floor-mounted Technology: Digital, Analog, Hybrid, Smart |
| Companies Covered | Mitsubishi Electric Corporation, CHINT, Schneider Electric, Hyundai Electric, LS Electric, ABB, Eaton, Guangzhou Baiyun Electric Equipment, Siemens, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Low Voltage Switchgear Market Trends and Innovations
Electrification of heavy industry and data center buildouts are accelerating product architecture shifts across the Asia-Pacific switchgear value chain. Suppliers are repositioning around software-enabled differentiation rather than hardware specifications alone.
Modular withdrawable circuit breaker designs are decomposing traditional fixed-mounted switchgear configurations in heavy industrial applications. Mining operators in Western Australia and steel producers in Jiangsu Province are specifying抽出式 (withdrawable) units for reduced maintenance downtime. This architecture is decomposing the aftermarket service model by enabling rapid module exchange rather than complete unit replacement.
China's GB/T 7251.8-2020 arc fault mitigation standards are mandating internal arc classification testing for all new switchgear installations in public buildings. Manufacturers must demonstrate 100ms fault clearing times and reinforced door retention under pressure. Commercial real estate developers in Shanghai and Shenzhen are now specifying IAC A FLR 100kA ratings as baseline procurement criteria, filtering out uncertified suppliers.
Data center operators are unbundling switchgear procurement from EPC contracts and contracting directly with certified assembly manufacturers. This disintermediation bypasses traditional electrical contractor margins and accelerates specification control. The pattern is most visible in Singapore's Tuas data center cluster and Navi Mumbai's hyperscale facilities, where owners now maintain approved vendor lists with direct factory relationships.
Asia-Pacific Low Voltage Switchgear Market Segmentation
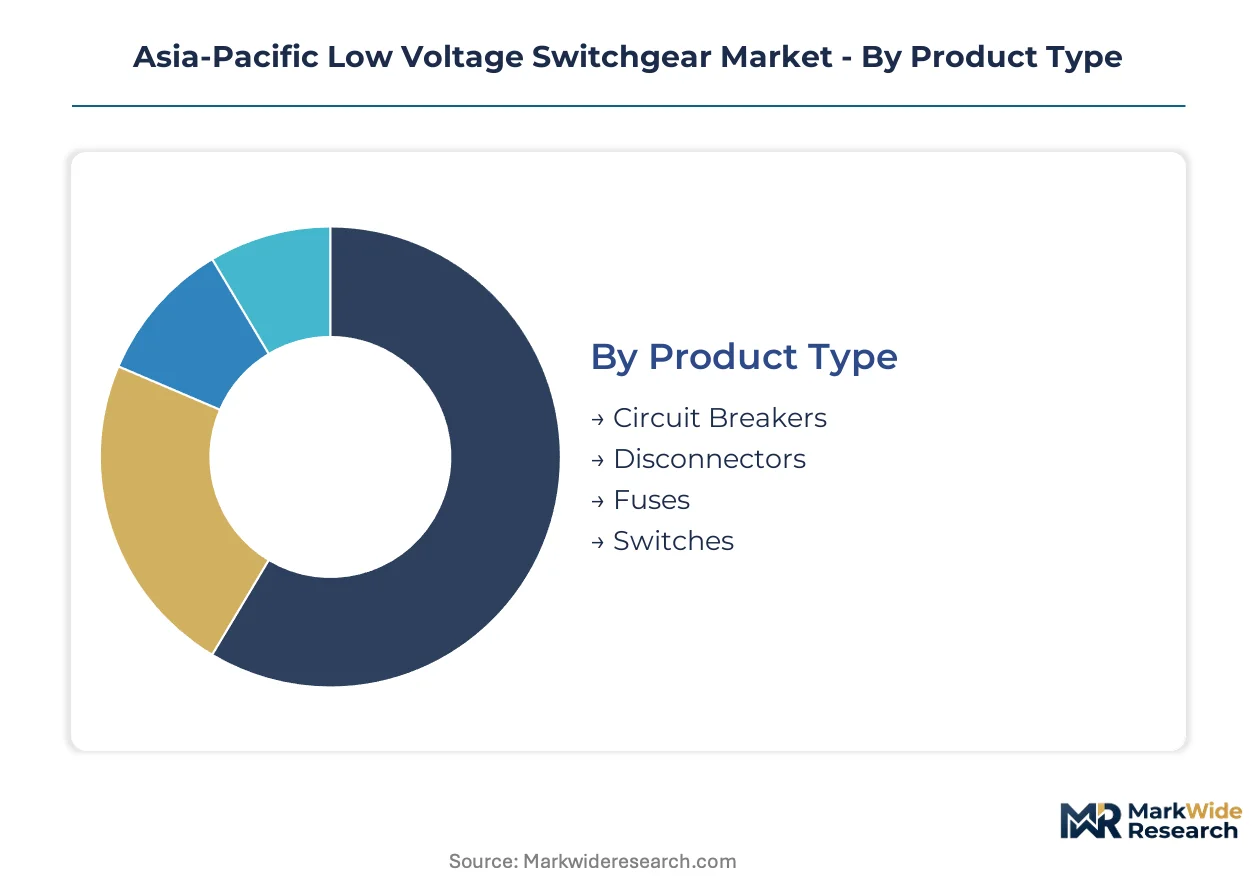
Low voltage switchgear procurement across Asia-Pacific fragments across four critical dimensions. Product architecture determines compliance pathways against GB/T 7251 and BIS IS/IEC 61439 standards. End-use concentration in India's industrial corridors and Vietnam's manufacturing zones reshapes volume allocation by segment.
Product Type:
GB/T 7251.12 thermal testing mandates and BIS IS/IEC 61439 arc fault classifications create divergent certification burdens across product categories. Suppliers must align R&D investment with the compliance intensity each segment demands.
- Circuit Breakers:Molded-case and air circuit breakers interrupt fault currents up to 100kA in heavy industrial installations. Demand concentrates in Jiangsu Province steel complexes and Western Australian mining operations where withdrawable designs reduce maintenance downtime. GB/T 7251.8-2020 arc fault mitigation standards now mandate 100ms clearing times for public building installations.
- Disconnectors:These isolating devices provide visible break verification for maintenance safety in utility substations and commercial switchboards. Procurement accelerates across Singapore's Tuas data center cluster as operators unbundle switchgear from EPC contracts and specify direct manufacturer relationships.
- Fuses:Current-limiting fuse links protect downstream equipment in distribution boards and motor control centers.
- Switches:Load-break and isolating switches handle routine switching operations in commercial building electrical distribution.
Circuit breakers handle the majority of throughput; smart breaker assemblies with embedded condition monitoring are gaining share fastest.
End User:
Cost tier differentiation separates premium-specified industrial installations from price-sensitive residential distribution. Procurement authority and technical specification complexity vary sharply across end-use categories.
- Industrial:Heavy manufacturing, mining, and petrochemical facilities specify withdrawable breaker configurations and tropicalized assemblies. India's PLI scheme for electrical equipment attracts domestic manufacturing investment to Gujarat and Tamil Nadu corridors. Copper and silver price volatility directly compress margins for assembled switchgear in this volume-intensive segment.
- Utilities:Distribution network operators in South Korea and Australia deploy IoT-enabled circuit breakers with embedded condition monitoring. Smart grid modernization creates recurring software revenue streams for hardware suppliers serving this technically demanding customer base.
- Commercial:Office complexes, retail centers, and hospitality facilities specify molded-case breakers with electronic trip units below 4000A ratings.
- Residential:Multi-unit dwellings and individual housing units drive volume for compact distribution boards and miniature circuit breakers.
Industrial installations dominate absolute spend; utility smart grid deployments are expanding most quickly on share.
Installation Type:
Physical mounting configuration responds to site constraints and environmental exposure. Density limitations in East Asian urban centers favor compact architectures, while Australia's mining sectors demand weather-resistant outdoor variants.
- Indoor:Metal-enclosed assemblies rated for controlled environments dominate East Asian commercial and industrial stock. Shanghai and Shenzhen commercial real estate developers now specify IAC A FLR 100kA ratings as baseline procurement criteria.
- Outdoor:Weatherproof enclosures with enhanced sealing and corrosion protection serve utility substations and remote industrial sites. Australia's mining and utility sectors drive specification of tropicalized outdoor variants with extended temperature ranges.
- Wall-mounted:Compact distribution boards conserve floor space in high-rise commercial and residential buildings across dense urban centers.
- Floor-mounted:Free-standing switchgear assemblies accommodate large breaker frames and auxiliary equipment in heavy industrial facilities.
Indoor configurations command the installed base; outdoor variants are climbing the fastest as mining and utility investment extends to exposed sites.
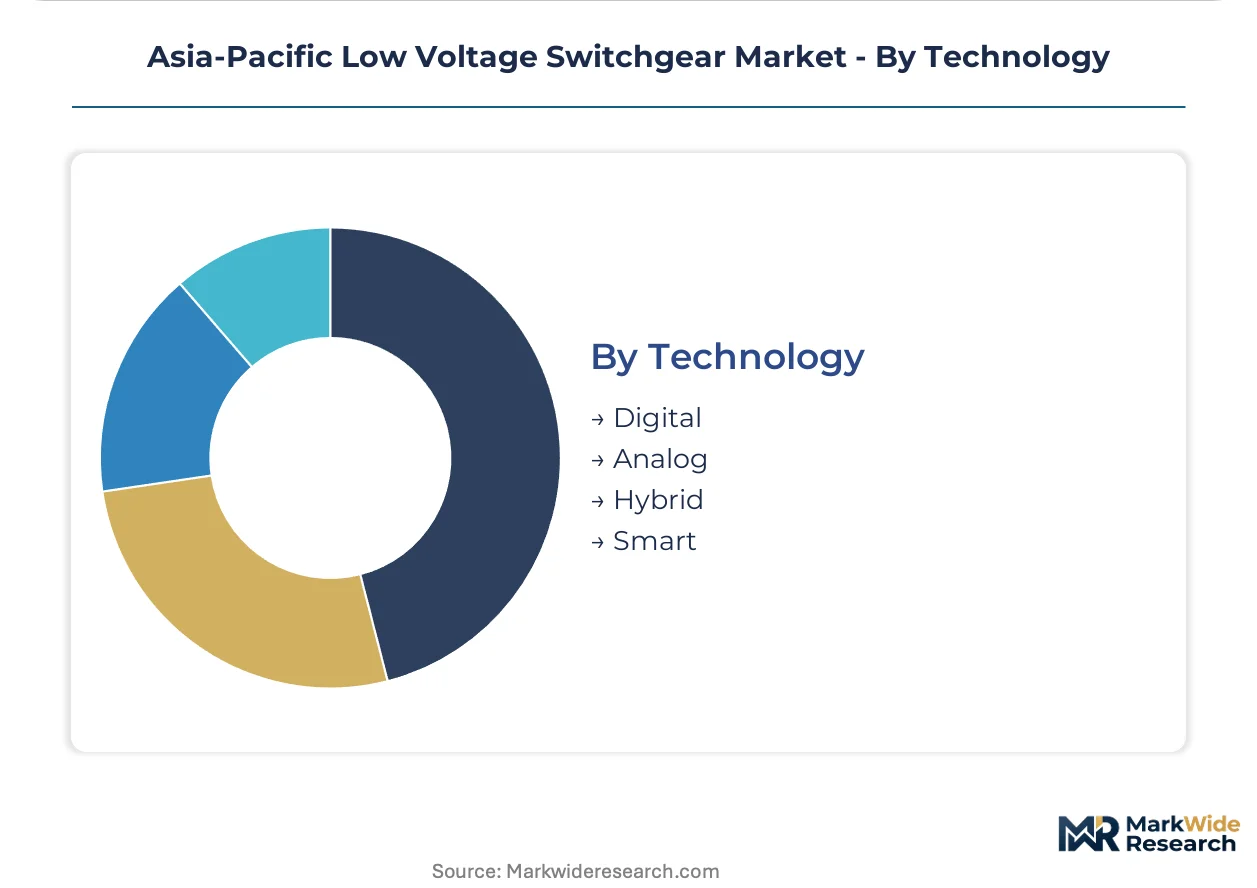
Technology:
Maturity gradients separate established electromechanical platforms from emerging digital architectures. Software-enabled differentiation increasingly determines margin capture versus commodity competition.
- Smart:IoT-enabled switchgear with embedded sensors, edge computing, and cloud connectivity enables predictive maintenance and asset performance management. Data center operators in Singapore and Vietnam specify tropicalized smart assemblies as standard, forcing retooling investment or tender exclusion.
- Digital:Solid-state protection and electronic trip units replace thermal-magnetic mechanisms in precision applications. Brownfield industrial facilities in Japan and South Korea require costly gateway development for proprietary SCADA protocol interoperability.
- Hybrid:Electromechanical breakers with digital monitoring modules bridge legacy infrastructure and modern asset management platforms.
- Analog:Conventional thermal-magnetic protection persists in cost-sensitive residential and small commercial installations.
Smart technology represents the steepest expansion trajectory; analog platforms retain volume in price-constrained segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial procurement authority concentrates with heavy manufacturing clusters and data center operators across five national markets. Each geography imposes distinct certification burdens that filter supplier participation.
China
Jiangsu Province steel complexes and Pearl River Delta manufacturing zones drive withdrawable breaker demand. GB/T 7251.8-2020 arc fault mitigation standards mandate 100ms clearing times for public building installations. Shanghai and Shenzhen commercial developers now specify IAC A FLR 100kA ratings as baseline procurement criteria.
India
Gujarat and Tamil Nadu industrial corridors attract domestic manufacturing investment under the PLI scheme for electrical equipment. BIS IS/IEC 61439 testing at Indian laboratories now exceeds 16 weeks for foreign-designed products. Navi Mumbai hyperscale data centers maintain approved vendor lists with direct factory relationships.
Japan
Brownfield industrial facilities in Kanto and Kansai regions operate proprietary SCADA communication protocols. METI technical standards add compliance layers for switchgear entrants targeting Northeast Asian procurement channels. Chubu steel producers specify tropicalized assemblies for reduced maintenance downtime.
South Korea
Distribution utilities deploy IoT-enabled circuit breakers with embedded condition monitoring across Seoul Capital Area networks. KC certification requirements filter supplier participation in national tender processes. Smart grid modernization creates recurring software revenue streams for hardware suppliers.
Vietnam
Manufacturing zones around Ho Chi Minh City and Hanoi accelerate procurement of smart switchgear assemblies. Direct power purchase agreement regulations allow industrial consumers to contract renewable energy directly. This drives demand for grid-interactive switchgear with bi-directional protection capabilities.
Asia-Pacific Low Voltage Switchgear Market Competitive Landscape
Player mix skews toward integrated multinational electrical equipment groups with regional certification capabilities. Market structure concentrates around three strategic tiers: full-range system suppliers with software platforms, component-integrated manufacturers with backward control over contactor production, and specialized assembly fabricators serving national markets. Dominant competitive moves include certification leadership investments in tropicalized product lines and digital platform integration with asset management software.
Within the integrated multinational tier, Schneider Electric, ABB, and Siemens exemplify archetypes competing on certification breadth and digital differentiation. Schneider Electric leverages R&D footprints in India and China to sustain tropicalized product leadership. ABB competes on digital switchgear platforms integrated with asset management software. Siemens anchors European-origin positioning across Northeast Asian procurement channels. CHINT represents the component-integrated archetype through captive contactor and relay manufacturing. Hyundai Electric and LS Electric occupy Korea-based positions serving domestic utility modernization programs.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| CHINT |
| Schneider Electric |
| Hyundai Electric |
| LS Electric |
| ABB |
| Eaton |
| Guangzhou Baiyun Electric Equipment |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Sixteen-week certification queues at Indian BIS laboratories concentrate pricing power with pre-certified incumbents while forcing late entrants into discounting to recover lost tender windows. This lead-time compression rewards manufacturers with captive testing partnerships and penalizes those dependent on third-party validation cycles.
Pricing Analysis
Cost-plus contracts indexed to LME copper futures dominate industrial procurement in Jiangsu Province steel complexes and Western Australian mining operations. Pricing stratifies across IEC 61439-certified premium tiers, BIS-compliant standard assemblies, and non-certified economy imports. Cost compression in the standard tier is intensifying because Chinese GB/T 7251.8-2020 arc fault mandates require retooling investments that uncertified competitors cannot absorb. Data center operators in Singapore's Tuas cluster exhibit lowest price sensitivity due to unbundled direct procurement, while Philippine commercial developers remain most price-sensitive.
Supply Chain Analysis
Japanese and German electromechanical component suppliers control premium relay and contactor production, creating allocation chokepoints for Asian switchgear assemblers. Manufacturing draws from China for contactor housings, India for copper busbar fabrication, and South Korea for electronic trip units. Single-source vulnerability concentrates in silver-alloy contact materials sourced from concentrated refining operations. Distribution runs through authorized electrical distributors serving EPC contractors, though data center operators increasingly bypass this channel for direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward data center operators and state utility procurement offices as tender consolidation concentrates volume with fewer decision-makers. This concentration fragments pricing leverage for smaller commercial developers.
For Market Incumbents: Fortify certification leadership through expanded tropicalized product lines at Indian and Chinese R&D facilities. Deepen backward integration into contactor manufacturing to reduce exposure to Japanese supplier allocation constraints. Defend against molded-case breaker substitution by embedding predictive maintenance software that locks in recurring revenue streams. For New Entrants and Emerging Players: Differentiate on grid-interactive protection capabilities for Vietnam's direct power purchase agreement market. Capture white-space demand in Subic Bay and Clark Freeport manufacturing parks where localized assembly capacity remains underdeveloped. Pursue asset-light entry through digital twin software partnerships rather than capital-intensive manufacturing footprints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart switchgear segments as IoT-enabled condition monitoring requires embedded sensor and edge computing investments. Long-term viability favors platform-integrated suppliers with recurring software revenue over pure hardware assemblers. Target acquisition candidates with established BIS and GB/T certification pipelines. Monitor arc fault mitigation standard adoption rates as the signal for regulatory-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contactor Manufacturing | Captive supply of electromechanical components insulates margin from Japanese supplier allocation constraints. |
| Digital Twin Platform Development | Asset performance management software shifts revenue from capital sales to recurring predictive maintenance subscriptions. |
| Tropicalized Product Line Expansion | Certification leadership in IEC 61439 tropical variants secures preference in Southeast Asian data center tenders. |
| Direct Procurement Channel Establishment | Bypassing EPC contractor margins captures specification control with Singapore and Navi Mumbai data center operators. |
| Smart Grid Partnership Programs | Utility modernization contracts in South Korea create recurring software revenue streams alongside hardware deployment. |
Research Methodology
A spread of perspectives from switchgear procurement managers at data center operators, plant engineers at steel and petrochemical facilities, electrical contractors serving industrial corridors, and certification engineers at BIS and GB testing laboratories converged on the working assumptions. These primary insights were cross-referenced with customs trade data for copper busbar and contactor imports, IEC and GB standard publication records, state utility tender documentation, and SEC filings from listed electrical equipment manufacturers. Bottom-up volume estimates from product-type and end-use segmentation were reconciled against top-down market value assessments.
Segmentation dimensions modeled include product architecture, end-use industry concentration, installation type, and technology maturity tier across the projection horizon. CAGRs were derived from growth driver elasticity analysis applied to baseline installation stock data. Forecast inputs incorporated data center capex pipelines from Singapore and Vietnam, PLI scheme uptake rates in Gujarat and Tamil Nadu, and smart grid deployment schedules from South Korean distribution utilities.
Forecasts assume regulatory continuity in China's GB standard regime and India's BIS certification framework; material policy shifts would require re-modeling. Commodity price volatility in copper and silver markets, certification timeline extensions at Indian laboratories, and legacy SCADA protocol fragmentation in Japanese brownfield facilities represent specific revision risks. Practitioners should keep alternative scenarios live as arc fault mitigation standard adoption rates and direct power purchase agreement regulatory evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Oil Level Switches Market
Switches
Timer Switch Socket Market
Switches
5G Solid State Switches Market
Switches
Navigation Switches Market
Switches
Miniature-Circuit Breaker Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Global Float Level Switches Market
Switches
Membrane Switch Market
Switches
Smart Dimmer Switch Market
Switches
Proximity Switches Market
Switches
5G Electromechanical RF Switch Market
Switches
Molded Case Circuit Breaker Market
Switches
Global Switchgear Market
Switches
Optical Switches Market