
 Global Industrial Smart Sensors Market | 2026-2036
Global Industrial Smart Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Smart Sensors Market Outlook
A shift from single-source chip procurement toward multi-source qualification is rebalancing supply chain risk across the sensor value chain. Texas Instruments leverages its analog front-end portfolio to sustain design-win momentum in precision temperature sensing. Infineon Technologies AG anchors its position through in-house MEMS fabrication, while Analog Devices, Inc. differentiates via signal-conditioning integration that reduces board-level complexity for OEMs.
Industrial smart sensors are transducer-based devices with embedded microprocessors, communication interfaces, and self-diagnostic algorithms that convert physical variables into digital signals with accuracy thresholds often below 0.1% full-scale error. They serve primarily to enable real-time equipment monitoring, predictive maintenance, and closed-loop process control in automated production environments. Pressure sensors occupy the largest revenue pool among product types due to universal deployment in hydraulic and pneumatic systems across manufacturing and energy sectors. IoT-enabled technology segments are expanding fastest as edge-computing architectures displace purely analog signal paths, though wired deployments still dominate margin capture in safety-critical aerospace applications.
FDA oversight of sensor-equipped medical manufacturing equipment, EPA emissions monitoring mandates for energy facilities, and EU Machinery Directive conformity requirements collectively elevate product certification costs while creating compliance barriers for non-standardized suppliers. China's MIIT GB standards and NMPA medical device rules add further testing protocols for vendors targeting Asia-Pacific industrial clusters. Stakeholders must monitor how converging cybersecurity standards for operational technology networks reshape firmware architecture requirements and vendor qualification timelines.
Market Dynamics
Edge computing architectures are displacing purely analog signal paths across factory floors, compressing hardware BOMs while elevating firmware complexity as the dominant value-capture mechanism in industrial sensing.
Growth Catalysts
- EU AI Act compliance mandates:Machinery Directive conformity requirements for autonomous sensor networks are forcing OEMs to upgrade legacy equipment, creating replacement cycles in Germany's automotive corridor.
- Automotive manufacturing IoT integration:Predictive maintenance systems on assembly lines are pulling multi-sensor arrays into hydraulic and pneumatic monitoring applications.
- MEMS fabrication advances:In-house semiconductor production capabilities are lowering unit costs for pressure transducers deployed in energy sector emissions monitoring.
Market Restraints
- Silicon wafer supply concentration:Taiwan-based foundry dominance creates single-source vulnerability for analog front-end chip procurement.
- FDA certification timelines:Sensor-equipped medical manufacturing equipment faces validation protocols that extend product launch windows by 18-24 months.
- Copper and rare earth input volatility:Magnetostrictive position sensors face margin pressure from commodity price swings in neodymium and dysprosium markets.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for smart manufacturing are opening greenfield deployment opportunities in Gujarat and Tamil Nadu automotive clusters.
- Cybersecurity firmware integration:Converging IEC 62443 standards for operational technology networks create premium positioning for vendors with certified secure boot architectures.
- Digital twin convergence:Real-time sensor-to-simulation pipelines are enabling new subscription revenue models in process control applications.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers proficient in deterministic real-time operating systems slows product development cycles.
- Legacy 4-20mA infrastructure retrofit complexity:Brownfield installations require protocol gateway layers that increase integration cost and failure points.
- Multi-jurisdiction certification stacking:Simultaneous EPA, EU Machinery Directive, and China MIIT GB compliance testing extends time-to-revenue for new product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Smart Sensors Market |
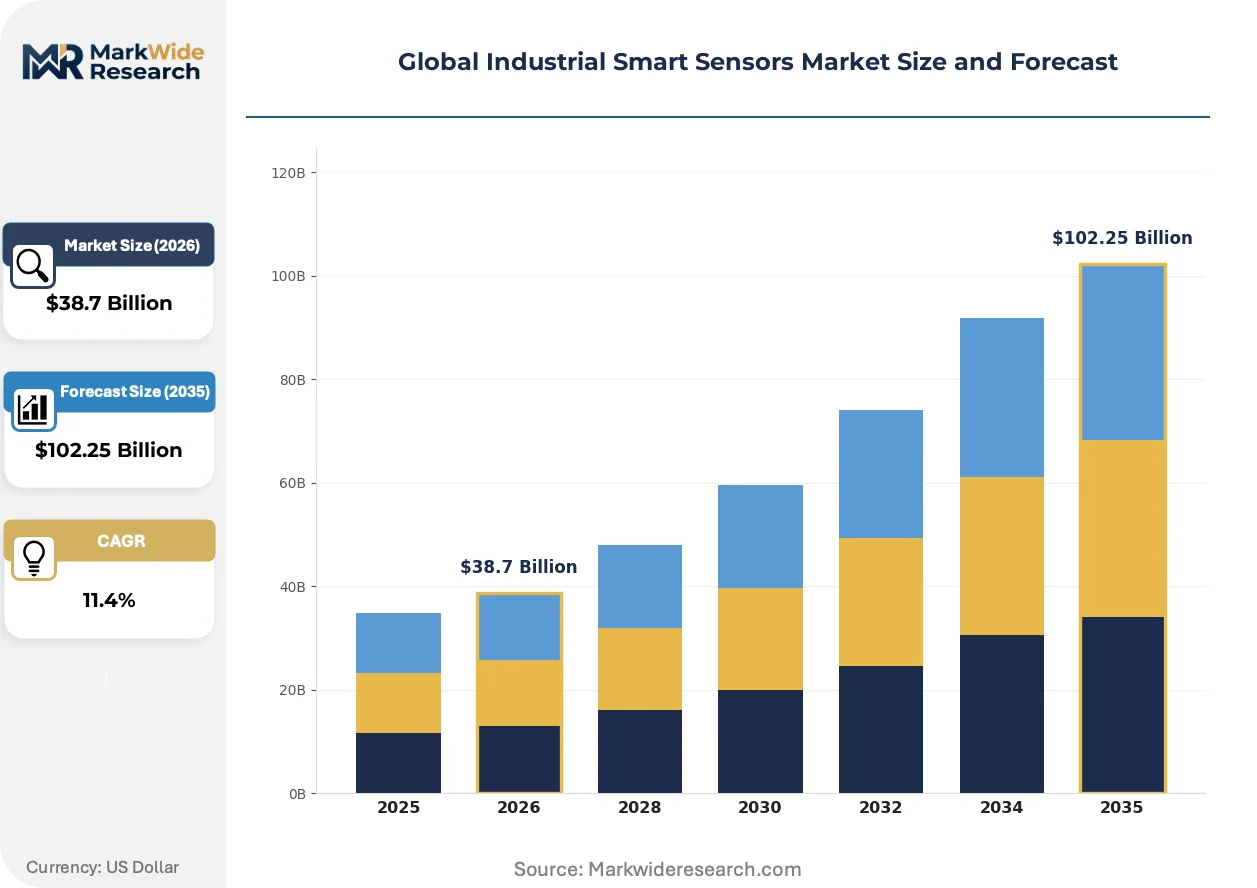
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Humidity Sensors Technology: Wireless, Wired, IoT-Enabled, Analog End User: Manufacturing, Automotive, Aerospace, Energy Deployment: On-Premises, Cloud-Based, Hybrid, Embedded |
| Companies Covered | Texas Instruments Incorporated, Infineon Technologies AG, Analog Devices, Inc., Robert Bosch GmbH, ABB, Honeywell International Inc., TE Connectivity, STMicroelectronics, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Smart Sensors Market Strategic Shifts
Signal-conditioning integration is compressing board-level complexity while edge AI inference engines are embedding directly into transducer housings, fundamentally altering where value accumulates in the sensing stack.
Time-sensitive networking over Ethernet is consolidating factory floor communication architectures by unifying sensor data streams, safety traffic, and control commands onto single physical layers. Automotive OEMs in Stuttgart and Wolfsburg are deploying TSN-enabled pressure and temperature arrays at line-replacement rates. This consolidation is collapsing the traditional separation between IT and OT network infrastructure, forcing sensor vendors to certify against dual cybersecurity frameworks.
The EU F-Gas Regulation and REACH substance restrictions are tightening material compliance for sealing compounds and potting materials used in harsh-environment sensors. Industrial gas detection equipment faces reformulation requirements for elastomer diaphragms and housing polymers. German chemical processors and Dutch food manufacturing facilities are accelerating qualification of fluorinated-gas-free sensor designs to preempt enforcement deadlines.
Outcome-based maintenance contracts are displacing component-only procurement in heavy process industries. Refinery operators in Rotterdam and Houston are negotiating sensor availability guarantees rather than capital purchases, transferring operational risk to vendors. This shift concentrates demand among suppliers with captive service networks and remote diagnostics platforms, marginalizing pure hardware vendors without lifecycle service capabilities.
Global Industrial Smart Sensors Market Segmentation
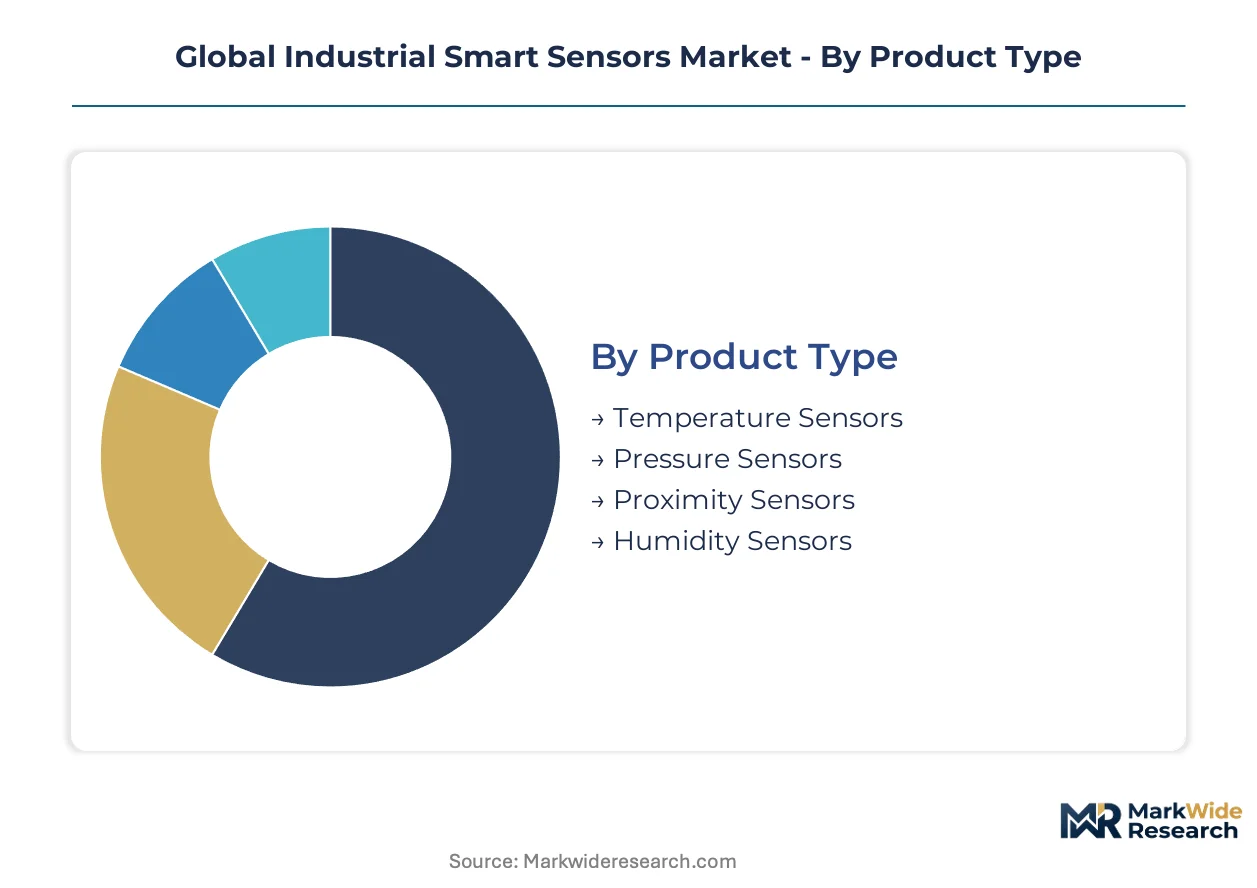
Segmentation in industrial smart sensors reveals how capital deployment, connectivity architecture, and end-use requirements fragment vendor strategies. Each dimension carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across transducer categories, with fabrication processes and calibration infrastructure driving divergent upfront investment thresholds.
- Pressure Sensors:Piezoresistive and capacitive MEMS elements dominate hydraulic and pneumatic system monitoring. Demand concentrates in Germany's automotive corridor where Bosch and Siemens anchor smart factory deployments, pulled by EU Machinery Directive conformity mandates for autonomous equipment networks.
- Temperature Sensors:Platinum RTD and thermocouple architectures achieve accuracy thresholds below 0.1% full-scale error through precision analog front-end integration. Energy sector emissions monitoring under EPA mandates drives qualification volumes in Texas and Louisiana refinery clusters.
- Proximity Sensors:Inductive and capacitive detection modules serve position feedback in automated assembly lines.
- Humidity Sensors:Thin-film polymer and capacitive ceramic elements monitor environmental conditions in pharmaceutical cleanrooms and food processing facilities.
Most installed capacity flows through pressure transducers. Expansion is steepest in temperature sensing arrays.
Technology:
Connectivity architecture determines where value accumulates in the sensing stack, with edge-computing firmware commanding premium positioning over legacy signal paths.
- IoT-Enabled:Embedded microprocessors with self-diagnostic algorithms and communication interfaces convert physical variables into digital signals for real-time equipment monitoring. Automotive manufacturing lines in Stuttgart and Wolfsburg deploy predictive maintenance systems that pull multi-sensor arrays into hydraulic monitoring applications.
- Wired:4-20mA current loops and fieldbus protocols maintain dominance in safety-critical aerospace applications where deterministic latency requirements exclude wireless alternatives. FAA certification timelines extend product launch windows for sensor-equipped avionics systems.
- Wireless:Battery-powered and energy-harvesting radio modules reduce cabling infrastructure in brownfield retrofit scenarios.
- Analog:Pure voltage-output transducers persist in legacy process control installations requiring minimal firmware complexity.
Revenue concentrates in wired deployments for margin capture. IoT-enabled segments are expanding most quickly as edge AI inference engines embed directly into transducer housings.
End User:
Customer procurement patterns separate capital-intensive manufacturing from regulated sectors with extended validation protocols.
- Manufacturing:Discrete and process automation applications demand closed-loop control with sub-millisecond response times. China's MIIT GB standards and NMPA medical device rules add testing protocols for vendors targeting Asia-Pacific industrial clusters.
- Automotive:OEM assembly lines integrate multi-sensor arrays for predictive maintenance on hydraulic and pneumatic systems. EU AI Act compliance mandates force equipment upgrades in Germany's industrial corridor.
- Aerospace:Sensor-equipped systems face FAA and EASA dual certification requirements that compress vendor pools.
- Energy:Emissions monitoring mandates from EPA and EU Green Deal obligations drive continuous sensor deployment in Rotterdam and Houston refinery operations.
Procurement volume concentrates in manufacturing automation. Steepest expansion trajectory belongs to energy sector monitoring applications.
Deployment:
Architecture choice reflects trade-offs between data sovereignty, latency requirements, and lifecycle service integration.
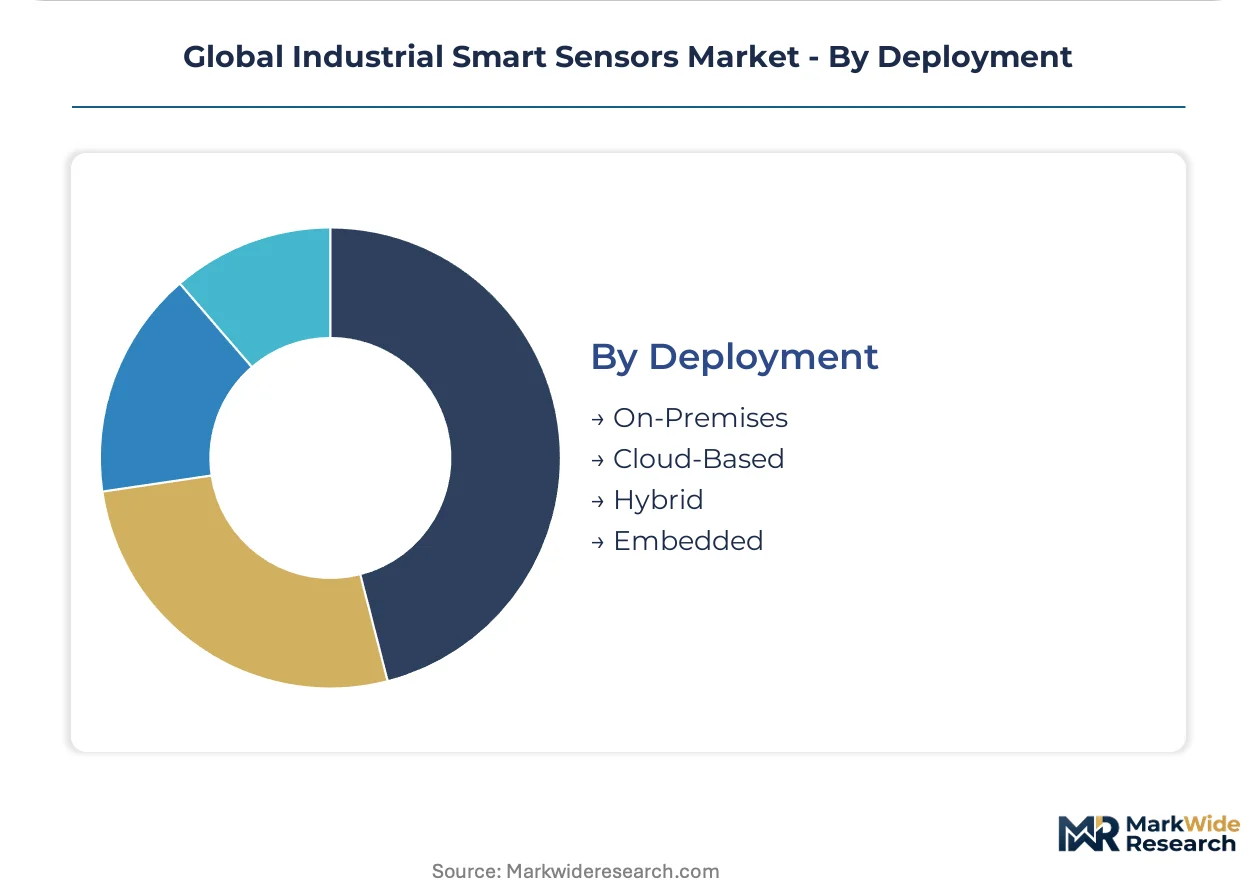
- Embedded:Microprocessor and communication interface integration within transducer housings enables deterministic real-time operating systems for closed-loop process control. FDA oversight of sensor-equipped medical manufacturing equipment elevates firmware architecture requirements.
- On-Premises:Local edge computing clusters process sensor streams without cloud egress, satisfying operational technology network cybersecurity standards under IEC 62443.
- Cloud-Based:Centralized analytics platforms support remote diagnostics and outcome-based maintenance contracts in heavy process industries.
- Hybrid:Partitioned architectures route safety-critical traffic locally while pushing optimization data to cloud analytics.
Installed base concentrates in embedded architectures. Hybrid deployments are gaining share fastest as digital twin convergence enables real-time sensor-to-simulation pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as vendors migrate manufacturing to jurisdictions with streamlined certification pathways. The EU AI Act's conformity costs are pushing assembly toward lower-compliance zones while design engineering remains concentrated in high-standard markets.
United States
EPA emissions monitoring mandates for energy facilities and FDA oversight of sensor-equipped medical manufacturing equipment are driving qualification volumes. Texas and Louisiana refinery clusters deploy continuous temperature sensing arrays under federal environmental rules. Houston operators negotiate outcome-based maintenance contracts that transfer operational risk to vendors with remote diagnostics platforms.
Germany
EU Machinery Directive conformity requirements and the EU AI Act are forcing OEM equipment upgrades in automotive manufacturing corridors. Stuttgart and Wolfsburg assembly lines integrate TSN-enabled pressure and temperature arrays at accelerated replacement rates. Bosch and Siemens anchor smart factory deployments that pull multi-sensor arrays into hydraulic monitoring applications.
China
MIIT GB standards and NMPA medical device rules add testing protocols for vendors targeting industrial clusters. Yangtze River Delta and Pearl River Delta manufacturing bases concentrate demand for closed-loop process control systems. Domestic vendors leverage captive MEMS fabrication to serve automotive and energy sector monitoring applications.
India
PLI scheme incentives for smart manufacturing are opening greenfield deployment opportunities in Gujarat and Tamil Nadu automotive clusters. Central Electricity Authority regulations and BIS standards shape product qualification requirements for domestic suppliers. Maharashtra and Karnataka industrial corridors attract sensor vendors seeking to bypass EU certification timelines while serving export markets.
Japan
METI industrial policy and JIS standards maintain stringent performance validation for factory automation equipment. Kanto and Kansai manufacturing belts demand sub-millisecond response times for discrete automation applications. Japanese semiconductor fabricators supply precision analog front-end components to sensor vendors across Asia-Pacific industrial clusters.
Global Industrial Smart Sensors Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue edge-AI firmware specialization and cybersecurity certification. The vendor base clusters around three archetypes: diversified electronics conglomerates with captive MEMS fabrication, analog semiconductor specialists with signal-conditioning integration, and industrial automation integrators with lifecycle service networks. Consolidation pressure concentrates among mid-scale vendors lacking either in-house semiconductor production or certified secure boot architectures. Competitive moves center on backward integration into MEMS foundry capacity and strategic partnerships for TSN protocol certification.
Within the diversified electronics tier, Texas Instruments Incorporated and Infineon Technologies AG exemplify archetypes built on analog front-end portfolios and in-house MEMS fabrication respectively. Analog Devices, Inc. occupies a position emphasizing signal-conditioning integration that reduces board-level complexity for OEM customers. These three anchors demonstrate how vendor strategies diverge based on whether value capture concentrates at the transducer, the conditioning layer, or the firmware stack.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| Analog Devices, Inc. |
| Robert Bosch GmbH |
| ABB |
| Honeywell International Inc. |
| TE Connectivity |
| STMicroelectronics |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Neodymium and dysprosium price volatility on the Shanghai Metal Market cascades through magnetostrictive position sensor manufacturing, compressing margins in mid-tier suppliers while premium vendors with captive rare earth processing pass through cost stability to automotive OEMs in Germany and Japan.
Pricing Analysis
Input-cost pass-through from silicon wafer foundry services and MEMS fabrication capacity anchors pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on IEC 62443 cybersecurity certification grade and after-sales service bundling for predictive maintenance platforms. Cost compression in standard-tier pressure transducers intensifies as Taiwan-based foundry concentration limits multi-source qualification options. Automotive OEMs in Stuttgart exhibit lowest price sensitivity due to EU AI Act compliance mandates, while Indian PLI-scheme beneficiaries in Gujarat drive hardest bargain negotiations for volume scale.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Siemens and Bosch in Germany's automotive corridor, while distribution partners serve fragmented process industries across Texas refinery clusters and Yangtze River Delta manufacturing bases. Geographic supply concentration centers on Taiwan for analog front-end chip fabrication, Germany for precision MEMS calibration equipment, and Japan for platinum RTD wire drawing. Raw material dependencies draw from rare earth magnet alloys, silicon carbide substrates, and fluorinated-gas-free sealing compounds. Single-source vulnerability in Taiwan-based foundry capacity for automotive-grade microcontrollers presents structural supply chain risk. Distribution runs through authorized technical distributors with field application engineering support for brownfield retrofit complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's Machinery Directive conformity deadlines compound demand for certified autonomous sensor networks, creating replacement cycle visibility for vendors with pre-validated firmware architectures.
For Market Incumbents: Deepen backward integration into MEMS foundry capacity to defend margin position against analog semiconductor specialists expanding signal-conditioning integration. Prioritize TSN protocol certification investment to maintain design-win momentum with Stuttgart and Wolfsburg automotive OEMs deploying unified factory floor architectures. Fortify lifecycle service networks in Rotterdam and Houston refinery corridors where outcome-based maintenance contracts concentrate procurement among full-stack vendors.
For New Entrants and Emerging Players: The premium-to-economy tier price gap in cybersecurity-certified firmware stacks presents white-space opportunity for edge-AI inference engine specialization targeting mid-scale manufacturing automation in India's Gujarat and Tamil Nadu clusters. Pursue white-label partnerships with established industrial automation integrators lacking in-house deterministic real-time operating systems capability. Target wireless retrofit applications in brownfield European facilities facing legacy 4-20mA infrastructure replacement pressure.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale vendors lack either captive MEMS fabrication or certified secure boot architectures against IEC 62443 standards. Long-term viability favors suppliers with dual competence in transducer physics and firmware cybersecurity across the 5-10 year operational technology convergence horizon. Acquisition target archetype: edge-computing firmware specialists with hospital system or refinery operator reference deployments. Signal to watch: FDA certification timeline compression for sensor-equipped medical manufacturing equipment as indicator of regulatory arbitrage opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| TSN Protocol Certification Investment | Enables unified factory floor architectures for Stuttgart automotive OEMs consolidating IT-OT networks. |
| Backward Integration into MEMS Fabrication | Secures captive supply of piezoresistive elements for pressure transducer cost stability. |
| Cybersecurity Firmware Stack Development | Addresses IEC 62443 compliance for operational technology network certification requirements. |
| Outcome-Based Service Platform Launch | Captures maintenance contract revenue from Rotterdam refinery operators transferring operational risk. |
| India PLI Scheme Manufacturing Footprint | Bypasses EU certification timelines while serving export markets from Maharashtra industrial corridor. |
Study Parameters
Direct dialogue with plant engineers at German automotive OEMs, maintenance directors in Texas refinery operations, OEM procurement teams for hydraulic systems, and aftermarket service heads for industrial automation equipment grounded qualitative findings. Secondary validation drew from EPA emissions monitoring filings, EU Machinery Directive conformity assessment databases, SEC 10-K disclosures from analog semiconductor suppliers, and MIIT GB standard publication records. Bottom-up and top-down triangulation reconciled sensor shipment volumes with end-use equipment production data.
Bottom-up modeling aggregated product-type and technology-segment volumes across deployment architectures, while top-down cross-checks validated aggregate market scale against industrial automation capex patterns over the projection horizon. Segmentation dimensions spanned transducer category, connectivity architecture, end-use industry, and regional regulatory cluster. CAGRs were derived from regression analysis of historical replacement cycle data and compliance-driven upgrade elasticity. Forecast inputs incorporated EU AI Act implementation pacing and rare earth commodity price trajectory assumptions.
Caveats apply where Taiwan foundry capacity constraints, FDA certification timeline extensions, or REACH substance restriction enforcement could materially shift the outlook. Forecasts reflect assumptions regarding regulatory harmonization pace and cybersecurity standard adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Wearable Temperature Sensors Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Global Rotation Laser Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
NB-IoT Smart Meter Market