
 Condition Monitoring Equipment Market | 2026-2036
Condition Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Condition Monitoring Equipment Market Analysis
Maintenance technician shortages across heavy industry is reorganizing how capital-intensive sectors deploy automated condition monitoring systems. SKF AB leverages its bearing diagnostics heritage to anchor predictive maintenance programs across European wind farms. Siemens AG competes through integrated digital twin platforms that merge vibration data with process control systems. Emerson Electric Co. specializes in ultrasonic leak detection portfolios that dominate downstream oil and gas inspection workflows.
Condition monitoring equipment encompasses sensors, analyzers, and software platforms that capture mechanical, thermal, and chemical indicators of asset degradation, typically sampling vibration at 10-20 kHz bandwidths or surface temperatures via infrared detectors with 0.1°C resolution to forestall unplanned downtime. Vibration analyzers retain the largest installed base across rotating machinery applications, though thermal cameras command premium pricing in electrical infrastructure inspection. Wireless sensors represent the fastest-expanding technology category as battery-powered nodes eliminate cabling costs in hazardous environments. Oil analysis tools occupy a mature niche where laboratory turnaround times limit growth against real-time alternatives.
OSHA machinery safety directives and EPA emissions enforcement in the United States compel continuous monitoring of compressor seals and pump bearings to prevent both mechanical failure and fugitive releases. The EU Machinery Directive and ATEX certification requirements shape product design standards for European suppliers seeking market access. Stakeholders must weigh capital deployment between edge-computing architectures and cloud-centric platforms as connectivity infrastructure evolves across industrial sites.
Market Dynamics
Wireless sensor networks are compressing deployment timelines for predictive maintenance programs, eliminating cabling infrastructure that previously consumed 40-60% of installation budgets in hazardous industrial environments.
Growth Catalysts
- OSHA machinery safety directives:US refineries and chemical plants now mandate continuous bearing temperature monitoring on critical rotating equipment, creating baseline demand for thermal and vibration sensor packages.
- Power generation infrastructure modernization:European utilities retrofit aging gas turbines and hydroelectric generators with integrated condition monitoring to extend asset life and defer capital replacement cycles.
- Edge computing architectures:Onboard signal processing in battery-powered wireless nodes reduces bandwidth requirements and enables real-time anomaly detection without cloud dependency.
Market Restraints
- Lithium battery supply concentration:Wireless sensor manufacturers face input cost volatility as cell production concentrates in China, exposing margins to export restriction risks and freight rate spikes.
- ATEX certification complexity:European suppliers endure 12-18 month approval timelines for intrinsically safe designs intended for Zone 0 hazardous atmospheres, delaying revenue recognition.
- Cloud platform switching costs:Industrial operators embedding analytics workflows into specific vendor ecosystems encounter friction migrating historical trend data to competing architectures.
Strategic Opportunities
- India manufacturing expansion:Automotive and steel producers under the PLI scheme deploy first-generation predictive maintenance systems as greenfield plants commission without legacy instrumentation baggage.
- EU Green Deal industrial decarbonization:Carbon-intensive sectors receive capital subsidies for efficiency upgrades that bundle condition monitoring with energy optimization software.
- Digital twin convergence:Vibration data streams merge with process historian databases to enable unified asset performance modeling across rotating machinery and control loops.
Industry Challenges
- Vibration analyst certification scarcity:ISO 18436-2 qualified personnel shortages force operators to rely on vendor-managed service contracts rather than in-house diagnostic capabilities.
- Legacy DCS integration friction:Brownfield installations require protocol gateways and custom middleware to bridge Modbus/Profibus sensor networks with modern analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condition Monitoring Equipment Market |
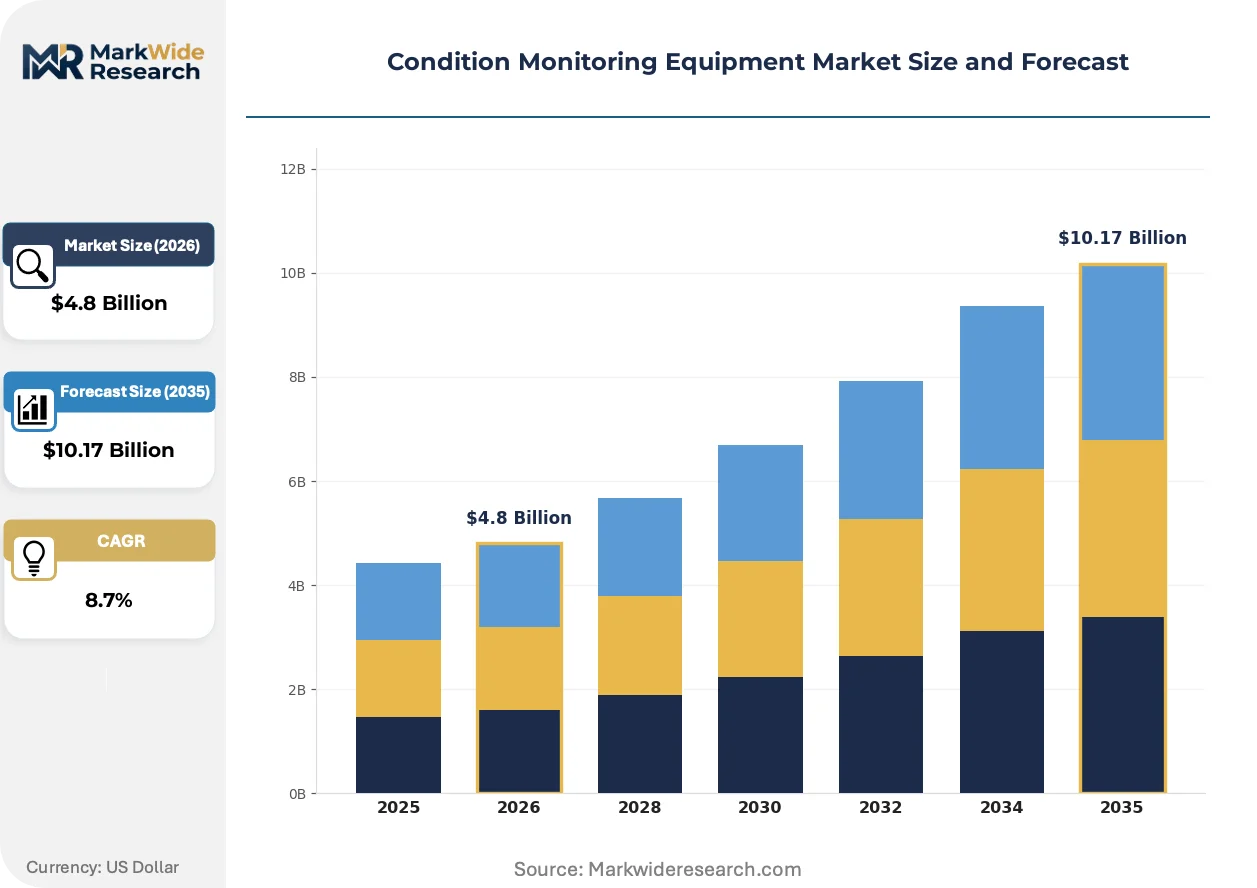
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Analyzers, Thermal Cameras, Ultrasonic Detectors, Oil Analysis Tools Technology: Wireless Sensors, Infrared Thermography, Predictive Analytics, Remote Monitoring End User: Manufacturing, Oil & Gas, Power Generation, Aerospace Installation: Fixed Systems, Portable Devices, Integrated Solutions, Cloud-based Platforms |
| Companies Covered | Emerson Electric Co., SKF AB, Honeywell International Inc., Siemens AG, ABB Ltd., General Electric, Rockwell Automation Inc., Schneider Electric SE, Schaeffler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condition Monitoring Equipment Market Emerging Trajectories
Artificial intelligence inference at the sensor edge is collapsing the latency between anomaly detection and maintenance dispatch, compressing response windows from hours to minutes in critical rotating machinery applications.
MEMS accelerometers with integrated FFT processing is supplanting piezoelectric sensors in mid-criticality pump and fan applications. Water treatment facilities and HVAC contractors adopt these lower-cost nodes for condition-based maintenance programs previously uneconomical at conventional price points. The technology is supplanting route-based manual data collection, eliminating technician walkdowns and enabling continuous monitoring coverage across dispersed asset populations.
EPA emissions enforcement under the Clean Air Act now treats compressor seal monitoring as preventive compliance infrastructure rather than optional reliability investment. Downstream oil and gas operators face penalties for fugitive releases detectable through ultrasonic acoustic sensors paired with bearing temperature trending. Ultrasonic leak detection portfolios dominate inspection workflows in Texas and Louisiana refining corridors where regulatory scrutiny intensifies.
Power utilities now unbundle hardware procurement from analytics subscriptions, treating sensor networks as capital equipment while purchasing predictive insights through annual software licenses. This bifurcation fragments vendor relationships and creates openings for specialized analytics providers without manufacturing heritage. Germany and Japan exhibit the most pronounced unbundling as large industrial buyers consolidate sensor purchasing through framework agreements while selecting best-of-breed cloud platforms independently.
Condition Monitoring Equipment Market Segmentation
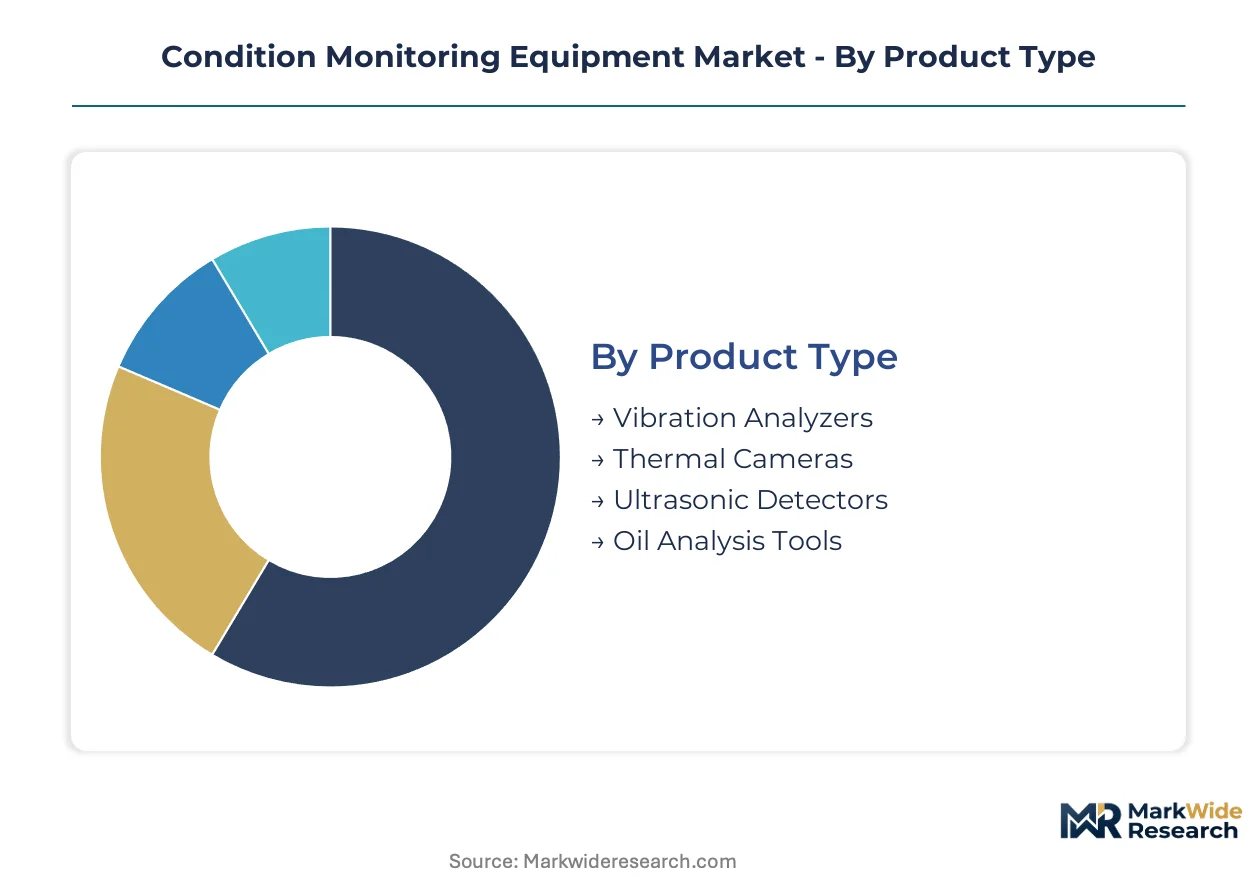
Equipment buyers fragment procurement decisions across hardware specifications, connectivity architectures, and deployment models. Understanding substitution pressures between wired and wireless configurations, between fixed and portable form factors, shapes competitive positioning for component suppliers and system integrators alike.
Product Type:
Wireless sensors and integrated analytics platforms are displacing traditional route-based data collection methods, compressing margins for standalone hardware categories that lack embedded intelligence.
- Vibration Analyzers:Piezoelectric and MEMS-based units sample mechanical oscillations at 10-20 kHz bandwidths to detect bearing wear and shaft misalignment. German automotive production lines deploy these across CNC machining centers and robotic assembly stations under ISO 18436-2 diagnostic protocols. Vibration analyzers anchor the volume base while thermal cameras gain share at the steepest rate.
- Thermal Cameras:Infrared detectors with 0.1°C resolution surface temperature differentials identify electrical hotspotting in switchgear and motor windings. US utilities under FERC reliability mandates deploy handheld and fixed-mount thermal imagers across substation infrastructure, with premium pricing sustained by ATEX certification requirements for hazardous zone deployment.
- Ultrasonic Detectors:Acoustic emission sensors operating above 20 kHz detect compressor seal leaks and valve bypass in downstream oil and gas workflows. EPA Clean Air Act enforcement treats these as preventive compliance infrastructure in Texas and Louisiana refining corridors.
- Oil Analysis Tools:Laboratory-based spectrometry and particle counting systems characterize lubricant degradation and wear metal concentration. Turnaround times of 24-72 hours limit growth against real-time alternatives in continuous process industries.
Vibration analyzers dominate installed base economics while thermal imaging commands the steepest price escalation trajectory among hardware categories.
Technology:
Cost tier differentiation separates capital-intensive edge-computing nodes from subscription-dependent cloud architectures, with procurement patterns diverging by operator IT maturity and connectivity infrastructure.
- Wireless Sensors:Battery-powered nodes with integrated FFT processing eliminate cabling costs that previously consumed 40-60% of installation budgets in hazardous environments. European wind farm operators under EU Green Deal decarbonization subsidies deploy mesh networks across offshore turbine populations, though lithium cell supply concentration in China exposes margins to export restriction risks.
- Infrared Thermography:Non-contact temperature measurement systems span handheld diagnostic tools and fixed-mount continuous monitoring arrays. Japanese steel producers integrate thermal imaging into hot rolling mill predictive maintenance under METI energy efficiency directives.
- Predictive Analytics:Machine learning platforms processing multi-sensor data streams generate remaining useful life estimates and maintenance dispatch recommendations. Power utilities increasingly unbundle analytics subscriptions from hardware procurement, fragmenting vendor relationships.
- Remote Monitoring:Cloud-centric architectures enabling centralized diagnostics across dispersed asset populations. Indian manufacturing expansion under PLI scheme incentives favors remote monitoring for greenfield plants without legacy instrumentation baggage.
Wireless sensors expand most quickly as battery chemistry improvements extend node lifecycles, while oil analysis confronts substitution pressure from real-time alternatives.
End User:
Application-specific regulatory intensity and asset criticality determine willingness to pay for continuous versus periodic monitoring modalities.
- Manufacturing:Automotive and machinery producers deploy integrated vibration monitoring across production lines to prevent unplanned downtime. German OEMs anchor regional demand concentration with framework agreements consolidating sensor purchasing.
- Oil & Gas:Downstream operators face EPA emissions enforcement treating compressor seal monitoring as compliance infrastructure rather than optional reliability investment. Ultrasonic leak detection dominates inspection workflows in US Gulf Coast refining.
- Power Generation:European utilities retrofit aging gas turbines and hydroelectric generators with integrated condition monitoring to extend asset life and defer capital replacement cycles. FERC reliability mandates shape US procurement patterns.
- Aerospace:MRO providers and engine OEMs deploy high-frequency vibration analysis and oil debris monitoring for flight-critical rotating components. Certification requirements under FAA and EASA directives sustain premium pricing tiers.
Power generation commands the largest project scale while manufacturing delivers the highest unit volume through distributed machine tool populations.
Installation:
Customer type stratification separates asset owner-operators from third-party service providers, with procurement authority shifting toward IT departments as analytics unbundling accelerates.
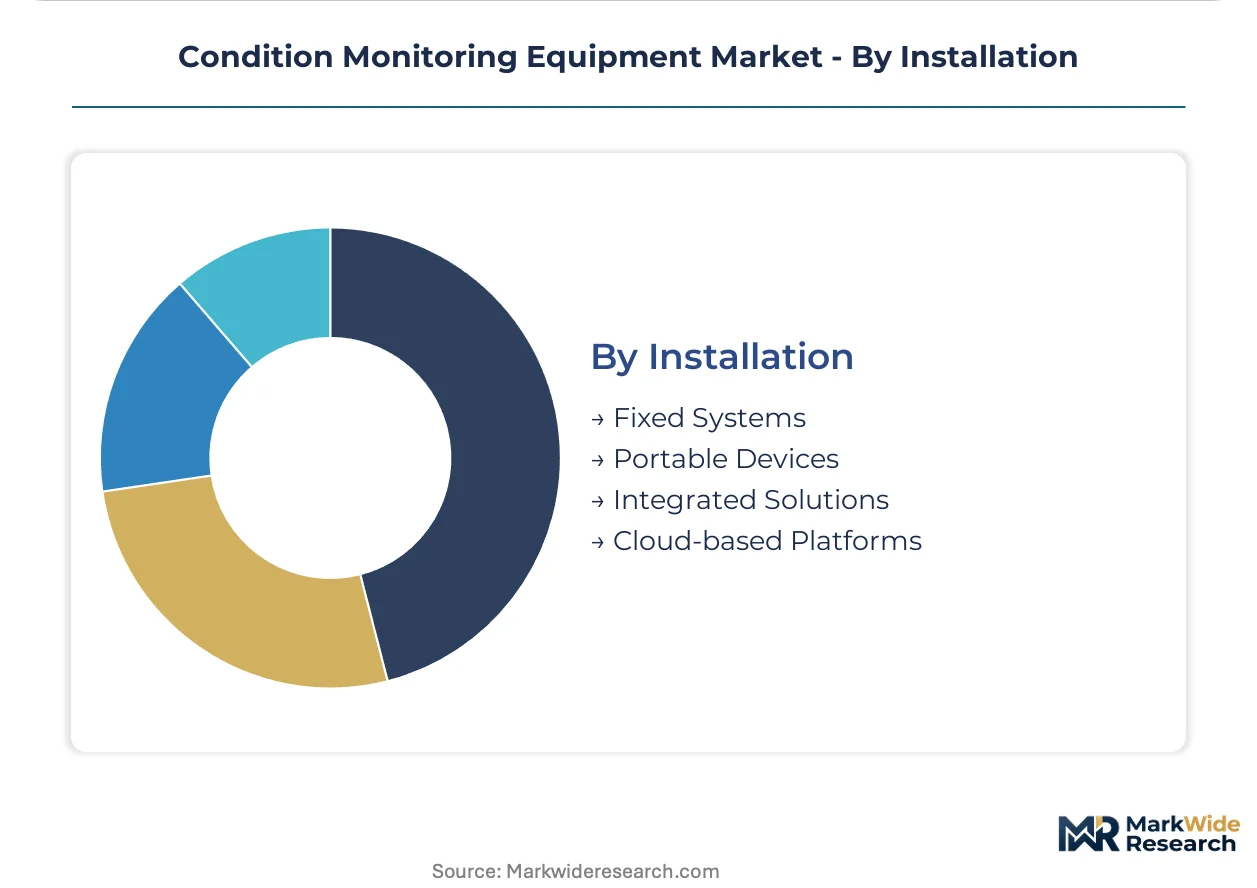
- Fixed Systems:Permanently mounted sensor arrays with hardwired power and data connectivity deliver highest sampling fidelity for critical rotating machinery. Brownfield installations require protocol gateways to bridge Modbus/Profibus networks with modern analytics platforms.
- Portable Devices:Handheld vibration analyzers and thermal cameras enable route-based periodic inspection programs. Technician certification scarcity under ISO 18436-2 standards forces reliance on vendor-managed service contracts.
- Integrated Solutions:Combined hardware-software deployments with unified asset performance modeling across rotating machinery and control loops. Digital twin convergence merges vibration data with process historian databases.
- Cloud-based Platforms:Software-as-a-service analytics purchasing decoupled from sensor hardware procurement. Germany and Japan exhibit the most pronounced unbundling as large industrial buyers select best-of-breed cloud platforms independently.
Fixed systems retain revenue concentration in hazardous environments while cloud-based platforms climb the fastest as procurement authority shifts toward enterprise IT functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs command 15-20% pricing premiums over Indian steel producers for equivalent vibration monitoring hardware, reflecting divergent regulatory enforcement intensity and labor cost structures across manufacturing clusters.
United States
OSHA machinery safety directives and EPA emissions enforcement under the Clean Air Act mandate continuous bearing temperature monitoring on critical rotating equipment in refineries and chemical plants. FERC reliability standards shape procurement patterns across power generation infrastructure. Texas and Louisiana refining corridors concentrate ultrasonic leak detection deployments as regulatory scrutiny intensifies.
Germany
EU Machinery Directive and ATEX certification requirements shape product design standards for suppliers seeking European market access. EU Green Deal industrial decarbonization subsidies channel capital toward efficiency upgrades bundling condition monitoring with energy optimization software. Automotive production lines across Baden-Württemberg deploy integrated vibration monitoring under ISO 18436-2 diagnostic protocols.
China
Dual carbon goals and MIIT industrial efficiency mandates accelerate predictive maintenance adoption across steel and cement sectors. GB standards and SAMR certification requirements govern product compliance for domestic and export markets. Yangtze River Delta manufacturing clusters drive wireless sensor network deployments as greenfield plants commission without legacy instrumentation.
India
PLI scheme incentives for automotive and steel producers drive first-generation predictive maintenance system deployments in greenfield facilities. CEA grid reliability directives encourage condition monitoring retrofits across thermal and renewable power assets. Maharashtra and Gujarat industrial corridors anchor regional demand concentration for vibration analyzers and thermal imaging systems.
Japan
METI energy efficiency directives integrate thermal imaging into hot rolling mill predictive maintenance across steel producers. JIS standards and PMDA-equivalent industrial safety regulations govern equipment certification requirements. Kansai and Chubu manufacturing regions exhibit pronounced procurement unbundling as large buyers consolidate sensor purchasing through framework agreements.
Condition Monitoring Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated industrial conglomerates commanding premium positioning through digital twin platforms while specialized sensor manufacturers compete on deployment economics. The market structure consolidates around three tiers: diversified automation giants with full-stack portfolios, bearing and rotating machinery specialists leveraging diagnostic heritage, and emerging wireless sensor pure-plays attacking mid-criticality applications. Two dominant competitive moves define current dynamics: backward integration into MEMS accelerometer fabrication to capture component margins, and strategic partnerships between hardware manufacturers and cloud analytics providers to counter procurement unbundling.
Among European-based industrial specialists, SKF AB and Schaeffler Group occupy positions within the rotating machinery heritage tier, anchoring predictive maintenance programs through bearing diagnostics expertise. Siemens AG exemplifies the diversified automation archetype, competing through integrated digital platforms that merge equipment data with process control systems. Emerson Electric Co. sits within the instrumentation-focused tier, with geographic concentration in North American energy and chemical markets.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| SKF AB |
| Honeywell International Inc. |
| Siemens AG |
| ABB Ltd. |
| General Electric |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Schaeffler Group |
| Others |
Supply Flow & Price Mechanics
MEMS accelerometer substitution for piezoelectric sensors in mid-criticality applications simultaneously redistributes manufacturing activity toward East Asian semiconductor foundries and compresses unit economics at the standard tier, forcing legacy suppliers to defend margin through ATEX-certified premium positioning.
Pricing Analysis
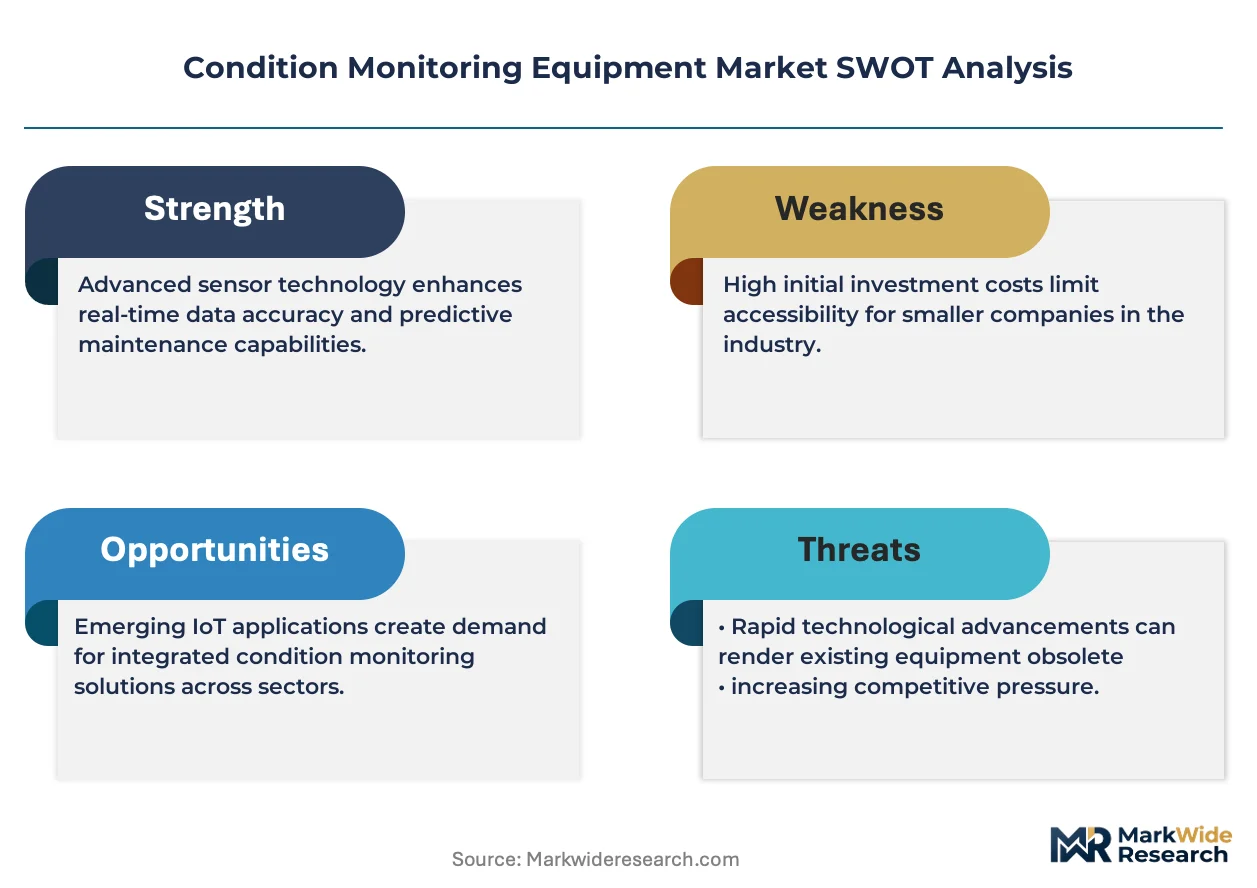
Configured-to-order pricing for ATEX-certified wireless nodes commands spreads of 40-60% above standard SKUs lacking hazardous-zone ratings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because Chinese MEMS producers are flooding mid-criticality pump and fan applications with sub-$50 nodes. Automotive OEMs in Germany exhibit least price sensitivity due to unplanned downtime costs, while Indian steel producers under PLI scheme constraints drive hardest bargaining on greenfield sensor packages.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability crunches at Rotterdam and Hamburg are extending inbound lead times for lithium cells and MEMS wafers. Component sourcing draws from China for battery cells, Taiwan for MEMS foundry capacity, and Germany for precision piezoelectric ceramics. Single-source vulnerability concentrates in Chinese lithium refining, exposing margins to export permit delays. Distribution runs through industrial automation distributors and direct OEM framework agreements, with cloud analytics subscriptions bypassing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where hardware-software unbundling fragments vendor relationships and rewards interoperability investments that bridge sensor networks with multi-cloud analytics environments.
For Market Incumbents: Secure captive supply of MEMS accelerometer fabrication capacity to defend component margins against Chinese pure-plays. Deepen certification investment in ATEX and SIL-rated designs to maintain premium positioning as wireless commoditization accelerates through the standard tier.
For New Entrants and Emerging Players: Anchor in Indian manufacturing expansion under PLI scheme incentives, where greenfield steel and automotive plants lack legacy instrumentation and procurement decisions remain unconsolidated. Lead with battery-life-extended wireless nodes priced below incumbent route-based alternatives to capture first-generation predictive maintenance budgets.
For Investors and Strategic Acquirers: EU Green Deal industrial decarbonization subsidies reshapes the acquisition landscape by channeling capital toward efficiency-upgrade bundling opportunities. Long-term viability hinges on software recurring revenue attachment rates rather than hardware shipment volumes. Watch for cloud platform switching cost thresholds as the inflection signal separating consolidatable specialists from stranded hardware vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captures component margins as Chinese foundries drive price erosion through the standard tier. |
| Cloud Analytics Partnership | Counters procurement unbundling by bundling predictive insights with sensor hardware subscriptions. |
| ATEX Certification Investment | Preserves premium pricing power in European oil and gas and chemical plant deployments. |
| India Greenfield Market Entry | Exploits PLI scheme infrastructure buildout before incumbent framework agreements consolidate. |
| Digital Twin Platform Integration | Merges vibration data with Siemens and ABB process historians to anchor enterprise-wide contracts. |
Methodological Framework
A spread of perspectives from maintenance directors at European utilities, plant engineers at German automotive OEMs, procurement leads at Indian steel producers, and aftermarket service heads at bearing manufacturers converged on the working assumptions. Primary interview insights combined with secondary validation against SEC 10-K filings, EU Machinery Directive implementation reports, and MIIT industrial efficiency disclosures. Bottom-up unit economics triangulated against top-down capital expenditure tracking across power generation and manufacturing verticals.
Segmentation dimensions modeled span product type, connectivity architecture, installation mode, and end-use industry intensity across the projection horizon. CAGRs derived from installed base replacement cycles, wireless sensor penetration curves, and analytics subscription attachment rates. Industry-specific inputs include ISO 18436-2 certification pipeline constraints and lithium cell supply concentration risk assessments.
Decision-makers should treat outputs as directional under assumptions of continued OSHA machinery safety enforcement and EU Green Deal subsidy continuity; material deviation in regulatory intensity or battery supply geography would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Absolute Pressure Sensor Market