
 Insulation Monitoring Devices (IMD) Market | 2026-2036
Insulation Monitoring Devices (IMD) Market Size, Share, and Industry Trends Forecast 2026-2036
Insulation Monitoring Devices (IMD) Market Intelligence
The EU Green Deal's electrification targets are recalibrating industrial safety procurement across European manufacturing. ABB Ltd. leverages its installed base in process automation to anchor IMD sales within chemical and pharmaceutical plants. Siemens AG dominates rail and hospital infrastructure through integrated power management platforms that bundle insulation monitoring with breaker control systems.
Insulation Monitoring Devices detect degradation in electrical insulation resistance between live conductors and protective earth, typically measuring from kilohms to gigaohms using DC or AC injection methods to prevent arc faults and equipment damage. Fixed IMD installations sustain the largest revenue pool as permanent integration into switchgear and distribution boards creates recurring calibration and replacement cycles. Capacitive technology leads measurement accuracy for variable-frequency drive applications, while pulse voltage methods specialize in detecting intermittent faults across long cable runs in renewable energy arrays.
The IEC 61543 standard governs device performance requirements in Europe, while OSHA electrical safety regulations and NFPA 70E mandate periodic insulation verification in US industrial workplaces. China's GB standards and NMPA-equivalent electrical safety certifications shape product entry requirements for Asian manufacturing equipment suppliers. Stakeholders must monitor evolving data center tier certification criteria from Uptime Institute and TIA-942 that increasingly specify continuous insulation monitoring as a condition of critical facility designation.
Market Dynamics
Hyperscale data center construction is compressing procurement cycles for Insulation Monitoring Devices as operators race to meet IEC 61543 compliance before facility commissioning deadlines, forcing IMD suppliers to accelerate calibration service deployment.
Growth Catalysts
- EU Green Deal electrification mandates:Industrial manufacturing facilities across Germany and France must upgrade electrical safety systems, creating mandatory replacement demand for legacy insulation monitoring infrastructure.
- Data center tier certification criteria:Uptime Institute and TIA-942 standards now specify continuous insulation monitoring as a condition for critical facility designation, pulling IMD procurement forward in construction timelines.
- Variable-frequency drive proliferation:Capacitive measurement technology adoption accelerates in chemical processing and pharmaceutical manufacturing where motor control precision demands superior fault detection accuracy.
Market Restraints
- Semiconductor component concentration:Specialized analog-to-digital converters for high-impedance measurement concentrate in Taiwanese and South Korean foundries, exposing IMD manufacturers to single-source supply risk.
- Calibration infrastructure gaps:Third-party metrology laboratories capable of certifying gigaohm-range accuracy remain scarce outside Germany, Japan, and the United States, extending replacement cycle timelines.
- Passive insulation testing substitution:Handheld megohmmeters retain cost advantage in non-critical commercial installations, limiting IMD penetration in tier-2 and tier-3 facility upgrades.
Strategic Opportunities
- India manufacturing corridor expansion:BIS electrical safety certification requirements for industrial equipment imports create first-mover advantage for IMD suppliers establishing local calibration partnerships.
- Renewable energy array monitoring:Pulse voltage detection methods specialized for long cable fault identification align with offshore wind and utility-scale solar construction pipelines.
- Digital twin convergence:Integration of IMD data streams with predictive maintenance platforms enables condition-based replacement contracts, shifting revenue from hardware to recurring analytics services.
Industry Challenges
- Embedded systems firmware specialization:Shortage of engineers proficient in both high-impedance analog circuit design and IEC 62304 medical device software standards constrains product development velocity.
- Multi-jurisdiction certification parallelism:Simultaneous pursuit of CE marking, UL listing, and China Compulsory Certification extends product launch timelines by twelve to eighteen months.
- Legacy switchgear integration complexity:Retrofit installations in brownfield chemical plants require custom mounting adaptations, eroding margin on smaller contract values.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulation Monitoring Devices (IMD) Market |
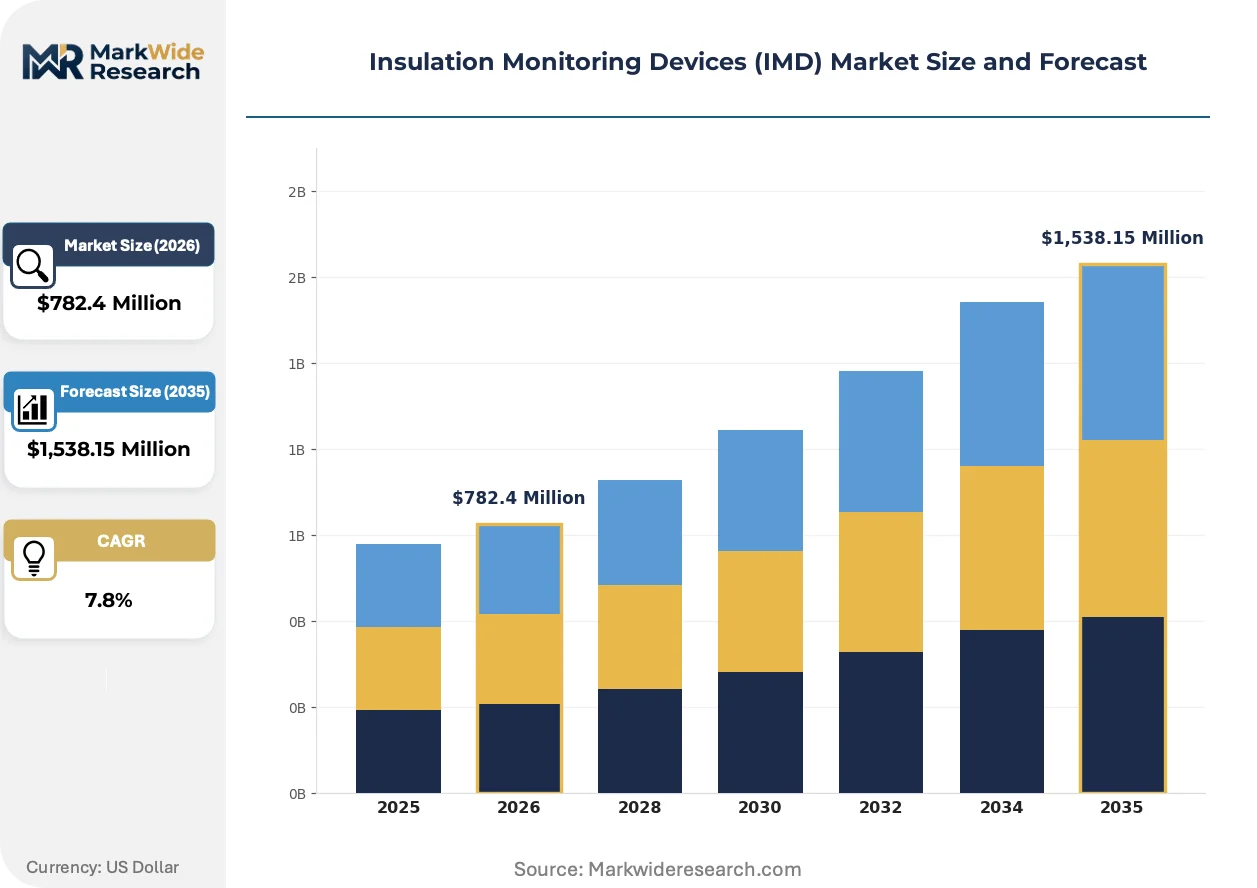
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,538.15 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable IMD, Fixed IMD, Busbar IMD, Modular IMD Technology: Capacitive, Resistive, Frequency Response, Pulse Voltage, Zero-Sequence Voltage Application: Renewable Energy, Data Centers, Manufacturing Plants, Public Infrastructure, Commercial Complexes End User: Electrical Contractors, Facility Managers, Machine Builders, Power Utilities |
| Companies Covered | Eaton Corporation plc, Fluke Corporation, ABB Ltd., Hioki E.E. Corporation, Megger Group Limited, Schneider Electric SE, Bender GmbH & Co. KG, Littelfuse Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulation Monitoring Devices (IMD) Market Strategic Shifts & Innovations
Measurement methodology diversification and regulatory precision requirements are fragmenting the IMD technology landscape. Suppliers now compete on detection speed and integration depth rather than base accuracy specifications alone.
Capacitive coupling technology is expanding into variable-frequency drive applications where traditional DC injection methods generate false positives from motor capacitance. Automotive battery pack manufacturers in South Korea and Germany now specify capacitive IMD architectures for production line testing equipment. This expansion is compressing the addressable market for legacy resistive measurement systems in industrial motor control segments.
OSHA electrical safety enforcement memoranda issued in 2023 tightened periodic verification requirements for industrial workplaces above 600 volts. Facility safety managers now face citation exposure for reliance on annual manual testing rather than continuous monitoring. Chemical processing plants in Texas and Louisiana are responding fastest, embedding IMD arrays into MCC bucket retrofits ahead of scheduled inspections.
Buyer consolidation among hyperscale data center operators has collapsed vendor qualification lists to three approved suppliers per region. Procurement teams now bundle IMD procurement with medium-voltage switchgear contracts, displacing standalone device distributors. This concentration is most visible in Northern Virginia and Frankfurt where Amazon Web Services, Microsoft, and Google account for over sixty percent of new facility electrical infrastructure spending.
Insulation Monitoring Devices (IMD) Market Segmentation
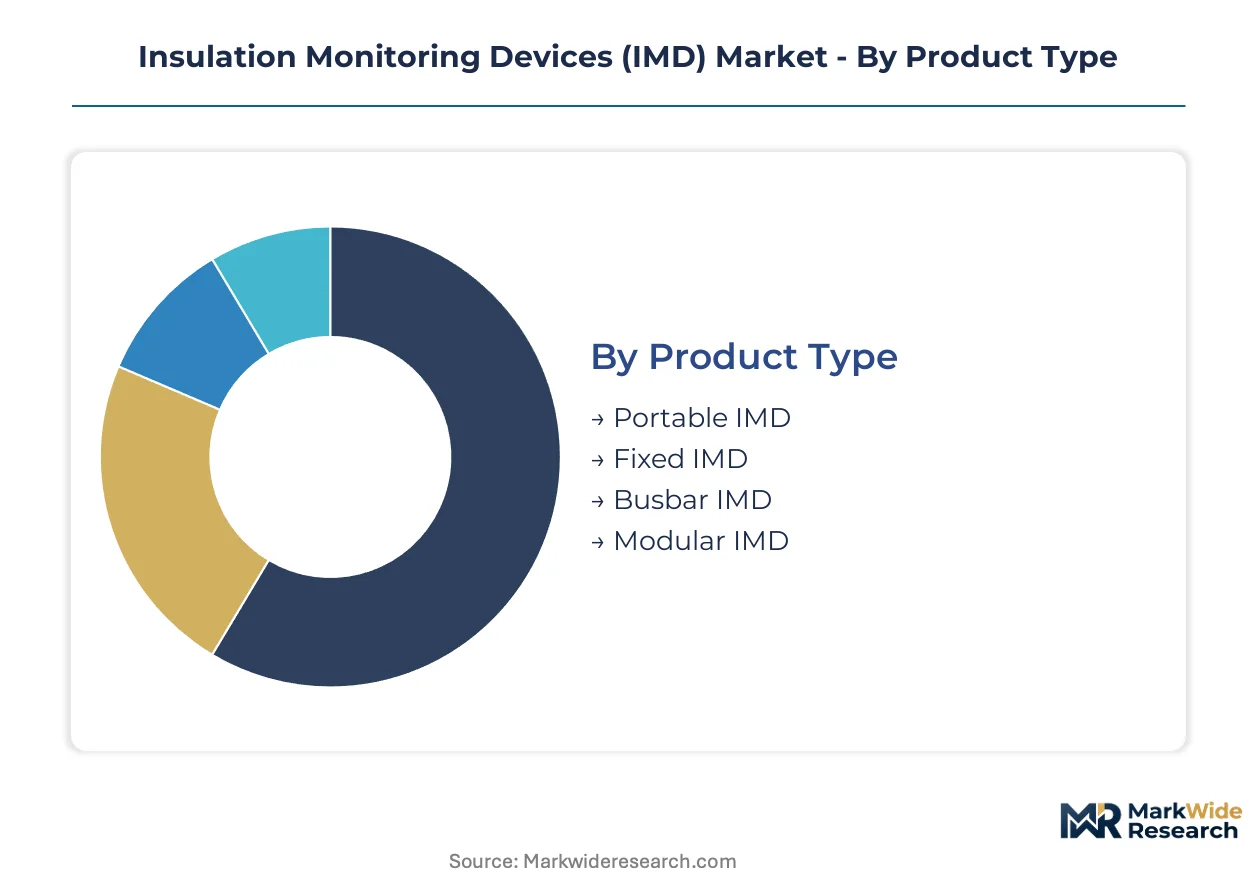
Insulation Monitoring Devices fragment across measurement methodologies, installation permanence, and facility criticality tiers. Procurement patterns diverge sharply between continuous-mission environments demanding fixed installations and maintenance crews requiring portable verification tools.
Product Type:
Physical form factor determines integration depth, calibration cycles, and replacement revenue predictability in electrical infrastructure.
- Fixed IMD:Permanent installation into switchgear and distribution boards creates recurring calibration contracts and hardware replacement cycles. Data center operators in Northern Virginia and Frankfurt specify these for IEC 61543 compliance ahead of Uptime Institute tier certification deadlines.
- Portable IMD:Handheld units serve maintenance crews performing spot verification across distributed asset bases. Electrical contractors in Texas and Louisiana deploy these for OSHA-driven MCC bucket retrofits ahead of enforcement inspections.
- Busbar IMD:Specialized form factor for high-current distribution assemblies in manufacturing plants.
- Modular IMD:Scalable architecture allowing incremental channel expansion in brownfield chemical facilities.
Mature deployment sits with Fixed IMD. Newer deployment is concentrated in Modular IMD.
Technology:
Measurement methodology selection pivots on load characteristics, fault signature requirements, and electromagnetic interference tolerance.
- Capacitive:Superior accuracy for variable-frequency drive applications where motor capacitance generates false positives under DC injection. Chemical processing and pharmaceutical manufacturing in Germany specify this architecture for production line precision.
- Pulse Voltage:Specialized detection of intermittent faults across long cable runs in offshore wind and utility-scale solar arrays. Renewable developers in the North Sea and Chinese coastal provinces drive specification.
- Resistive:Legacy DC injection approach for standard industrial motor control without VFD complexity.
- Frequency Response:Broadband impedance characterization for mixed-load distribution networks.
- Zero-Sequence Voltage:Earth fault detection in compensated neutral networks common in European utility practice.
Capacitive technology commands premium positioning in precision manufacturing. Pulse Voltage methods are expanding most quickly in renewable construction pipelines.
Application:
Facility criticality and regulatory exposure intensity shape procurement specifications and vendor qualification rigor.
- Data Centers:Continuous monitoring mandated by Uptime Institute and TIA-942 tier certification criteria. Hyperscale operators in Ashburn and Frankfurt compress procurement cycles to meet commissioning deadlines.
- Renewable Energy:Long cable fault detection requirements in offshore wind and solar arrays. Developers prioritize pulse voltage methods for array-wide insulation surveillance.
- Manufacturing Plants:VFD proliferation in chemical and pharmaceutical processing drives capacitive technology specification.
- Public Infrastructure:Hospital and rail power systems requiring integrated breaker control per Siemens platform architectures.
- Commercial Complexes:Cost-sensitive tier-2 and tier-3 facilities where handheld megohmmeters compete on upfront expenditure.
Data center application concentrates vendor consolidation. Renewable energy application shows steepest expansion trajectory.
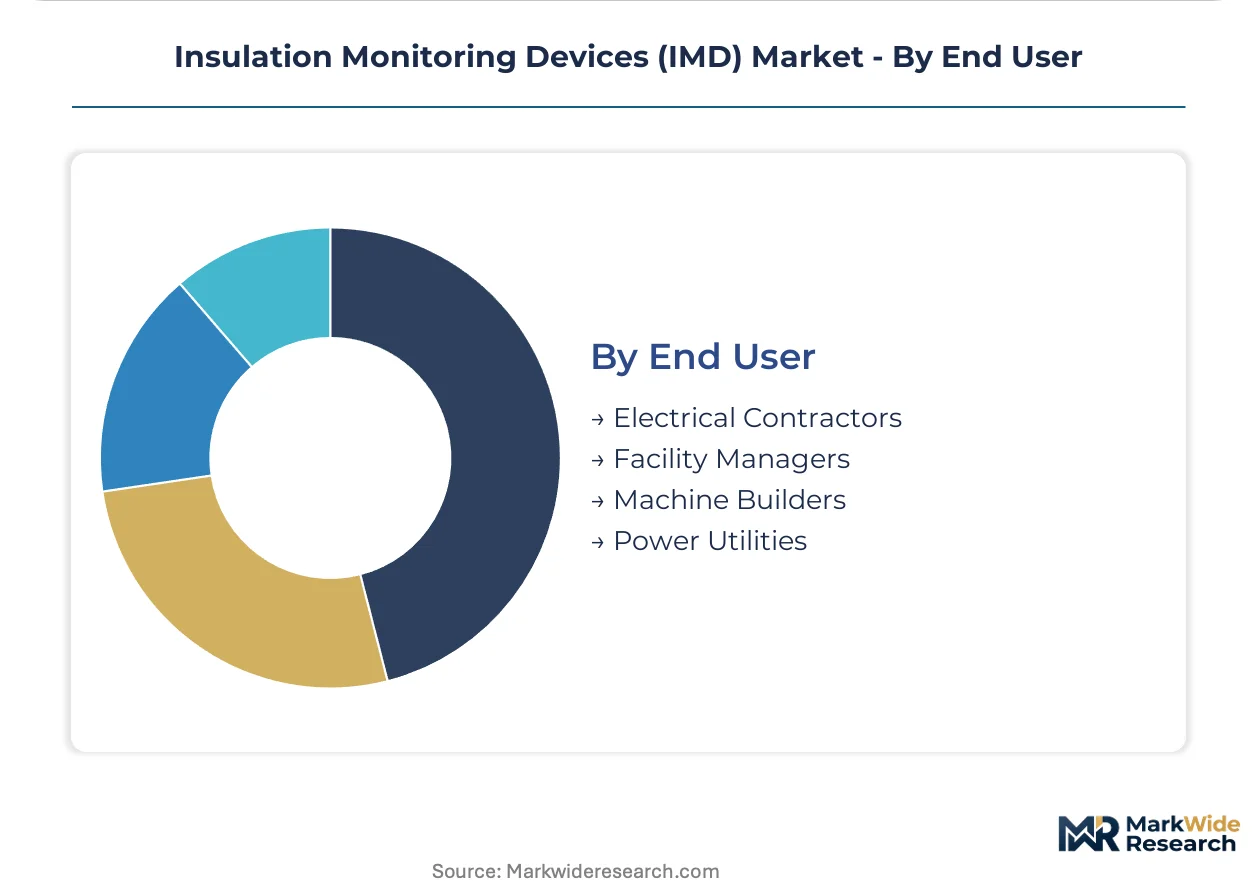
End User:
Purchasing authority and technical specification control vary across installation, operation, and equipment manufacturing contexts.
- Power Utilities:Grid-scale insulation monitoring for distribution network reliability. European utilities specify zero-sequence voltage methods for compensated neutral systems.
- Machine Builders:OEM integration of IMD into production equipment for BIS certification compliance in Indian manufacturing corridor expansion.
- Facility Managers:Operational responsibility for continuous monitoring in commissioned critical infrastructure.
- Electrical Contractors:Installation-phase procurement bundled with medium-voltage switchgear contracts in hyperscale construction.
Power utilities anchor long-term service contracts. Machine builders represent emerging specification influence in export manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's hyperscale data center corridor drives the largest concentrated procurement of fixed Insulation Monitoring Devices worldwide, with Frankfurt and Ashburn forming the twin poles of IEC 61543 compliance demand.
United States
OSHA's 2023 electrical safety enforcement memoranda tightened verification requirements for industrial workplaces above 600 volts. Chemical processing plants in Texas and Louisiana embed IMD arrays into MCC bucket retrofits ahead of scheduled inspections. Northern Virginia's data center construction pipeline compresses procurement cycles as operators race to meet Uptime Institute tier certification deadlines.
Germany
EU Green Deal electrification mandates force industrial manufacturing facilities to upgrade electrical safety systems, creating mandatory replacement demand for legacy insulation monitoring infrastructure. IEC 61543 compliance requirements shape product specifications across chemical and pharmaceutical plants. Siemens AG anchors integrated power management platforms in rail and hospital infrastructure throughout Bavaria and North Rhine-Westphalia.
China
GB standards and NMPA-equivalent electrical safety certifications govern product entry requirements for manufacturing equipment suppliers. Hyperscale facility construction accelerates in coastal provinces where pulse voltage methods gain specification for utility-scale solar arrays. Yangtze River Delta data center operators pull IMD procurement forward in construction timelines to meet commissioning deadlines.
India
BIS electrical safety certification requirements for industrial equipment imports create first-mover advantage for suppliers establishing local calibration partnerships. Machine builders in Maharashtra and Gujarat integrate IMD into production equipment for export manufacturing compliance. The Delhi-Mumbai Industrial Corridor expansion drives specification influence among electrical contractors bundling procurement with medium-voltage switchgear contracts.
United Kingdom
CE marking alignment post-Brexit maintains IEC 61543 performance requirements for device certification in critical infrastructure. Data center operators in Slough and London Docklands specify continuous insulation monitoring as a condition of tier designation. Offshore wind developers in the North Sea prioritize pulse voltage detection methods for long cable fault identification across renewable arrays.
Insulation Monitoring Devices (IMD) Market Key Industry Players
The competitive structure tilts toward diversified electrical infrastructure conglomerates with installed base advantages in process automation and power distribution. Market concentration intensifies as hyperscale data center operators collapse vendor qualification lists to three approved suppliers per region. Two strategic archetypes dominate: integrated platform providers bundling IMD with breaker control systems, and specialized measurement technology firms competing on detection speed and calibration service density. M&A activity targets calibration infrastructure capabilities, while geographic expansion focuses on establishing metrology partnerships in underserved jurisdictions.
Among Germany-based specialists, Bender GmbH & Co. KG exemplifies the precision measurement archetype with deep calibration service integration. Eaton Corporation plc and Siemens AG occupy positions as diversified infrastructure platforms leveraging switchgear installed bases to anchor IMD procurement within bundled electrical contracts. These three represent the dominant competitive vectors: specialized accuracy, integrated platforms, and service-network density.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Fluke Corporation |
| ABB Ltd. |
| Hioki E.E. Corporation |
| Megger Group Limited |
| Schneider Electric SE |
| Bender GmbH & Co. KG |
| Littelfuse Inc. |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between IEC 61543-compliant fixed installations and handheld verification tools manifests in both pricing power and component sourcing strategies. Premium-tier fixed IMDs command sustained margins through bundled calibration service contracts, while economy-tier portable units face cost compression from megohmmeter substitution in non-critical commercial deployments.
Pricing Analysis
Uptime certification-linked pricing anchors value capture for data center operators seeking tier designation compliance. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61543-certified fixed installations from modular brownfield retrofits and handheld spot-verification units. Price differentiation hinges on calibration service density and gigaohm-range accuracy certification. Margins are tightening in the portable segment due to passive insulation testing substitution. Facility managers in tier-2 commercial complexes exhibit highest price sensitivity, while hyperscale data center procurement teams prioritize certification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized analog-to-digital converters for high-impedance measurement concentrated in Taiwanese and South Korean foundries. Component sourcing draws from Germany for precision measurement assemblies, China for enclosure and passive electronics, and Japan for metrology-grade reference components. Supply chain risk centers on semiconductor fabrication concentration exposing IMD manufacturers to foundry allocation constraints. Distribution runs through electrical contractors bundling procurement with medium-voltage switchgear contracts in hyperscale construction, supplemented by specialized industrial distributors serving process automation retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IMD market occupies a technology-transition phase as capacitive measurement architectures displace legacy DC injection methods in variable-frequency drive applications. Pulse voltage detection methods are simultaneously capturing specification share in renewable energy array monitoring.
For Market Incumbents: Extend calibration service networks into underserved jurisdictions to defend recurring revenue streams against emerging entrants with hardware-only offerings. Deepen backward integration into high-impedance ADC sourcing to mitigate Taiwanese foundry concentration risk. Prioritize firmware development capacity addressing IEC 62304 medical device software standards to accelerate product launch velocity.
For New Entrants and Emerging Players: The mid-tier price-point gap between Siemens-ABB bundled platforms and handheld megohmmeters creates white-space opportunity for modular IMD architectures targeting brownfield chemical plant retrofits. India manufacturing corridor expansion offers most penetrable geography given BIS certification requirements and scarce local calibration infrastructure. Pursue partnership-based go-to-market models with electrical contractors bundling IMD procurement with switchgear installation contracts.
For Investors and Strategic Acquirers: Re-rating potential sits with calibration infrastructure specialists given hyperscale operator consolidation to three approved suppliers per region. Long-term viability favors service-network density over pure hardware scale across the five-to-ten year window. Monitor Uptime Institute tier certification deadline acceleration as inflection indicator for fixed IMD procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Establishes recurring revenue moats in Germany, Japan, and United States where metrology laboratories concentrate. |
| Capacitive Technology Platform Migration | Captures VFD proliferation demand in German chemical and pharmaceutical manufacturing where motor control precision dominates. |
| Pulse Voltage Method Specialization | Aligns with North Sea offshore wind and Chinese coastal solar construction pipelines requiring long cable fault detection. |
| Digital Twin Integration Development | Enables condition-based replacement contracts shifting revenue from hardware sales to predictive analytics services. |
| Multi-Jurisdiction Certification Parallelism | Compresses CE marking, UL listing, and China Compulsory Certification timelines to match hyperscale commissioning deadlines. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center engineering directors, electrical contractor procurement leads, chemical plant maintenance managers, and IMD manufacturer product strategists were combined with IEC 61543 compliance documentation, OSHA enforcement memoranda, and BIS certification registries. Bottom-up triangulation across facility-level procurement data and top-down validation through electrical infrastructure spending disclosures ensured cross-verification.
Segmentation granularity modeled product type, measurement technology, application criticality, and end-user purchasing authority across the projection horizon. CAGRs were derived from facility commissioning timelines, regulatory enforcement schedules, and equipment replacement cycle analysis. Forecast inputs incorporated hyperscale data center construction pipelines, EU Green Deal electrification mandates, and variable-frequency drive penetration rates in process manufacturing.
Inputs from Uptime Institute tier certification databases and electrical contractor bid documentation were available through the study window; gaps in brownfield retrofit spending data introduce uncertainty bands around modular IMD adoption trajectories. Forecasts reflect documented assumptions regarding IEC 61543 compliance deadlines and OSHA enforcement intensity. Semiconductor supply allocation volatility and multi-jurisdiction certification delays represent primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Pressure Monitoring Market