
 Piezoelectric Polymers Market | 2026-2036
Piezoelectric Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric Polymers Market Intelligence
Demand from medical device manufacturers is redrawing the competitive landscape, shifting focus from traditional industrial equipment applications. Arkema specializes in high-performance copolymers for niche medical and sensor applications. Solvay leverages its broad polymer portfolio to serve diverse end-user requirements across electronics and automotive sectors. Meanwhile, Daikin Industries sustains a strong position through its extensive production of polyvinylidene fluoride (PVDF) base resins.
Piezoelectric polymers are materials that produce an electrical charge in response to applied mechanical stress, known as the direct piezoelectric effect. This property allows them to function as converters of mechanical energy to electrical energy in devices like sensors, actuators, and transducers. Polyvinylidene fluoride (PVDF) leads the product segment, valued for its strong piezoelectric coefficients and processing flexibility. Within applications, sensors and energy harvesting are key areas, with use expanding in automotive and medical device end-user markets.
Material compliance is shaped by multiple frameworks, including the EU's RoHS directive for electronics and the US FDA's requirements for medical device components. Regulations from bodies like Japan's PMDA also influence material selection for healthcare applications. Navigating these varied, application-specific certification pathways is critical for market access and competitive differentiation.
Market Dynamics
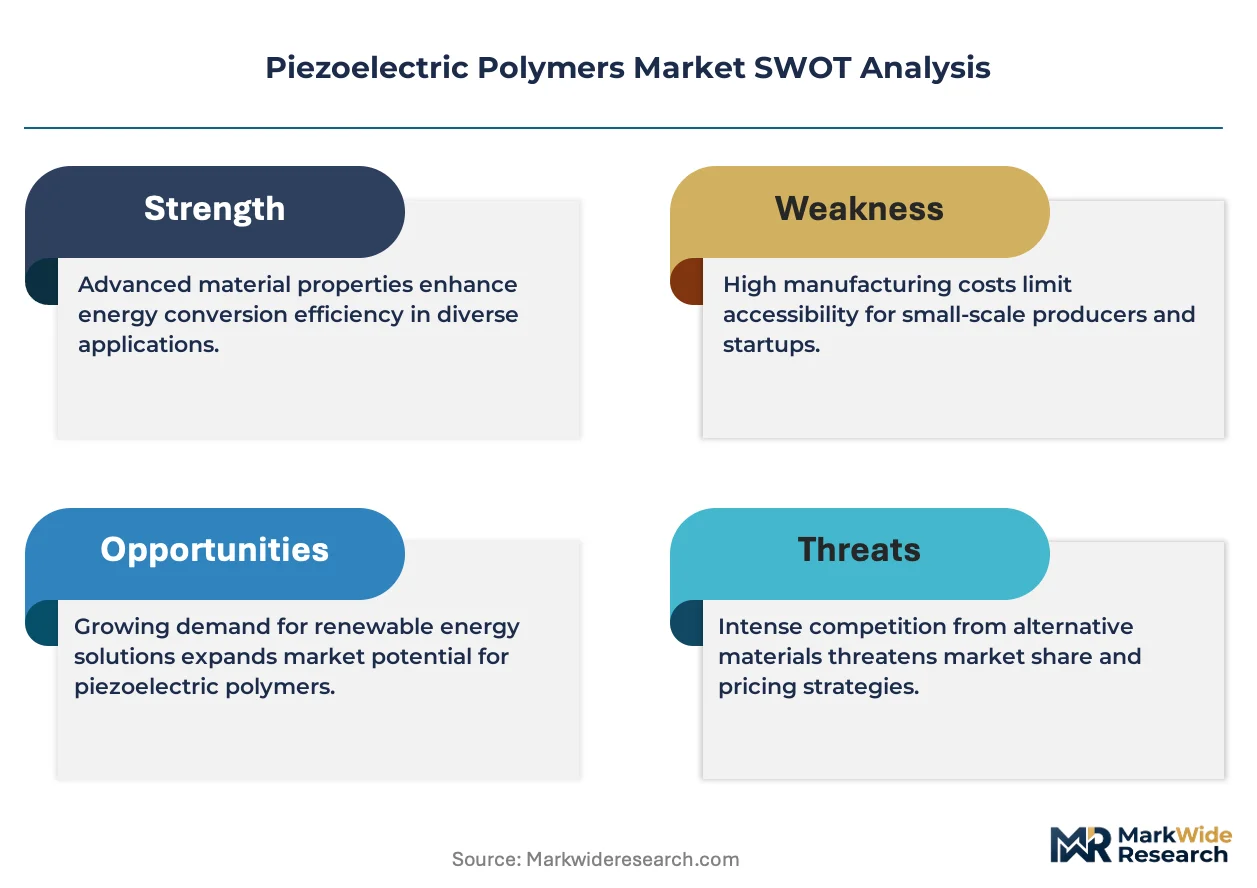
The structural pivot from traditional industrial applications toward the high-value medical device sector is the central force shaping the piezoelectric polymers market. This shift is driven by demand for advanced materials in diagnostic sensors, compelling producers to align with stringent healthcare regulations like the EU's MDR.
Growth Catalysts
- Nanostructured Polymer Development:The creation of nanostructured polymers enhances material sensitivity and performance, directly supporting their adoption in advanced medical diagnostic sensors and precision industrial monitoring equipment.
- Automotive Sector Integration:Expanding use in automotive systems for applications like tire pressure monitoring and occupant detection sensors provides a significant volume-based demand stream for piezoelectric polymer films.
- German Manufacturing Demand:Germany's concentration of high-tech manufacturing and medical technology sectors creates a strong, localized demand for high-performance, certified piezoelectric materials that meet exacting quality and reliability standards.
Market Restraints
- High Production Costs:The complex synthesis, purification, and electrical poling processes required for high-performance copolymers result in higher material costs compared to commodity plastics, limiting adoption in cost-sensitive applications.
- Technical Performance Limits:Piezoelectric polymers exhibit lower operating temperature ranges and piezoelectric coefficients than many ceramic alternatives, precluding their use in certain high-temperature or high-force industrial applications.
- Ceramic Material Competition:In applications where mechanical flexibility is not a primary requirement, established piezoelectric ceramics present a significant substitution threat due to their superior piezoelectric response and mature supply chains.
Strategic Opportunities
- Wearable Technology Integration:The market for wearable electronics and smart textiles offers a significant opportunity for flexible piezoelectric polymers in energy harvesting from motion and for creating integrated, unobtrusive physiological sensors.
- Biocompatible Material Innovation:Developing fully biocompatible and even biodegradable piezoelectric polymers opens new frontiers in implantable medical devices, transient electronics, and in-vivo diagnostic tools.
- Emerging Market Penetration:Untapped demand in Southeast Asian countries for consumer electronics manufacturing and an expanding medical device industry provides a geographic expansion opportunity beyond established North American and European markets.
Industry Challenges
- Regulatory Navigation Complexity:Manufacturers face the challenge of navigating divergent, application-specific regulatory pathways, such as the US FDA's premarket approval for medical devices and the EU's RoHS directive for electronic components.
- Standardization Deficits:A lack of universally accepted testing and characterization standards for novel polymer composites makes it difficult for end-users to compare materials from different suppliers, slowing adoption cycles.
- System Integration Hurdles:Integrating flexible, delicate polymer films with rigid circuit boards and housings in miniaturized electronic devices requires specialized manufacturing techniques and presents significant design challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric Polymers Market |
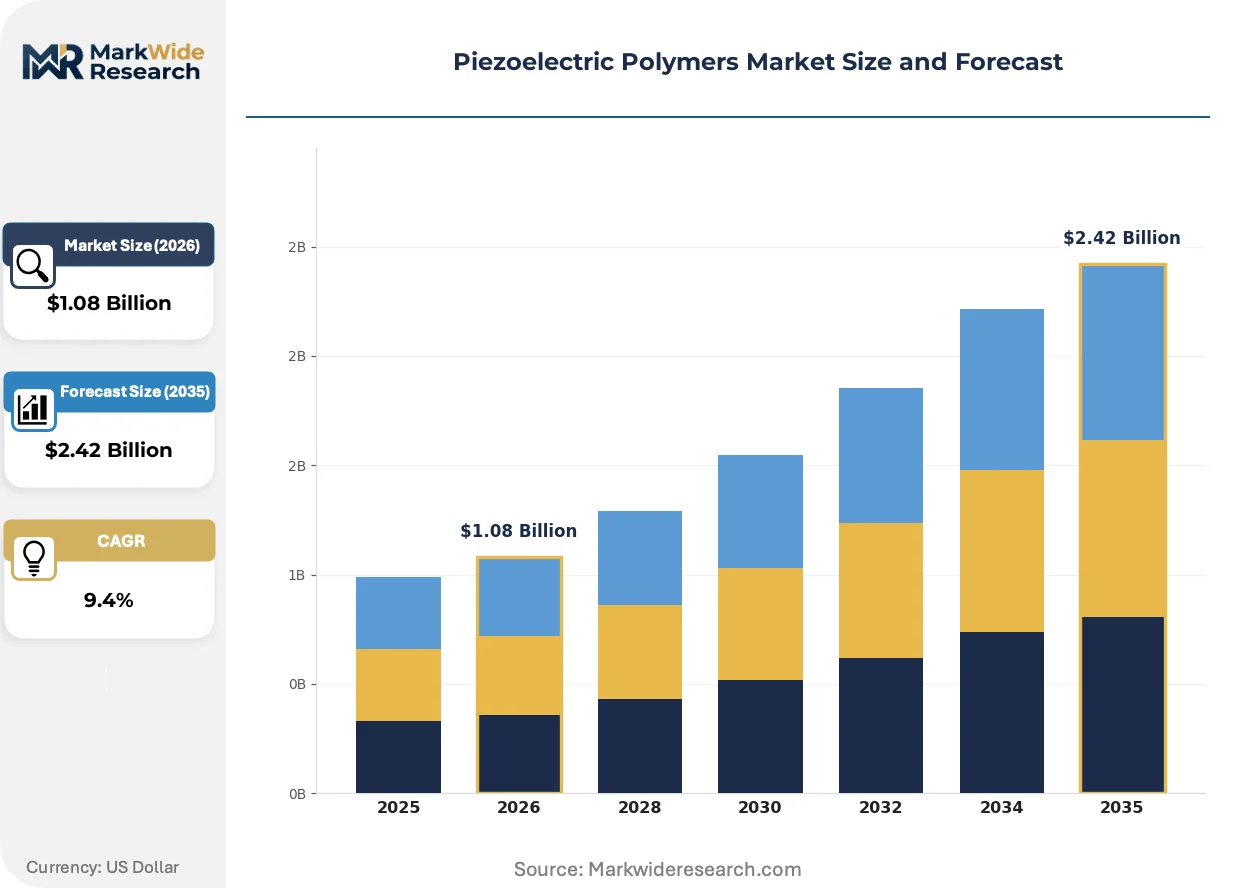
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinylidene Fluoride, Polyurethane, Polyamide, Copolymer End User: Consumer Electronics, Automotive Sensors, Medical Devices, Industrial Equipment Application: Energy Harvesting, Actuators, Sensors, Transducers Technology: 3D Printing, Nanostructured Polymers, Coating, Composite Materials |
| Companies Covered | Daikin Industries, Polyk Technologies, Arkema, APC International, Murata Manufacturing, Solvay, Toray Industries, PI Ceramic, Kureha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric Polymers Market Strategic Shifts & Innovations
Material innovation is concentrating on creating specialized polymer formulations designed to meet the precise performance and regulatory demands of specific end-uses. This moves the market away from general-purpose materials toward a portfolio of tailored, high-value solutions for sectors like healthcare and aerospace.
Nanostructured polymers and advanced copolymers provide enhanced piezoelectric response and greater mechanical durability. The medical device and aerospace sectors are steadily adopting these materials for next-generation sensors that require high fidelity and reliability in demanding environments. This specialization is fragmenting the material supply landscape away from a reliance on standard PVDF toward a more diverse array of application-specific formulations.
The European Union's Medical Device Regulation (MDR) establishes more rigorous criteria for material biocompatibility, clinical evaluation, and supply chain traceability. This regulation transforms compliance from a final check into a core element of material design and competitive positioning for suppliers. Polymer producers targeting the European healthcare market must now invest more heavily in documentation and testing, affecting development costs and timelines.
A demand-side shift toward co-development partnerships between polymer suppliers and device manufacturers is gaining momentum. This collaborative model is displacing the traditional, transactional procurement of off-the-shelf materials, especially for complex devices. The trend is most pronounced within the high-performance sensor segments of Germany's automotive industry and Japan's medical technology cluster, where custom material properties are essential.
Piezoelectric Polymers Market Segmentation
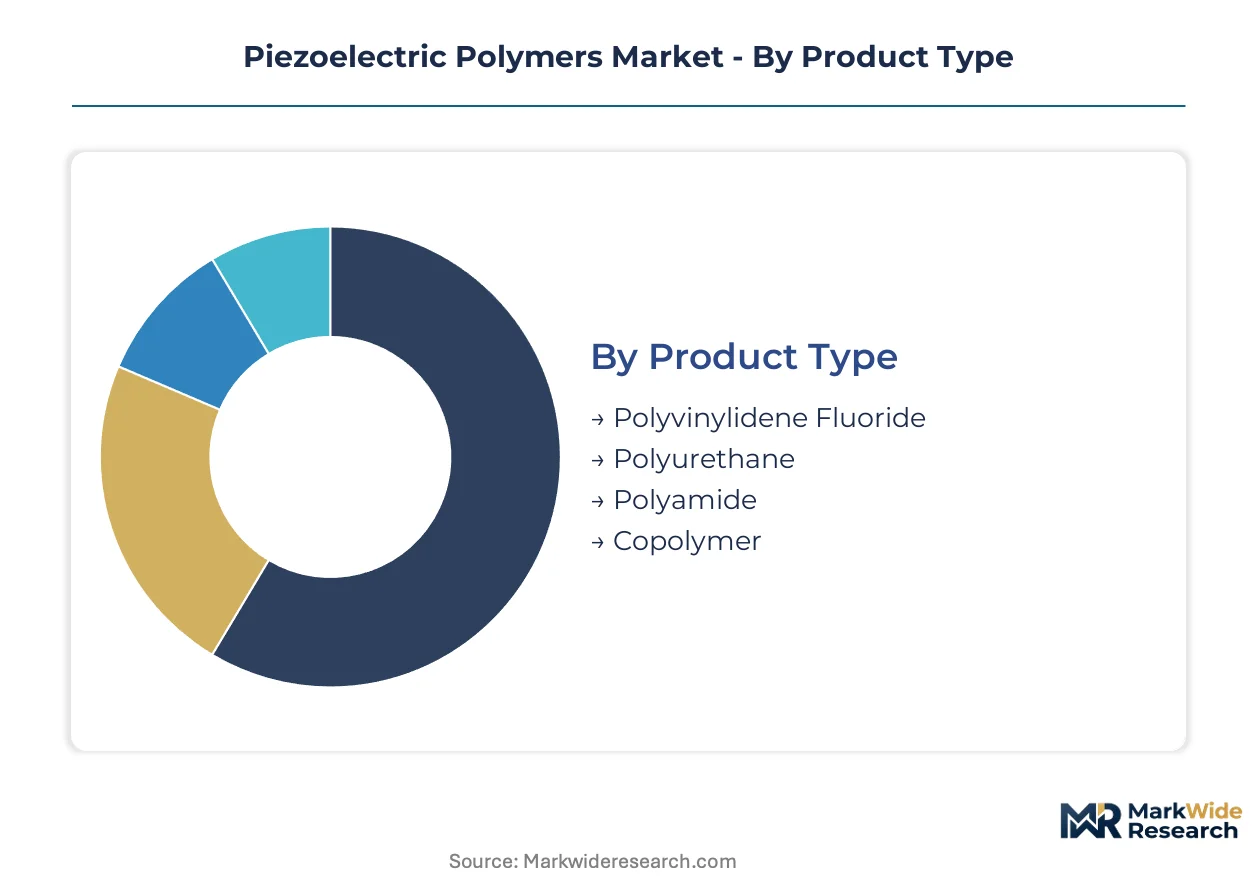
The piezoelectric polymers market segmentation highlights the diverse material properties and application requirements driving product development. Each category reflects distinct value propositions, influencing procurement strategies and competitive dynamics across the industry. Understanding these segments is critical for manufacturers to align product offerings with specific market needs.
Product Type:
The distribution channels for piezoelectric polymers vary significantly by product type, influencing market reach and application specificity.
- Polyvinylidene Fluoride:This fluoropolymer leads the product segment, valued for its strong piezoelectric coefficients, chemical resistance, and processing flexibility. Demand concentrates in sensors and medical devices, where its stability and performance are critical.
- Copolymer:High-performance copolymers offer enhanced piezoelectric response and mechanical durability, particularly suitable for demanding environments. Niche medical and advanced sensor applications drive demand, compelling producers to meet exacting performance standards.
- Polyurethane:These flexible polymers find use in applications requiring high mechanical strength and elasticity, often for actuators and soft robotics.
- Polyamide:Polyamide-based piezoelectric materials provide good thermal stability and mechanical properties for structural sensing and energy harvesting in moderate conditions.
By volume, Polyvinylidene Fluoride leads. By growth pace, Copolymer represents the fastest-growing trajectory.
End User:
Application requirements dictate the choice of piezoelectric polymer, with end-user segments demanding tailored material properties for optimal performance.
- Medical Devices:This sector demands biocompatible, high-sensitivity piezoelectric polymers for diagnostic sensors and implantable technologies. Stringent healthcare regulations, such as the EU's MDR, shape material selection and development.
- Automotive Sensors:Piezoelectric films are increasingly integrated into automotive systems for tire pressure monitoring, occupant detection, and engine knock sensors. This application requires robust materials capable of operating in diverse environmental conditions.
- Consumer Electronics:Piezoelectric polymers enable haptic feedback, touch sensors, and energy harvesting in portable gadgets. Miniaturization and energy efficiency are key drivers for material innovation.
- Industrial Equipment:Traditional industrial applications utilize piezoelectric materials for vibration monitoring, non-destructive testing, and process control sensors.
Medical Devices exhibit the steepest expansion trajectory, while Industrial Equipment maintains a stable, foundational demand.
Application:
Volume contribution varies across different applications, reflecting the diverse functional roles piezoelectric polymers fulfill in various systems.
- Sensors:Piezoelectric polymers convert mechanical stress into electrical signals, enabling high-fidelity and reliable sensing in medical diagnostics and industrial monitoring. The demand for precision in complex environments drives material innovation.
- Energy Harvesting:These materials convert ambient mechanical energy from motion or vibration into electrical power, extending battery life or enabling self-powered devices. Wearable technology and smart textiles offer significant growth opportunities.
- Actuators:Piezoelectric polymers deform in response to an electric field, used in micro-pumps, haptic feedback devices, and precision positioning systems.
- Transducers:Combining both sensing and actuating capabilities, transducers find use in medical ultrasound imaging and non-destructive testing.
Sensors command the largest share of market value, whereas Energy Harvesting demonstrates substantial potential for future adoption.
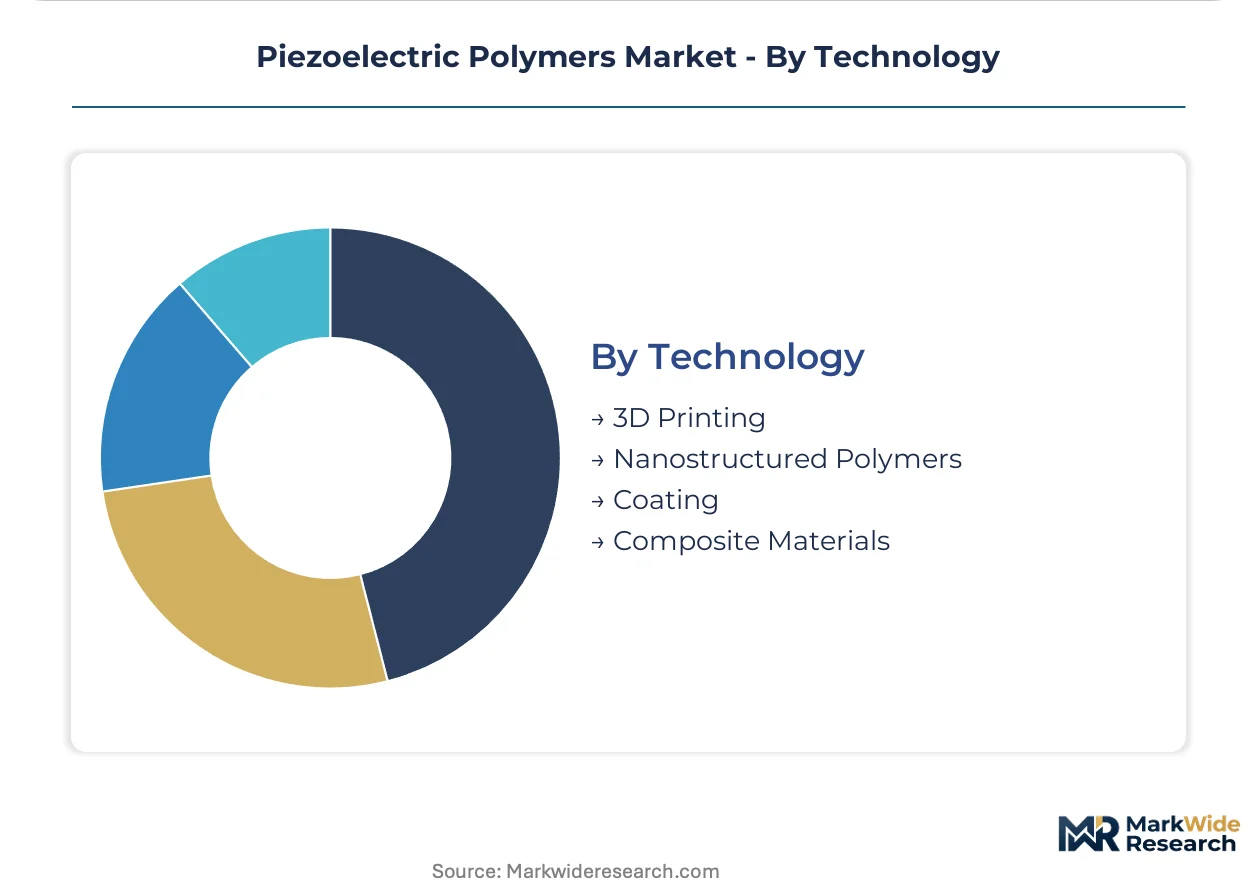
Technology:
The maturity level of underlying technologies influences their commercial viability and integration speed within piezoelectric polymer manufacturing.
- Nanostructured Polymers:The development of nanostructured polymers enhances material sensitivity, performance, and mechanical strength. This technology supports adoption in advanced medical diagnostic sensors and precision industrial equipment.
- 3D Printing:Additive manufacturing techniques enable the creation of complex, customized piezoelectric polymer structures with tailored geometries and integrated functionalities. This technology reduces prototyping time and allows for novel device designs.
- Coating:Piezoelectric polymer coatings offer a cost-effective method to impart sensing or energy harvesting capabilities to existing surfaces and components.
- Composite Materials:Combining piezoelectric polymers with other materials enhances specific properties like mechanical stiffness or thermal conductivity for specialized applications.
Nanostructured Polymers are gaining share fastest, while Coating technologies provide broad applicability across existing platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for piezoelectric polymers shows significant geographic concentrations, particularly in regions with robust high-tech manufacturing. These areas drive material innovation and application expansion across various end-user markets. Strategic investments in advanced R&D further solidify these regional strongholds.
Germany
Germany's high-tech manufacturing sector drives substantial demand for piezoelectric polymers, particularly in advanced medical devices and precision automotive sensors. The EU's Medical Device Regulation (MDR) establishes stringent material biocompatibility criteria for healthcare applications. Clusters around Stuttgart and Munich are developing next-generation sensor solutions for electric vehicles and diagnostic equipment.
United States
The United States market for piezoelectric polymers benefits from strong demand in medical device manufacturing and advanced aerospace applications. US FDA regulations govern the use of these materials in implantable and diagnostic medical technologies. Innovation hubs in Boston and Silicon Valley are fostering the development of flexible sensors for wearable tech and high-fidelity diagnostic tools.
Japan
Japan's advanced medical technology cluster and robust automotive industry fuel significant demand for specialized piezoelectric polymers. The Pharmaceuticals and Medical Devices Agency (PMDA) influences material selection for healthcare applications within the country. Major industrial centers like Tokyo and Osaka are pioneering co-development partnerships for custom material formulations in sensor technologies.
China
China's expansive consumer electronics manufacturing base and rapidly expanding medical device sector create a substantial market for piezoelectric polymers. The National Medical Products Administration (NMPA) increasingly regulates materials used in medical devices, influencing supplier compliance. Industrial zones in the Yangtze River Delta and Shenzhen are integrating these materials into haptic feedback systems and diagnostic sensors.
Piezoelectric Polymers Market Key Industry Players
Concentration sits with specialized material producers focusing on high-performance formulations for niche applications. The market structure exhibits a tiered landscape, ranging from base resin manufacturers to highly specialized copolymer suppliers. Key strategic archetypes include innovators of nanostructured polymers and broad-spectrum polymer providers. Companies are engaging in portfolio diversification and fostering co-development partnerships with device manufacturers.
On the premium-tier vector, Arkema exemplifies specialization in high-performance copolymers, particularly for niche medical and sensor applications. Solvay, leveraging its broad polymer portfolio, occupies a position serving diverse end-user requirements across electronics and automotive sectors. Daikin Industries, a Japanese company, anchors the market through its extensive production of polyvinylidene fluoride (PVDF) base resins. These players collectively represent the strategic approaches of material innovation, application breadth, and core material supply. Their presence underscores the importance of both specialized and foundational polymer offerings in the market, driving competitive advancements in material science.
| Leading Market Players |
|---|
| Daikin Industries |
| Polyk Technologies |
| Arkema |
| APC International |
| Murata Manufacturing |
| Solvay |
| Toray Industries |
| PI Ceramic |
| Kureha Corporation |
| Others |
Cost & Logistics Intelligence
Extended lead times for high-performance copolymers directly influence downstream pricing power, dictating material availability for specialized medical device manufacturers. This supply concentration also impacts material development costs.
Pricing Analysis
The EU's Medical Device Regulation (MDR) dictates the pricing tier structure for specialized piezoelectric polymers in Europe. Pricing predominantly follows a contract-based long-term offtake model for high-performance copolymers, while standard PVDF is often transactional. Certification level, particularly US FDA approval, drives significant price differentiation. Cost compression in base PVDF resins stems from mature production capabilities. Medical device manufacturers exhibit the lowest price sensitivity, prioritizing performance and regulatory compliance, whereas consumer electronics producers remain highly cost-conscious.
Supply Chain Analysis
Specialized purification processes underwrite the supply chain for high-performance piezoelectric polymers, particularly for critical medical applications. Geographic supply concentrates in Japan for PVDF base resins and Germany for advanced material integration. The market draws from specific fluoropolymer precursors and proprietary catalysts. Single-source vulnerability for these specialized monomers presents a significant structural risk. Downstream distribution typically involves direct sales to large medical device OEMs and automotive integrators, with regional distributors handling broader industrial and electronics demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piezoelectric polymers market is undergoing a platform-economics inflection, driven by the increasing interoperability of advanced sensor ecosystems in medical diagnostics. This shift redefines value creation from material supply to integrated functionality within complex systems.
For Market Incumbents: Shield core positions by deepening vertical integration into specialized medical device component manufacturing. Invest heavily in R&D for biocompatible nanostructured polymers to counter emerging material innovation threats. Proactive certification investment, particularly for EU MDR compliance, reinforces market access and differentiation against new entrants. Control over critical IP for high-performance copolymers ensures sustained competitive advantage.
For New Entrants and Emerging Players: Anchor in niche application segments like wearable technology and smart textiles, where flexibility and energy harvesting capabilities are paramount. Target underpenetrated Southeast Asian markets for consumer electronics manufacturing, leveraging cost-effective production. Develop specialized, application-specific formulations through co-development partnerships with device manufacturers, bypassing the need for broad portfolio competition. Focus on rapid prototyping enabled by 3D printing technologies.
For Investors and Strategic Acquirers: Long-term, this sits as a high-tech materials enabler play because piezoelectric polymers are foundational to next-generation medical and automotive sensing. Identify specialized copolymer producers with strong IP portfolios in nanostructured materials for acquisition. The signal to watch is the accelerated commercialization of fully biocompatible and biodegradable piezoelectric polymers for implantable devices, indicating significant market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity PVDF | Ensures stable supply of foundational material for diverse sensor and medical applications. |
| Co-development Partnerships with Medical OEMs | Accelerates integration of specialized piezoelectric polymers into advanced diagnostic devices. |
| R&D Investment in Biocompatible Nanomaterials | Unlocks new applications in implantable electronics and next-generation in-vivo sensors. |
| Proactive EU MDR and US FDA Certification | Secures critical market access and competitive differentiation within the stringent healthcare sector. |
| Penetration of Southeast Asian Electronics Markets | Captures untapped demand for flexible sensors and energy harvesting in consumer gadgets. |
Research Approach
A spread of perspectives from material scientists, medical device engineers, and automotive R&D leads converged on the working assumptions for the piezoelectric polymers market. This analysis integrated primary interviews with industry stakeholders and validated findings against comprehensive secondary data. Secondary sources included EU RoHS directives, US FDA guidelines, and corporate annual filings. Bottom-up data aggregation and top-down market sizing provided a robust triangulation for market estimates.
Product type, end user, application, technology, and regional regulatory compliance constituted the core segmentation dimensions modeled across the analysis window. The quantitative framework projected compound annual growth rates derived from historical data analysis and identified market drivers. Industry-specific forecast inputs included advancements in nanostructured polymer performance and the pace of new material approvals by the US FDA. The model captured the evolving demand dynamics for specialized material solutions.
Underlying assumptions cover regulatory stability and consistent technological development within advanced material science, with deviation risk concentrated in unforeseen geopolitical shifts impacting supply chains. Forecasts reflect these assumptions, acknowledging potential for rapid change. Practitioners should keep alternative scenarios live as regulatory landscapes and material innovation pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
North America Turbomachinery Control Systems Market